

High-Purity Fluoropolymer Valves Market Size, Share, and Industry Trends Forecast 2026-2036
High-Purity Fluoropolymer Valves Market Insights
Modular manifold-integrated valve assemblies is restructuring procurement patterns across semiconductor and biopharmaceutical end users, replacing discrete component purchasing with pre-tested subsystems. Swagelok leverages its captive fitting and tubing ecosystem to anchor premium bundled offerings. Entegris specializes in contamination-controlled fluid management architectures that extend its reach beyond discrete valves into process enclosures. Parker Hannifin dominates hydraulic and pneumatic adjacencies, competing through scale in chemical processing infrastructure.
High-purity fluoropolymer valves are precision flow-control devices machined from perfluorinated resins—principally PFA with melt-flow indices below 2 g/10min—to deliver particle counts below 0.1 particles per milliliter in ultrapure chemical distribution. Their primary purpose is eliminating metallic ion contamination during aggressive acid and solvent handling in semiconductor wet-process benches and pharmaceutical sterile transfer lines. Ball valves occupy the largest volume position across chemical processing and water treatment installations, though diaphragm valves command the strongest margin pools in biopharmaceuticals where zero-dead-leg designs justify premium positioning. PFA material grades lead revenue contribution due to superior creep resistance and weldability, while ETFE grades are gaining fastest in wastewater management where mechanical toughness outweighs absolute chemical inertness.
EPA effluent guidelines and FDA Current Good Manufacturing Practice standards jointly determine material qualification pathways, with the former restricting fluoropolymer waste streams and the latter mandating extractables documentation for pharmaceutical contact surfaces. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing European valve users to validate next-generation MFA grades ahead of broader regulatory phase-downs. Semiconductor fabs and their tier-one equipment suppliers must now decide whether to dual-qualify emerging copolymer grades or accelerate in-house material recycling to hedge against supply discontinuity.
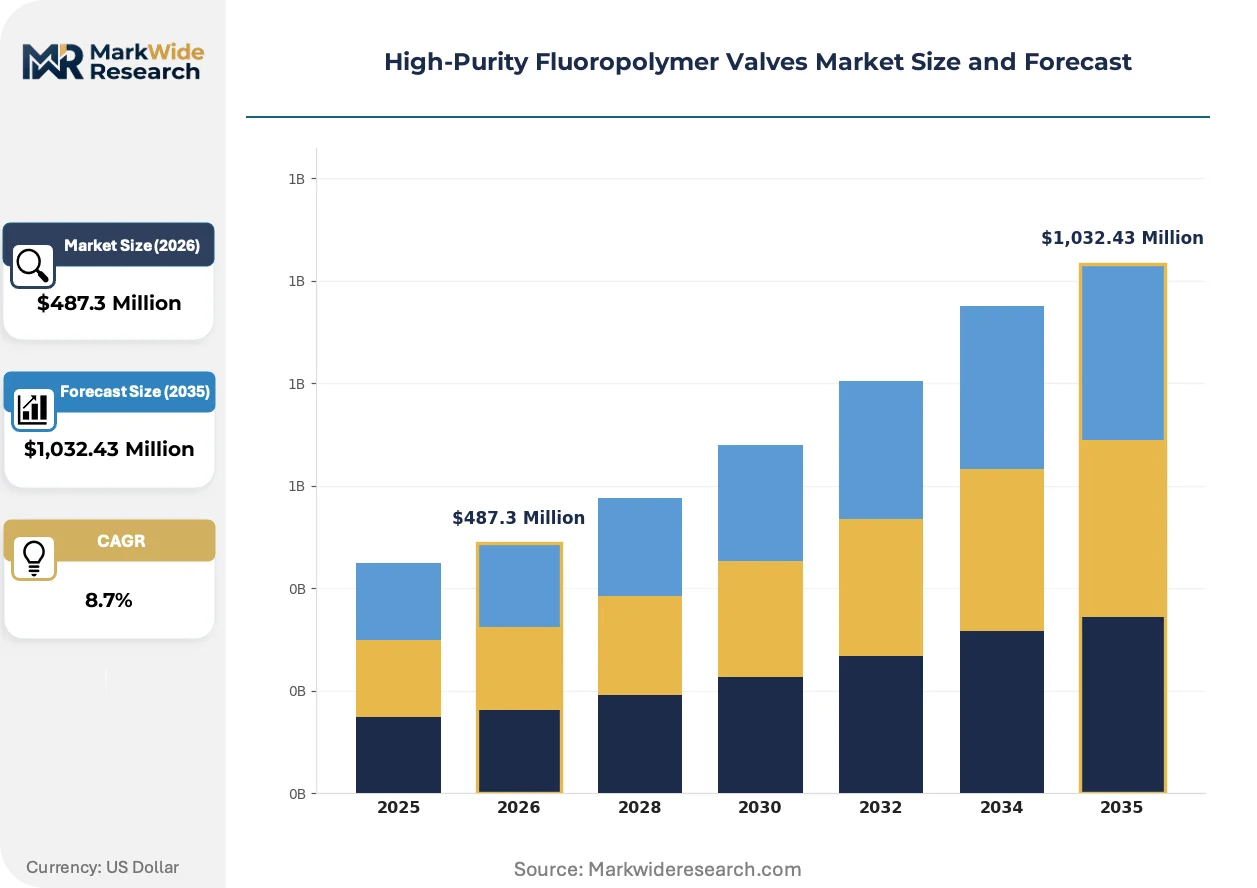
Market Dynamics
Sub-10nm semiconductor contamination thresholds are compressing qualification cycles for fluoropolymer valve architectures, forcing simultaneous upgrades across wet-process bench, chemical distribution, and gas delivery subsystems.
Growth Catalysts
- Semiconductor node shrinkage:Samsung and SK Hynix fabs in South Korea now mandate sub-0.1 particle-per-milliliter specifications for etching chemistry valves, pulling PFA-grade procurement volumes upward.
- REACH Annex XVII phase-downs:European ECHA restrictions on legacy perfluorinated compounds are accelerating validation of MFA and ETFE copolymer alternatives ahead of broader supply discontinuity risks.
- Biopharmaceutical sterile transfer expansion:FDA Current Good Manufacturing Practice extractables documentation requirements are widening addressable demand for zero-dead-leg diaphragm valve configurations in single-use systems.
Market Restraints
- Fluoropolymer resin supply concentration:Virgin PFA pellet production clusters among Japanese and US chemical conglomerates, exposing valve fabricators to force majeure pricing volatility without captive resin streams.
- REACH compliance friction:ECHA registration dossier costs for next-generation MFA grades are prohibiting mid-tier valve assemblers from European market entry, consolidating supply among capital-rich incumbents.
- Mechanical toughness trade-offs:ETFE's inferior creep resistance versus PFA limits its deployment in high-cycle pneumatic actuation, capping substitution potential in critical wet-bench applications.
Strategic Opportunities
- Modular manifold-integrated assemblies:Pre-tested subsystems bundling valves, fittings, and sensors are displacing discrete component procurement in semiconductor OEM supply chains, opening margin capture for architecture-level suppliers.
- Wastewater management ETFE adoption:Mechanical toughness requirements in industrial effluent handling are outpacing absolute chemical inertness needs, creating faster-growth deployment for ETFE grades versus saturated PFA markets.
- India PLI scheme for semiconductors:Domestic fab incentives under India's production-linked incentive framework are seeding localized valve qualification programs ahead of anticipated chemical distribution infrastructure buildouts.
Industry Challenges
- Multi-grade dual-qualification burden:Semiconductor fabs must simultaneously validate emerging MFA copolymers and maintain legacy PFA supply chains, doubling qualification timeline and capex intensity for process engineering teams.
- ISO 14644-1 cleanroom integration:Valve assembly and testing facilities require Class 4 or better environments, constraining geographic expansion to regions with established high-purity infrastructure clusters.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Purity Fluoropolymer Valves Market Trends and Innovations
Laser welding of PFA valve bodies is compressing particle generation versus legacy socket fusion, while REACH-driven material transitions and buyer consolidation are restructuring how valve architectures reach end-use equipment.
Modular manifold-integrated valve assemblies is consolidating procurement authority away from discrete component buyers toward subsystem-level suppliers who control pre-tested architecture qualification. Semiconductor OEMs and biopharmaceutical CDMOs now specify complete fluid management modules rather than individual valve SKUs, compressing the addressable vendor base and elevating architecture-level competitors. This consolidation is forcing mid-tier valve fabricators into captive supply relationships or exit from premium contamination-controlled segments.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling European valve users to validate MFA and ETFE alternatives ahead of broader regulatory phase-down timelines. ECHA registration requirements for next-generation copolymers are extending material qualification cycles by 18-24 months, delaying product launches and concentrating development resources among resin producers with existing regulatory dossier capabilities. Semiconductor fabs in Germany and France are responding by accelerating in-house material recycling programs to hedge virgin resin supply discontinuity.
Buyer consolidation among tier-one semiconductor equipment suppliers is compressing valve vendor negotiation leverage and elongating payment terms. Lam Research, Applied Materials, and Tokyo Electron now mandate outcome-based performance guarantees covering particle counts, actuation cycles, and field failure rates, unbundling traditional hardware-plus-service contracts into pure performance obligations. This shift is most visible in South Korea's domestic etching equipment supply chain, where Samsung and SK Hynix procurement teams have consolidated qualified valve suppliers from twelve to four over the past qualification cycle.
High-Purity Fluoropolymer Valves Market Segmentation
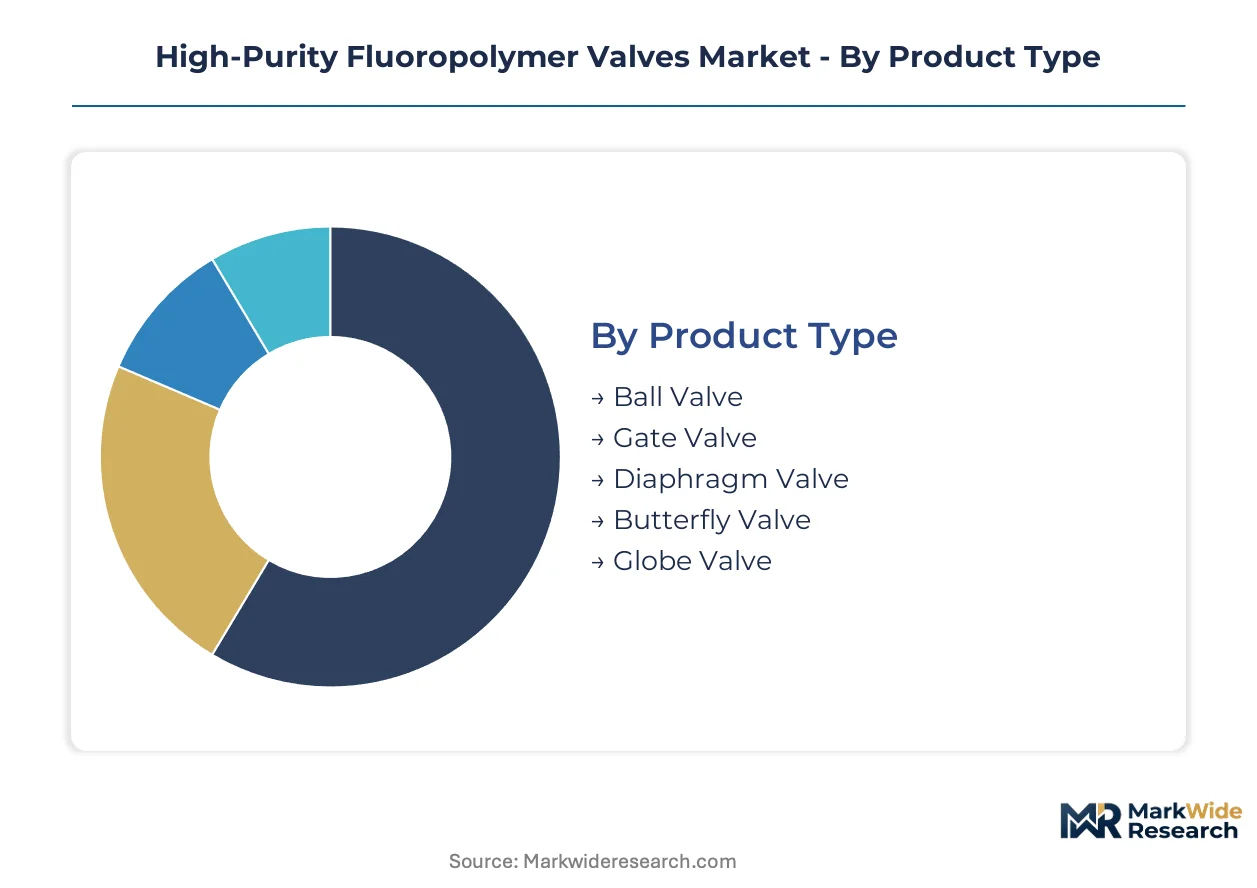
Segmentation in high-purity fluoropolymer valves tracks the tension between contamination thresholds and mechanical durability across distinct process environments. Material-grade selection and valve architecture together determine qualification pathways for semiconductor fabs versus chemical processing installations.
Product Type:
Valve architecture selection hinges on actuation frequency, dead-leg tolerance, and seal integrity requirements in aggressive chemical service.
- Ball Valve:Quarter-turn shutoff devices with floating or trunnion-mounted PFA balls deliver bidirectional sealing for ultrapure water and acid distribution lines. Demand concentrates in chemical processing facilities across Germany and Japan where high-cycle reliability outweighs zero-dead-leg mandates.
- Diaphragm Valve:Flexible PTFE or PFA diaphragms isolate process fluids from mechanical actuators, enabling zero-dead-leg configurations essential for biopharmaceutical sterile transfer. South Korean biologics CDMOs are specifying these for single-use manifold integration.
- Gate Valve:Linear-motion wedge designs provide full-bore flow with minimal pressure drop for slurry and particulate-laden chemical streams. ETFE-bodied variants are penetrating wastewater management applications in the US where abrasion resistance trumps ultrapurity.
- Butterfly Valve:Rotating disc mechanisms offer compact face-to-face dimensions for space-constrained wet-process benches. PFA-lined configurations serve semiconductor chemical distribution in Taiwan and Singapore fabs.
- Globe Valve:Throttling-optimized seat designs regulate flow in precision dosing applications. Limited deployment in high-purity segments due to inherent dead-leg geometry restricting biopharmaceutical adoption.
Mature deployment sits with ball valves. Newer deployment is concentrated in diaphragm valves for single-use bioprocessing architectures.
Material Grade:
Resin selection balances chemical inertness, mechanical toughness, and regulatory qualification status across fluoropolymer families.
- PFA:Perfluoroalkoxy resins with melt-flow indices below 2 g/10min deliver superior creep resistance and laser-weldability for sub-10nm particle specifications. Samsung and SK Hynix fabs in South Korea mandate PFA grades exclusively for etching chemistry valves.
- ETFE:Ethylene-tetrafluoroethylene copolymers trade absolute chemical resistance for mechanical toughness and radiation stability. Industrial effluent handling in the US and China is expanding ETFE adoption where mechanical durability outweighs ultrapurity thresholds.
- PTFE:Polytetrafluoroethylene offers maximum chemical inertness but requires compression molding due to non-melt-processability. Diaphragm valve fabricators specify PTFE for static seal components.
- FEP:Fluorinated ethylene propylene provides melt-processability with slightly reduced thermal stability versus PFA. Limited to lower-temperature pharmaceutical transfer lines.
- MFA:Perfluorinated copolymers with modified side chains are emerging as REACH-compliant alternatives to legacy perfluorinated compounds. ECHA registration dossiers are delaying European commercialization.
PFA captures the steepest expansion trajectory in semiconductor applications. ETFE is climbing the fastest in wastewater and industrial chemical segments.
Application:
End-use process requirements dictate valve specification from particle counting to mechanical duty cycles.
- Semiconductor Fabrication:Wet-process benches, chemical distribution loops, and gas delivery systems demand sub-0.1 particle-per-milliliter performance. PFA ball and diaphragm valves are specified for sub-10nm node production in South Korea, Taiwan, and the US.
- Pharmaceutical Manufacturing:FDA Current Good Manufacturing Practice extractables documentation drives zero-dead-leg diaphragm valve adoption. Single-use system integrators are bundling pre-qualified valve assemblies.
- Chemical Processing:Aggressive acid and solvent handling in batch and continuous reactors favors ball and gate valve architectures. ETFE grades are substituting PFA where mechanical toughness dominates.
- Water Treatment:Municipal and industrial ultrapure water systems specify PFA-lined butterfly valves for corrosion resistance. Growth is moderating versus semiconductor and biopharmaceutical segments.
- Food & Beverage:Limited high-purity fluoropolymer penetration due to cost-positioning against stainless steel alternatives. Niche applications in aseptic packaging lines.
Semiconductor fabrication anchors premium pricing. Pharmaceutical manufacturing is expanding most quickly for zero-dead-leg configurations.
End User Industry:
Industry-specific contamination protocols and capital cycles reshape procurement timing and specification authority.
- Electronics Manufacturing:Tier-one semiconductor equipment suppliers consolidate valve vendor bases from twelve to four qualified sources. Samsung and SK Hynix procurement teams now mandate outcome-based performance guarantees.
- Biopharmaceuticals:CDMOs and single-use system integrators specify complete fluid management modules rather than discrete valve SKUs. FDA extractables documentation requirements are widening addressable demand.
- Chemical Plants:Process licensors and engineering contractors specify valves for grassroots and retrofit installations. REACH Annex XVII compliance is forcing material-grade transitions in European facilities.
- Wastewater Management:Industrial effluent treatment plants prioritize mechanical toughness and chemical resistance balance. ETFE grades are gaining deployment for abrasion resistance.
- Beverage Production:Aseptic filling lines represent limited high-purity fluoropolymer opportunity due to stainless steel cost competition. Niche specifications for CIP/SIP compatibility.
Electronics manufacturing concentrates the highest specification valves. Biopharmaceuticals are driving fastest adoption for modular manifold-integrated assemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea, Taiwan, and the US concentrate semiconductor fabrication investment, pulling fluoropolymer valve procurement toward these tax-advantaged manufacturing clusters. Regulatory divergence across REACH, EPA, and domestic semiconductor incentive programs is fragmenting material qualification pathways.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Yongin now mandate sub-0.1 particle-per-milliliter valve specifications for sub-10nm etching chemistry lines. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative accelerates domestic equipment supply chain localization. Domestic etching equipment manufacturers in Suwon are consolidating qualified valve suppliers from twelve to four sources.
United States
Intel's Ohio and Arizona fab expansions plus TSMC's Arizona project drive PFA-grade valve demand for chemical distribution infrastructure. EPA effluent guidelines restrict fluoropolymer waste streams from valve manufacturing and assembly operations. The Phoenix-Tucson corridor hosts expanding cleanroom assembly facilities serving domestic semiconductor buildouts.
Germany
Infineon and Bosch semiconductor operations in Dresden and Reutlingen require REACH Annex XVII-compliant valve architectures ahead of perfluorinated compound phase-downs. ECHA registration dossier costs for MFA copolymer alternatives are delaying material qualification by 18-24 months. The Dresden Silicon Saxony cluster is accelerating in-house PFA recycling programs to hedge virgin resin discontinuity risks.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor fluoropolymer valve demand across Kyushu and Tohoku fabrication corridors. METI's semiconductor revitalization subsidies support domestic etching and deposition equipment supply chain reinforcement. Yokohama-based resin producers control virgin PFA pellet supply, exposing valve fabricators to force majeure pricing volatility.
Taiwan
TSMC's Nanke and Longtan fabs specify PFA ball and diaphragm valves for sub-7nm node chemical distribution loops. The National Development Council's chip industry stimulus funds expand domestic valve qualification programs. Taichung's precision machining ecosystem supports laser-welded PFA valve body production for semiconductor OEM integration.
High-Purity Fluoropolymer Valves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive fitting ecosystems, contamination-control specialists with architecture-level fluid management capabilities, and regional precision fabricators serving discrete component demand. Consolidation pressures from tier-one semiconductor equipment suppliers favor scale-advantaged incumbents with pre-qualified subsystem portfolios. Competitive moves center on modular manifold integration and REACH-compliant material-grade transitions.
Within the diversified conglomerate tier, Parker Hannifin and SMC Corporation occupy positions anchored by scale advantages in hydraulic and pneumatic adjacencies. Entegris exemplifies the contamination-control specialist archetype, extending reach beyond discrete valves into process enclosure architectures. Among precision fabricators, Swagelok represents the captive ecosystem model, leveraging integrated fitting and tubing offerings to anchor premium bundled positioning. TK-Fujikin and GEMÜ Group sit within regional specialist tiers serving qualified supplier consolidation trends in East Asian semiconductor supply chains.
| Leading Market Players |
|---|
| Parker Hannifin |
| Swagelok |
| Entegris |
| Saint-Gobain |
| CKD |
| SMC Corporation |
| TK-Fujikin |
| GEMÜ Group |
| White Knight Fluid Handling |
| Others |
Pricing and Supply Chain Analysis
Sub-10nm particle specifications mandated by Samsung and SK Hynix procurement teams are compressing supplier margins and forcing fabricators toward captive resin streams or premium qualification partnerships. This demand-side precision threshold reshapes how valve architectures reach end users and where pricing power accumulates.
Pricing Analysis
Short lead-time premiums of 15-25% apply to PFA valve bodies for sub-10nm node qualification cycles, while spot inventory of ETFE grades trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels separates laser-welded PFA for semiconductor OEMs from compression-molded PTFE diaphragms and injection-grade FEP for water treatment. Cost compression in mid-tier ball valve segments is intensifying because REACH dossier costs are prohibiting European market entry by regional fabricators. Biopharmaceutical CDMOs exhibit lowest price sensitivity due to FDA extractables documentation requirements, while municipal water treatment authorities drive hardest volume negotiations.
Supply Chain Analysis
Regional distribution centers in Yokohama, Seoul, and Phoenix anchor hub-and-spoke patterns for cleanroom valve assembly and testing. Virgin PFA pellet production clusters in Japan and the United States, with ETFE resin streams drawing from German and Chinese chemical conglomerates. Raw material dependencies center on fluoropolymer resin grades, laser welding equipment, and Class 4 cleanroom infrastructure. Single-source vulnerability sits with Japanese resin producers controlling high-purity PFA melt-flow specifications. Distribution runs through tier-one semiconductor equipment OEMs and biopharmaceutical system integrators rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race. Players are pursuing upstream control over virgin PFA resin streams to hedge force majeure pricing volatility and secure qualification continuity.
For Market Incumbents: Deploy laser-welding capability expansion to defend premium positioning against mid-tier fabricators adopting legacy socket fusion. Consolidate qualified supplier relationships with Samsung and SK Hynix procurement teams before dual-qualification cycles complete. Backward integration into virgin resin streams hedges supply discontinuity risks from Japanese chemical conglomerates. For New Entrants and Emerging Players: Capture wastewater management ETFE deployment in the United States and China where mechanical toughness specifications outpace ultrapurity thresholds. India's PLI semiconductor incentives seed localized valve qualification programs ahead of chemical distribution infrastructure buildouts. Partner with domestic etching equipment manufacturers in Suwon for captive supply relationships. For Investors and Strategic Acquirers: The window for entry favors contamination-control specialists with architecture-level fluid management capabilities over discrete component fabricators. Long-term viability rests on modular manifold-integrated assembly portfolios that displace individual valve SKU procurement. Watch ECHA registration timelines for MFA copolymer alternatives as inflection indicator for material-grade transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Resin | Captive PFA supply hedges force majeure volatility from Japanese chemical producers. |
| Laser Welding Capability Expansion | Compresses particle generation below socket fusion thresholds for sub-10nm qualification. |
| Modular Manifold Assembly Launch | Displaces discrete valve procurement in semiconductor OEM supply chains. |
| REACH-Compliant Material Transition | MFA and ETFE validation ahead of ECHA phase-down timelines secures European access. |
| Cleanroom Assembly Footprint Expansion | Class 4 facilities in Phoenix-Tucson corridor serve Intel and TSMC domestic buildouts. |
Research Methodology
Multi-period observation of particle count specifications, resin price volatility, and qualification cycle durations anchored the trend analysis, supplemented by interviews with semiconductor process engineers, biopharmaceutical CDMO procurement leads, fluoropolymer resin technical directors, and cleanroom assembly facility managers. Secondary validation drew from SEC 10-K filings, ECHA registration dossiers, customs trade data, and SEMI equipment market statistics. Bottom-up fabrication capacity modeling and top-down end-use demand estimation were triangulated against reported OEM procurement patterns.
Input-output matrices mapped valve architecture deployment across material grades, actuation mechanisms, and end-use contamination thresholds over the projection horizon. Segmentation dimensions modeled include product type, material grade, application environment, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield fab capital expenditure trajectories. Forecast inputs incorporated REACH Annex XVII phase-down timelines and semiconductor node migration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA copolymer registration delays and resin producer force majeure events. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.