
 Reciprocating Compressor Components Market | 2026-2036
Reciprocating Compressor Components Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Compressor Components Market Analytics
Aftermarket parts distribution through authorized service networks is rewriting procurement patterns for compressor operators seeking uptime guarantees. Atlas Copco AB leverages its global parts logistics infrastructure to sustain rapid component availability across remote oilfield locations. Ingersoll Rand Inc. anchors its position through captive distribution channels that bypass third-party distributors for critical valve and piston assemblies. Burckhardt Compression AG specializes in hyperbaric and process gas applications where custom cylinder specifications command premium positioning.
Reciprocating compressor components encompass the precision-machined mechanical elements—pistons, cylinders, valves, crankshafts, and associated sealing and lubrication hardware—that convert rotational energy into pulsating gas compression through linear displacement within a confined chamber, typically operating at pressure ratios from 1.5:1 to over 100:1 depending on staging configuration and application severity. These components serve as the functional core of positive-displacement gas handling equipment deployed across oil and gas production, industrial refrigeration, chemical processing, and power generation infrastructure where continuous or intermittent compression duty cycles are required. Steel and cast iron materials still dominate high-pressure cylinder and crankshaft manufacturing, though aluminum piston constructions are displacing legacy iron designs in refrigeration and lighter-duty manufacturing compressors where thermal conductivity and reciprocating mass reduction improve efficiency. The Oil & Gas end-user segment commands the deepest component replacement cycles due to continuous-duty operation in upstream gathering and downstream refining, while Refrigeration applications are generating accelerated valve and seal demand as ammonia and CO2 systems replace hydrofluorocarbon architectures.
EPA refrigerant management regulations under Section 608 of the Clean Air Act and evolving OSHA process safety management standards shape material selection and leak-tightness specifications for compressor valves and piston rings in US industrial installations. The EU F-Gas Regulation and accompanying CE marking requirements under the Machinery Directive constrain market access for component suppliers lacking certified material traceability and pressure equipment conformity assessment. Stakeholders must monitor how divergent regional decarbonization timelines recalibrate the relative demand intensity across natural gas infrastructure versus electrified industrial heat pump applications.
Market Dynamics
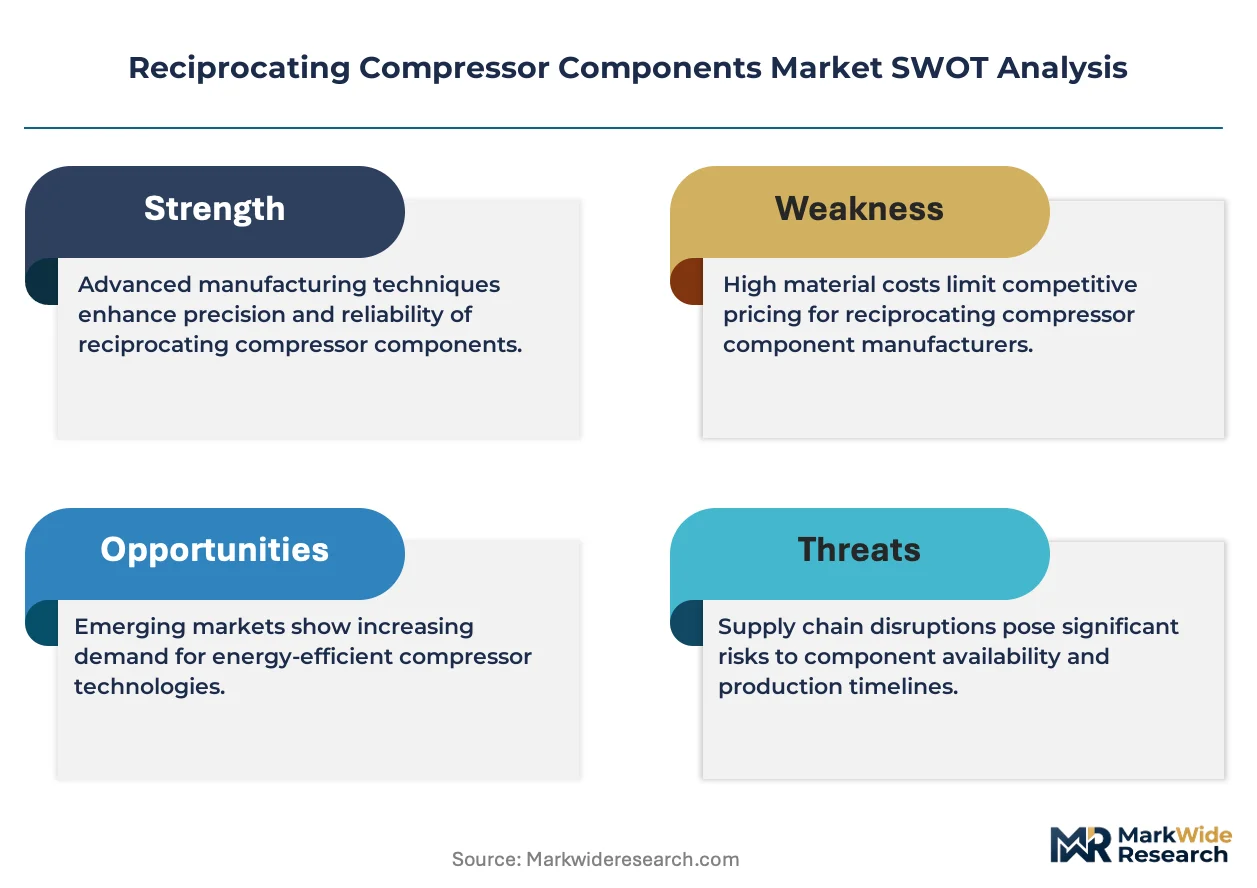
The transition to low-global-warming-potential refrigerants under Kigali Amendment obligations is forcing fundamental redesigns of valve and sealing systems across compressor architectures. This regulatory pressure cascades through material specifications, manufacturing processes, and aftermarket service protocols.
Growth Catalysts
- EPA Section 608 refrigerant management:Leak-tightness mandates under the Clean Air Act accelerate replacement cycles for piston rings and valve plates in US industrial refrigeration infrastructure.
- Petrochemical processing expansion:Gulf Coast facility upgrades pull demand for high-pressure cylinder assemblies rated for hydrogen-rich process streams.
- China's state-backed manufacturing upgrades:Heavy-duty crankshaft and piston replacements concentrate demand in industrial heartland provinces.
Market Restraints
- Specialized alloy supply concentration:High-performance valve steel production concentrates among a limited supplier base in Western Europe, creating input vulnerability.
- EU F-Gas Regulation compliance friction:CE marking requirements under the Machinery Directive constrain market access for component suppliers lacking certified material traceability.
- Electrification substitution threat:Industrial heat pump architectures displace natural gas compression in select process heating applications.
Strategic Opportunities
- India's PLI scheme for capital goods:Domestic manufacturing incentives create localization pathways for piston and cylinder production serving South Asian demand.
- Ammonia and CO2 system conversion:Hydrofluorocarbon phase-out mandates generate accelerated valve and seal demand in cold chain infrastructure.
- Authorized service network expansion:Aftermarket parts distribution through captive channels rewrites procurement patterns for uptime-critical operators.
Industry Challenges
- Precision machining skill scarcity:Qualified crankshaft grinding and valve seat lapping technicians remain concentrated among aging workforce cohorts in Germany and Japan.
- Legacy system integration complexity:Redesigned sealing geometries for new refrigerant chemistries must retrofit existing compressor footprints without full replacement.
- Dual certification timeline compression:Simultaneous ASME and PED conformity assessments stretch engineering resources for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Compressor Components Market |
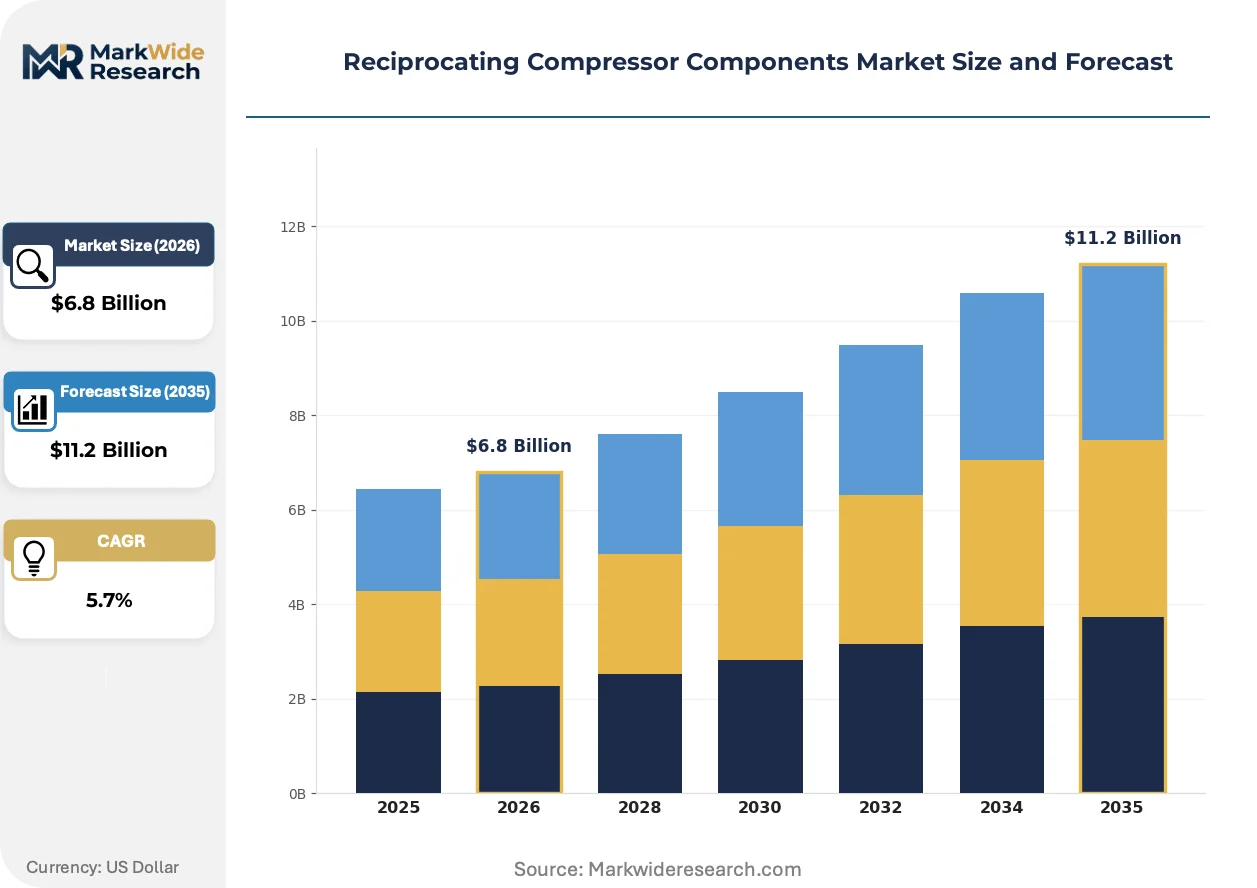
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Piston, Cylinder, Valves, Crankshaft Material: Steel, Aluminum, Cast Iron, Composite End User: Oil & Gas, Refrigeration, Manufacturing, Power Generation Functionality: Compression, Cooling, Lubrication, Transmission |
| Companies Covered | Atlas Copco AB, Ingersoll Rand Inc., Burckhardt Compression AG, Gardner Denver Holdings, Inc., Ariel Corporation, Siemens Energy AG, Kaeser Compressors, Inc., Baker Hughes Company, ELGi Equipments Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Compressor Components Market Evolving Landscape
Component architectures are compressing toward modular, condition-monitored assemblies that merge mechanical precision with embedded sensing. This convergence alters design priorities, supplier capabilities, and buyer evaluation criteria simultaneously.
Aluminum piston constructions are collapsing the thermal mass and reciprocating inertia that constrained legacy cast iron designs. Refrigeration OEMs and lighter-duty manufacturing compressor builders adopt these geometries aggressively. The shift compresses energy consumption benchmarks and extends maintenance intervals in continuous-duty applications.
The EU F-Gas Regulation tightens containment requirements for fluorinated gases across stationary refrigeration and air conditioning. Industrial end-users face mandatory leak detection systems and repair protocols. This pressure concentrates valve and seal innovation investment in hermetic joint designs and real-time monitoring integration.
Aftermarket procurement now favors authorized service networks offering uptime guarantees over traditional third-party distributors. Oil and gas operators in remote North American locations prioritize rapid component availability through integrated logistics. This behavioral pivot rewards suppliers with captive distribution infrastructure and penalizes fragmented sourcing models.
Reciprocating Compressor Components Market Segmentation
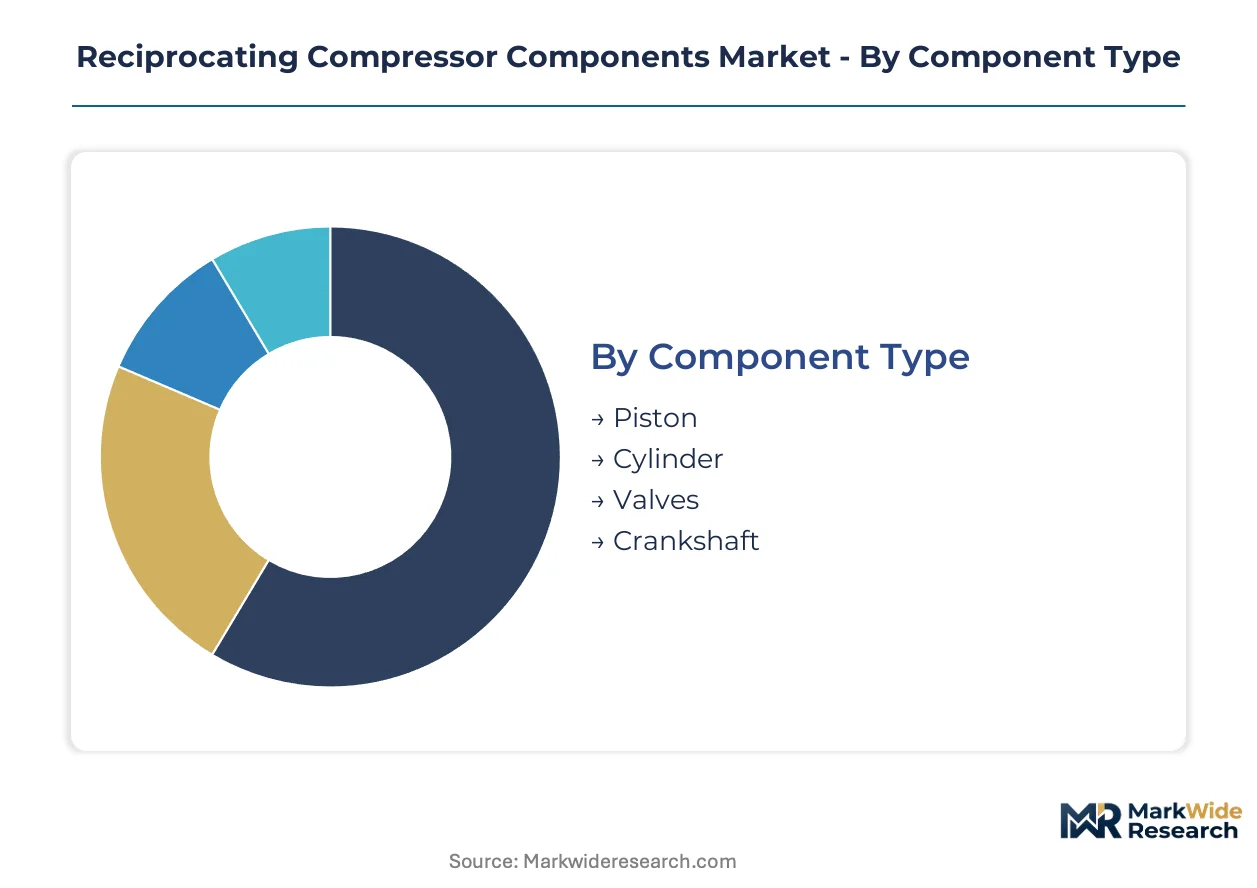
Component replacement cycles vary dramatically across reciprocating compressor architectures. Understanding these differential turnover rates allows suppliers to calibrate inventory depth, pricing power, and service attach rates against predictable demand pulses.
Component Type:
Valves and piston rings turn over fastest under continuous duty, while crankshafts and cylinder blocks anchor decade-long capital cycles. This divergence splits supplier economics between high-velocity aftermarket parts and lumpy OEM equipment sales.
- Valves:Precision-machined plates and springs that regulate gas flow direction during compression and suction strokes. EPA Section 608 leak-tightness mandates accelerate replacement schedules across US industrial refrigeration infrastructure as operators face mandatory repair protocols.
- Piston:Aluminum constructions displace legacy cast iron in refrigeration and lighter-duty manufacturing compressors, collapsing reciprocating mass and improving thermal conductivity. China's state-backed manufacturing upgrades concentrate demand for heavy-duty piston replacements in industrial heartland provinces.
- Cylinder:High-pressure housings containing compression chambers.
- Crankshaft:Forged steel or ductile iron shafts converting rotational to linear motion.
Valves anchor the volume base while piston constructions gain share at the steepest rate.
Material:
Cost tiers stratify sharply between commodity ferrous inputs and specialized alloys commanding certification premiums. Material selection directly constrains which end-use segments and regulatory jurisdictions a supplier can serve.
- Steel:Forged and heat-treated grades dominate high-pressure cylinder and crankshaft manufacturing where fatigue resistance and pressure containment are non-negotiable. Oil and gas production infrastructure across the Gulf Coast pulls demand for steel rated for hydrogen-rich process streams.
- Aluminum:Die-cast and machined alloys displace iron in refrigeration compressors seeking thermal efficiency and mass reduction. The Kigali Amendment transition to low-global-warming-potential refrigerants forces redesigns that favor aluminum's superior heat dissipation.
- Cast Iron:Gray and ductile grades persist in legacy industrial compressors.
- Composite:Polymer matrix and ceramic hybrid materials for specialized sealing and bearing applications.
Steel constructions anchor the volume base while aluminum expands most quickly.
End User:
Application severity and duty cycle intensity determine component life expectancy. Continuous upstream operations consume parts faster than intermittent manufacturing duty.
- Oil & Gas:Upstream gathering and downstream refining operations impose the deepest replacement cycles due to continuous-duty compression of sour gas and process streams. Remote North American locations prioritize rapid component availability through authorized service networks.
- Refrigeration:Industrial cold chain and commercial HVAC systems generate accelerated valve and seal demand as ammonia and CO2 architectures replace hydrofluorocarbon systems. EU F-Gas Regulation containment requirements concentrate innovation investment in hermetic joint designs.
- Manufacturing:General industrial compressed air and process gas applications.
- Power Generation:Fuel gas compression and auxiliary systems in thermal and combined-cycle plants.
Oil and gas anchors the volume base while refrigeration climbs the fastest.
Functionality:
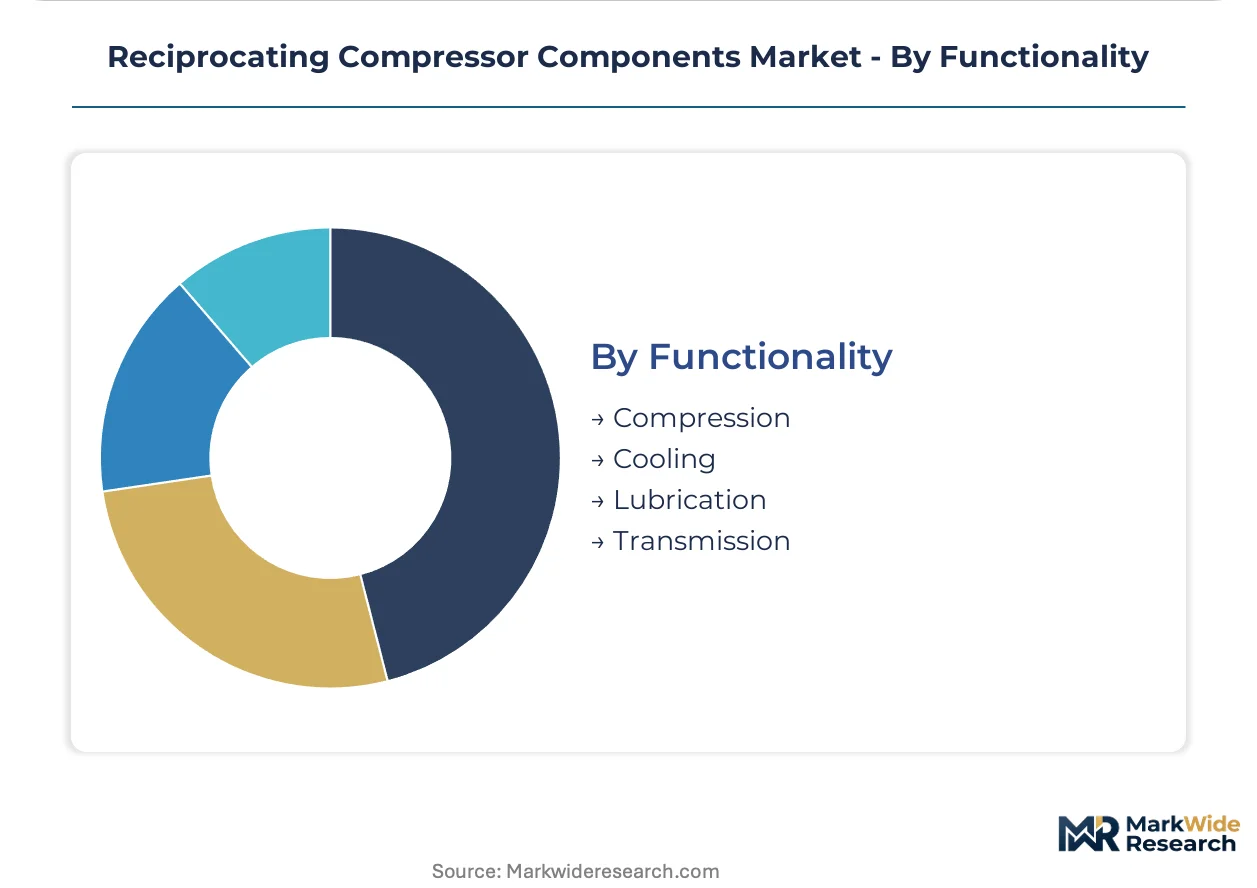
System architecture separates components by their thermodynamic and mechanical role. This functional lens reveals which suppliers can cross-sell across compressor types versus remaining siloed in specialized niches.
- Compression:Pistons, cylinders, and valves executing the core gas displacement function. Petrochemical processing facility upgrades across the US Gulf Coast pull demand for high-pressure assemblies.
- Lubrication:Oil pumps, galleries, and filtration maintaining bearing and seal integrity.
- Cooling:Heat exchangers and thermal management hardware.
- Transmission:Couplings, flywheels, and speed reducers linking driver to compressor.
Compression functionality anchors the volume base while lubrication systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA refrigerant management regulations under Section 608 of the Clean Air Act anchor demand patterns in the United States, while parallel regulatory frameworks across Germany, China, India, and Saudi Arabia create differentiated procurement environments for component suppliers.
United States
Petrochemical processing facilities along the Gulf Coast pull demand for high-pressure cylinder assemblies rated for hydrogen-rich process streams. EPA Section 608 leak-tightness mandates accelerate replacement cycles for piston rings and valve plates in industrial refrigeration infrastructure. Houston and Corpus Christi anchor the densest concentration of compression-intensive refining and chemical manufacturing operations.
Germany
Precision machining capabilities for crankshaft grinding and valve seat lapping remain concentrated among specialized fabricators in Baden-Württemberg and Bavaria. EU F-Gas Regulation containment requirements and CE marking obligations under the Machinery Directive constrain market access for suppliers lacking certified material traceability. The Stuttgart industrial corridor houses the deepest concentration of high-performance valve steel processing expertise.
China
State-backed manufacturing upgrades in industrial heartland provinces concentrate demand for heavy-duty crankshaft and piston replacements. The country's national environmental regulator enforces dual carbon goals that reshape compressor efficiency specifications in heavy industry. Jiangsu and Shandong provinces anchor the largest clusters of petrochemical and steel manufacturing compression infrastructure.
India
The PLI scheme for capital goods creates localization pathways for piston and cylinder production serving South Asian demand. Central Electricity Authority regulations and BIS standards govern pressure equipment certification for industrial installations. Gujarat and Maharashtra host expanding petrochemical and refining complexes that import high-specification components pending domestic supply maturation.
Saudi Arabia
Downstream oil and gas expansion in the Eastern Province generates procurement for continuous-duty compression components in sour gas processing. The country's national petroleum regulator enforces process safety management standards that align with international pressure equipment codes. Jubail Industrial City anchors the densest concentration of gas processing and petrochemical manufacturing infrastructure.
Reciprocating Compressor Components Market Competitive Landscape
Integrated industrial conglomerates and specialized compression technology houses split the market into distinct capability tiers. Consolidation pressures concentrate around captive distribution networks and rapid component availability guarantees for remote oilfield locations. Three archetypes dominate: diversified industrial equipment multinationals with global logistics infrastructure; mid-scale specialists focused on hyperbaric and process gas applications; and regional fabricators serving price-sensitive replacement demand. Competitive moves center on authorized service network expansion and backward integration into precision machining capabilities.
Among diversified industrial equipment multinationals, Atlas Copco AB exemplifies the global logistics archetype through its parts distribution infrastructure. Ingersoll Rand Inc. occupies a position within the captive channel tier, while Burckhardt Compression AG represents the specialized application segment. These three anchors illustrate how supplier economics diverge between high-velocity aftermarket parts and lumpy OEM equipment sales.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand Inc. |
| Burckhardt Compression AG |
| Gardner Denver Holdings, Inc. |
| Ariel Corporation |
| Siemens Energy AG |
| Kaeser Compressors, Inc. |
| Baker Hughes Company |
| ELGi Equipments Ltd. |
| Others |
Value Network & Pricing Analysis
Baden-Württemberg's concentration of precision valve steel processing capacity concentrates pricing power among German fabricators serving global compressor OEMs. This geographic clustering of high-performance metallurgy expertise creates tiered cost structures where certification-grade materials command substantial premiums over commodity ferrous inputs.
Pricing Analysis
Geographic price spreads between Western European precision-machined components and Asian commodity castings reach three-to-one multiples. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified high-pressure assemblies from CE-marked industrial grades and unmarked replacement parts. Pricing pressure stems from India's PLI scheme incentivizing domestic piston and cylinder production at 30-40% cost deltas. Manufacturing end-users exhibit highest price sensitivity, while oil and gas operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts aluminum alloy sourcing for refrigeration piston manufacturers. Component supply draws from Germany, China, and Japan for precision-machined valves; India and Vietnam for emerging casting capacity; and Brazil for regional aftermarket fabrication. Forged crankshaft steel rests on scrap metal availability and electric arc furnace capacity in Turkey and Italy. Single-source vulnerability concentrates in high-performance valve spring wire from a limited Western European supplier base. Distribution runs through authorized service networks for critical assemblies, with third-party channels handling commodity replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Kigali Amendment's refrigerant transition is accelerating component redesign cycles, compressing product lifespans and expanding addressable aftermarket volume. This regulatory inflection creates asymmetric opportunity for suppliers with modular, condition-monitored architectures.
For Market Incumbents: Build captive distribution moats by acquiring regional service networks in the Permian Basin and North Dakota oilfields. Deepen backward integration into precision grinding capabilities in Germany and Japan to secure scarce technician labor pools. Electrification of industrial heat poses substitution threat; anchor position through hydrogen-ready compressor specifications for Gulf Coast petrochemical expansions.
For New Entrants and Emerging Players: Build out ammonia and CO2-compatible valve and seal portfolios targeting cold chain infrastructure retrofits in India and Southeast Asia. India's PLI scheme offers the most penetrable geography for localized piston and cylinder production. Pursue joint development agreements with European refrigeration OEMs seeking second-source suppliers for low-GWP refrigerant systems.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle compounder play because compressor installed base expansion from the 2010s petrochemical boom enters peak maintenance phase. Target mid-scale specialists with hyperbaric process gas expertise and certified material traceability systems. Watch EPA Section 608 enforcement intensity as signal for US aftermarket valve demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captures scarce crankshaft grinding capacity in Baden-Württemberg and Bavaria industrial corridors. |
| Authorized Service Network Expansion | Locks in uptime-critical oil and gas operators across remote North American shale basins. |
| Hydrogen-Ready Component Certification | Positions suppliers for Gulf Coast petrochemical facility upgrades processing hydrogen-rich streams. |
| Low-GWP Refrigerant System Conversion | Captures accelerated valve and seal demand from ammonia and CO2 cold chain retrofits. |
| India PLI Localization Partnership | Establishes cost-competitive piston and cylinder production serving South Asian manufacturing demand. |
Research Methodology
The analysis maps valve, piston, cylinder, and crankshaft sub-sectors, each validated through maintenance directors at oil and gas gathering facilities, refrigeration OEM procurement teams, and aftermarket service network heads. Primary fieldwork combined with secondary validation against SEC filings from listed compressor manufacturers, customs trade data for steel and aluminum alloy flows, and EPA refrigerant enforcement records. Bottom-up component demand modeling triangulated against top-down capital expenditure surveys across petrochemical, refrigeration, and manufacturing end-use segments.
Forecast assumptions held Kigali Amendment implementation timelines and regional decarbonization policy intensity within observed regulatory patterns. The analytical framework spans component type, material grade, end-use severity, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from replacement cycle analysis calibrated against historical compressor installed base data and emerging duty cycle intensity from hydrogen infrastructure buildout. Industry-specific inputs include EPA Section 608 enforcement case volumes and EU F-Gas Regulation containment requirement phase-in schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed manufacturers or Indian PLI beneficiaries would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Servo Valves Market
Valves
Deluge Valve Market
Valves
Global Check Valve Market
Valves
Industrial Valves Market
Valves
Valve Seat Inserts Market
Valves
Chemical Injection Skid Market
Valves
Pipeline Equipment Market
Valves
Flanges Market
Valves
Steel Cylinder Market
Valves
Vacuum Insulated Pipe Market
Valves
Valve Manifold Box (VMB) Market
Valves
Orifice Reducers Market
Valves
Hydraulic Valves Market
Valves
Mooring Inspection Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
Choke Valves Market