
 Bend Restrictors and Stiffeners Market | 2026-2036
Bend Restrictors and Stiffeners Market Size, Share, and Industry Trends Forecast 2026-2036
Bend Restrictors and Stiffeners Market Outlook
Offshore supply channel priorities are tilting toward integrated cable protection bundling as project developers seek single-source accountability. Trelleborg AB leverages its polymer compounding expertise to sustain premium positioning in dynamic bend restrictor applications. Parker Hannifin Corporation anchors North American distribution through its fluid power channel infrastructure, while Tekmar Energy Limited dominates North Sea installation support with specialized vessel-based deployment capabilities.
Bend restrictors and stiffeners are engineered polymer or metallic structures designed to limit cable flexure radius below manufacturer-specified thresholds, typically molded from polyurethane or cast in ductile iron with elastomeric interfaces to prevent fatigue failure in subsea umbilicals and power export cables. Their primary commercial purpose is extending asset life in high-fatigue marine environments where uncontrolled bending induces conductor strand breakage or optical fiber attenuation. Polyurethane bend restrictors command the deepest margin pools due to formulation complexity and certification barriers, while steel stiffeners retain volume leadership in deepwater fixed platforms where compressive loading dominates. Protective sleeves represent the fastest-expanding category as offshore wind array cables proliferate in shallow-to-moderate water depths.
DNV standards, the EU F-Gas Regulation, and the UK Health and Safety Executive's offshore structural integrity frameworks collectively elevate product qualification costs while screening out uncertified suppliers. These regimes mandate traceable material batches, finite-element validated designs, and third-party witnessed factory acceptance testing for all permanently installed subsea cable protection systems. Stakeholders must monitor polymer feedstock volatility and evolving offshore wind turbine platform electrification standards as these forces reshape specification requirements faster than traditional product development cycles can absorb.
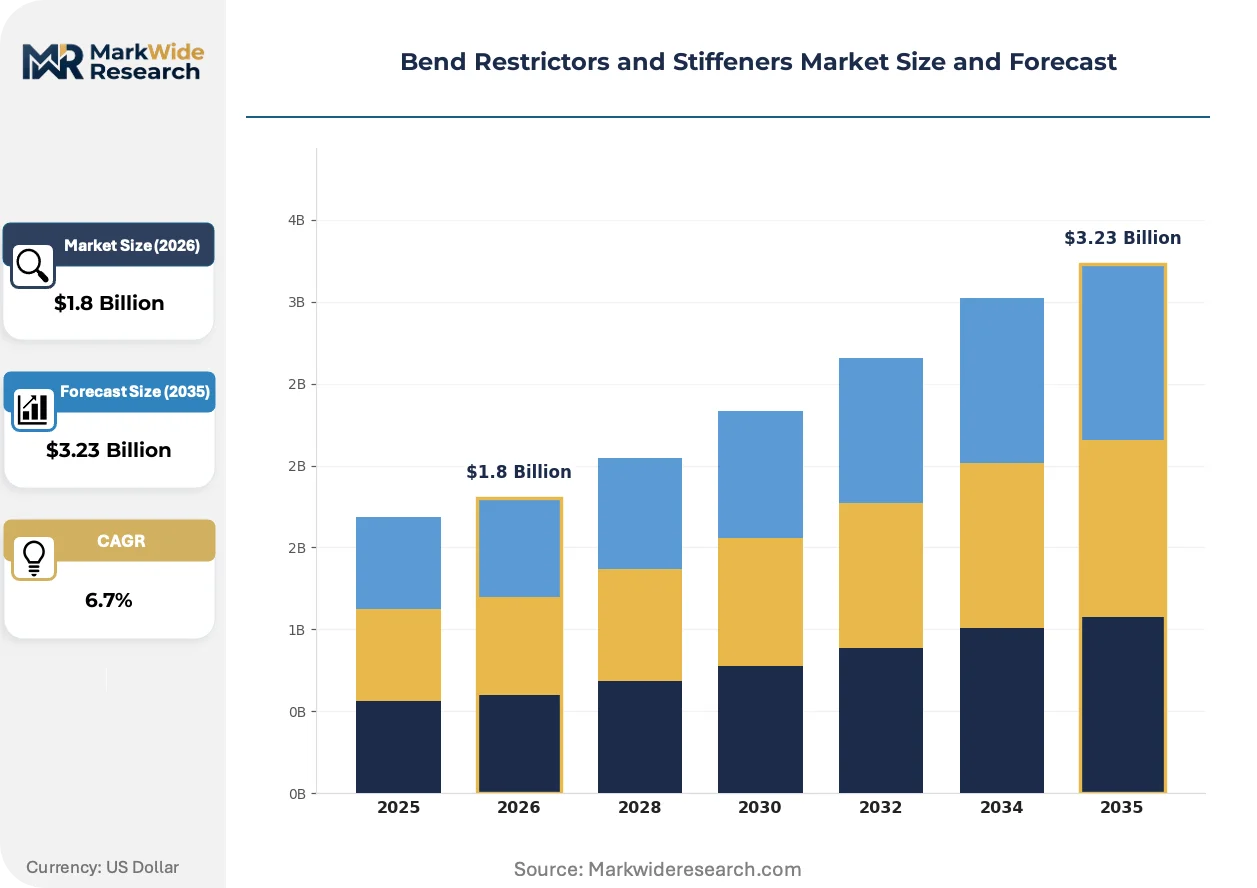
Market Dynamics
Offshore wind farm developers now bundle cable protection procurement into single-source EPC contracts, compressing supplier margins while elevating qualification barriers for component specialists who lack integrated system capabilities.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases accelerates polyurethane formulation R&D, creating first-mover advantages for compounders with recyclable polymer platforms certified under DNV-ST-F203.
- Offshore wind array electrification:Floating turbine platforms in the North Sea require dynamic bend restrictor architectures that accommodate platform motion, expanding addressable scope beyond fixed-bottom installations.
- Shallow-water cable density:Germany's clustered offshore wind zones concentrate protective sleeve demand, driving volume procurement frameworks that favor suppliers with regional manufacturing footprints.
Market Restraints
- Polyol feedstock volatility:Crude-linked polyurethane raw material costs swing unpredictably, squeezing margin stability for molders without backward integration into petrochemical supply.
- Installation vessel scarcity:North Sea cable-lay vessel availability constraints create deployment bottlenecks, forcing project delays that cascade through protective component delivery schedules.
- Steel stiffener displacement limits:Deepwater fixed platforms in Norway's Equinor-operated fields retain ductile iron specifications due to compressive load requirements, capping polymer substitution potential in premium segments.
Strategic Opportunities
- Floating offshore wind scale-up:Portugal's WindFloat Atlantic and Scotland's Kincardine demonstrators validate dynamic cable protection architectures, opening specification windows for fatigue-optimized restrictor designs.
- DNV digital twin integration:Third-party witnessed factory acceptance testing data feeds into asset integrity platforms, creating recurring revenue streams through predictive maintenance service contracts.
- UK Health and Safety Executive framework alignment:Offshore structural integrity mandates drive bundled certification demand, rewarding suppliers with in-house finite-element validation capabilities.
Industry Challenges
- Polymer formulation chemist scarcity:Specialized expertise in hydrolysis-resistant polyurethane elastomers concentrates among legacy compounders, constraining new entrant scale-up.
- Multi-standard certification timelines:Simultaneous DNV, Bureau Veritas, and Lloyd's Register qualification processes extend product commercialization cycles beyond typical offshore wind auction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bend Restrictors and Stiffeners Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bend Restrictors, Cable Stiffeners, Protective Sleeves, Conduits Material: Polyamide, Polypropylene, Steel, Rubber Industry Vertical: Aerospace, Marine, Telecommunications, Automotive Installation Method: Welding, Mechanical Fastening, Adhesive Bonding, Snap-Fit |
| Companies Covered | Parker Hannifin Corporation, Exsto, Trelleborg AB, Vos Prodect, Ovun, Tekmar Energy Limited, Delmar Systems, Inc, The Weir Group, CRP Subsea Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bend Restrictors and Stiffeners Market Strategic Shifts
Material science advances and procurement model compression are converging to redefine competitive differentiation, with certification data portability and modular architectures displacing legacy product-centric selling approaches.
Recycled-content polyurethane is hybridizing conventional fossil-based formulations, maintaining mechanical performance while satisfying EU Green Deal circularity mandates. Offshore wind developers in Denmark and the Netherlands specify minimum recycled content thresholds in tender documents. The structural consequence is a bifurcation between integrated compounders with chemical recycling capabilities and commodity molders dependent on virgin feedstock.
The EU F-Gas Regulation's 2027 phase-down milestones force reformulation of blowing agents and curing catalysts across polyurethane production. Compounders in Germany and Belgium invest in bio-based polyol pilot lines to preempt supply discontinuity. Dynamic bend restrictor categories face the steepest compliance costs due to density-critical foam core requirements.
Integrated cable protection bundling now dominates procurement behavior among major offshore wind developers, collapsing the historical multi-vendor assembly model. Engineering-procurement-construction contractors in the United Kingdom and Germany consolidate specification authority, marginalizing standalone component suppliers without system integration capabilities. Norway's Equinor retains more fragmented sourcing for legacy fixed platforms, preserving niche opportunities for specialized stiffener manufacturers.
Bend Restrictors and Stiffeners Market Segmentation
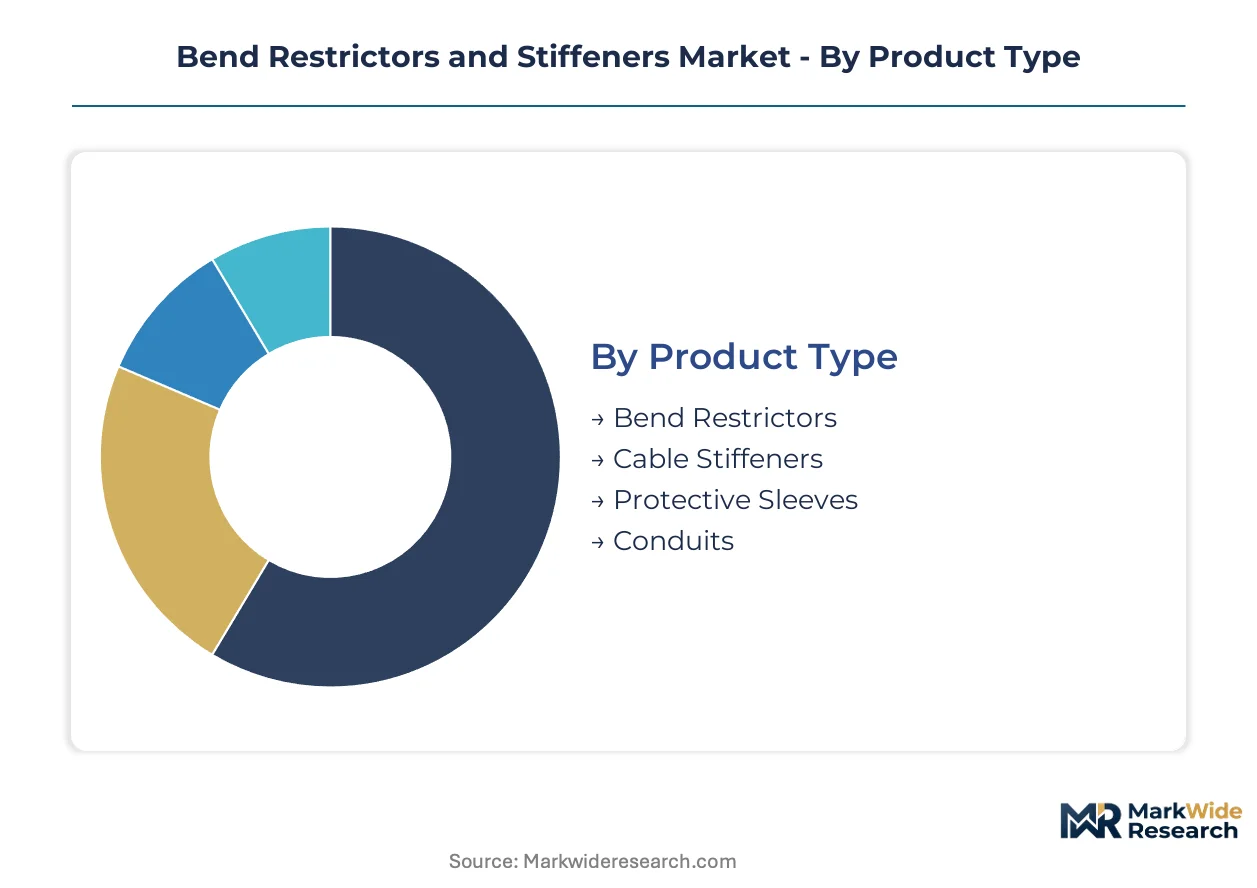
Segmentation in the Bend Restrictors and Stiffeners Market reveals distinct margin pools and qualification barriers across product architectures, material platforms, and installation protocols. Each dimension carries divergent certification requirements and supply chain concentration patterns that reshape supplier positioning.
Product Type:
Mature polyurethane-molded architectures dominate North Sea offshore wind contracts, while emerging dynamic designs gain traction in floating platform applications.
- Bend Restrictors:Polyurethane or ductile iron structures engineered to enforce minimum bend radius limits on subsea umbilicals and power export cables. Norway's Equinor-operated fixed platforms and Germany's clustered offshore wind zones drive specification authority toward DNV-ST-F203 certified compounders with in-house finite-element validation.
- Cable Stiffeners:Metallic or composite reinforcement elements that resist compressive buckling in deepwater riser configurations. Ductile iron specifications persist in Norway's premium fixed-platform segments where compressive loading dominates, constraining polymer substitution despite EU F-Gas Regulation pressures.
- Protective Sleeves:Elastomeric or thermoplastic sheaths for shallow-to-moderate water depth array cables. Germany's densely clustered offshore wind procurement frameworks favor regional molders with recycled-content polyurethane capabilities.
- Conduits:Rigid or semi-rigid channel systems for cable segregation and mechanical shielding. Telecommunications subsea fiber projects in the United Kingdom specify conduits with integrated bend management features.
Bend Restrictors retain volume leadership; Protective Sleeves hold the steepest expansion curve.
Material:
Cost tier differentiation separates premium formulation-controlled compounds from commodity-grade alternatives subject to feedstock volatility.
- Polyamide:Engineering thermoplastic with hydrolysis resistance for dynamic marine environments. Belgium and Germany compounders invest in bio-based pilot lines to preempt EU F-Gas Regulation supply discontinuity.
- Polypropylene:Lightweight thermoplastic with lower density than polyurethane for protective sleeve applications. Shallow-water offshore wind arrays in the Netherlands specify minimum recycled content thresholds.
- Steel:Ductile iron castings with elastomeric interfaces for deepwater fixed platforms. Norway's structural integrity mandates preserve steel specifications in compressive-load-dominated segments.
- Rubber:Natural and synthetic elastomer compounds for compliant interface layers. Marine applications in the United Kingdom require Bureau Veritas-certified rubber formulations.
Steel retains volume leadership in premium fixed-platform segments; Polyamide holds the steepest expansion curve in dynamic applications.
Industry Vertical:
Customer type concentration varies sharply, with marine procurement consolidating into bundled EPC contracts while aerospace retains fragmented specification authority.
- Marine:Offshore wind developers and oil and gas operators requiring subsea cable protection. United Kingdom and Germany EPC contractors now consolidate multi-component procurement into single-source accountability frameworks.
- Telecommunications:Subsea fiber optic cable systems requiring bend management for optical attenuation prevention. North Sea and Atlantic corridor projects drive demand for DNV-certified restrictor assemblies.
- Aerospace:Aircraft wiring harness protection with weight-critical specifications. Fragmented procurement across OEM and MRO channels contrasts with marine consolidation.
- Automotive:High-voltage cable routing in electric vehicle platforms. Emerging specification windows favor snap-fit installation methods for assembly-line integration.
Marine retains volume leadership; Telecommunications holds the steepest expansion curve as subsea fiber density intensifies.
Installation Method:
Application environment dictates method selection, with subsea permanence requiring welded or mechanically fastened solutions while topside modularity favors adhesive and snap-fit alternatives.
- Welding:Permanent metallic stiffener attachment for deepwater fixed platforms. Norway's Equinor-operated fields mandate welded ductile iron specifications for structural integrity compliance.
- Mechanical Fastening:Bolted or clamped assembly enabling field adjustability. United Kingdom offshore wind installation vessels deploy mechanically fastened restrictor systems for vessel-based deployment efficiency.
- Adhesive Bonding:Polyurethane or epoxy-based attachment for polymer-to-polymer interfaces. Germany's recycled-content mandates complicate adhesive formulation selection.
- Snap-Fit:Tool-free modular assembly for protective sleeves and conduits. Automotive and telecommunications applications favor snap-fit for installation speed and rework accessibility.
Mechanical Fastening retains volume leadership in marine applications; Snap-Fit holds the steepest expansion curve in modular system architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Norway's deepwater fixed-platform segments where compressive-load specifications preserve steel stiffener demand, while Germany's offshore wind procurement frameworks drive volume aggregation at compressed margins.
Norway
Equinor-operated fields in the North Sea and Norwegian Sea sustain ductile iron specifications for deepwater fixed platforms where compressive loading dominates. The country's Petroleum Safety Authority mandates structural integrity frameworks that preserve premium steel stiffener procurement. Stavanger anchors subsea engineering clusters where specialized vessel-based deployment capabilities concentrate installation expertise.
Germany
Clustered offshore wind zones in the North Sea concentrate protective sleeve demand through volume procurement frameworks favoring regional manufacturing footprints. The EU F-Gas Regulation accelerates polyurethane formulation shifts toward recyclable polymer platforms certified under DNV-ST-F203. Bremerhaven and Cuxhaven host cable-lay vessel operations where mechanically fastened restrictor systems deploy for installation efficiency.
United Kingdom
The Health and Safety Executive's offshore structural integrity frameworks elevate bundled certification demand for permanently installed subsea cable protection systems. EPC contractors consolidate multi-component procurement into single-source accountability frameworks. Aberdeen maintains subsea engineering clusters where integrated cable protection bundling dominates developer procurement behavior.
Netherlands
Shallow-water offshore wind arrays specify minimum recycled content thresholds in tender documents for protective sleeve applications. The EU Green Deal circularity mandates drive specification authority toward compounders with chemical recycling capabilities. Rotterdam's port infrastructure supports cable-lay logistics where vessel availability constraints create deployment bottlenecks.
Belgium
Compounders invest in bio-based polyol pilot lines to preempt EU F-Gas Regulation supply discontinuity for dynamic bend restrictor foam core requirements. The country's national chemical regulator enforces traceable material batch requirements for subsea installations. Port of Antwerp-Bruges clusters polyurethane formulation expertise where hydrolysis-resistant elastomer R&D concentrates.
Bend Restrictors and Stiffeners Market Competitive Environment
Polymer compounders and steel fabricators split the market along material-platform lines, with formulation-controlled specialists commanding premium positioning in dynamic applications while metal-casting incumbents retain fixed-platform dominance. The vendor base concentrates among DNV-certified suppliers with in-house finite-element validation capabilities, screening out uncertified competitors through qualification barriers. Three archetypes define competitive positioning: integrated compounders with captive polymer supply, specialized installation-support contractors with vessel-based deployment assets, and diversified industrial conglomerates with fluid power distribution infrastructure. Dominant competitive moves center on backward integration into petrochemical feedstock and strategic partnerships with EPC contractors for bundled system procurement.
Within the integrated compounder tier, Trelleborg AB exemplifies premium positioning through polymer formulation expertise, while Tekmar Energy Limited occupies a position among installation-support specialists with North Sea vessel capabilities. Parker Hannifin Corporation anchors the diversified conglomerate archetype through fluid power channel infrastructure. These three represent the strategic archetypes reshaping competitive dynamics as procurement consolidation favors suppliers with system integration capabilities over standalone component manufacturers.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Exsto |
| Trelleborg AB |
| Vos Prodect |
| Ovun |
| Tekmar Energy Limited |
| Delmar Systems, Inc |
| The Weir Group |
| CRP Subsea Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in North Sea cable-lay vessel fleets compresses installation schedules and elevates urgency premiums for mechanically fastened restrictor systems, while simultaneously squeezing compounder margins as EPC contractors consolidate procurement authority.
Pricing Analysis
Configured-to-order pricing for DNV-ST-F203 certified dynamic bend restrictors commands spreads of 40-60% above standard protective sleeve catalog pricing, with differentiation anchored in finite-element validation documentation and third-party witnessed factory acceptance testing. Price compression runs through shallow-water array cable segments as Germany's volume procurement frameworks aggregate demand and eliminate specification premiums. Polyurethane compounders with backward integration into petrochemical feedstock exhibit lowest price sensitivity; standalone molders dependent on spot polyol markets face acute margin vulnerability.
Supply Chain Analysis
Polyol feedstock supply concentrates in Belgium, Germany, and the Netherlands, with bio-based pilot lines emerging to preempt EU F-Gas Regulation discontinuity. Hydrolysis-resistant polyurethane elastomer production draws from crude-linked aromatic isocyanates and specialty polyether polyols, exposing compounders to commodity price volatility. Single-source vulnerability concentrates in North Sea cable-lay vessel availability, where installation bottlenecks cascade through protective component delivery schedules. Distribution runs through EPC contractor consolidated procurement frameworks in the United Kingdom and Germany, marginalizing standalone component suppliers without system integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among EPC contractors bundling multi-component procurement into single-source accountability frameworks, fragmenting specification authority away from standalone component suppliers.
For Market Incumbents: Build formulation-controlled moats around hydrolysis-resistant polyurethane elastomer expertise to defend against recycled-content compounders with chemical recycling capabilities. Deepen backward integration into bio-based polyol pilot lines to preempt EU F-Gas Regulation supply discontinuity. Anchor capacity additions in Bremerhaven and Cuxhaven to capture Germany's clustered offshore wind volume procurement. For New Entrants and Emerging Players: Establish a beachhead in automotive high-voltage cable routing segments where snap-fit installation methods and assembly-line integration specifications remain underpenetrated by marine-focused incumbents. Target telecommunications subsea fiber projects in the Atlantic corridor with DNV-certified restrictor assemblies as specification windows open outside North Sea concentration. Pursue channel partnerships with European cable-lay vessel operators to bypass EPC procurement consolidation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across dynamic bend restrictor foam core production as EU F-Gas Regulation compliance forces reformulation investment. Five-to-ten year viability favors integrated compounders with captive polymer supply and in-house finite-element validation capabilities over commodity molders. Monitor bio-based polyol pilot line commissioning announcements as inflection indicators for first-mover certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyol Supply | Preempts EU F-Gas Regulation supply discontinuity for dynamic bend restrictor foam cores. |
| DNV Digital Twin Integration | Feeds factory acceptance testing data into asset integrity platforms for recurring predictive maintenance revenue. |
| Regional Manufacturing Footprint Expansion | Captures Germany's clustered offshore wind volume procurement frameworks with localized production. |
| Recycled-Content Polyurethane Certification | Satisfies Netherlands and Denmark tender thresholds for minimum circularity mandates. |
| Installation-Support Vessel Partnerships | Bypasses EPC contractor procurement consolidation through direct deployment capability relationships. |
Study Parameters
A spread of perspectives from subsea engineering directors, EPC procurement leads, polyurethane R&D heads, cable-lay vessel operators, and DNV certification specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings from listed industrial conglomerates, Bureau Veritas and Lloyd's Register certification databases, and EU regulatory filings. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across product architecture, material platform, installation protocol, and regional regulatory cluster. CAGRs derived from elasticity-adjusted growth curves incorporating offshore wind auction timelines, vessel availability constraints, and polymer feedstock volatility. Industry-specific inputs included DNV-ST-F203 certification pipeline tracking, Equinor field development schedules, and UK Health and Safety Executive framework evolution.
Stress conditions across polyol price volatility bands, cable-lay vessel availability bottlenecks, and EU F-Gas Regulation phase-down milestones were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from macroeconomic, regulatory, or technological shifts in subsea cable protection applications. Cross-checking against IEA offshore wind capacity announcements and DNV certification registry updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Marine Actuators and Valves Market
Valves
Global Pipeline Safety Market
Valves
Global Industrial Thermostatic Control Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Subsea Valves Market
Valves
Magnetic Coupler Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Chemical Injection Skid Market
Valves
Cathodic Protection Market
Valves
Safety Valve Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Valve Manifold Box (VMB) Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Pneumatic Positioner Market
Valves
Servo Valves Market
Valves
North America Industrial Valves Market