
 Europe Valves Market | 2026-2036
Europe Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Valves Market Foresight
Industrial distribution channels serving the Europe Valves Market is tilting toward direct OEM partnerships and engineered-solutions contracts. Emerson Electric Co. leverages its automation portfolio to bundle valve and control systems for process industries. KSB SE & Co. KGaA anchors its position through deep vertical integration in pump-valve combined offerings. Alfa Laval Corporate AB specializes in hygienic valve designs that dominate food and pharmaceutical processing installations.
A valve is a mechanical device that regulates, directs, or controls fluid flow by opening, closing, or partially obstructing passageways, typically constructed with pressure-rated bodies, elastomeric or metal seals, and actuation mechanisms rated for temperatures from cryogenic to above 500°C. Its primary industrial purpose is to ensure safe, efficient, and precise management of liquids, gases, and slurries across continuous and batch processes. Ball valves capture substantial share in oil and gas transmission due to tight shutoff and quarter-turn speed, while stainless steel material grades command margin premiums in chemical processing and power generation where corrosion resistance extends service intervals. Gate valves retain maturity in water treatment bulk flow applications where full-port, low-pressure-drop characteristics outweigh cost sensitivity.
The EU Green Deal, REACH, and F-Gas Regulation collectively mandate tighter fugitive emission limits and material traceability across valve supply chains, forcing manufacturers to certify low-emission packing and qualify alternative sealing compounds. CE marking under the Pressure Equipment Directive remains mandatory for market access, with notified bodies in Germany, Italy, and France conducting conformity assessments. Stakeholders must monitor evolving ECHA substance restrictions and national transposition timelines to anticipate material redesign obligations and certification renewal cycles.
Market Dynamics
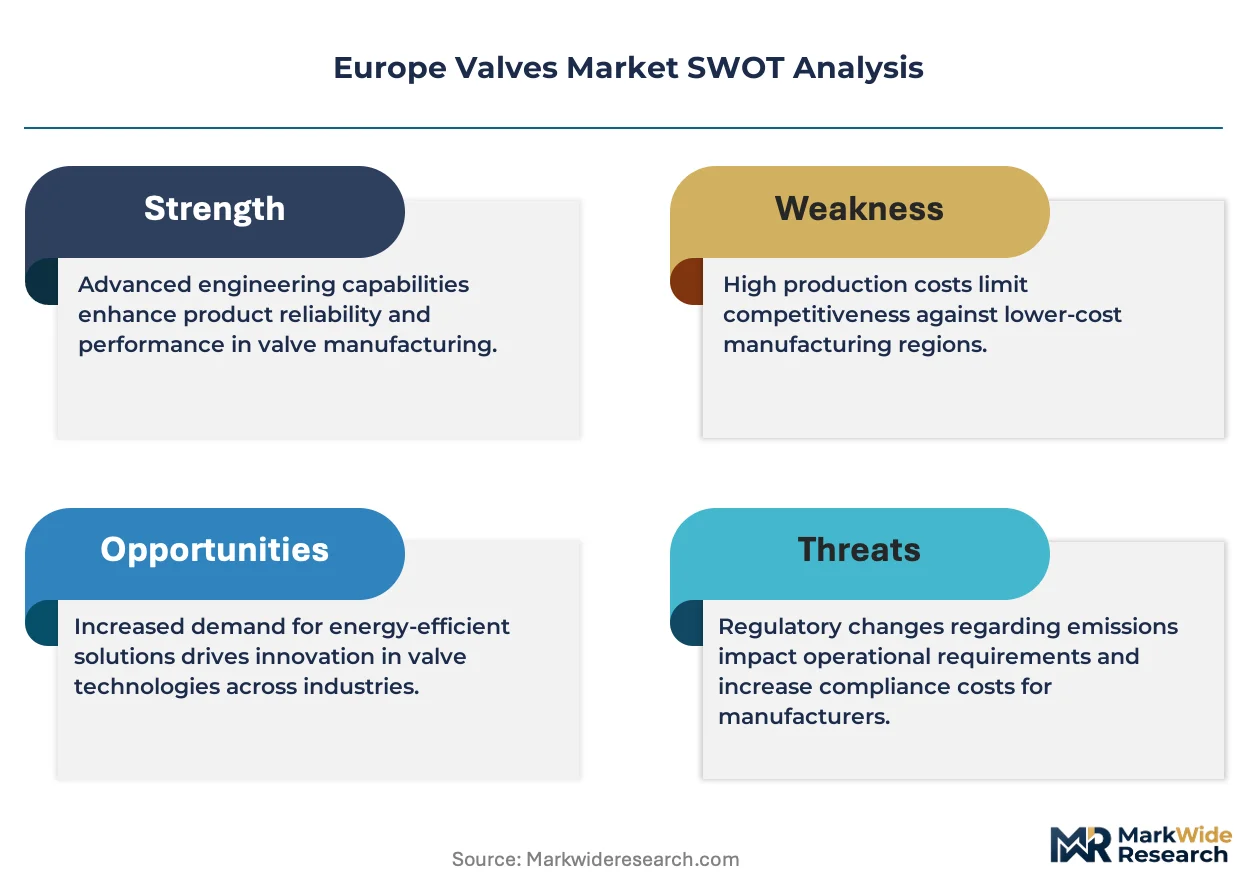
The EU Green Deal and F-Gas Regulation are compressing allowable emission thresholds across process industries, forcing valve manufacturers to redesign sealing architectures and recertify product lines for low-leakage performance. This regulatory tightening is reshaping procurement criteria and supplier qualification timelines.
Growth Catalysts
- Water infrastructure modernization:Utilities across Germany, France, and Italy are replacing aging gate and butterfly valve fleets with automated, remotely operable alternatives to reduce unplanned downtime.
- REACH substance restrictions:ECHA's expanding candidate list is accelerating demand for fluoropolymer-free packing materials and metal-to-metal seal designs in chemical processing.
- Hydrogen economy buildout:Electrolyzer and pipeline projects in the Netherlands and Spain are specifying cryogenic-rated ball valves with specialized metallurgy for high-purity hydrogen service.
Market Restraints
- Specialized alloy supply concentration:Super-duplex stainless steel and Inconel feedstocks concentrate among Scandinavian and German specialty mills, creating input cost volatility for severe-service valve producers.
- CE marking conformity costs:Notified body assessments under the Pressure Equipment Directive impose fixed compliance burdens that disproportionately constrain mid-tier manufacturers without captive testing facilities.
- Extended replacement cycles:Advanced coating technologies and predictive maintenance adoption are stretching intervals between valve replacements in mature industrial installations.
Strategic Opportunities
- Polish and Romanian industrial expansion:Automotive and battery manufacturing investments in these markets are creating demand for hygienic and high-pressure valve configurations previously concentrated in Western Europe.
- Digital twin integration:Valve-embedded sensors converging with asset management platforms enable predictive maintenance contracts that capture recurring revenue streams from process operators.
- Carbon border adjustment mechanism:CBAM implementation is incentivizing local valve production and near-shoring of foundry operations to avoid embedded emissions tariffs on imported castings.
Industry Challenges
- Materials engineering talent scarcity:Specialized expertise in elastomer compatibility for aggressive chemical service is concentrating among aging workforces in German and Italian valve design centers.
- Legacy system integration complexity:Retrofitting smart actuation onto installed valve populations requires custom mechanical adapters and control signal translation that prolongs commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Valves Market |
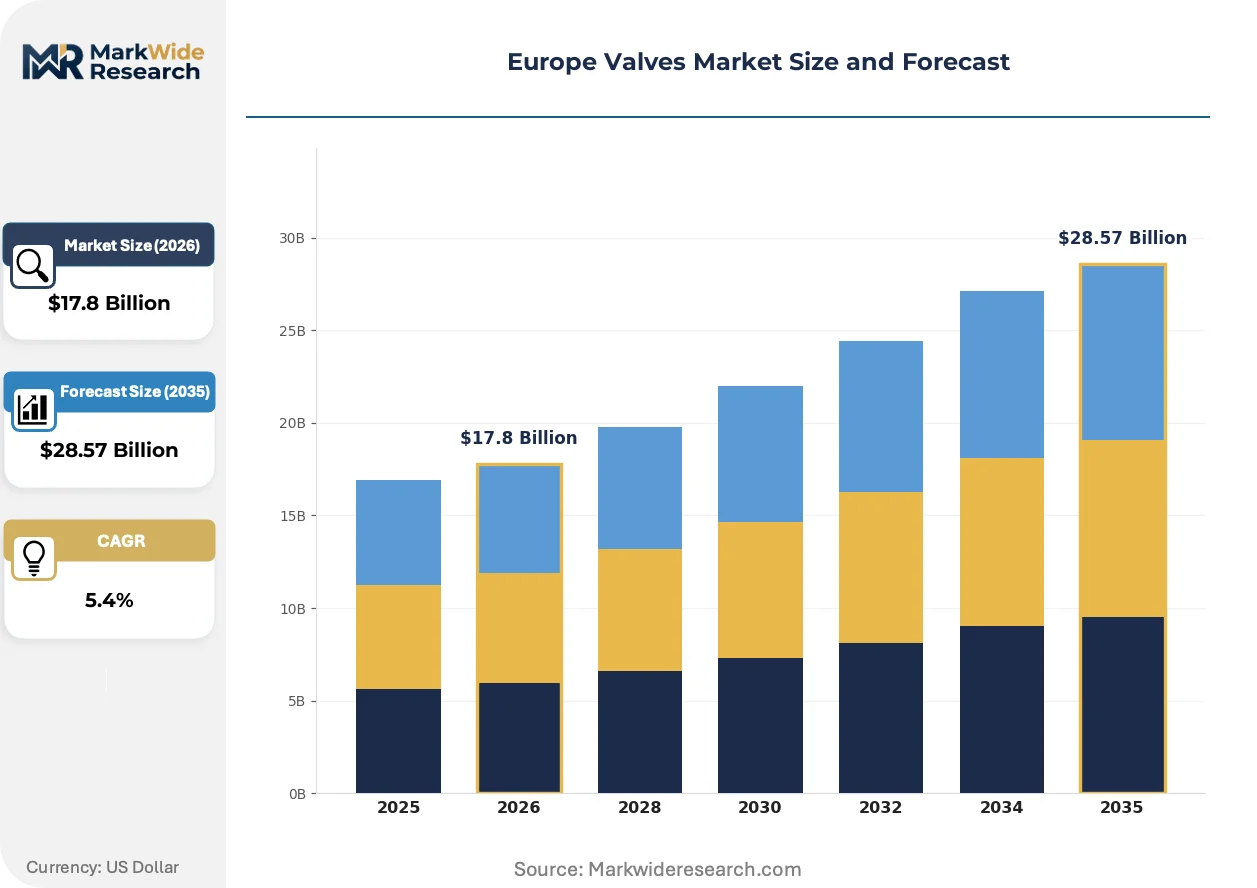
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
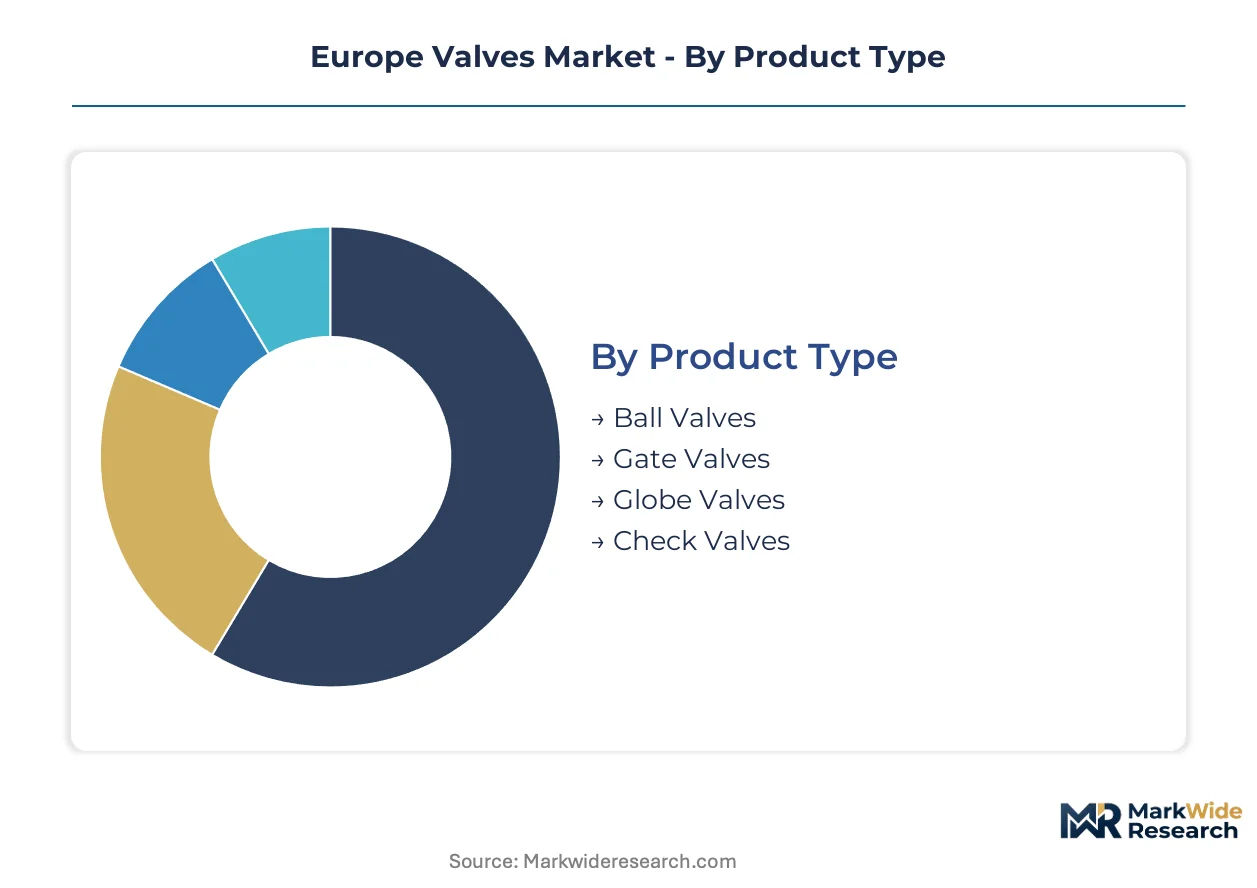
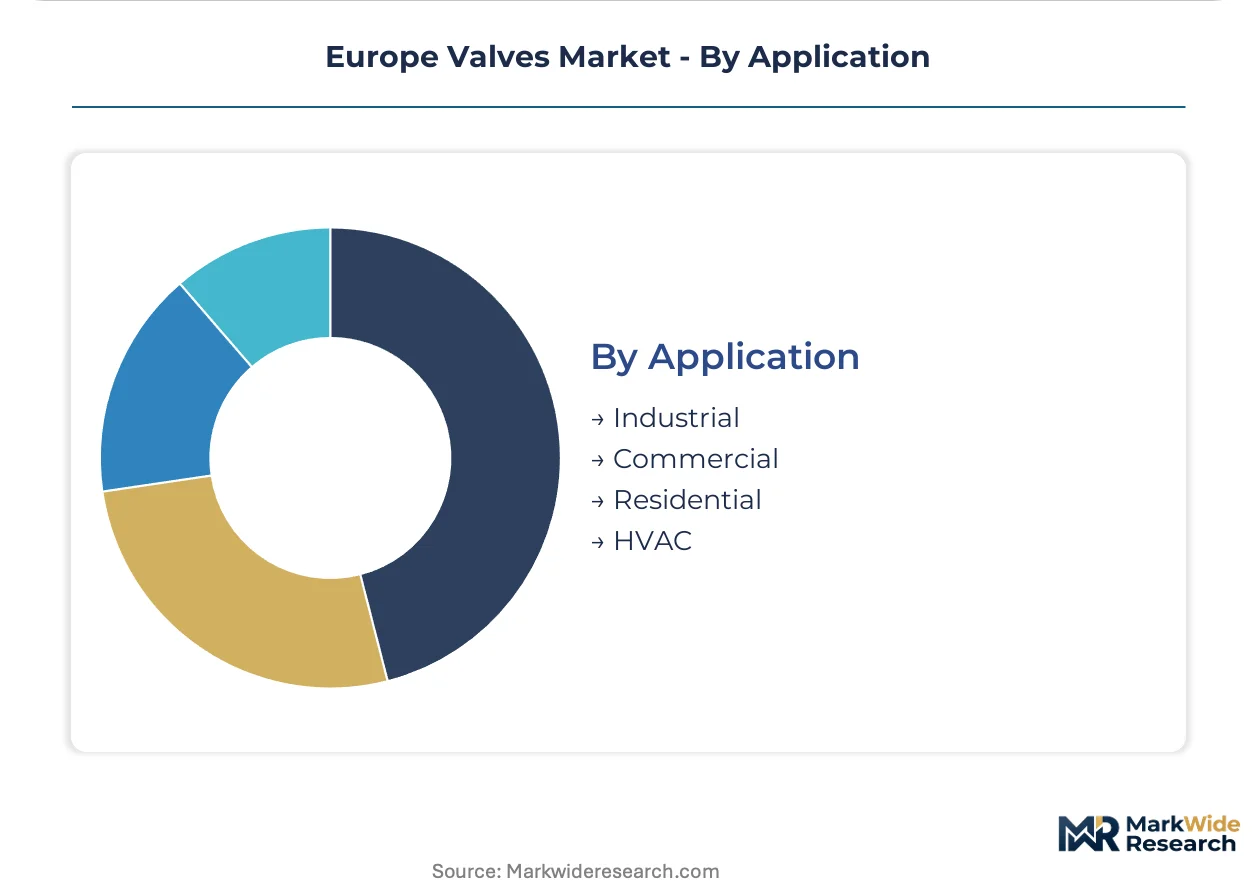
| Segmentation | Product Type: Ball Valves, Gate Valves, Globe Valves, Check Valves End User: Oil & Gas, Water Treatment, Power Generation, Chemical Processing Material: Stainless Steel, Cast Iron, PVC, Bronze Application: Industrial, Commercial, Residential, HVAC |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Alfa Laval Corporate AB, IMI plc, Crane Company, Danfoss A/S, AVK Holding A/S, KSB SE & Co. KGaA, Schlumberger Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Valves Market Shifts & Advancements
Digital instrumentation and advanced materials are redefining how valve performance is monitored, certified, and monetized across European process industries. These shifts are compressing traditional hardware margins while opening service-based revenue architectures.
Smart valve positioners equipped with edge computing capabilities are virtualizing traditional maintenance schedules by processing vibration, temperature, and stroke signature data locally. Chemical and power generation operators in Belgium and the Netherlands are deploying these devices at scale to shift from calendar-based overhaul to condition-triggered intervention. This virtualization is collapsing the distinction between valve hardware and process control software, enabling OEMs to capture recurring diagnostic revenue.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon-based sealing compounds is compelling reformulation of packing materials across the entire installed base. ECHA's restriction roadmap is forcing manufacturers to qualify graphite and PTFE alternatives for high-temperature steam and hydrocarbon service. Food and pharmaceutical processors in Denmark and Switzerland are responding fastest, specifying fully fluorine-free valve architectures ahead of mandate timelines to secure green certification premiums.
Engineered-solution contracting is displacing transactional valve procurement as project owners consolidate supplier relationships. EPC firms serving North Sea oil and Nordic renewable hydrogen projects are bundling valve specification, actuation integration, and commissioning under single-source responsibility. This concentration is most pronounced in offshore energy and carbon capture installations, where interface risk allocation favors turnkey performance guarantees over component-level purchasing.
Europe Valves Market Segmentation
Valve procurement cycles vary dramatically across Europe's industrial base, with some segments turning every 3-5 years in corrosive chemical service while others stretch past 15 years in municipal water infrastructure. Understanding these replacement rhythms shapes inventory strategy and aftermarket service planning for manufacturers serving the region.
Product Type:
Quarter-turn designs cycle faster than linear-motion alternatives due to seal wear patterns in high-cycle service, while gate valves in low-actuation water applications demonstrate the longest field lifespans.
- Ball Valves:Spherical closure elements rotate 90 degrees to achieve tight shutoff with minimal operating torque. Hydrogen pipeline projects in the Netherlands and Spain are specifying cryogenic-rated ball valves with specialized metallurgy for high-purity service, driving accelerated procurement cycles.
- Gate Valves:Wedge or parallel-slide disks move perpendicular to flow direction, providing full-port, low-pressure-drop characteristics ideal for bulk transfer. German and French water utilities are replacing aging gate valve fleets with automated alternatives, though replacement intervals remain the longest in the product spectrum.
- Globe Valves:Disk-and-seat geometry enables precise throttling control across steam and chemical modulation applications.
- Check Valves:Self-actuating designs prevent backflow without external power, concentrating in pump discharge protection across industrial installations.
Gate valves anchor the volume base while ball valves gain share at the steepest rate.
End User:
Capital intensity and regulatory exposure create divergent margin profiles across end-use sectors, with process industries accepting premium pricing for certified severe-service designs.
- Oil & Gas:Exploration, production, and transmission operations demand fire-safe, sour-gas-rated valves with API certification. North Sea operators and Nordic renewable hydrogen projects are consolidating procurement under engineered-solution contracts that bundle specification, actuation, and commissioning.
- Water Treatment:Municipal and industrial utilities prioritize reliability and remote operability over precision control. Infrastructure modernization across Germany, France, and Italy is accelerating replacement of manual valves with automated, remotely operable alternatives to reduce unplanned downtime.
- Power Generation:Thermal, nuclear, and renewable plants specify pressure-rated designs for steam, cooling water, and feedwater systems.
- Chemical Processing:Aggressive media compatibility drives specification of exotic alloys and fluoropolymer-free packing materials under REACH substance restrictions.
Water treatment anchors the volume base while chemical processing climbs the fastest on regulatory-driven material upgrades.
Material:
Raw material cost volatility and alloy supply concentration shape procurement risk profiles, with super-duplex and Inconel feedstocks concentrating among Scandinavian and German specialty mills.
- Stainless Steel:Austenitic and duplex grades deliver corrosion resistance for chemical, pharmaceutical, and food processing. Stainless steel material grades command margin premiums where corrosion resistance extends service intervals in chemical processing and power generation applications.
- Cast Iron:Gray and ductile iron bodies dominate low-pressure water distribution for cost-sensitive municipal infrastructure.
- PVC:Thermoplastic construction offers chemical resistance and lightweight installation for corrosive fluid handling.
- Bronze:Copper-tin alloys provide seawater compatibility and low-friction seating in marine and desalination service.
Cast iron anchors the volume base while stainless steel expands most quickly on process industry specification upgrades.
Application:
Performance certification requirements and actuation complexity stratify the application landscape, with industrial process control demanding the most sophisticated integration.
- Industrial:Continuous and batch process plants require pressure-rated, emission-certified valves with smart positioners and predictive diagnostic capability. Chemical and power generation operators in Belgium and the Netherlands are deploying edge-computing valve positioners at scale to enable condition-triggered maintenance.
- Commercial:Building services and district heating applications balance first cost with energy efficiency in moderate-pressure systems.
- Residential:Plumbing and heating systems prioritize compact dimensions and ease of installation over extended service ratings.
- HVAC:Climate control systems specify low-leakage dampers and control valves for energy code compliance.
Industrial applications anchor the volume base while commercial installations show the steepest expansion trajectory on building efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German valve manufacturers command pricing premiums for certified severe-service designs, while Polish and Romanian fabricators compete on volume for standard industrial configurations. This asymmetry shapes procurement patterns across the continent.
Germany
Water utilities in North Rhine-Westphalia and Bavaria are replacing aging gate valve fleets with automated alternatives, while chemical processors specify exotic alloys for corrosive service. The F-Gas Regulation drives recertification of low-leakage packing across the Ruhr industrial cluster. Stuttgart and Munich anchor precision engineering centers where materials expertise concentrates among aging workforces.
France
Nuclear power maintenance and offshore wind projects sustain demand for pressure-rated designs in steam and cooling water systems. REACH substance restrictions accelerate qualification of fluoropolymer-free sealing compounds. The Lyon-Grenoble corridor hosts process industry clusters specifying hygienic valve architectures for pharmaceutical manufacturing.
Italy
Food and pharmaceutical processors in Emilia-Romagna specify fully fluorine-free valve designs ahead of mandate timelines to secure green certification premiums. CE marking conformity assessments by Italian notified bodies impose fixed compliance burdens on mid-tier manufacturers. Milan and Turin concentrate design centers with specialized elastomer compatibility expertise.
Netherlands
Electrolyzer and hydrogen pipeline projects specify cryogenic-rated ball valves with specialized metallurgy for high-purity service. Rotterdam's port infrastructure drives demand for marine-compatible bronze and super-duplex configurations. Chemical operators in the Antwerp-Rotterdam-Amsterdam cluster deploy edge-computing valve positioners at scale for condition-triggered maintenance.
Poland
Automotive and battery manufacturing investments in Silesia and Greater Poland create demand for hygienic and high-pressure valve configurations previously concentrated in Western Europe. The Carbon Border Adjustment Mechanism incentivizes local foundry operations to avoid embedded emissions tariffs. Warsaw and Kraków emerge as distribution hubs for Eastern European industrial expansion.
Europe Valves Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material-critical niches. The vendor base stratifies between automation bundlers, verticalized pump-valve combinations, and precision fabricators serving severe-service applications. Three archetypes dominate: diversified industrial conglomerates with process control portfolios, family-owned engineering groups with captive foundry capacity, and niche specialists in hygienic or cryogenic designs. Competitive moves concentrate on engineered-solution contracting and backward integration into specialty alloy supply.
Within the diversified industrial tier, Emerson Electric Co. and Flowserve Corporation exemplify platform players bundling valve and control systems for process industries. Alfa Laval Corporate AB occupies a position among specialists in hygienic designs for food and pharmaceutical processing. KSB SE & Co. KGaA represents the vertically integrated archetype through pump-valve combined offerings with deep in-house production of critical components.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Alfa Laval Corporate AB |
| IMI plc |
| Crane Company |
| Danfoss A/S |
| AVK Holding A/S |
| KSB SE & Co. KGaA |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Undercapacity in Scandinavian super-duplex stainless mills is tightening feedstock availability and amplifying pricing power for severe-service valve producers serving North Sea hydrogen projects. German and Italian notified body bottlenecks are extending lead times for CE-marked configurations, compressing margins on standard industrial grades while cryogenic-certified alternatives capture widening premiums.
Pricing Analysis
The customization-premium spread separates configured-to-order cryogenic ball valves from catalog-standard gate valves by a factor reflecting metallurgy complexity and certification depth. Project-based pricing dominates engineered-solution contracts bundling actuation, commissioning, and predictive diagnostics, while transactional per-unit sales persist in municipal water replacement cycles. Price differentiation rests on CE marking tier and alloy grade, with F-Gas Regulation compliance adding certification cost layers that least price-sensitive hydrogen developers absorb readily. Cost compression in standard cast iron water valves is intensifying as Polish foundries expand capacity, while margins tighten least in hygienic stainless configurations where Alfa Laval and KSB anchor brand premiums.
Supply Chain Analysis
Contract manufacturing concentrates among German specialty foundries in Düsseldorf-Duisburg corridor, Italian precision machining clusters around Milan-Turin, and emerging Polish casting operations in Silesia. Raw material dependencies draw from Scandinavian super-duplex mills, German Inconel feedstock suppliers, and graphite packing compound producers in France and Switzerland. Single-source vulnerability concentrates in cryogenic-rated alloy supply for hydrogen service, where three Nordic mills control specification-grade output. Distribution runs through direct OEM partnerships for process industries, with engineered-solution contractors displacing traditional distributor networks in offshore energy and carbon capture installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as EPC firms and utility consortia consolidate procurement under single-source engineered-solution contracts, fragmenting the supplier base into performance-guarantee winners and component-price takers.
For Market Incumbents: Insulate margin position through captive super-duplex alloy supply agreements with Scandinavian mills, locking in feedstock priority for hydrogen certification ramps. Deepen backward integration into smart actuator production to capture diagnostic revenue streams that emerging digital twin platforms threaten to disintermediate. CE marking renewal cycles under evolving ECHA substance restrictions demand proactive packing material qualification to avoid forced redesign windows. For New Entrants and Emerging Players: Pursue white-space expansion in Romanian battery manufacturing and Polish automotive fluid systems, where Western European specification standards are penetrating faster than established supplier footprints. Target hygienic valve configurations for Eastern European pharmaceutical investments as REACH compliance becomes table stakes for EU market access. A go-to-market angle through predictive maintenance service contracts, rather than hardware-only positioning, sidesteps incumbent brand advantages in direct procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic metallurgy and edge-computing actuator development, favoring scaled platforms over niche fabricators. Long-term viability in this market hinges on recurring service revenue attachment rates rather than replacement-cycle hardware exposure. Acquisition target archetypes include mid-tier Italian valve designers with elastomer expertise and aging ownership structures, plus Nordic foundry-integrated specialists serving hydrogen infrastructure. The signal to watch is CBAM implementation pace, which determines near-shoring economics for foundry capacity decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive super-duplex capacity insulates margin against Scandinavian mill pricing power and hydrogen certification bottlenecks. |
| Predictive Maintenance Platform Development | Edge-computing valve positioners enable recurring diagnostic revenue that collapses traditional hardware-only business models. |
| Fluoropolymer-Free Packing Qualification | ECHA restriction roadmaps and F-Gas Regulation phasedown mandate graphite and PTFE alternative certification ahead of compliance deadlines. |
| Near-Shored Foundry Expansion | CBAM embedded emissions tariffs on imported castings incentivize Polish and Romanian production for EU market access. |
| Engineered-Solution Contracting Capability | Single-source performance guarantees displace component-level purchasing in North Sea oil and Nordic renewable hydrogen projects. |
Research Methodology
A spread of perspectives from plant engineers at German chemical processors, procurement leads at French water utilities, EPC contractors serving Dutch hydrogen projects, and aftermarket service heads at Italian valve manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through CE marking databases, ECHA substance restriction filings, customs trade data on alloy imports, and SEC disclosures from listed industrial conglomerates. Bottom-up segment sizing triangulated against top-down macro industrial production indices.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling replacement cycles by product type, material grade, end-use sector, and application intensity. Segmentation dimensions included quarter-turn versus linear-motion designs, austenitic versus duplex stainless grades, and industrial process control versus commercial building services. CAGRs derived from historical procurement pattern analysis and regulatory mandate timelines, with hydrogen economy buildout rates and water infrastructure modernization spend curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, alloy commodity price volatility, or ECHA restriction enforcement pace would shift the trajectory. Forecasts embed assumptions on CE marking processing efficiency and super-duplex mill capacity expansion that warrant sensitivity testing. Quarterly review of notified body queue lengths, hydrogen project FID announcements, and CBAM tariff implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Valve Sack Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Air Heated Vaporizer Market
Valves
Subsea Control System Market
Valves
Choke Valves Market
Valves
Butterfly Valves Market
Valves
Steam Trap Market
Valves
Motorized Valves Market
Valves
Insulation Flanges Market
Valves
Three Way Ball Valve Market
Valves
APAC Valves Market
Valves
Valve Interlocks Market
Valves
Leak Detection Market
Valves
Pneumatic Slide Gates Market
Valves
Thermal Power Valve Market
Valves
Emergency Venting System Market