
 India Industrial Valves Market | 2026-2036
India Industrial Valves Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Valves Market Insights
Gujarat's petrochemical and refinery capacity build-out is reconfiguring procurement patterns across India's valve supply base. L&T Valves Limited anchors large-project execution through its domestic manufacturing footprint and engineering depth. Kirloskar Brothers Limited leverages its century-old brand equity and irrigation-to-industrial diversification to sustain recurring orders. Flowserve Corporation competes on technology leadership in severe-service applications, positioning its Indian operations as a regional export hub.
Industrial valves are mechanical devices engineered to control, direct, or modulate fluid flow within piping systems, typically rated by pressure class, temperature tolerance, and Cv flow coefficient as core functional parameters. Stainless steel valve fabrication dominates premium procurement for corrosive chemical processing, while cast iron retains volume leadership in water treatment and utility distribution where cost efficiency outweighs metallurgical demands. Ball valves capture growing share in oil and gas quick-cycle operations, whereas gate valves occupy mature, maintenance-intensive positions in power generation feedwater systems.
BIS standards, CEA thermal power directives, and the Petroleum and Natural Gas Regulatory Board's pipeline safety codes collectively determine product certification requirements and market access thresholds for domestic and imported valves. India's PLI scheme for specialty steel and precision manufacturing is gradually reshaping local sourcing economics for valve castings and forged components. Stakeholders must monitor how state-level environmental clearances and coastal refinery expansions alter delivery timelines and specification intensity.
Market Dynamics
The India Industrial Valves Market is being restructured by the mandatory BIS certification regime and the concurrent shift toward smart actuation systems. These twin pressures are compressing replacement cycles and disqualifying legacy suppliers while opening procurement lanes for digitally integrated valve architectures.
Growth Catalysts
- Petrochemical capacity build-out:Refinery expansions in Gujarat's industrial corridor are generating bulk orders for severe-service valves rated for high-pressure hydrogen and sour gas applications.
- CEA thermal power directives:The Central Electricity Authority's emission norms are forcing retrofits of feedwater and steam isolation valves across aging coal plants.
- Smart valve actuation:Integration of IoT-enabled positioners and predictive diagnostics is digitizing maintenance workflows in oil and gas midstream infrastructure.
Market Restraints
- Specialty steel import dependency:High-grade stainless steel forgings for corrosive service valves remain concentrated in European and Japanese mill supply bases.
- BIS certification timelines:Bureau of Indian Standards testing protocols create 12-18 month product approval windows that freeze out speculative product development.
- Cast iron substitution ceiling:Ductile iron and thermoplastic valve alternatives cap pricing power in municipal water distribution segments.
Strategic Opportunities
- PLI scheme for specialty steel:Production-linked incentives for precision manufacturing are gradually enabling captive sourcing of valve castings and forged bodies.
- Hydrogen pipeline infrastructure:Emerging demand for high-integrity ball valves in nascent hydrogen blending and transmission networks offers first-mover positioning.
- Digital twin integration:Convergence of valve telemetry with plant-level digital twin platforms creates recurring software and analytics revenue streams.
Industry Challenges
- Smart valve integration complexity:Retrofitting digital positioners onto legacy mechanical actuators demands scarce instrumentation engineering talent.
- Environmental clearance delays:State-level coastal regulation zone approvals for refinery expansions are stretching project delivery timelines and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Valves Market |
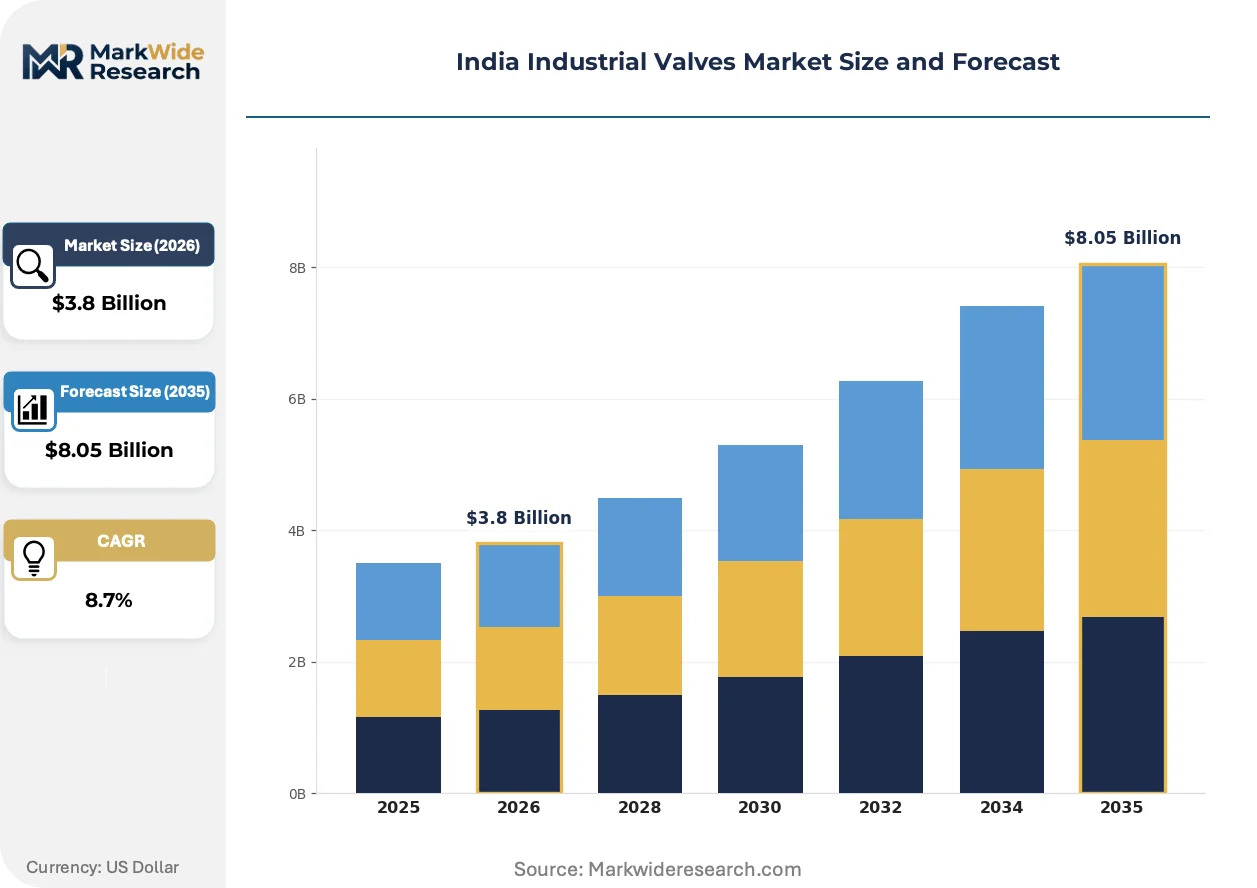
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valve Type: Gate Valve, Ball Valve, Globe Valve, Check Valve Application Area: Oil & Gas, Water Treatment, Power Generation, Chemical Processing Material: Stainless Steel, Cast Iron, Bronze, Plastic End User Sector: Manufacturing, Utilities, Construction, Mining |
| Companies Covered | Emerson Electric Co., Hawa Valves, L&T Valves Limited, VIP Valves, Amco Industrial Valves, Kirloskar Brothers Limited, AVK Valves India Pvt Ltd, Amtech, Flowserve Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Valves Market Trends and Innovations
Digital instrumentation and predictive maintenance architectures are displacing mechanical-only valve specifications across process industries. The competitive frontier is shifting from metallurgical performance to data integration and lifecycle service models.
Intelligent valve positioners with embedded pressure and temperature sensors are digitizing condition monitoring in refinery and petrochemical units. Reliance Industries and Indian Oil Corporation are mandating smart valve packages for greenfield installations. This sensor integration is compressing maintenance intervals and enabling shift from scheduled replacement to predictive intervention.
BIS certification mandates for industrial valves under the Compulsory Registration Scheme are tightening market access thresholds. Domestic manufacturers must now submit to third-party testing for pressure integrity and fire-safe performance. Petroleum and Natural Gas Regulatory Board pipeline safety codes are accelerating compliance investments among midstream operators.
Integrated service contracts bundling valve supply, installation supervision, and predictive maintenance are displacing transactional procurement in large capital projects. Engineering-procurement-construction firms are consolidating vendor lists to single-source responsibility. This bundling is most visible in Gujarat's petrochemical complexes where Reliance and Nayara Energy dominate capital deployment.
India Industrial Valves Market Segmentation
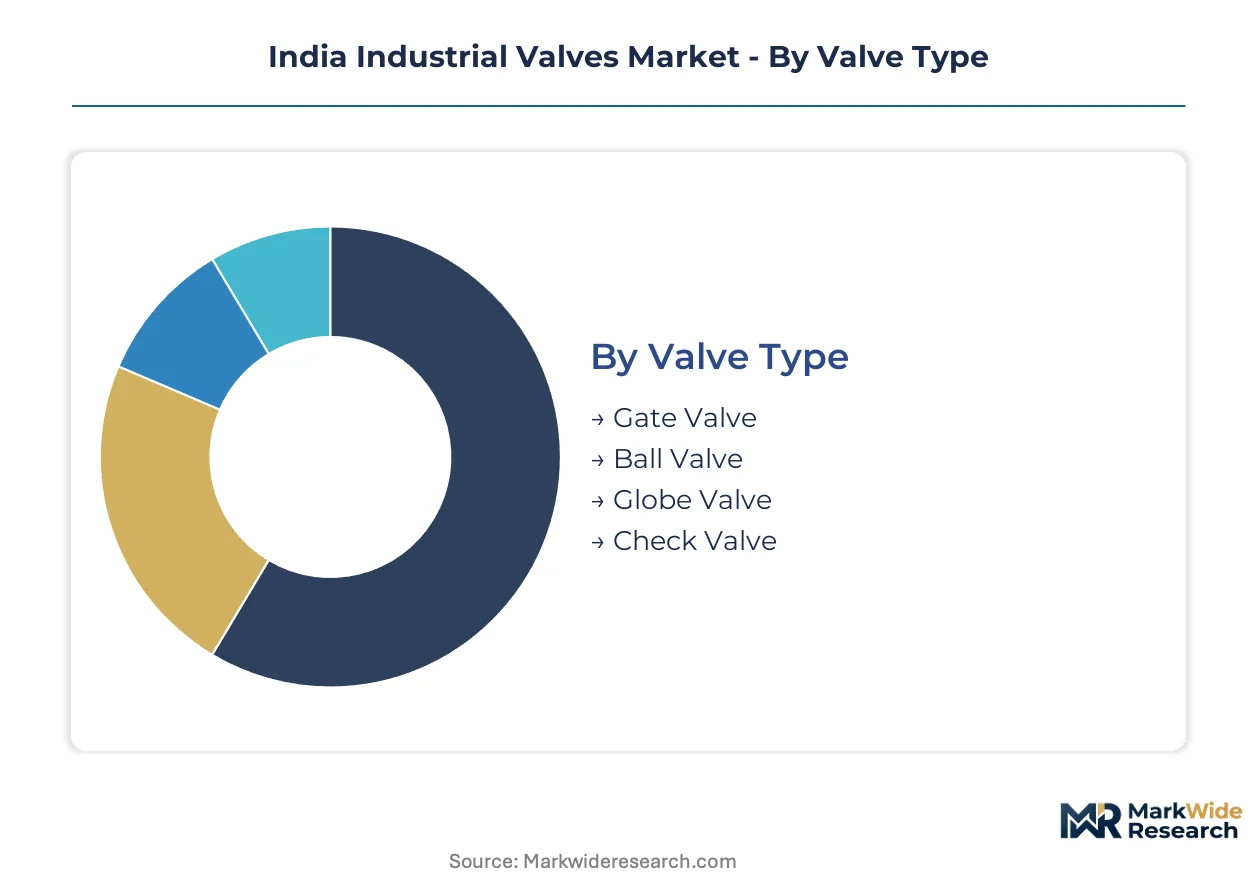
Industrial valve procurement in India fragments across pressure ratings, metallurgical specifications, and actuation architectures. Each segment tier carries distinct certification burdens and margin profiles that reshape vendor positioning.
Valve Type:
Application severity spans from low-cycle isolation to high-frequency modulation, dictating design complexity and replacement economics.
- Gate Valve:Linear-motion isolation devices engineered for full-bore flow with minimal pressure drop. Coal plant feedwater retrofits under CEA directives are concentrating orders in Gujarat and Tamil Nadu, though maintenance-intensive operation limits pricing power.
- Ball Valve:Quarter-turn shutoff mechanisms with floating or trunnion-mounted ball elements. Hydrogen blending pilot projects and LNG terminal expansions are accelerating specification upgrades for high-integrity sealing systems.
- Globe Valve:Throttling designs with S-shaped flow paths for precise flow modulation.
- Check Valve:Passive backflow prevention devices including swing, lift, and dual-plate configurations.
The dominant share belongs to gate valves in installed base terms, while ball valves are closing the gap fastest on project value.
Application Area:
End-use intensity correlates with process criticality and regulatory scrutiny, creating tiered margin pools.
- Oil & Gas:Upstream, midstream, and downstream installations spanning exploration through refining. Pipeline safety codes from the Petroleum and Natural Gas Regulatory Board mandate fire-safe and fugitive-emission-certified designs for coastal refinery corridors.
- Power Generation:Thermal, combined-cycle, and renewable energy balance-of-plant systems. CEA emission norms are forcing valve replacements across aging coal units in Chhattisgarh and Odisha.
- Water Treatment:Municipal distribution, desalination, and industrial effluent management.
- Chemical Processing:Aggressive fluid handling for acids, caustics, and specialty intermediates.
Oil and gas commands the premium pricing tier, with power generation trailing on retrofit-driven volume.
Material:
Metallurgical selection trades corrosion resistance against procurement cost and domestic mill availability.
- Stainless Steel:Austenitic and duplex grades for sour gas, chloride service, and hygienic applications. Specialty steel import dependency from European and Japanese mills inflates lead times for super-duplex forgings.
- Cast Iron:Gray and ductile iron bodies for low-pressure water and steam service. Municipal utilities in Maharashtra and Karnataka anchor volume procurement despite substitution pressure from thermoplastic alternatives.
- Bronze:Copper-tin alloys for seawater and marine environments.
- Plastic:PVC, CPVC, and PVDF constructions for chemical resistance at ambient pressures.
Cast iron retains volume leadership, though stainless steel is climbing fastest on specification intensity.
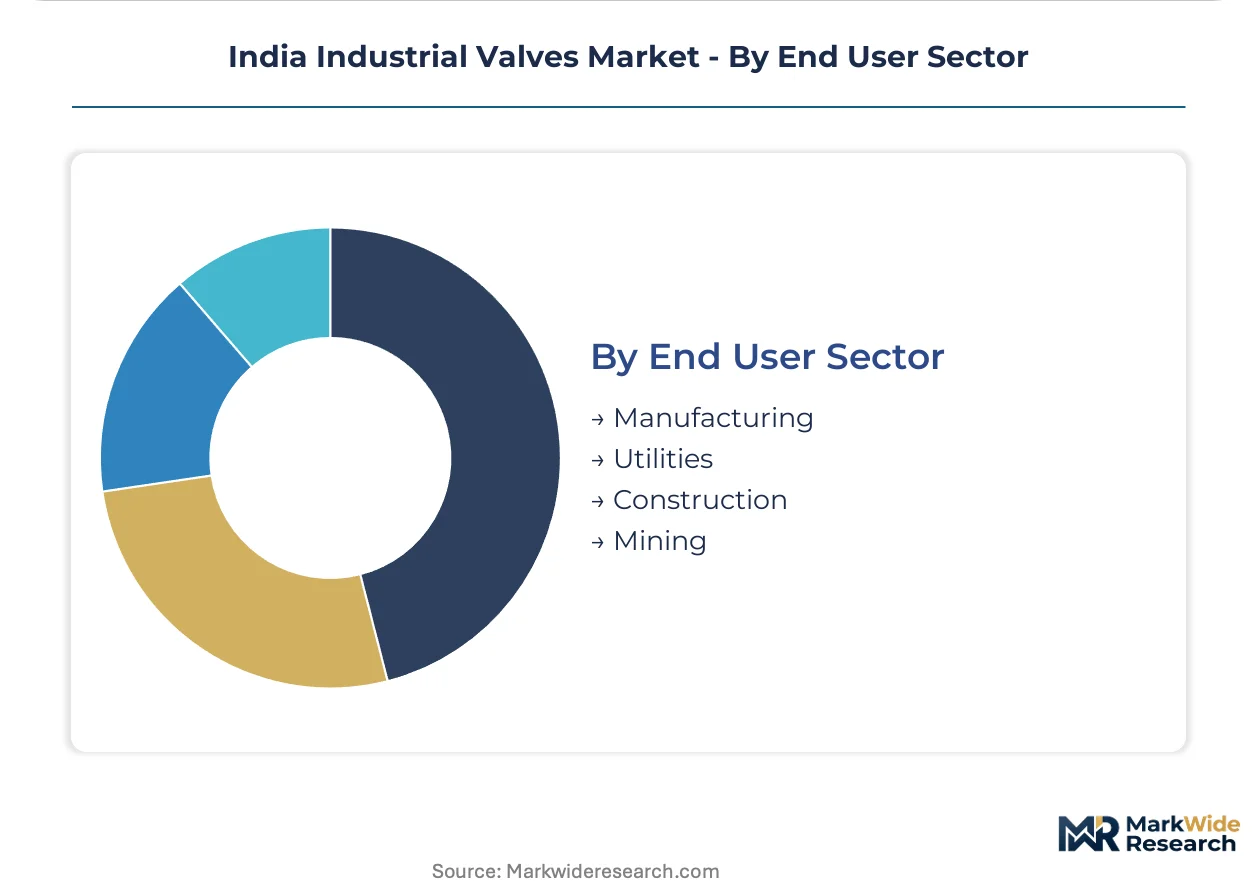
End User Sector:
Customer sophistication varies from specification-driven EPC contractors to price-sensitive municipal buyers.
- Manufacturing:Process industries including petrochemicals, fertilizers, and pharmaceuticals. Reliance Industries and Indian Oil Corporation are consolidating vendor lists to single-source responsibility for greenfield complexes.
- Utilities:Power generators, water boards, and gas distribution entities. State-level environmental clearances are stretching project timelines for coastal refinery expansions.
- Construction:Commercial and industrial building services for HVAC and plumbing.
- Mining:Slurry handling and tailings management for coal and mineral extraction.
Manufacturing dominates project value, with utilities expanding fastest on infrastructure replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valve fabrication clusters concentrate in western India, where petrochemical complexes and refinery corridors generate specification-intensive demand. State-level industrial policies and coastal regulation frameworks reshape procurement timelines across sub-regional markets.
Gujarat
Jamnagar and Vadodara anchor India's densest valve demand corridor, with Reliance Industries and Nayara Energy driving severe-service procurement for hydrogen and sour gas applications. BIS certification mandates under the Compulsory Registration Scheme compress supplier qualification windows for coastal refinery expansions. Dahej and Hazira industrial zones concentrate bulk orders for high-pressure ball valves and smart actuation packages.
Maharashtra
Mumbai-Pune industrial belt sustains recurring demand from pharmaceutical and chemical processing installations requiring hygienic stainless steel specifications. State pollution control board effluent norms accelerate valve replacement cycles in Thane and Raigad chemical clusters. Nagpur and Nashik municipal utilities anchor cast iron volume procurement for water distribution networks.
Tamil Nadu
CEA thermal power directives force feedwater valve retrofits across aging coal units in Neyveli and Ennore generation complexes. Tiruchirappalli and Coimbatore fabrication hubs supply ductile iron and carbon steel bodies for domestic project execution. Chennai port infrastructure drives marine-grade bronze valve specifications for seawater handling systems.
Karnataka
Bengaluru precision manufacturing ecosystem supports actuator instrumentation and digital positioner integration for smart valve architectures. Mangalore refinery and petrochemical complex generates demand for fire-safe certified designs under Petroleum and Natural Gas Regulatory Board pipeline codes. State renewable energy targets expand balance-of-plant valve procurement for solar thermal and wind hybrid installations.
Haryana
Faridabad and Gurgaon industrial corridors supply forged valve bodies and specialty steel castings to western India project clusters. PLI scheme incentives for precision manufacturing gradually enable captive sourcing of super-duplex and austenitic grades. National Capital Region water treatment infrastructure sustains mid-tier procurement for butterfly and check valve configurations.
India Industrial Valves Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in forging, casting, and instrumentation layers. The vendor base stratifies between full-service engineering-procurement-construction partners and discrete product fabricators competing on metallurgical certification. Three archetypes dominate: diversified industrial conglomerates with captive valve divisions, standalone valve specialists with BIS-accredited testing facilities, and international technology licensors with Indian assembly operations. Competitive dynamics center on vertical integration into specialty steel supply and strategic bundling of predictive maintenance software with hardware supply.
Among domestic fabricators, L&T Valves Limited and Kirloskar Brothers Limited occupy positions as full-service platform providers with integrated manufacturing footprints. Flowserve Corporation exemplifies the technology-licensor archetype, positioning Indian operations as regional export hubs for severe-service applications. These three represent contrasting strategic postures: conglomerate-backed scale, century-old brand equity diversification, and multinational technology leadership.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Hawa Valves |
| L&T Valves Limited |
| VIP Valves |
| Amco Industrial Valves |
| Kirloskar Brothers Limited |
| AVK Valves India Pvt Ltd |
| Amtech |
| Flowserve Corporation |
| Others |
Pricing and Supply Chain Analysis
The Mundra-Jamnagar freight corridor channels specialty steel forgings from European and Japanese mills to Gujarat's petrochemical clusters, with logistics cost dynamics amplifying supply concentration effects and compressing margins for non-integrated fabricators serving price-sensitive municipal buyers.
Pricing Analysis
BIS certification mandates under the Compulsory Registration Scheme dictate the pricing tier structure across India's valve market. Project-based contract pricing dominates severe-service procurement for hydrogen and sour gas applications, with differentiation driven by fire-safe certification grade and after-sales service bundling. Cost compression in cast iron municipal water segments intensifies as ductile iron and thermoplastic alternatives cap pricing power, while stainless steel specifications for chemical processing command the least price sensitivity due to corrosion failure risks.
Supply Chain Analysis
Extended payment terms from EPC contractors and supply-chain finance facilities strain working capital for domestic valve fabricators. Raw material sourcing draws from Germany, Japan, and China for high-grade stainless steel forgings, super-duplex castings, and precision actuator components. Single-source vulnerability concentrates in European mill supply for super-duplex grades essential to hydrogen service. Distribution runs through engineering-procurement-construction firms consolidating vendor lists to single-source responsibility in Gujarat's refinery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's industrial valve market demands substitution defense as thermoplastic valve alternatives and ductile iron technologies erode traditional metallurgical positions in municipal water segments.
For Market Incumbents: Harden BIS certification portfolios to disqualify speculative entrants facing 12-18 month approval windows. Deepen backward integration into specialty steel castings through PLI scheme incentives, capturing margin from European and Japanese mill dependencies. Consolidate vendor relationships with Reliance Industries and Indian Oil Corporation through integrated service contracts bundling predictive maintenance software.
For New Entrants and Emerging Players: Pursue hydrogen pipeline infrastructure white space as first-mover positioning in high-integrity ball valve specifications for blending and transmission networks. Target Karnataka's smart valve actuator ecosystem, where Bengaluru precision manufacturing clusters support digital positioner integration without legacy mechanical retrofit burdens. Lead with digital twin compatibility as the go-to-market angle for greenfield petrochemical installations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming valve divisions lacking BIS accreditation or smart actuation capabilities. Long-term viability hinges on captive specialty steel sourcing and software-enabled service revenue streams. Watch state-level environmental clearance velocity as the inflection indicator for project delivery timelines and working capital cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | PLI scheme incentives enable captive sourcing of super-duplex forgings from Haryana clusters. |
| Smart Actuation Platform Development | IoT-enabled positioners digitize maintenance workflows for Reliance Industries installations. |
| BIS Certification Acceleration | Third-party fire-safe testing compresses 12-18 month approval windows for qualified entrants. |
| Hydrogen Service Valve Qualification | High-integrity sealing systems capture nascent demand from Petroleum and Natural Gas Regulatory Board pilot projects. |
| Integrated Service Contract Expansion | Predictive maintenance bundling displaces transactional procurement in Nayara Energy greenfield complexes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS certification registries, Petroleum and Natural Gas Regulatory Board pipeline safety filings, and Central Electricity Authority thermal power directives. Primary interviews engaged plant engineers at Gujarat petrochemical complexes, procurement leads at Indian Oil Corporation, aftermarket service heads at L&T Valves Limited, and maintenance directors at Neyveli thermal generation units. Secondary validation incorporated customs data on specialty steel imports, SEC filings from Flowserve Corporation and Emerson Electric Co., and state pollution control board effluent compliance records. Bottom-up project pipeline assessments triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs span valve type segmentation by pressure rating and actuation architecture, material tier by corrosion resistance specification, and end-use intensity by regulatory scrutiny level across oil and gas, power generation, and chemical processing verticals. CAGRs derive from installed base replacement cycles, greenfield capacity announcements, and technology substitution elasticities. Industry-specific inputs include BIS certification queue lengths, PLI scheme disbursement trajectories, and coastal regulation zone approval velocity.
Sensitivities concentrate around European and Japanese mill supply disruptions, state-level environmental clearance delays, and hydrogen infrastructure policy acceleration. Forecasts reflect assumptions on specialty steel import dependency persistence and smart valve adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Air Vent Heads Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Pressure Control Equipment Market
Valves
Motorized Valves Market
Valves
Fluid Handling Systems Market
Valves
North America Irrigation Valves Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Global Gate Valve Market
Valves
North America Industrial Valves Market
Valves
APAC Valves Market
Valves
Global Control Valves Market
Valves
Pipeline and Process Services Market
Valves
Degassing Valves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Valve Remote Control System Market
Valves
Pipeline Strainers Market