
 Harmonic Dampers Market | 2026-2036
Harmonic Dampers Market Size, Share, and Industry Trends Forecast 2026-2036
Harmonic Dampers Market Analytics
OEM-grade torsional vibration specifications is collapsing the gap between commodity dampers and precision-engineered solutions. Schaeffler Group leverages its integrated bearing-damper platforms to anchor premium powertrain contracts. ZF Friedrichshafen AG dominates heavy-duty commercial vehicle applications through captive foundry and machining capacity. Bosch competes across multiple damping technologies with R&D intensity in active control systems.
Harmonic dampers are mechanical or electromechanical devices engineered to attenuate oscillatory energy through mass-spring-damping principles, typically employing elastomeric compounds, silicone fluids, or piezoelectric actuators tuned to specific resonant frequencies. Their primary purpose spans torsional vibration absorption in crankshaft assemblies, seismic energy dissipation in building structures, and chatter suppression in precision machining. Viscous dampers lead automotive powertrain applications due to thermal stability and maintenance-free operation, while tuned mass dampers command premium positioning in skyscraper and bridge installations where frequency-specific tuning determines structural safety margins. Active control systems represent the fastest-growing technology segment as semi-active magnetorheological architectures gain traction in aerospace and high-performance automotive platforms.
EPA tailpipe standards, ECE R51 noise regulations, and China's GB/T automotive vibration norms collectively tighten allowable NVH thresholds and expand mandatory damper fitment scope. Japan's METI enforces JIS standards on construction damping hardware that limit market access for uncertified suppliers. Stakeholders must monitor convergence between automotive electrification trends and torsional damper design requirements as hybrid powertrains introduce novel vibration signatures.
Market Dynamics
Engine downsizing mandates from EPA, ECE R51, and China's GB/T standards are intensifying torsional vibration challenges in compact powertrains, collapsing the performance gap between commodity and precision-engineered damper solutions.
Growth Catalysts
- EPA Tailpipe Standards:Stricter emissions rules in the United States force engine downsizing that amplifies crankshaft vibration loads and expands OEM damper fitment requirements across light-vehicle platforms.
- China Infrastructure Build-out:Domestic vehicle production and skyscraper construction in Shanghai and Shenzhen pull structural and automotive damper procurement into double-digit volume expansion.
- Magnetorheological Actuators:Semi-active control architectures gain traction in aerospace and high-performance automotive platforms where real-time damping adjustment commands premium positioning.
Market Restraints
- Specialized Elastomer Supply:High-damping silicone compounds and fluoroelastomers concentrate among Japanese and German chemical suppliers, exposing tier-two damper manufacturers to input cost volatility and allocation risk.
- JIS Certification Barriers:Japan's METI enforces construction damping hardware standards that limit market access for uncertified foreign suppliers and prolong qualification timelines.
- Active Mount Substitution:Electromagnetic active engine mounts in luxury electric vehicles threaten traditional crankshaft damper volumes as powertrain architectures electrify.
Strategic Opportunities
- India Commercial Vehicle Fleet:Underpenetrated heavy-duty OEM specification creates white space for viscous damper suppliers as domestic truck production scales under BS-VI emission compliance.
- EU Green Deal Retrofit Mandates:Building energy efficiency directives accelerate seismic upgrade cycles across aging European building stock, expanding tuned mass damper replacement demand.
- Sensor-Damper Convergence:Integration of IoT vibration monitoring with predictive maintenance contracts opens recurring revenue streams in wind turbine and industrial rotating equipment sectors.
Industry Challenges
- NVH Simulation Talent Scarcity:Finite element and multi-body dynamics expertise for torsional system modeling concentrates among aging specialist engineers in Stuttgart, Detroit, and Nagoya.
- Hybrid Powertrain Recalibration:Novel vibration signatures from PHEV and range-extender architectures force complete damper redesign cycles that compress development timelines and strain validation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harmonic Dampers Market |
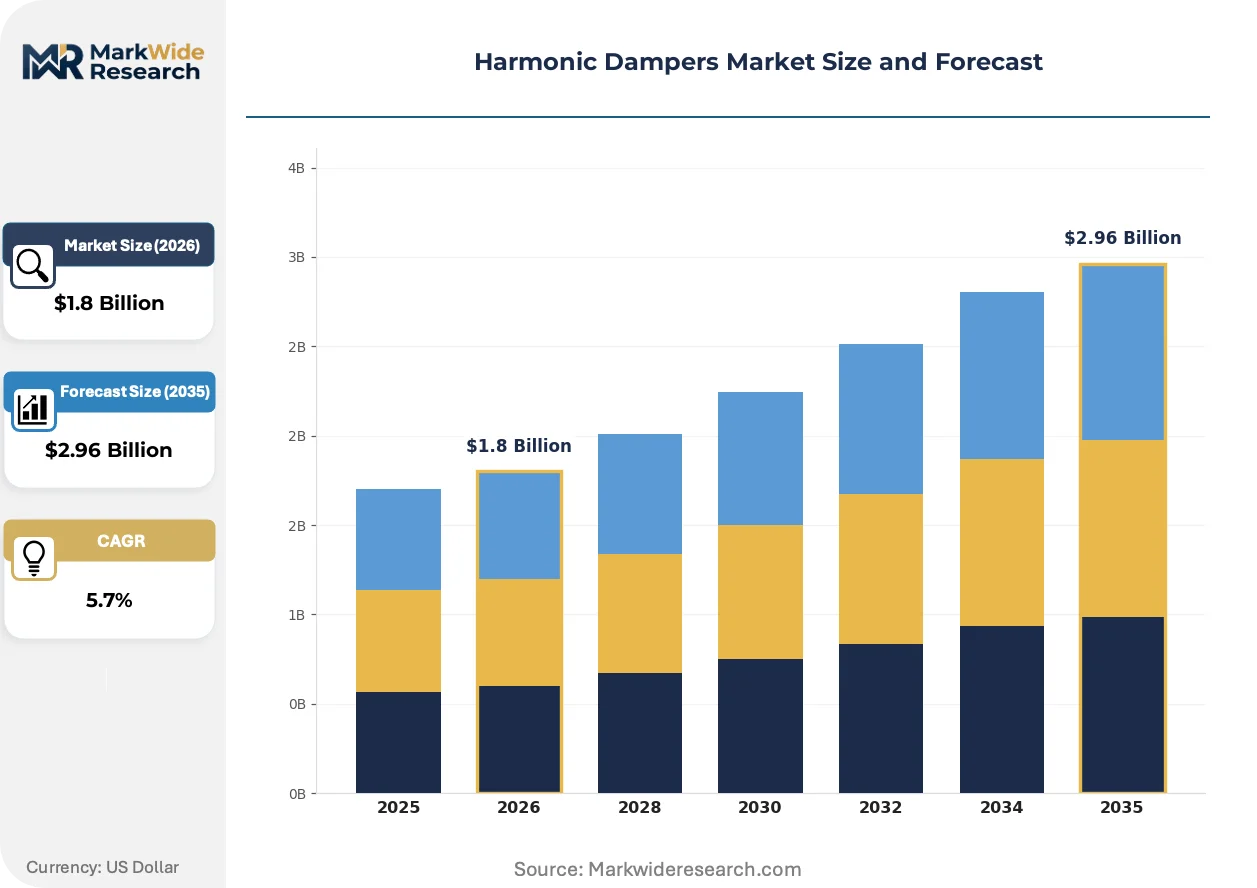
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
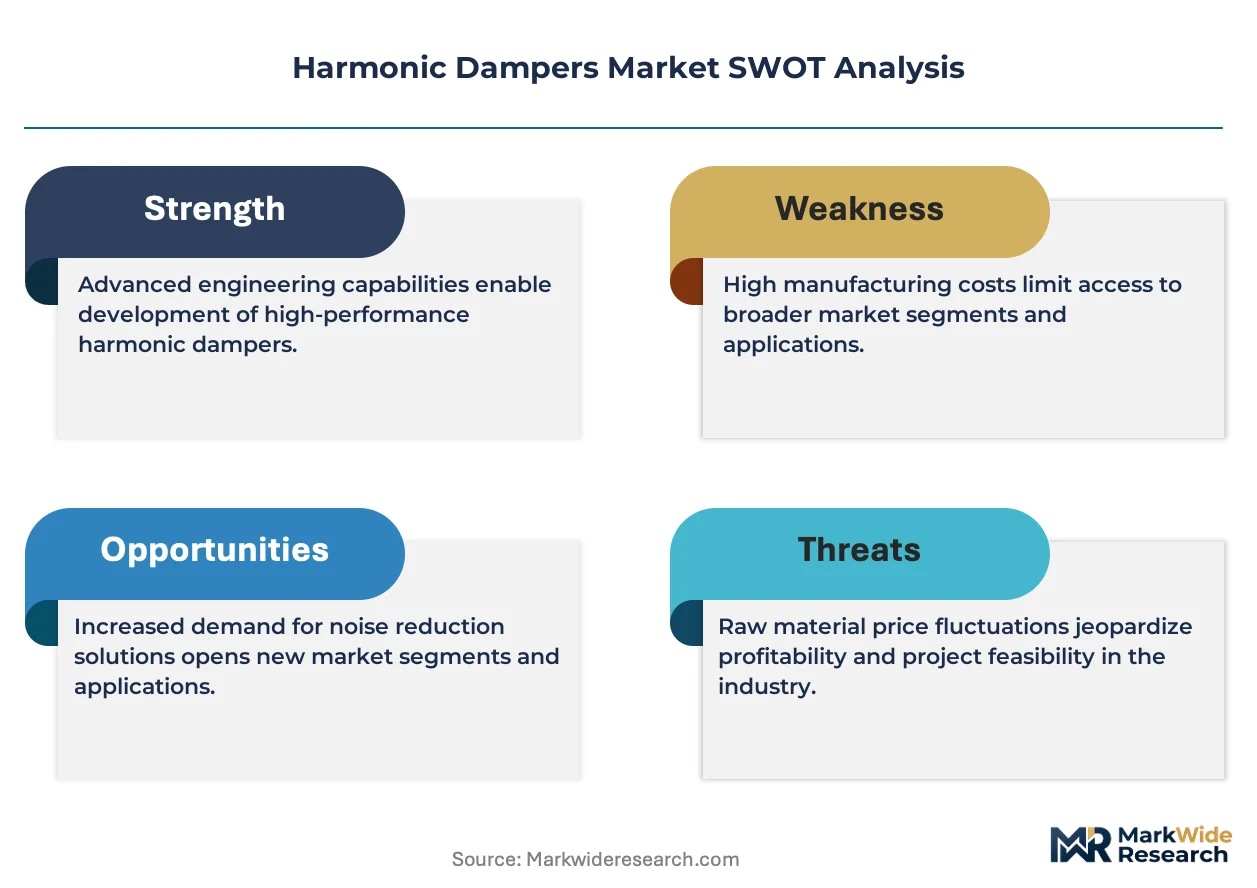
| Segmentation | Product Type: Viscous Dampers, Friction Dampers, Tuned Mass Dampers, Active Dampers Application: Building Structures, Bridges, Automotive, Machinery End User: Civil Engineering, Aerospace, Automotive OEMs, Industrial Manufacturers Technology: Passive Control, Semi-Active Control, Active Control, Hybrid Systems |
| Companies Covered | Bosch, Schaeffler Group, ZF Friedrichshafen AG, Valeo, BorgWarner, Continental AG, Knorr-Bremse Group, Dayco, Vibratech TVD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harmonic Dampers Market Evolving Landscape
Damper technology is splitting along performance tiers as electrification and smart infrastructure demands reshape material selection, control architectures, and procurement specifications across automotive and structural applications.
Magnetorheological fluid systems is bifurcating the high-performance segment from conventional passive damping. These electrorheological architectures enable millisecond-level stiffness modulation for active vibration cancellation. Aerospace landing gear and motorsport suspension programs in Germany and the United Kingdom adopt them fastest. The technology is compressing margins for fixed-parameter hydraulic dampers in premium tiers while opening adjacent markets in precision manufacturing equipment.
REACH substance restrictions and the EU F-Gas Regulation are phasing out legacy hydrofluorocarbon-based damping fluids and certain high-density elastomer formulations. Industrial consequence forces reformulation of viscous damper fill materials toward bio-based and low-GWP alternatives. Automotive OEMs in France and Italy face compressed homologation timelines as compound suppliers requalify thermal stability under new chemical compliance frameworks.
Specification consolidation among tier-one automotive suppliers is consolidating damper procurement decisions into platform engineering teams rather than commodity purchasing functions. Long-term damping performance warranties and predictive replacement scheduling displace spot-buying in heavy-duty commercial vehicle channels. This concentration is most visible in Germany's commercial vehicle cluster around Munich and Stuttgart, where captive foundry relationships anchor multi-year supply agreements.
Harmonic Dampers Market Segmentation
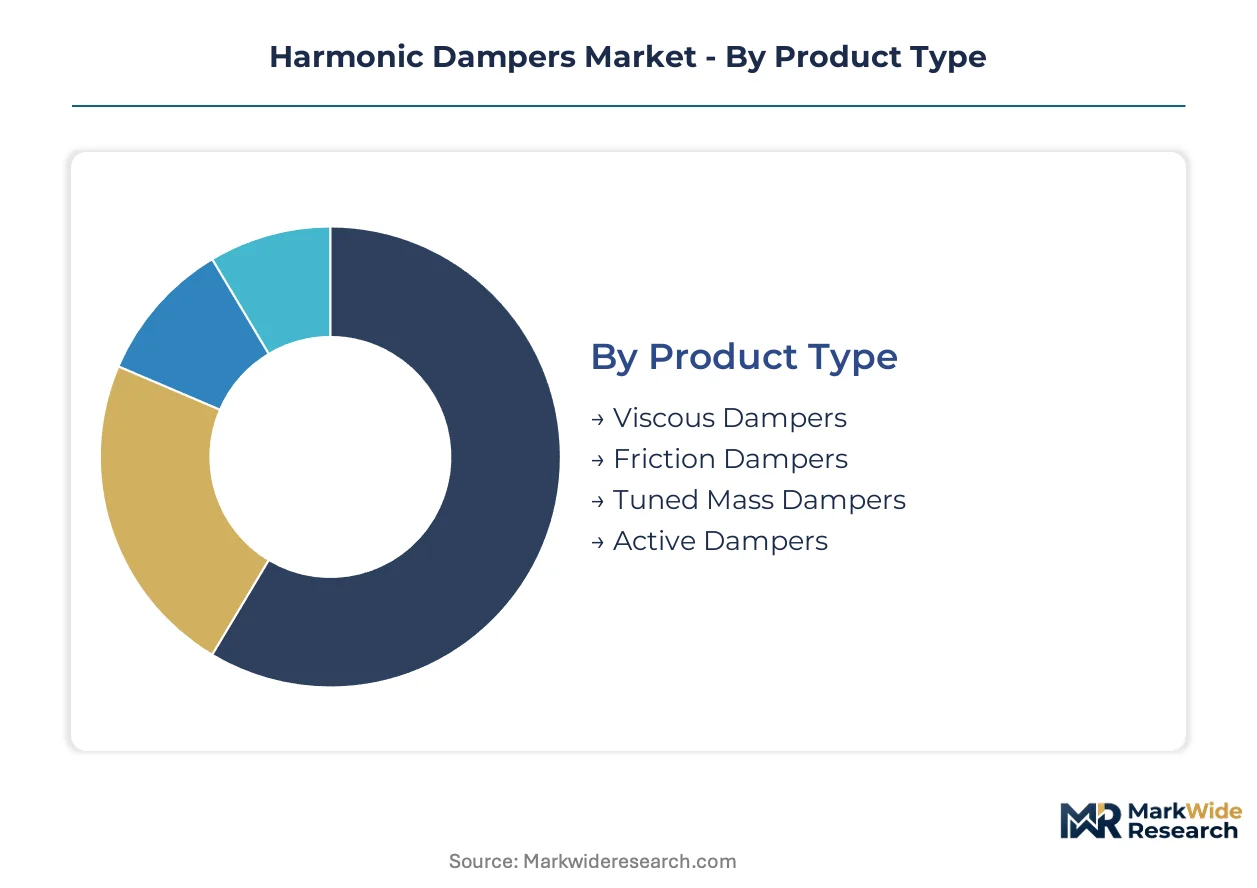
Harmonic damper procurement splits sharply between domestic infrastructure build-outs and export-driven automotive supply chains. Understanding where each segment concentrates geographically exposes margin structures and qualification barriers that shape supplier strategy.
Product Type:
Domestic demand concentrates on viscous and tuned mass variants for local construction and powertrain fitment, while active dampers travel almost exclusively through aerospace and motorsport export channels.
- Viscous Dampers:Silicone-fluid-filled housings tuned to specific frequency ranges through inertia ring mass and fluid shear properties. China's domestic vehicle production and Germany's commercial vehicle cluster absorb the heaviest procurement volumes as crankshaft torsional vibration specifications tighten under EPA and ECE R51 downsizing mandates.
- Active Dampers:Electromechanical architectures employing magnetorheological fluids or piezoelectric actuators for real-time stiffness modulation. Aerospace landing gear programs in the United Kingdom and high-performance automotive platforms in Germany command nearly all output, with qualification cycles stretching across multiple regulatory jurisdictions.
- Friction Dampers:Metallic or composite friction interfaces dissipate energy through sliding contact, common in railway and heavy machinery applications.
- Tuned Mass Dampers:Mass-spring systems tuned to structural resonant frequencies, dominating skyscraper and bridge installations in Shanghai and Shenzhen.
Viscous dampers hold the largest share; momentum sits with active dampers as semi-active architectures gain aerospace traction.
Application:
Cost tier separation runs deepest here, with building and bridge installations commanding premium engineering fees against automotive's volume-scaled pricing.
- Building Structures:Tuned mass and viscous damper arrays installed at mechanical floors or roof levels to attenuate wind-induced sway. Japan's METI enforces JIS certification that limits foreign supplier access, while EU Green Deal retrofit mandates across aging European stock expand replacement demand.
- Automotive:Crankshaft-mounted viscous dampers and dual-mass flywheel assemblies for powertrain NVH control. China's GB/T vibration norms and EPA tailpipe standards force expanded fitment across light-vehicle and heavy-duty platforms as engine downsizing intensifies torsional loads.
- Bridges:Long-span cable and deck damping systems, concentrated in China's infrastructure build-out and Japan's seismic retrofit programs.
- Machinery:Rotating equipment and precision manufacturing chatter suppression, with sensor-damper convergence opening predictive maintenance contracts.
Building structures command the highest unit margins; automotive delivers the steepest volume expansion trajectory.
End User:
Customer type determines procurement modality, with civil engineering and aerospace favoring project-based contracting against automotive OEMs' platform-integrated supply agreements.
- Automotive OEMs:Integrated bearing-damper platforms and crankshaft-mounted assemblies procured through multi-year supply agreements anchored by captive foundry relationships. Germany's commercial vehicle cluster around Munich and Stuttgart concentrates specification authority into platform engineering teams rather than commodity purchasing functions.
- Civil Engineering:Seismic and wind damping systems for skyscrapers, bridges, and public infrastructure. China's state-backed developers and Japan's construction consortia dominate procurement, with JIS and GB standards creating divergent qualification pathways.
- Aerospace:Landing gear and airframe damping systems, concentrated in United Kingdom and German defense and commercial aviation programs.
- Industrial Manufacturers:Wind turbine, precision machining, and rotating equipment applications where IoT vibration monitoring integration opens recurring revenue streams.
Civil engineering absorbs the highest absolute spending; automotive OEMs are consolidating procurement fastest.
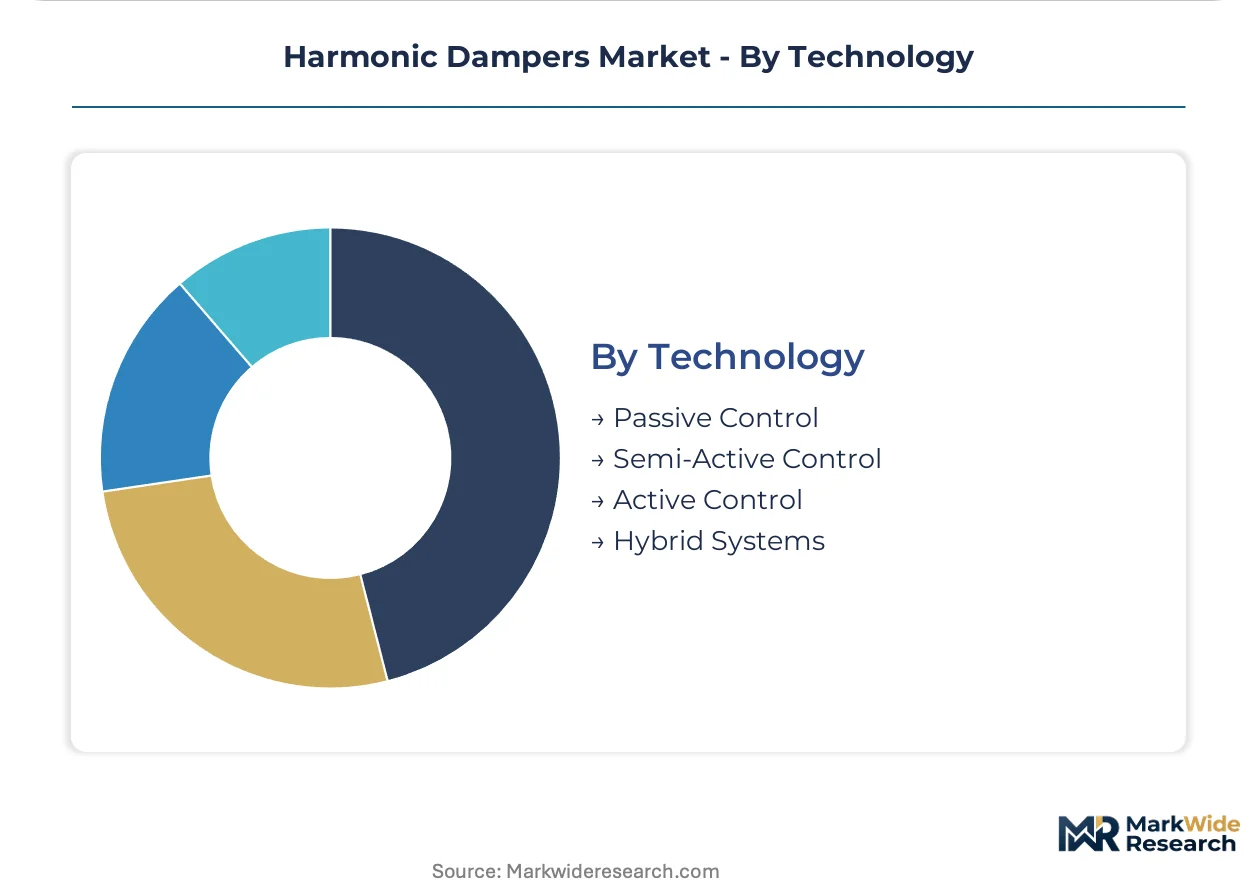
Technology:
Supply concentration tracks technology maturity, with passive control commoditizing while semi-active and hybrid architectures concentrate among specialized fluid and actuator suppliers.
- Passive Control:Fixed-parameter elastomeric, viscous, or friction-based systems with no external energy input. REACH substance restrictions and EU F-Gas Regulation force reformulation of silicone compounds and hydrofluorocarbon fluids toward bio-based alternatives, compressing margins for established suppliers.
- Semi-Active Control:Magnetorheological and electrorheological architectures enabling millisecond-level stiffness adjustment. Aerospace landing gear in Germany and motorsport applications in the United Kingdom adopt fastest, with real-time damping adjustment commanding premium positioning over fixed-parameter hydraulic alternatives.
- Active Control:Fully powered electromechanical systems with sensor feedback loops, emerging in precision manufacturing equipment.
- Hybrid Systems:Combined passive-active architectures for critical infrastructure, gaining traction in Japan's seismic retrofit market.
Passive control retains volume dominance; semi-active architectures are gaining share fastest in high-performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for harmonic dampers tilt toward net imports across emerging automotive hubs, while established manufacturing clusters in Germany and Japan maintain surplus positions in precision-engineered components. China's infrastructure build-out and domestic vehicle production now absorb the largest absolute volumes globally.
China
Domestic vehicle production and skyscraper construction in Shanghai and Shenzhen pull structural and automotive damper procurement into double-digit volume expansion. GB/T automotive vibration norms tighten allowable NVH thresholds and expand mandatory damper fitment scope across light-vehicle platforms. The Yangtze River Delta hosts concentrated foundry and machining capacity serving both local OEMs and export markets.
Germany
Commercial vehicle production around Munich and Stuttgart anchors multi-year supply agreements for viscous crankshaft dampers as ECE R51 noise regulations force engine downsizing. The EU F-Gas Regulation and REACH substance restrictions compel reformulation of silicone damping fluids toward bio-based alternatives. Bavaria's automotive cluster concentrates specification authority into platform engineering teams rather than commodity purchasing functions.
United States
EPA tailpipe standards force engine downsizing that amplifies crankshaft vibration loads and expands OEM damper fitment requirements across light-vehicle platforms. The Detroit metropolitan area retains finite element and multi-body dynamics expertise for torsional system modeling. Heavy-duty commercial vehicle channels in the Midwest show early adoption of long-term damping performance warranties and predictive replacement scheduling.
Japan
METI enforces JIS standards on construction damping hardware that limit market access for uncertified foreign suppliers and prolong qualification timelines. Seismic retrofit programs for aging building stock and bridge infrastructure sustain demand for tuned mass damper arrays. The Nagoya-Toyota industrial corridor concentrates aging specialist engineers with NVH simulation expertise for hybrid powertrain recalibration.
India
Underpenetrated heavy-duty OEM specification creates white space for viscous damper suppliers as domestic truck production scales under BS-VI emission compliance. The country's national automotive regulator mandates stricter tailpipe and noise standards that intensify torsional vibration challenges. Maharashtra and Tamil Nadu host expanding commercial vehicle assembly operations pulling in component procurement from established supply bases.
Harmonic Dampers Market Competitive Landscape
Listed leaders compete with private specialists across technology tiers and geographic footprints, creating a bifurcated structure where scale-driven automotive suppliers face off against focused damping technology developers. The vendor base concentrates around three strategic archetypes: integrated bearing-damper platform providers, captive foundry operators with machining depth, and fluid technology specialists with magnetorheological expertise. Dominant competitive moves include specification consolidation into platform engineering teams and backward integration into high-damping elastomer compound supply.
Within the integrated platform tier, Schaeffler Group and ZF Friedrichshafen AG exemplify contrasting geographic and structural positioning—Schaeffler's German AG structure represents bearing-damper convergence strategies, while ZF's Friedrichshafen base anchors heavy-duty commercial vehicle specification authority. Bosch occupies a diversified technology position across multiple damping architectures. These three entities collectively illustrate how automotive supply chain consolidation favors entities with captive manufacturing depth and multi-year OEM anchoring relationships.
| Leading Market Players |
|---|
| Bosch |
| Schaeffler Group |
| ZF Friedrichshafen AG |
| Valeo |
| BorgWarner |
| Continental AG |
| Knorr-Bremse Group |
| Dayco |
| Vibratech TVD |
| Others |
Value Network & Pricing Analysis
Ninety-day silicone compound lead times concentrate pricing power among Japanese and German chemical suppliers, compressing margins for tier-two damper manufacturers while amplifying cost pass-through capacity for integrated bearing-damper platform providers. This inventory tension feeds directly into how procurement teams structure long-term supply agreements versus spot-buying exposure.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure, with three-tier pricing separating JIS-certified precision solutions from standard automotive fitments and economy-grade friction dampers. Price differentiation rests on certification level—GB/T compliance for China-bound automotive volume versus METI-endorsed JIS tiers for seismic construction—and captive foundry integration. Cost compression in mid-tier viscous dampers is intensifying because REACH substance restrictions force compound reformulation. Aftermarket distributors show highest price sensitivity; aerospace landing gear programs demonstrate least.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for high-damping elastomer compounds, with Shanghai port congestion periodically extending raw material transit windows. Manufacturing gravity centers on Germany, China, and Japan, drawing from specialized silicone fluid suppliers, fluoroelastomer compounders, and precision inertia ring forgers. Single-source vulnerability concentrates in Japanese chemical suppliers for magnetorheological fluids. Distribution runs through tier-one automotive platform engineering teams and project-based civil engineering consortia rather than commodity purchasing functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where specification authority is migrating from commodity buyers to integrated engineering teams, with interoperability between sensor networks and predictive maintenance contracts reshaping how damping solutions capture recurring revenue.
For Market Incumbents: Compound captive supply advantages in high-damping elastomer formulations to deepen backward integration into silicone compound supply, insulating margin structures from Japanese supplier allocation risk. Extend multi-year supply agreements with China's Yangtze River Delta OEMs before GB/T vibration norm enforcement tightens qualification windows. Electromagnetic active engine mounts in luxury electric vehicles threaten traditional crankshaft damper volumes; anchor replacement demand through sensor-damper convergence in wind turbine and industrial rotating equipment sectors. For New Entrants and Emerging Players: Differentiate on magnetorheological fluid architectures for aerospace landing gear programs in the United Kingdom and Germany, where qualification cycles stretch across multiple regulatory jurisdictions but create durable supplier lock-in. Target India's underpenetrated heavy-duty commercial vehicle fleet as BS-VI emission compliance scales domestic truck production. Pursue joint development agreements with tier-one automotive platform engineering teams rather than commodity purchasing channels to bypass entrenched foundry relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification authority concentration favors entities with captive manufacturing depth and multi-year OEM anchoring relationships over pure technology developers. Acquisition target archetype: mid-cap fluid technology specialists with magnetorheological expertise and existing aerospace qualification. Watch for hybrid powertrain recalibration cycles forcing complete damper redesigns as the signal indicating which suppliers possess validation capacity to capture platform shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Supply | Captive silicone compound production insulates margins from Japanese supplier allocation volatility under REACH reformulation timelines. |
| Sensor-Damper Platform Convergence | IoT vibration monitoring integration opens recurring revenue streams in wind turbine predictive maintenance contracts. |
| JIS Certification Investment | METI-enforced construction damping standards limit foreign supplier access; certification creates durable Japan market entry. |
| Magnetorheological R&D Expansion | Millisecond-level stiffness modulation commands premium positioning in aerospace landing gear and motorsport suspension programs. |
| India Commercial Vehicle Footprint | BS-VI emission compliance scales domestic truck production, creating white space for viscous damper specification. |
Research Methodology
The analysis maps viscous damper, tuned mass damper, active control system, and friction damper sub-sectors, each validated through primary interviews with OEM platform engineers, tier-one procurement directors, civil engineering project managers, and aerospace landing gear specialists, combined with secondary validation from vehicle production databases, IHS Markit registration data, customs/trade flow records, and national automotive regulator filings. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon, with segmentation modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating engine downsizing intensity, infrastructure build-out trajectories, and regulatory enforcement timelines. Industry-specific inputs include torsional vibration specification tightening rates and seismic retrofit program acceleration under EU Green Deal mandates.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA tailpipe standard enforcement and China infrastructure investment continuity; material deviation would warrant model refresh. Specific risk factors include active mount substitution in electric vehicle powertrains and REACH substance restriction expansion beyond hydrofluorocarbon fluids. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Mobile Hydraulic Valves Market
Valves
North America Butterfly Valve Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Pipeline Strainers Market
Valves
US Water & Wastewater Valves Market
Valves
Electro Pneumatic Positioner Market
Valves
Pneumatic Needle Valves Market
Valves
HVAC Valves Market
Valves
Steam Trap Valve Market
Valves
Global Pressure Relief Valves Market
Valves
Christmas Tree Valves Market
Valves
Isolator Valves Market
Valves
Diaphragm Valve Market
Valves
Europe Butterfly Valve Market
Valves
Top Drive Systems Market