
 Energy Storage Software Market | 2026-2036
Energy Storage Software Market Size, Share, and Industry Trends Forecast 2026-2036
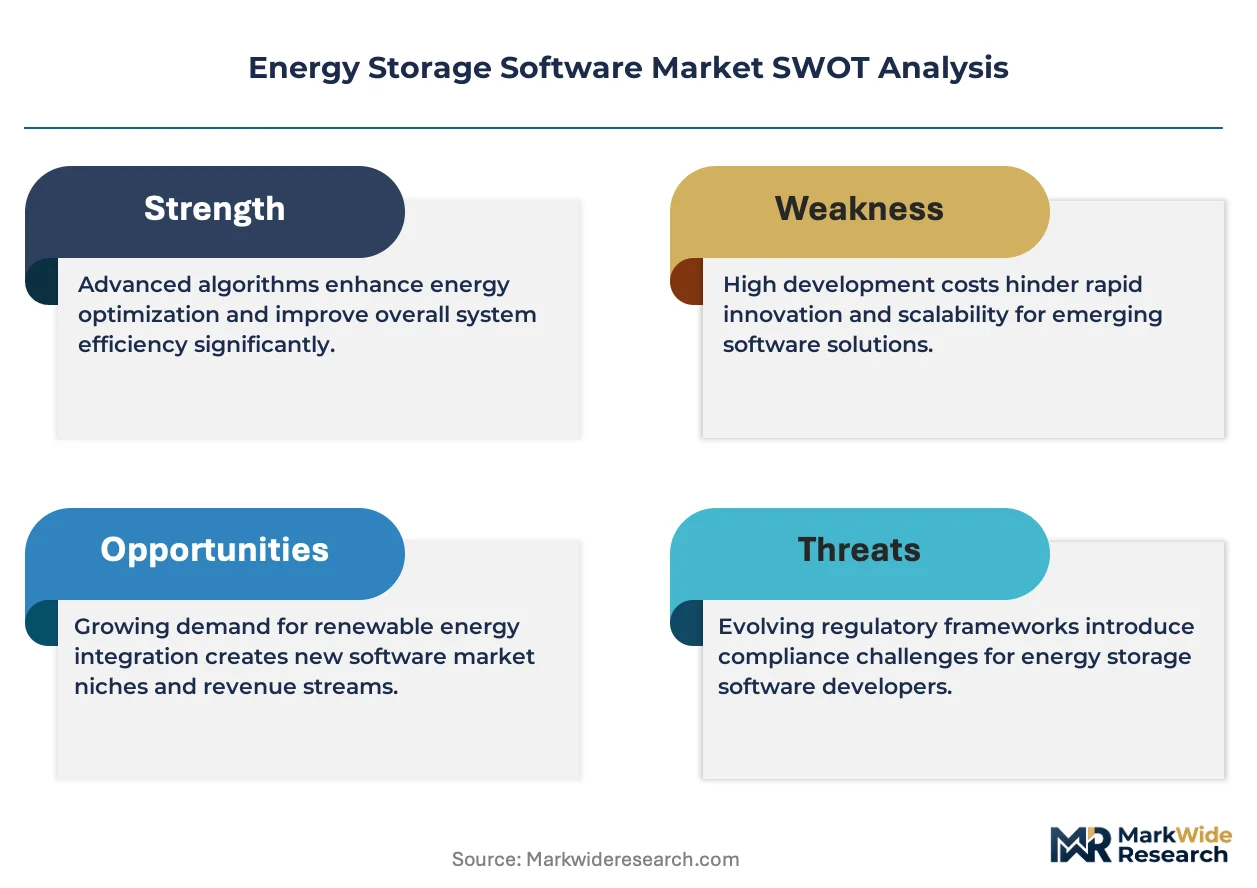
Energy Storage Software Market Analysis
The energy storage software landscape is restructuring around a sharp split between premium AI-driven optimization suites and commodity monitoring dashboards. Siemens Energy leverages deep vertical integration into utility control rooms across Europe. Fluence Energy competes through proprietary algorithms for battery dispatch optimization. Tesla anchors its position with end-to-end software-hardware coupling in large-scale storage installations.
Energy storage software encompasses the digital control, monitoring, and optimization layers that manage electrochemical, mechanical, or thermal storage assets, typically interfacing through SCADA protocols, API-based cloud architectures, or edge computing nodes with sub-second response latencies for grid-balancing functions. Battery Management Systems dominate current revenue pools due to cell-level safety mandates and warranty compliance requirements. Grid Management Software represents the fastest-expanding segment as transmission operators in markets like California and Texas replace legacy SCADA with predictive control platforms. Cloud-based deployment captures margin concentration from multi-site fleet operators seeking centralized analytics across dispersed storage assets.
The US Federal Energy Regulatory Commission (FERC) shapes market access through Order 841, which mandates storage participation in wholesale markets, while the EU F-Gas Regulation and CE marking frameworks constrain cooling-system software integrations in European battery installations. California's CPUC enforces resource adequacy requirements that force software-enabled dispatch forecasting. Stakeholders must monitor whether grid codes in Australia, South Korea, and the United Kingdom converge toward unified interoperability standards or fragment into incompatible regional protocols.
Market Dynamics
Grid operators are replacing centralized SCADA architectures with distributed edge-computing nodes that enable sub-second frequency response, compressing procurement cycles for software vendors and forcing hardware-agnostic interoperability standards.
Growth Catalysts
- FERC Order 841:US transmission operators must allow storage assets into wholesale markets, mandating software-enabled dispatch participation and creating immediate procurement pull for predictive control platforms.
- Battery-integrated solar farms:Hybrid renewable installations in California and Texas require co-optimized software stacks for DC-coupled inverter control, expanding addressable demand for multi-asset orchestration suites.
- Germany's FCR market redesign:Grid operators face mandatory frequency regulation upgrades that specify 250-millisecond response latencies, forcing replacement of legacy control systems with AI-driven optimization layers.
Market Restraints
- Lithium price volatility:Cell cost swings compress project margins for battery-integrated software vendors, forcing warranty reserve increases that drain R&D budgets.
- Cloud concentration risk:AWS and Azure host over 80% of fleet analytics platforms, creating single-point-of-failure exposure for multi-site operators.
- Cybersecurity certification delays:IEC 62443 compliance timelines stretch 14-18 months, freezing deployments for critical infrastructure projects.
Strategic Opportunities
- India's ancillary services market opening:CEA regulations now permit storage participation in frequency regulation, creating first-mover advantage for vendors with tropical climate optimization algorithms.
- Virtual power plant aggregation:Behind-the-meter residential batteries in Australia and Germany enable software-based fleet orchestration for grid services, bypassing utility procurement cycles.
- EU Battery Regulation digital passport mandates:Cell-level traceability requirements create recurring revenue streams for software vendors with embedded compliance modules.
Industry Challenges
- Power systems engineering talent scarcity:Control theory expertise required for grid-forming inverter software commands 40% salary premiums, constraining vendor scaling.
- Legacy DCS integration friction:Brownfield utility control rooms run 1990s-era protocols that resist API-based cloud architectures, extending deployment timelines.
- Multi-jurisdiction certification stacking:Vendors targeting California, Texas, and PJM markets must maintain parallel UL, IEEE, and NERC compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage Software Market |
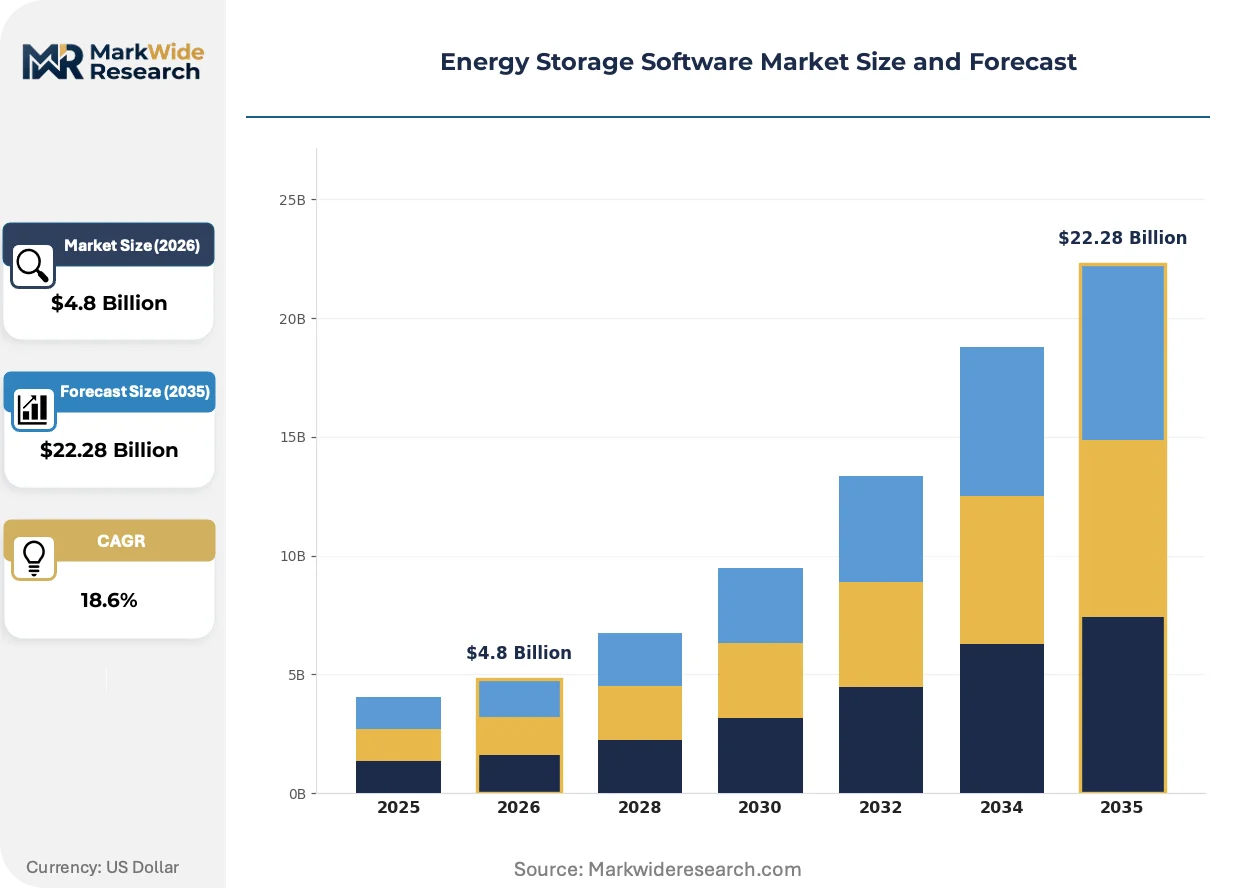
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Management Systems, Energy Management Systems, Grid Management Software, Analytics Platforms Deployment: On-premises, Cloud-based, Hybrid, Edge Computing End User: Utilities, Renewable Energy Companies, Industrial Operators, Commercial Users Application: Peak Shaving, Load Shifting, Frequency Regulation, Ancillary Services |
| Companies Covered | Siemens Energy, ABB Ltd., General Electric, Fluence Energy, Tesla, Inc., Hitachi Ltd., Eaton Corporation, SolarEdge Technologies, Inc., NextEra Energy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage Software Market Emerging Trajectories
Edge-native control architectures are displacing cloud-dependent SCADA systems, enabling millisecond-latency dispatch decisions that unlock new revenue streams in frequency regulation markets.
Distributed energy resource management systems are decentralizing control authority from centralized utility control rooms to substation-level edge nodes. Texas and California grid operators are deploying these architectures for wildfire-resilient islanding capabilities. The shift is compressing vendor margins on high-availability hardware while expanding software subscription attach rates.
EU F-Gas Regulation phase-down schedules are forcing cooling-system software redesigns for European battery installations. Thermal management algorithms must now optimize for lower-GWP refrigerants with degraded heat transfer coefficients. German and Dutch system integrators are absorbing 6-9 month redesign cycles to maintain CE marking compliance.
Asset owners are unbundling software procurement from hardware supply agreements, reversing a decade of bundled EPC contracting. US independent power developers now issue separate RFPs for battery hardware and optimization software, enabling best-of-breed selection. The pattern is most pronounced in ERCOT and CAISO markets where merchant revenue exposure rewards algorithmic sophistication over vendor integration.
Energy Storage Software Market Segmentation
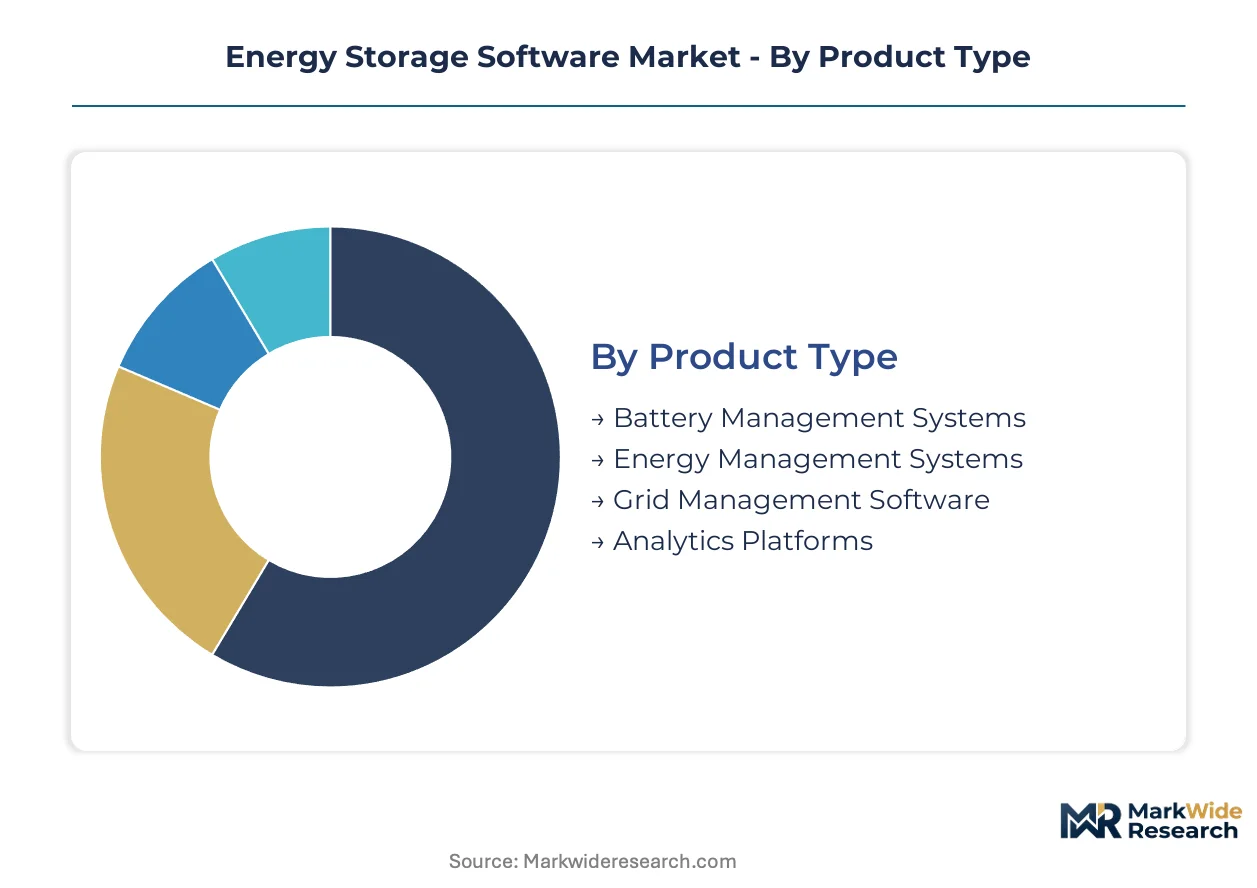
Energy storage software procurement splits sharply between safety-critical embedded systems and revenue-optimization platforms. Buyers prioritize integration depth with existing SCADA infrastructure over standalone feature richness.
Product Type:
Utility procurement committees weight warranty compliance and cell-level safety mandates above algorithmic sophistication when evaluating software stacks.
- Battery Management Systems:Embedded firmware monitors cell voltage, temperature, and state-of-charge with millisecond polling intervals. German grid operators mandate BMS integration for CE-marked battery installations under EU Battery Regulation traceability requirements.
- Energy Management Systems:Asset-level optimization software coordinates charging cycles with wholesale price signals and renewable generation forecasts. Industrial operators in Texas and California deploy EMS layers to maximize merchant revenue exposure in volatile nodal pricing environments.
- Grid Management Software:Transmission-scale control platforms enable predictive dispatch across multi-gigawatt storage fleets.
- Analytics Platforms:Cloud-based dashboards aggregate degradation modeling and predictive maintenance alerts for dispersed asset portfolios.
Battery Management Systems lead on scale; Grid Management Software leads on momentum.
Deployment:
Latency requirements for frequency regulation markets are compressing cloud dependency and accelerating edge-native procurement.
- On-premises:Air-gapped installations in critical infrastructure facilities satisfy NERC CIP cybersecurity mandates. US nuclear-coupled storage projects require on-premises control to maintain operational technology isolation from enterprise IT networks.
- Cloud-based:Multi-tenant SaaS architectures enable centralized fleet analytics across geographically dispersed assets. European independent power producers favor cloud deployment for cross-border portfolio optimization under EU electricity market coupling mechanisms.
- Hybrid:Split architectures process time-critical control loops locally while pushing historical analytics to cloud tiers.
- Edge Computing:Substation-mounted nodes execute dispatch decisions with sub-100-millisecond latency for primary frequency response.
Cloud-based deployment dominates current procurement volume; Edge Computing expands most quickly as grid codes tighten response windows.
End User:
Revenue model sophistication varies dramatically across buyer categories, with merchant-exposed developers demanding predictive algorithms over monitoring dashboards.
- Utilities:Vertically integrated operators procure enterprise-grade platforms for resource adequacy compliance and integrated resource planning. California's three major investor-owned utilities mandate software-enabled dispatch forecasting to satisfy CPUC-mandated reliability requirements.
- Renewable Energy Companies:Solar and wind developers require co-optimized software for DC-coupled battery control in hybrid installations. Texas renewable developers prioritize algorithmic sophistication to capture ERCOT's scarcity pricing events.
- Industrial Operators:C&I facilities deploy behind-the-meter storage with demand charge optimization software.
- Commercial Users:Retail and office building owners procure simplified monitoring platforms with limited dispatch autonomy.
Utilities anchor procurement volume; Renewable Energy Companies drive specification innovation.
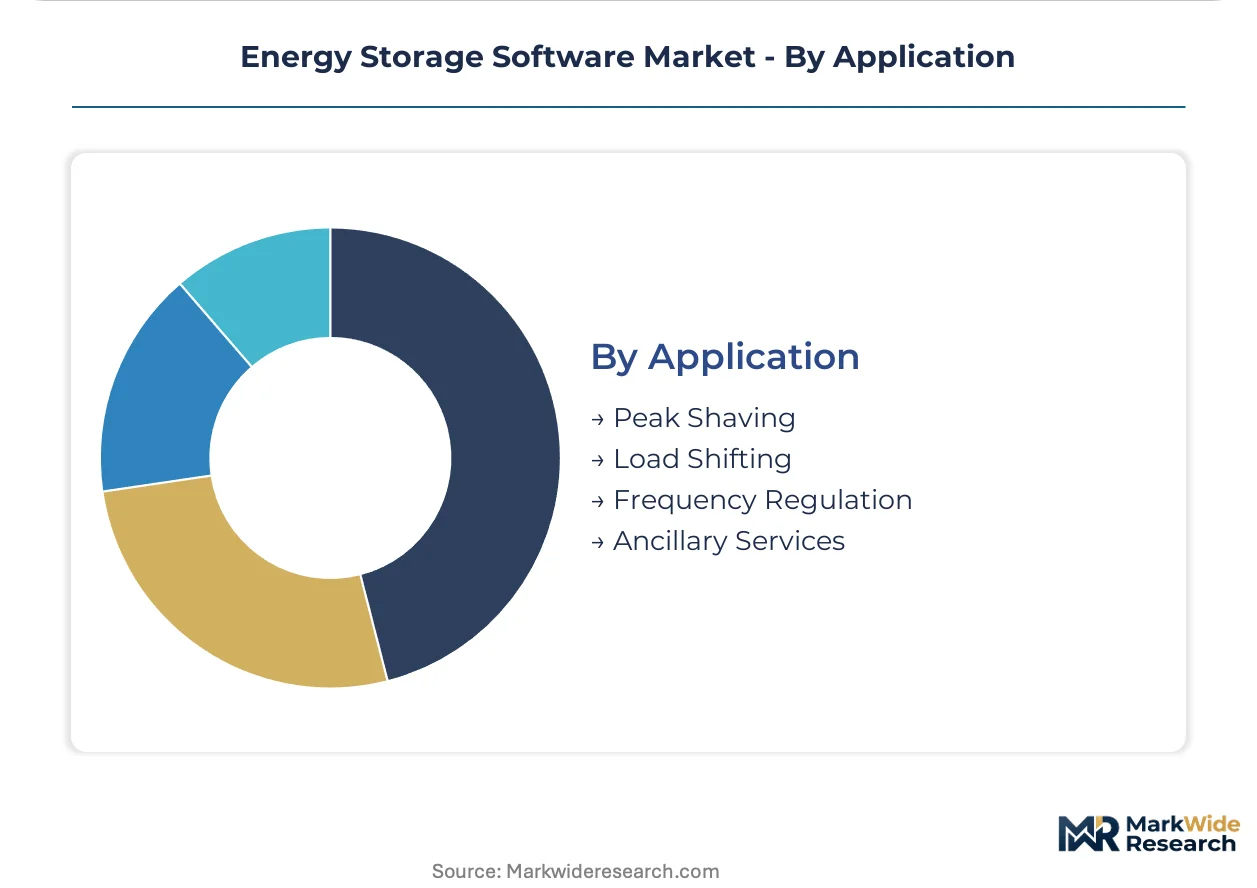
Application:
Revenue stackability determines software architecture complexity, with multi-service applications requiring modular control frameworks.
- Frequency Regulation:Fast-responding control loops maintain grid frequency within operational bounds. Germany's FCR market redesign mandates 250-millisecond response latencies, forcing replacement of legacy SCADA with AI-driven optimization layers.
- Peak Shaving:Demand charge reduction algorithms optimize battery dispatch against utility tariff structures. California commercial users deploy peak shaving software to minimize exposure to CPUC-approved demand charges exceeding $30 per kilowatt-month.
- Load Shifting:Time-of-use arbitrage software transfers energy consumption across pricing periods.
- Ancillary Services:Spinning reserve and voltage support applications require grid-code-certified control protocols.
Peak Shaving dominates installed base; Frequency Regulation commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany mandates 250-millisecond frequency response latencies that outpace US requirements, while India opens ancillary services markets with tropical climate optimization demands. Both jurisdictions illustrate how regulatory divergence shapes software procurement patterns.
United States
California and Texas grid operators deploy predictive control platforms for wildfire-resilient islanding capabilities. FERC Order 841 mandates storage participation in wholesale markets, forcing software-enabled dispatch forecasting. ERCOT's scarcity pricing events reward algorithmic sophistication among merchant developers in Houston and Dallas-Fort Worth.
Germany
Grid operators face mandatory frequency regulation upgrades under FCR market redesign specifications. The EU F-Gas Regulation constrains cooling-system software integrations, forcing 6-9 month thermal management redesigns. System integrators in Munich and Stuttgart absorb compliance costs to maintain CE marking for battery installations.
China
Dual carbon goals accelerate procurement of grid management platforms for utility-scale storage fleets. MIIT standards govern battery management system interoperability for electrochemical storage assets. Industrial clusters in Shenzhen and Shanghai concentrate software development for DC-coupled inverter control in hybrid renewable installations.
India
CEA regulations now permit storage participation in frequency regulation, creating first-mover advantage for climate-optimized algorithms. The PLI scheme for advanced chemistry cell manufacturing drives demand for cell-level traceability software. Developers in Gujarat and Maharashtra prioritize tropical climate optimization for grid-connected battery assets.
Australia
Behind-the-meter residential batteries enable software-based fleet orchestration for virtual power plant aggregation. The country's national electricity regulator enforces grid codes that specify sub-second response windows for frequency control ancillary services. Operators in South Australia and New South Wales deploy edge-native architectures for primary frequency response.
Energy Storage Software Market Vendor Landscape
Top-tier vendors anchor utility control room integration, while mid-tier specialists compete on algorithmic sophistication for merchant revenue optimization. The market structures around three archetypes: industrial conglomerates with captive hardware-software stacks, pure-play optimization vendors with proprietary dispatch algorithms, and renewable developers with vertically integrated software capabilities. Dominant competitive moves include strategic partnerships with inverter manufacturers and geographic expansion into newly liberalized ancillary services markets.
Within the industrial conglomerate tier, Siemens Energy and ABB Ltd. represent European-anchored positions built on deep utility relationships. Fluence Energy exemplifies the pure-play optimization archetype with algorithm-centric competitive positioning. Tesla, Inc. occupies a distinct tier through end-to-end software-hardware coupling in large-scale storage deployments.
| Leading Market Players |
|---|
| Siemens Energy |
| ABB Ltd. |
| General Electric |
| Fluence Energy |
| Tesla, Inc. |
| Hitachi Ltd. |
| Eaton Corporation |
| SolarEdge Technologies, Inc. |
| NextEra Energy, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up software specialists have consolidated fragmented control-system vendors across Germany and the United States, tightening supply discipline while enforcing subscription-based pricing models that decouple software revenue from hardware procurement cycles.
Pricing Analysis
Bundled hardware-software EPC contracts are giving way to unbundled procurement patterns where US independent power developers issue separate RFPs for battery hardware and optimization software. Pricing stratifies across premium AI-driven optimization suites, standard grid-management platforms, and economy monitoring dashboards differentiated by certification tier and integration depth. Cost compression in the standard tier is intensifying because AWS and Azure concentration creates margin pressure for multi-tenant SaaS operators. Merchant-exposed renewable developers in Texas and California show least price sensitivity, prioritizing algorithmic sophistication for scarcity pricing capture; small commercial users behind-the-meter exhibit highest sensitivity, defaulting to stripped-down monitoring tiers.
Supply Chain Analysis
IEC 62443 and UL 1973 certification gating stretches 14-18 months, freezing deployments and concentrating vendor relationships around pre-qualified system integrators in Germany, the United States, and South Korea. Firmware development draws from specialized power systems engineering talent pools, lithium-ion cell supply agreements, and cloud infrastructure provisioning. Single-source vulnerability runs through AWS and Azure hosting concentration for fleet analytics platforms. Distribution runs through EPC contractors and direct utility procurement committees with multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by mandatory grid-code upgrades that force predictable replacement cycles for legacy SCADA infrastructure across regulated utilities.
For Market Incumbents: Extend algorithmic differentiation into tropical climate optimization for India's opening ancillary services market, and deepen captive hardware-software coupling to defend against pure-play optimization vendors eroding margin in merchant-exposed segments. FERC Order 841 compliance investment represents the critical defensive lever. For New Entrants and Emerging Players: Inverter manufacturers present the most viable channel partnership route for algorithm specialists lacking utility control room relationships. India's CEA-regulated frequency regulation market offers the most penetrable geography, with tropical climate optimization as the specific go-to-market angle bypassing incumbent entrenched positions in temperate markets. For Investors and Strategic Acquirers: Industrial conglomerates with captive utility relationships are the most active acquirer in this space, seeking to bolt on AI-driven optimization capabilities. The 5-10 year viability window favors vendors with embedded compliance modules for EU Battery Regulation digital passport mandates. The signal to monitor is convergence versus fragmentation in grid code interoperability standards across Australia, South Korea, and the United Kingdom.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Partnership with Inverter OEMs | Unlocks co-optimized DC-coupled control for hybrid solar-storage installations in ERCOT and CAISO markets. |
| Edge-Native Architecture Deployment | Enables sub-100-millisecond latency compliance with Germany's FCR market redesign specifications. |
| Tropical Climate Optimization Module | Captures first-mover positioning in India's CEA-regulated ancillary services market opening. |
| EU Battery Regulation Compliance Integration | Creates recurring revenue streams through embedded digital passport traceability for cell-level assets. |
| Cybersecurity Certification Fast-Track | Compresses IEC 62443 compliance timelines to unblock critical infrastructure deployment pipelines. |
Methodological Framework
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded qualitative findings, validated against FERC filings, EIA project databases, IEA technology roadmaps, and EU regulatory frameworks. Bottom-up and top-down triangulation cross-checked installed capacity assumptions against procurement pipeline data.
Bottom-up modeling segmented the market by deployment architecture, end-user category, and application type, with value outputs derived from software attach rates to underlying storage hardware capacity additions across the projection horizon. CAGRs were synthesized from regulatory mandate timelines, replacement cycle analysis of legacy SCADA infrastructure, and subscription revenue recognition patterns for cloud-based fleet analytics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium price volatility, grid code fragmentation versus convergence, and cloud concentration risk exposure. A model refresh is warranted upon material change in FERC Order 841 implementation pace or EU Battery Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Supercapacitor Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
Solar Storage Inverter Market