
 Indonesia Renewable Energy CAPEX Market | 2026-2036
Indonesia Renewable Energy CAPEX Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Renewable Energy CAPEX Market Foresight
MEMR Regulation No. 50/2017 on renewable energy pricing is pivoting project economics toward feed-in-tariff structures that protect developer returns. PT Pertamina Geothermal Energy leverages its concession portfolio across the volcanic arc to sustain drilling programs. Siemens Gamesa anchors offshore wind feasibility studies near Sulawesi. PT PLN (Persero) competes as both offtaker and developer, creating asymmetric market access.
Indonesia Renewable Energy CAPEX encompasses capital deployed for generation assets, transmission interconnection, and grid-balancing infrastructure across archipelagic geography with fragmented load centers. Photovoltaic installations dominate near-term deployment due to module cost declines and distributed generation suitability for remote islands. Wind turbine procurement remains concentrated in South Sulawesi and Nusa Tenggara corridors where wind resource maps confirm Class 3+ regimes. Bioenergy systems attract industrial captive demand from palm oil processing clusters in Riau and North Sumatra.
PLN's RUPTL mandates shape capacity procurement timelines while MEMR tariff regulations determine project bankability thresholds. Bappenas coordinates international aid flows through Just Energy Transition Partnership frameworks. Stakeholders must monitor regulatory clarity on geothermal royalty restructuring and inter-island HVDC licensing timelines.
Market Dynamics
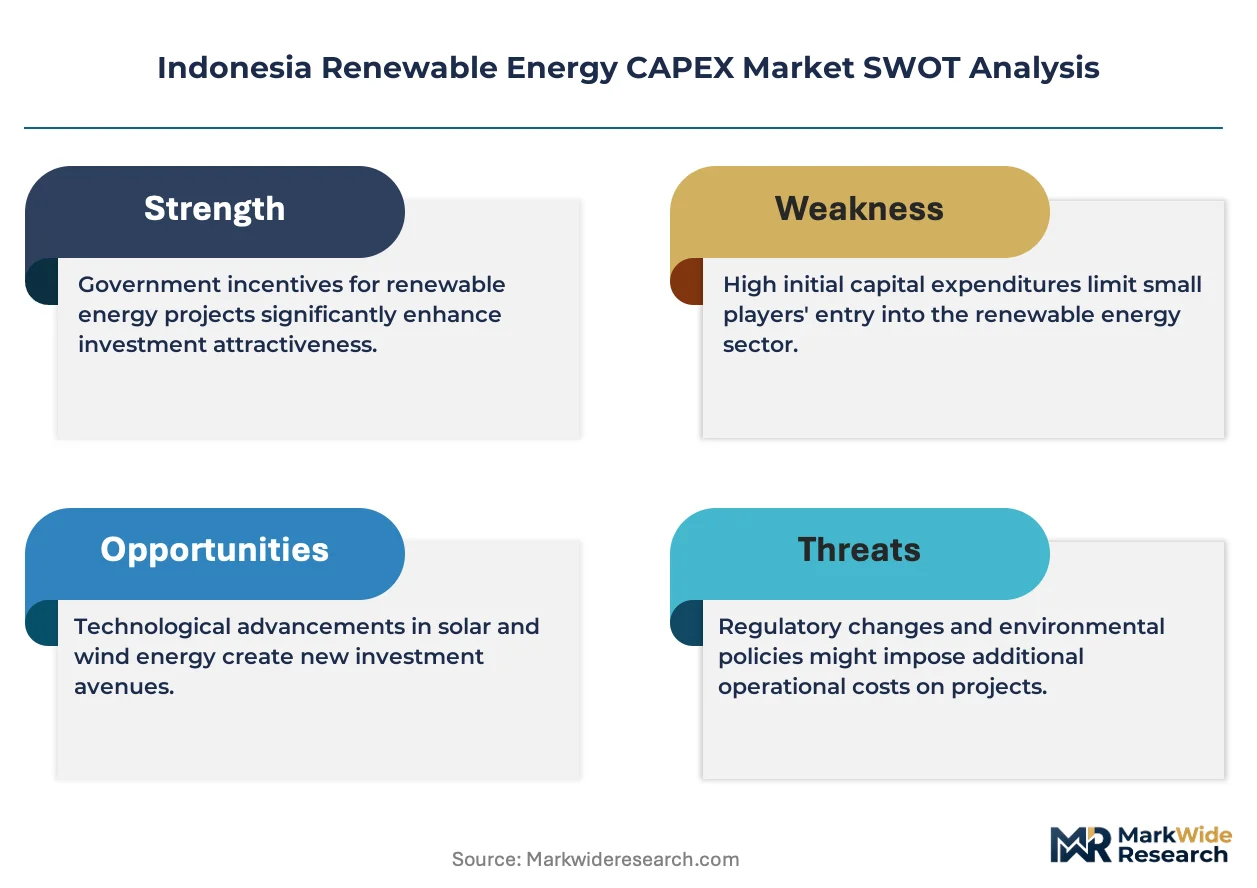
MEMR tariff restructuring and PLN's RUPTL procurement timelines are redirecting capital flows toward independent power producer arrangements, compressing traditional utility-led development cycles across the archipelago.
Growth Catalysts
- Geothermal Concession Expansion:MEMR's royalty rate adjustments for volcanic arc fields are improving project IRRs. Drilling programs accelerate across Sumatra and Sulawesi.
- Solar Module Cost Decline:Photovoltaic deployment is scaling on remote islands where diesel displacement economics now favor distributed generation. Module procurement concentrates through Jakarta port clusters.
- Just Energy Transition Partnership:Bappenas-coordinated international aid flows are de-risking early-stage project development. Blended finance structures unlock commercial lending for utility-scale arrays.
Market Restraints
- HVDC Interconnection Licensing:Cross-island transmission permits face multi-agency coordination delays. Regulatory friction extends project commissioning timelines.
- Domestic Content Requirements:Local component mandates for turbines and modules strain supply availability. Manufacturing capacity lags behind procurement schedules.
- Geothermal Resource Risk:Exploration drilling carries dry-hole probabilities above conventional hydrocarbon basins. Subsurface uncertainty elevates equity return thresholds.
Strategic Opportunities
- Captive Industrial Demand:Palm oil processing clusters in Riau and North Sumatra present bioenergy offtake anchors. Cogeneration systems capture waste stream value.
- Offshore Wind Feasibility:Sulawesi corridor wind resource mapping confirms Class 3+ regimes. Early-movers secure seabed lease positions ahead of regulatory framework finalization.
- Green Hydrogen Export:MEMR power-to-X roadmaps position Indonesian renewables for ammonia and methanol synthesis. Japanese and Korean offtake MOUs establish demand anchors.
Industry Challenges
- Grid Balancing Expertise:Archipelagic load fragmentation requires specialized frequency control engineering. Talent pools for inverter-dominated system integration remain shallow.
- Land Acquisition Complexity:Customary land tenure systems across Maluku and Papua create title clearance bottlenecks. Community engagement timelines extend development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Renewable Energy CAPEX Market |
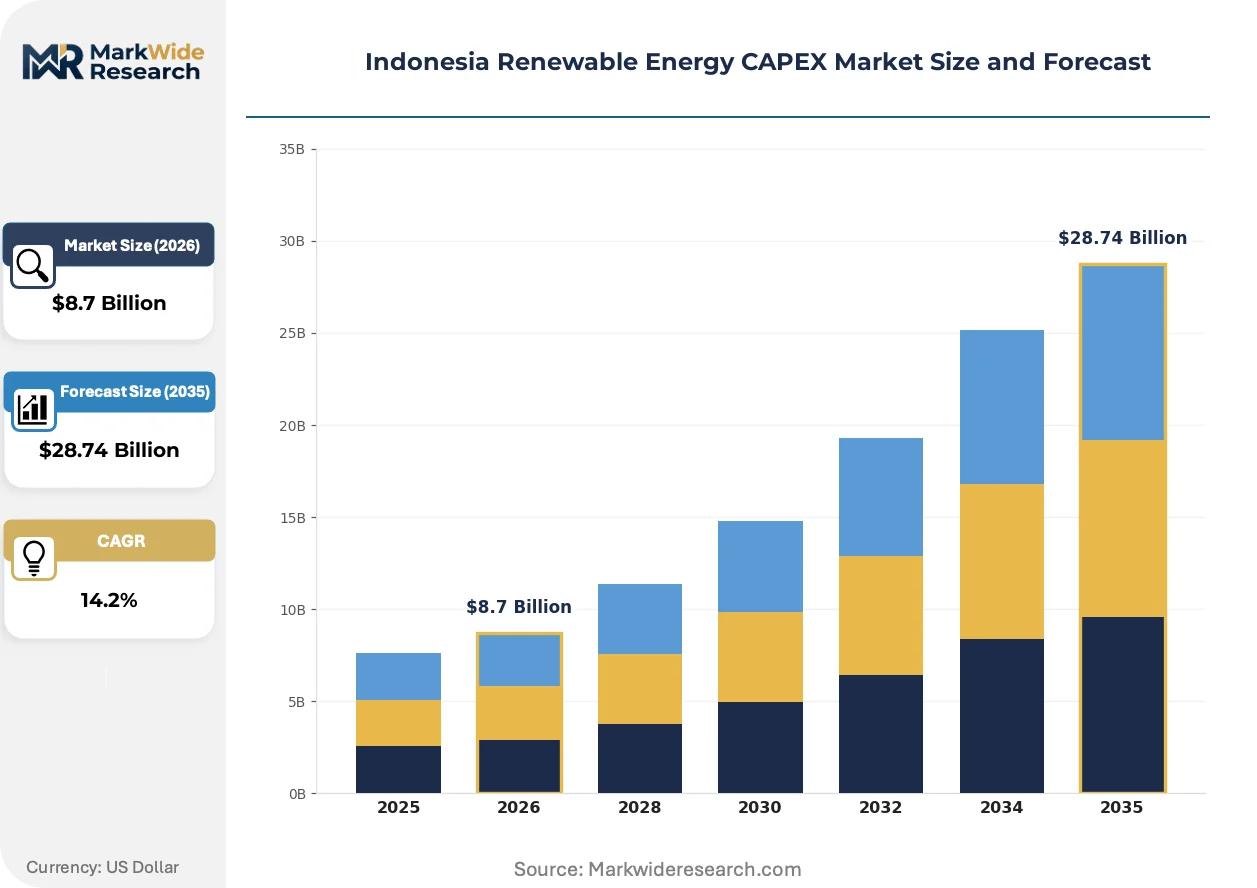
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Wind, Solar, Biomass, Geothermal Technology: Photovoltaic, Concentrated Solar Power, Wind Turbines, Bioenergy Systems End User: Utilities, Industrial, Commercial, Residential Funding Source: Government Grants, Private Equity, Green Bonds, International Aid |
| Companies Covered | PT Pertamina Geothermal Energy, Siemens Gamesa, PT PLN (Persero), ANDRITZ, PT Wijaya Karya (Persero) Tbk., Sindicatum Sustainable Resources, UPC Renewables, Sumitomo Corporation, BCPG Public Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Renewable Energy CAPEX Market Shifts & Advancements
Digital twin modeling and floating solar platforms are compressing site assessment cycles while expanding deployable surface area across reservoir and coastal zones.
Bifacial photovoltaic modules with tracking systems are penetrating utility-scale procurement. PLN and independent developers are specifying these configurations for Java-Bali grid injection. Module-level power electronics is converging with string inverter architectures to reduce balance-of-system costs and improve fault tolerance.
MEMR Regulation No. 50/2017 on renewable energy pricing is hardening feed-in-tariff floors. Developer returns now carry greater predictability against PLN offtake risk. Geothermal and biomass projects with firm capacity characteristics are capturing tariff premiums under the revised structure.
Corporate power purchase agreements are displacing traditional utility procurement for industrial loads. Mining and smelting operations in Sulawesi and Halmahera are contracting directly with renewable developers. This bilateral contracting trend concentrates in nickel processing corridors where energy intensity dominates opex.
Indonesia Renewable Energy CAPEX Market Segmentation
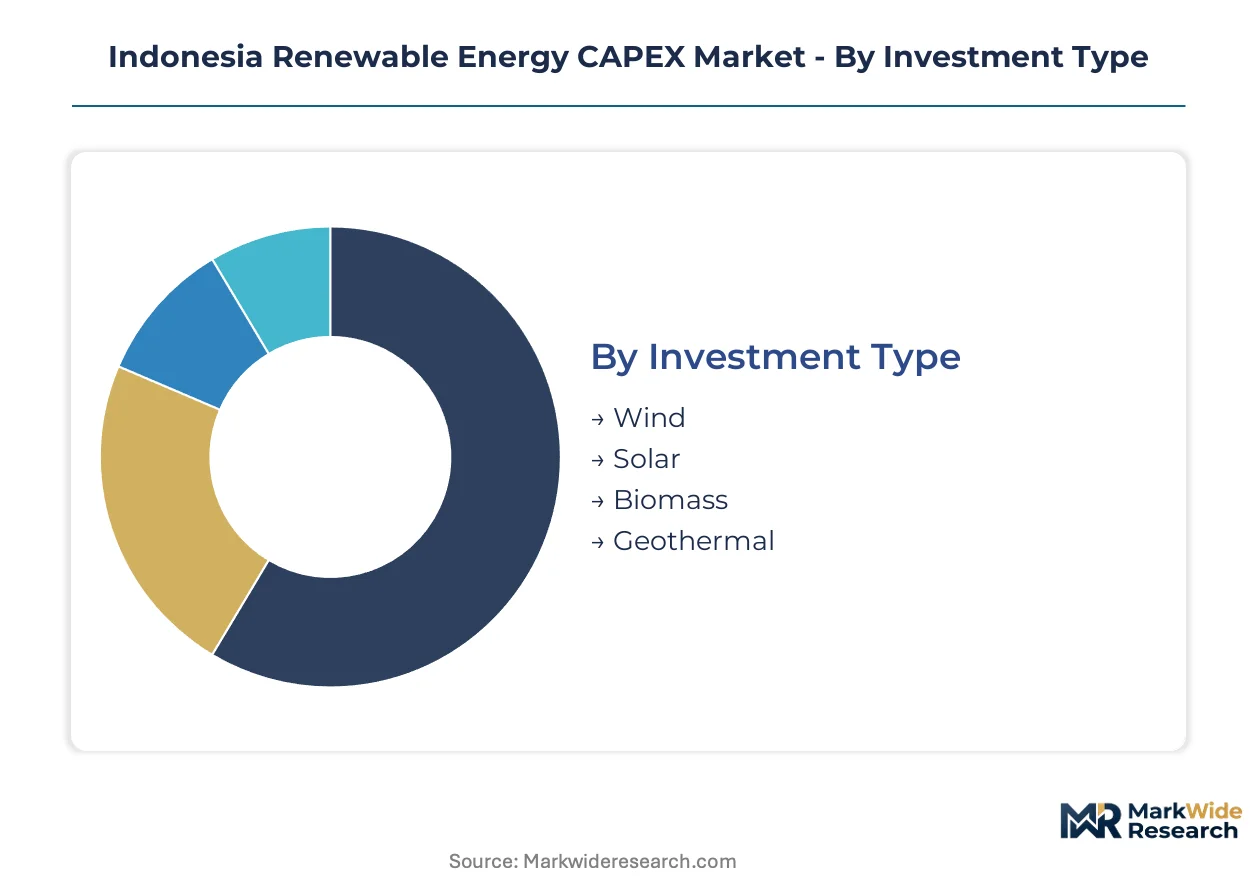
Indonesia's archipelagic geography fragments load centers across thousands of islands, making capital allocation decisions highly sensitive to segment-specific resource profiles and interconnection economics. Each segmentation dimension carries distinct regulatory, financing, and technical risk profiles that shape project bankability.
Investment Type:
Upgrade cycles for generation assets favor technologies with shorter construction timelines and lower resource uncertainty, redirecting capital from exploratory geothermal toward deployable solar and proven wind corridors.
- Wind:Class 3+ wind regimes in South Sulawesi and Nusa Tenggara anchor procurement. Offshore feasibility studies near Sulawesi are securing seabed positions ahead of regulatory finalization.
- Solar:Photovoltaic deployment dominates near-term CAPEX due to module cost declines and distributed generation suitability for diesel displacement on remote islands. Bifacial modules with tracking systems are penetrating utility-scale procurement for Java-Bali grid injection.
- Biomass:Palm oil processing clusters in Riau and North Sumatra drive cogeneration demand. Waste stream valorization captures industrial captive offtake.
- Geothermal:Volcanic arc concessions across Sumatra and Sulawesi sustain drilling programs. Royalty rate adjustments under MEMR regulations are improving project IRRs, though subsurface risk elevates equity return thresholds.
Volume placements concentrate in Solar; the faster expansion belongs to Wind.
Technology:
Technology selection tracks the tension between proven performance and emerging system architectures that reduce balance-of-system costs.
- Photovoltaic:Module-level power electronics converging with string inverter architectures improves fault tolerance. Procurement concentrates through Jakarta port clusters.
- Concentrated Solar Power:Thermal storage integration offers firm capacity characteristics for grid-balancing. Deployment remains limited to demonstration scales.
- Wind Turbines:Domestic content requirements for turbine components strain supply availability. Manufacturing capacity lags procurement schedules.
- Bioenergy Systems:Industrial process heat applications in palm oil refining anchor demand. Feedstock logistics determine project economics.
Photovoltaic captures dominant share; Concentrated Solar Power holds the steepest expansion trajectory contingent on storage cost curves.
End User:
Customer type shapes contracting structures, with bilateral corporate agreements displacing traditional utility procurement in energy-intensive corridors.
- Utilities:PT PLN operates as both offtaker and developer, creating asymmetric market access. RUPTL procurement timelines mandate capacity expansion schedules.
- Industrial:Mining and smelting operations in Sulawesi and Halmahera are contracting directly with renewable developers. Nickel processing corridors concentrate bilateral demand.
- Commercial:Distributed generation uptake tracks retail tariff structures and net metering availability. Urban load centers in Java drive deployment.
- Residential:Rural electrification programs and microgrid architectures serve fragmented island populations. Customary land tenure creates title clearance bottlenecks.
Utilities absorb the largest capital commitments; Industrial segments are gaining share fastest through captive procurement.
Funding Source:
Capital structure decisions hinge on de-risking mechanisms and blended finance availability for early-stage development.
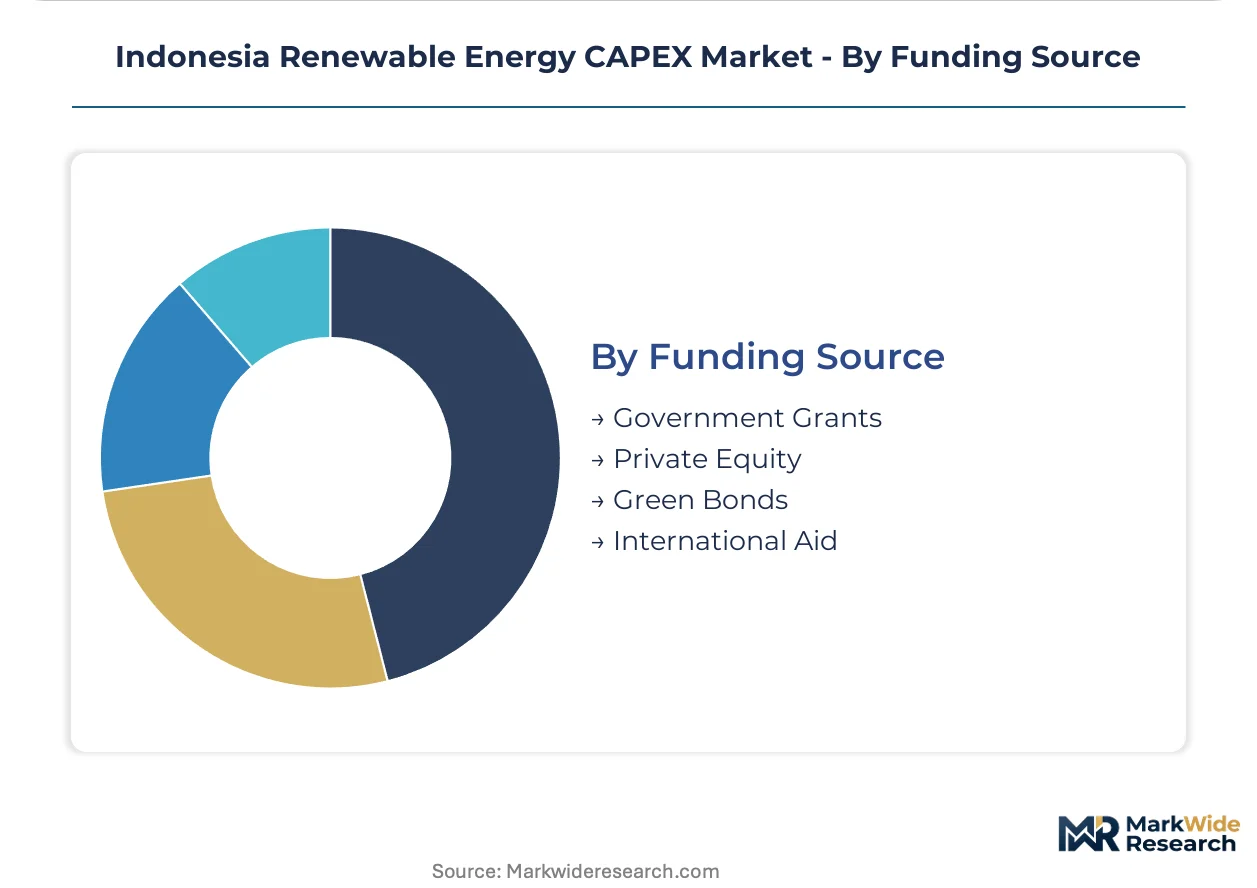
- Government Grants:Bappenas coordinates public allocation through national budget instruments. Fiscal capacity constraints limit scale.
- Private Equity:Developer returns carry greater predictability under MEMR Regulation No. 50/2017 feed-in-tariff floors. PLN offtake risk remains a structuring consideration.
- Green Bonds:International certification standards and use-of-proceeds reporting attract institutional capital. Jakarta listings are expanding.
- International Aid:Just Energy Transition Partnership frameworks de-risk early-stage project development. Blended structures unlock commercial lending for utility-scale arrays.
Private Equity dominates committed capital; International Aid is expanding most quickly through JETP coordination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java-Bali Special Economic Zones concentrate renewable energy investment through MEMR tariff incentives and PLN grid interconnection priority. Sumatra's volcanic arc fields and Sulawesi nickel processing corridors anchor geothermal and captive solar deployment.
Java-Bali Grid
Utility-scale solar arrays and grid-balancing infrastructure dominate CAPEX flows. MEMR Regulation No. 50/2017 feed-in-tariff floors protect developer returns for Java-Bali interconnection projects. Jakarta port clusters process module imports while Surabaya anchors manufacturing logistics.
Sumatra
Geothermal drilling programs accelerate across volcanic arc concessions in North Sumatra and Lampung. MEMR royalty rate adjustments improve project IRRs for volcanic field developers. Medan industrial zones host palm oil cogeneration clusters capturing waste stream value.
Sulawesi
Nickel processing corridors in Morowali and Konawe drive captive renewable procurement from mining-smelting operations. Class 3+ wind regimes in South Sulawesi anchor turbine procurement despite domestic content bottlenecks. Makassar serves as logistics hub for offshore wind feasibility positioning.
Nusa Tenggara
Remote island diesel displacement economics favor distributed solar deployment. PLN rural electrification programs channel microgrid investment through Kupang and Mataram load centers. Customary land tenure systems create title clearance delays in East Nusa Tenggara.
Papua and Maluku
Fragmented archipelagic populations require specialized off-grid architectures. Community engagement timelines extend development schedules across customary tenure zones. Sorong and Ambon anchor regional logistics for modular renewable system deployment.
Indonesia Renewable Energy CAPEX Market Competitive Landscape
Indonesian state-owned enterprises anchor one tier; European and Japanese specialists hold equipment supply positions. Market structure concentrates around PLN's dual role as offtaker and developer, creating asymmetric access patterns for independent power producers. Three archetypes dominate: integrated state utilities, geothermal concession holders, and international turbine suppliers. Competitive moves center on concession portfolio expansion and strategic partnerships for HVDC interconnection licensing.
Within the state-utility archetype, PT PLN (Persero) occupies the central coordinating position for RUPTL-mandated procurement timelines. PT Pertamina Geothermal Energy represents the concession-holder model across Sumatra and Sulawesi volcanic fields. Siemens Gamesa sits within the international equipment supply tier, anchoring offshore wind feasibility positioning near Sulawesi.
| Leading Market Players |
|---|
| PT Pertamina Geothermal Energy |
| Siemens Gamesa |
| PT PLN (Persero) |
| ANDRITZ |
| PT Wijaya Karya (Persero) Tbk. |
| Sindicatum Sustainable Resources |
| UPC Renewables |
| Sumitomo Corporation |
| BCPG Public Company Limited |
| Others |
Supply & Pricing Matrix
Captive module procurement through Jakarta port clusters anchors both supply security and developer pricing power for Indonesian renewable energy projects. PT PLN's dual role as offtaker and developer compresses margin negotiation space for independent power producers while MEMR tariff floors protect returns against input cost volatility.
Pricing Analysis
Premium pricing for expedited module delivery compresses project IRRs for developers facing RUPTL-mandated commissioning deadlines. Contract-based long-term offtake agreements dominate procurement structures, with price differentiation tracking certification tiers and domestic content ratios. Cost compression in standard-tier modules is intensifying because Chinese manufacturers are flooding Jakarta port channels. Industrial offtakers in nickel processing corridors show lowest price sensitivity due to energy intensity dominance in opex.
Supply Chain Analysis
Domestic content requirements for wind turbine components are reshaping sourcing patterns toward constrained local fabrication capacity. Manufacturing concentrates in China, Vietnam, and South Korea for photovoltaic modules; Germany and Denmark for turbine nacelles; and Japan for grid inverters. Raw material dependencies span polysilicon feedstock, rare-earth magnets, and high-grade steel forgings. Single-source vulnerability in HVDC converter stations elevates supply risk. Distribution runs through Surabaya manufacturing logistics hubs and Makassar offshore wind staging points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's renewable energy CAPEX market operates as a supply-constrained environment where domestic manufacturing bottlenecks for turbine components prop developer pricing. MEMR tariff floors protect returns but cannot eliminate commissioning delays from component shortages.
For Market Incumbents: Lock in concession portfolio extensions across Sumatra volcanic arc fields before royalty rate restructuring stabilizes. Secure captive fabrication partnerships for turbine towers to deflect domestic content compliance penalties. Prioritize HVDC interconnection licensing applications ahead of multi-agency coordination backlogs. For New Entrants and Emerging Players: Begin with distributed solar deployment in Nusa Tenggara diesel displacement corridors where PLN procurement timelines favor fast-track interconnection. Target palm oil cogeneration clusters in Riau for industrial captive offtake with waste stream valorization. Pursue direct corporate power purchase agreement origination with nickel smelting operations bypassing PLN offtake queues. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated state utilities seeking geothermal concession consolidation. Five-to-ten year viability hinges on JETP framework renewal and tariff floor durability. Monitor MEMR regulatory clarity on inter-island transmission licensing as primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Geothermal Concession Expansion | MEMR royalty adjustments improve project IRRs across Sumatra volcanic fields. |
| Corporate Power Purchase Agreements | Bilateral contracting with nickel smelters bypasses PLN procurement bottlenecks. |
| Domestic Content Compliance | Local turbine component mandates strain supply availability for wind developers. |
| HVDC Interconnection Licensing | Cross-island transmission permits face multi-agency coordination delays. |
| Floating Solar Platform Deployment | Reservoir-based PV expands deployable surface area for Java-Bali grid injection. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Indonesia renewable energy CAPEX analysis. Primary interviews with IPP project developers, EPC contractors, PLN planning officers, and grid operators combined with MEMR decree archives, PLN RUPTL documentation, and Bappenas aid flow disclosures. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic capacity targets.
Segment-level granularity modeled investment type, technology architecture, end-user category, and funding source dimensions across the projection horizon. CAGRs derived from capacity deployment curves weighted by construction timeline probability and regulatory approval status. Geothermal resource risk premiums and solar module cost decline trajectories informed technology-specific forecast inputs.
Underlying measurement precision varies by segment; utility-scale solar and onshore wind carry tighter precision than exploratory geothermal and offshore wind. Forecasts reflect assumptions on JETP framework continuity, MEMR tariff floor stability, and domestic content requirement enforcement. Regulatory reversal on royalty restructuring or inter-island transmission permitting could materially revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Farm Market
Renewable Energy
East Africa Renewable Energy Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Solar Boat Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Argentina Renewable Energy Market