
 United States Oil and Gas Midstream Market | 2026-2036
United States Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oil and Gas Midstream Market Analytics
The Permian Basin is rewriting midstream investment priorities across North America. Enterprise Products Partners L.P. leverages its Mont Belvieu fractionation complex to dominate NGL export capacity. Kinder Morgan, Inc. anchors natural gas transmission with its Tennessee Gas Pipeline network spanning the Northeast. Energy Transfer LP controls crude oil logistics through its Dakota Access Pipeline and Texas terminal assets.
United States oil and gas midstream operations encompass the processing, storage, transportation, and wholesale marketing of crude oil, natural gas, and natural gas liquids between upstream production fields and downstream refineries or export terminals. Pipeline systems operate at pressures ranging from 200 to 1,440 psi depending on product type and terrain, with corrosion-resistant coatings and cathodic protection extending asset life beyond fifty years. Transportation and processing services capture the largest margin pools, while digital monitoring technology is displacing conventional SCADA systems fastest as operators deploy IoT sensors for predictive maintenance. Fractionation capacity near Mont Belvieu, Texas leads volume growth due to rising associated gas output from Permian shale wells.
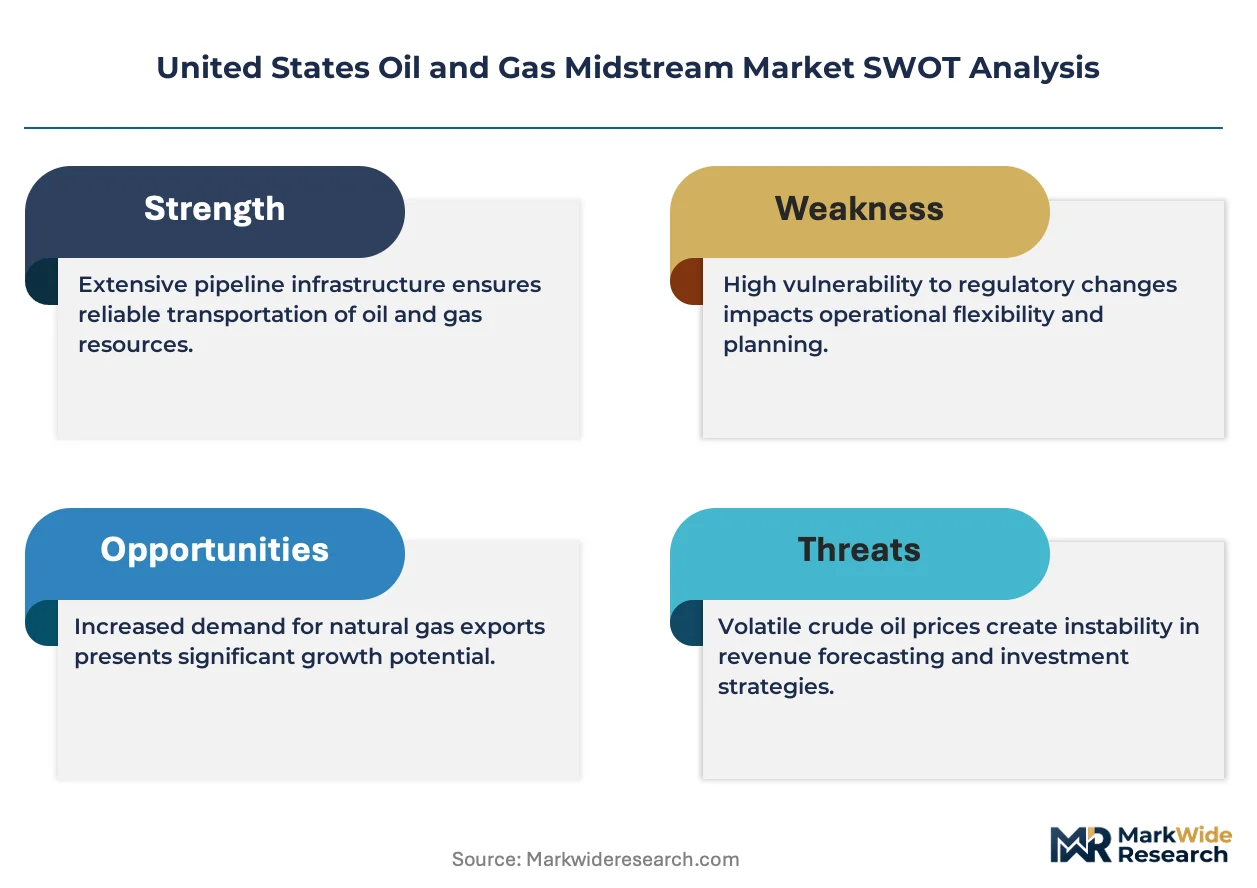
FERC governs interstate pipeline rates and certificate approvals, while EPA methane regulations under the Inflation Reduction Act mandate continuous emissions monitoring at compressor stations and storage facilities. DOT PHMSA enforces pipeline safety standards including integrity management rules for high-consequence areas, which operators must satisfy to maintain operating licenses. Stakeholders should monitor FERC certificate backlogs and state-level siting disputes, as these administrative bottlenecks increasingly determine project timelines more than capital availability or engineering feasibility.
Market Dynamics
FERC certificate backlogs and EPA methane enforcement under the Inflation Reduction Act are compressing project timelines more than capital constraints, forcing operators to front-load regulatory compliance spending before breaking ground on new pipeline or fractionation assets.
Growth Catalysts
- Permian Basin production expansion:Associated gas output from West Texas and New Mexico shale wells is saturating existing NGL fractionation capacity, pulling investment toward Mont Belvieu complex expansions and new Gulf Coast export terminal construction.
- Inflation Reduction Act methane rules:EPA mandates for continuous emissions monitoring at compressor stations are accelerating replacement of pneumatic controllers with electric alternatives, creating retrofit demand across interstate pipeline networks.
- Gulf Coast petrochemical offtake:Downstream crackers and derivative plants in Texas and Louisiana are expanding NGL absorption capacity, tightening the supply chain link between fractionation and chemical manufacturing.
Market Restraints
- Steel and alloy input volatility:Line pipe and compressor station fabrication costs swing with nickel and molybdenum price cycles, squeezing project returns when commodity spikes coincide with construction windows.
- FERC interstate rate regulation:Cost-of-service ratemaking and certificate approval delays create revenue recognition uncertainty for greenfield pipeline investments spanning multiple states.
- Electrification substitution in heating:Northeast utilities are displacing residential natural gas demand with heat pump deployment, compressing long-haul transmission load factors on legacy pipeline corridors.
Strategic Opportunities
- Hydrogen blending infrastructure:Pipeline operators in Texas and Louisiana can repurpose existing natural gas corridors for hydrogen transport, leveraging Gulf Coast ammonia and petrochemical demand clusters.
- Carbon capture and storage integration:EPA 45Q tax credit expansion is pulling investment toward CO2 compression and pipeline networks linking ethanol plants and Gulf Coast sequestration formations.
- AI-driven predictive maintenance:Machine vision and acoustic sensing convergence is creating white space for autonomous leak detection services, displacing manual survey crews across high-consequence areas.
Industry Challenges
- SCADA-to-IoT migration complexity:Legacy control system architectures in decades-old pipeline networks resist seamless integration with cloud-native monitoring platforms, forcing parallel infrastructure runs during transition periods.
- Specialized welding and inspection talent scarcity:X-ray and ultrasonic testing certification pipelines cannot match retirements in the non-destructive examination workforce, stretching integrity management timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oil and Gas Midstream Market |
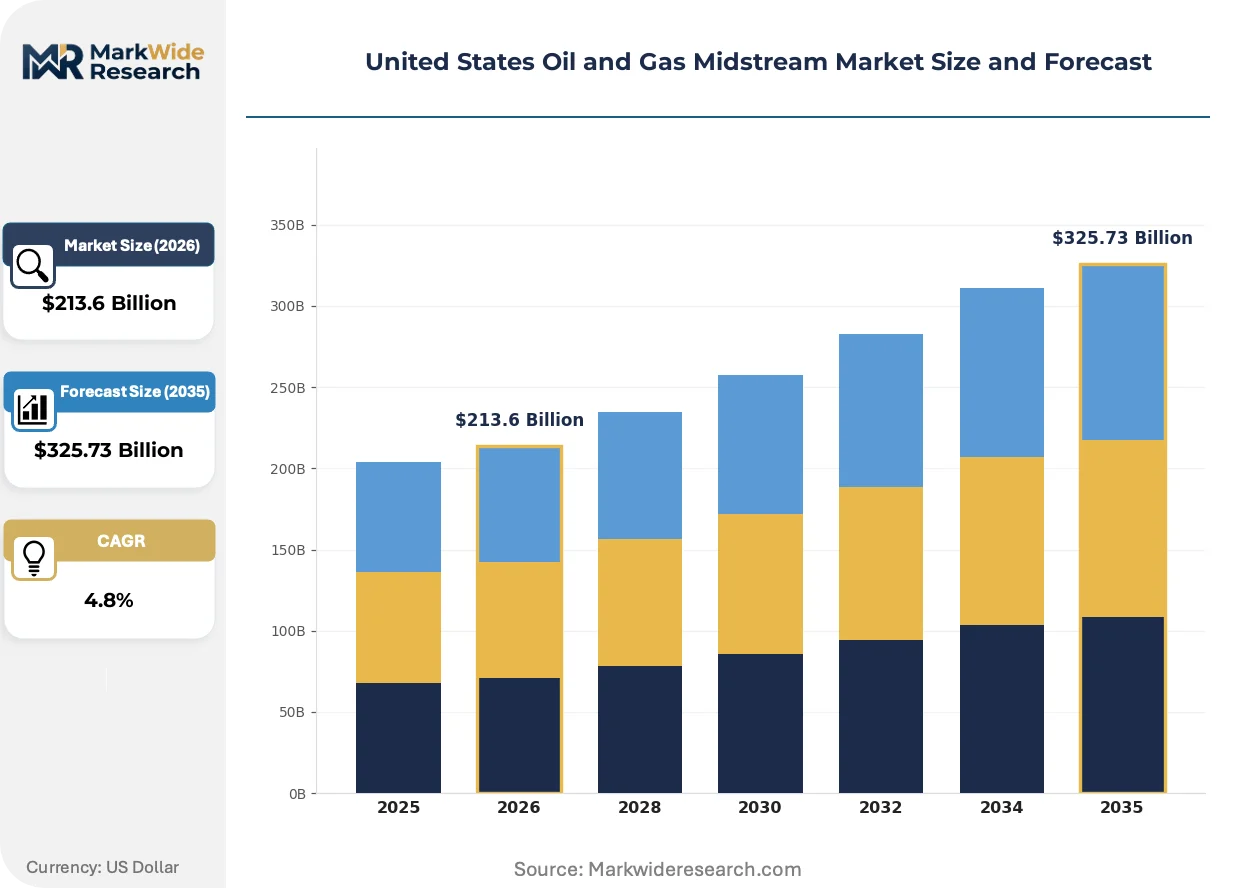
| Market Size in 2026 | $213.6 Billion |
| Market Size in 2035 | $325.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Processing, Fractionation Pipeline Type: Crude Oil, Natural Gas, Multi-Product, Water End User: Energy Companies, Industrial Users, Utilities, Refineries Technology: Conventional, Advanced, Digital Monitoring, Automation |
| Companies Covered | The Williams Companies, Inc., Enterprise Products Partners L.P., Kinder Morgan, Inc., Energy Transfer LP, MPLX LP, ONEOK, Inc., Cheniere Energy, Inc., Targa Resources Corp., Enbridge Inc. (U.S.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oil and Gas Midstream Market Evolving Landscape
Digital infrastructure is compressing operational response times across pipeline networks while regulatory pressure and export demand reshape capital allocation priorities for midstream operators.
IoT sensor networks deploying acoustic, thermal, and pressure transducers along pipeline rights-of-way are digitizing leak detection workflows that previously relied on aerial patrols and ground crews. Major interstate operators are adopting these systems fastest in high-consequence areas where PHMSA integrity management rules apply most stringently. The shift is compressing incident response windows from days to hours while generating continuous emissions data for EPA compliance reporting.
EPA methane performance standards under the Inflation Reduction Act are mandating zero-bleed pneumatic device replacements and quarterly LDAR surveys at storage facilities. These rules are forcing capital reallocation toward compressor station retrofits and gas capture systems ahead of scheduled maintenance cycles. The Permian Basin and Appalachian shale plays face the steepest compliance curves due to concentrated associated gas production and aging gathering infrastructure.
Long-term offtake contracting for LNG export terminals is displacing traditional utility procurement as the dominant demand-pull mechanism for new pipeline capacity. Developers in Texas and Louisiana are securing 15-20 year transportation agreements with Cheniere and Venture Global before FERC certificate filings, compressing project finance timelines. This shift concentrates counterparty risk with a handful of export facility operators while insulating pipeline returns from domestic demand fluctuations.
United States Oil and Gas Midstream Market Segmentation
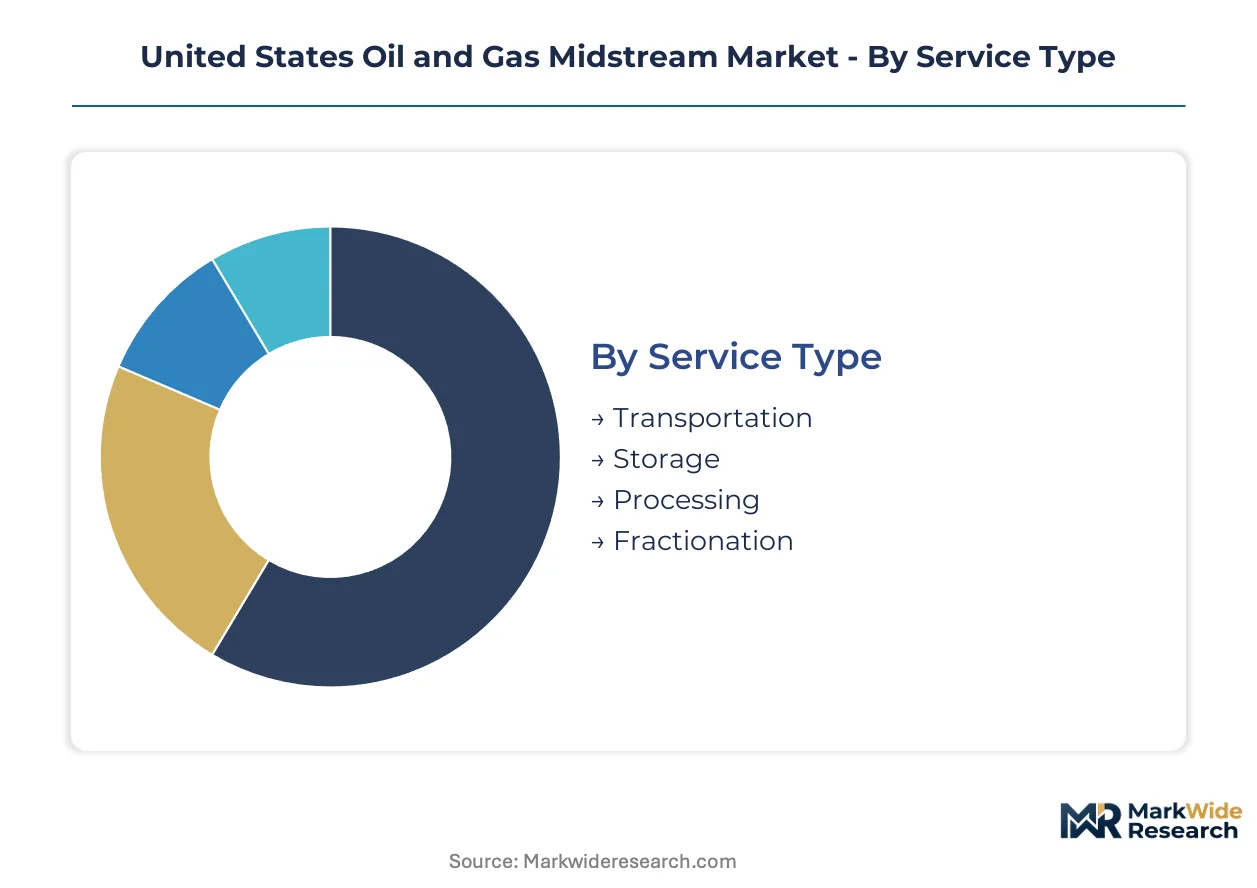
Midstream operators allocate capital across distinct service layers and infrastructure types, each carrying differentiated regulatory exposure and margin profiles. Segmentation clarity reveals where Permian Basin production growth is tightening capacity constraints versus where electrification is compressing legacy demand.
Service Type:
Use cases span commodity logistics, temporal arbitrage, molecular transformation, and purity separation.
- Transportation:Pipeline networks and rail terminals move crude oil, natural gas, and NGLs between production basins and demand centers. Texas and Louisiana corridors absorb the heaviest investment as Gulf Coast export terminal buildouts pull volume southward from the Permian.
- Storage:Underground salt caverns and above-ground tank farms enable inventory positioning and seasonal demand smoothing. Cushing, Oklahoma and the Gulf Coast dominate working capacity, with EPA methane rules now mandating continuous emissions monitoring at above-ground facilities.
- Processing:Gas treatment plants remove contaminants and condition raw production for pipeline specifications. Associated gas output from West Texas shale wells is saturating existing plant capacity, forcing operators to front-load compression and dehydration investments.
- Fractionation:NGL separation into purity products feeds Gulf Coast petrochemical crackers and export markets. Mont Belvieu complex expansions are capturing the steepest capital allocation as NGL production outpaces existing splitter capacity.
Established volume favors Transportation; emerging adoption favors Fractionation.
Pipeline Type:
Commodity-specific infrastructure carries distinct pressure ratings, metallurgical requirements, and regulatory oversight intensity.
- Crude Oil:Large-diameter trunk lines operate at 600-1,440 psi across long-haul corridors linking the Permian to Gulf Coast terminals. Dakota Access and Permian-to-Gulf routes anchor current capacity, with FERC certificate delays compressing greenfield project timelines more than capital availability.
- Natural Gas:Interstate transmission systems at 800-1,000 psi deliver dry gas to utilities and LNG export facilities. Tennessee Gas Pipeline and related Northeast corridors face load factor pressure as heat pump deployment displaces residential gas demand in New England.
- Multi-Product:Flexible batching systems transport refined products and NGLs on shared rights-of-way. These lines concentrate in the Gulf Coast petrochemical corridor where downstream crackers demand multiple feedstock streams.
- Water:Produced water gathering and disposal pipelines serve Permian and Appalachian shale plays. Saltwater disposal well proximity dictates route economics, with Texas Railroad Commission permitting timelines determining project velocity.
Crude Oil pipelines command the largest installed base; Natural Gas infrastructure faces the steepest demand uncertainty.
End User:
Customer contracting power and offtake duration vary sharply across the demand spectrum.
- Energy Companies:Integrated producers and independent E&Ps contract for gathering, processing, and transportation services. Permian Basin operators are driving the fastest capacity expansion as associated gas output strains existing midstream commitments.
- Industrial Users:Petrochemical manufacturers and ammonia plants absorb NGL and hydrogen feedstocks. Gulf Coast crackers are expanding offtake agreements with Mont Belvieu fractionators, tightening the supply chain link between midstream and chemical manufacturing.
- Utilities:Local distribution companies and power generators procure natural gas under seasonal and baseload contracts. Northeast utilities are reducing long-haul transmission commitments as electrification policies compress residential gas demand.
- Refineries:Downstream processors source domestic and imported crude through dedicated pipeline and marine terminals. Gulf Coast complex refineries dominate throughput, with waterborne access enabling both domestic Permian and international crude sourcing.
Industrial Users are expanding contract duration fastest; Utilities are shortening commitment horizons.
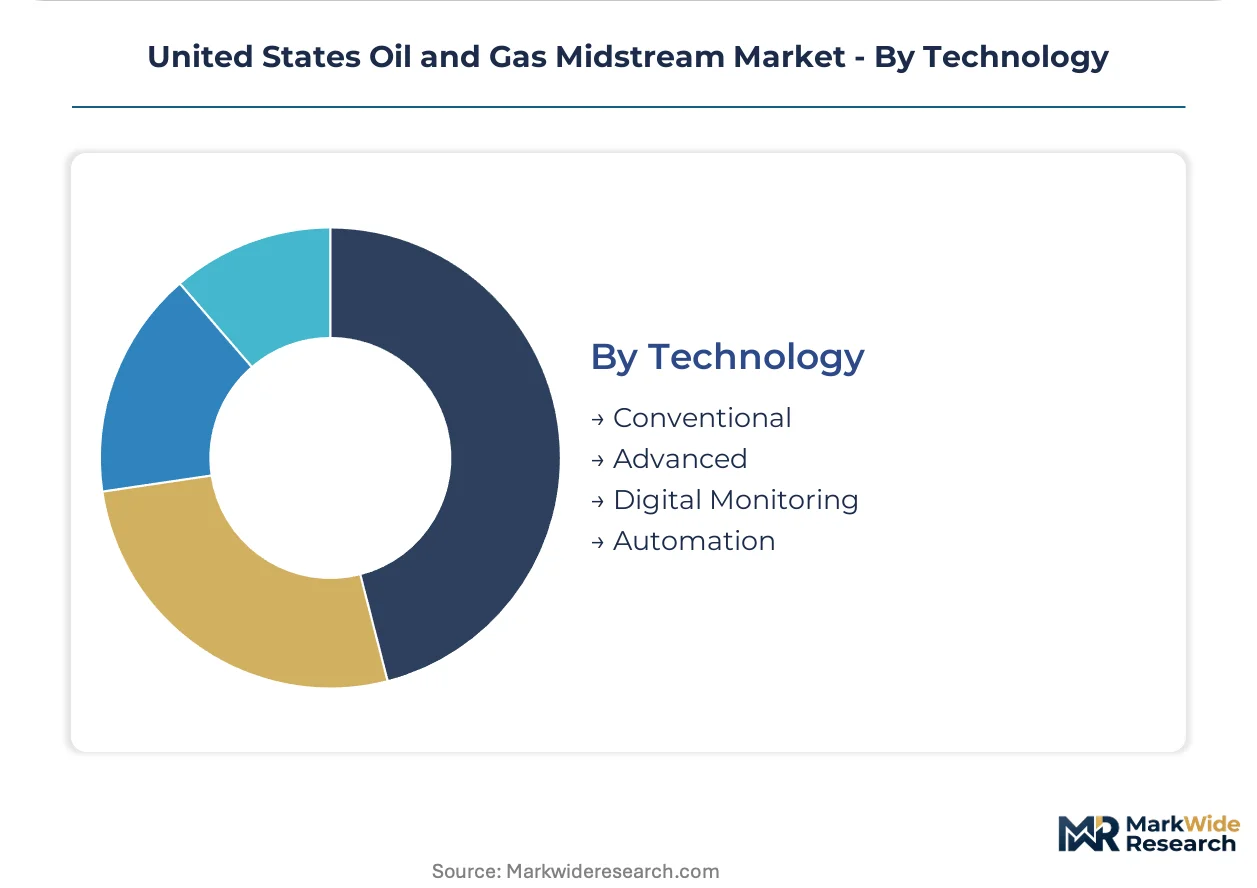
Technology:
Operational technology layers determine emissions compliance cost, labor intensity, and incident response speed.
- Conventional:Mechanical pneumatics and manual inspection regimes dominate legacy infrastructure. Appalachia and older Permian gathering systems face the steepest EPA methane retrofit burden as zero-bleed device mandates take effect.
- Advanced:Electric compressors, advanced materials, and automated valve stations improve efficiency and reduce venting. New build projects in Texas and Louisiana are specifying electric drive as standard to preempt regulatory compliance costs.
- Digital Monitoring:IoT sensor networks, acoustic leak detection, and cloud-native SCADA platforms compress incident response windows. High-consequence areas under PHMSA integrity management rules are adopting these systems fastest.
- Automation:Autonomous pigging, drone inspection, and machine vision inspection reduce crew exposure and survey cycle times. The technology is gaining traction in offshore Gulf corridors and remote West Texas routes where labor availability constrains manual operations.
Conventional systems retain the largest installed base; Digital Monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interstate certificate approvals and EPA methane enforcement under the Inflation Reduction Act dominate regulatory timelines across the United States midstream corridor. Texas and Louisiana absorb the heaviest capital deployment as Gulf Coast export terminal buildouts converge with Permian Basin production growth.
Texas Gulf Coast
Mont Belvieu fractionation complexes and Cheniere LNG export terminals drive capacity expansion along the Houston-Beaumont corridor. EPA continuous emissions monitoring mandates at compressor stations accelerate electric pneumatic retrofits. Enterprise Products Partners anchors NGL export infrastructure while new pipeline laterals connect Permian supply to Gulf Coast waterborne terminals.
Permian Basin
West Texas and southeastern New Mexico shale wells generate associated gas volumes saturating existing gathering and processing capacity. Texas Railroad Commission saltwater disposal permitting timelines dictate produced water pipeline economics. Midland-Odessa logistics clusters concentrate crude oil terminal and fractionation pre-investment as operators front-load compression assets.
Louisiana
Henry Hub pricing convergence and Mississippi River petrochemical corridors pull natural gas and NGL volumes eastward from Texas. FERC interstate rate proceedings for cross-border pipelines create revenue recognition uncertainty. Lake Charles industrial complexes expand offtake agreements with midstream fractionators, tightening supply chain links to chemical manufacturing.
Appalachia
Marcellus and Utica shale plays face pipeline takeaway constraints as Northeast utilities displace residential natural gas with heat pump electrification. PHMSA integrity management rules apply stringently across high-consequence areas in Pennsylvania and Ohio. Pittsburgh-area processing plants confront zero-bleed pneumatic mandates under EPA methane performance standards.
Oklahoma
Cushing crude oil storage hub maintains working capacity dominance despite Gulf Coast terminal competition. FERC certificate backlogs for greenfield pipeline investments compress project timelines more than capital availability. Tulsa-based pipeline operators navigate DOT PHMSA safety standards while expanding digital monitoring infrastructure across legacy SCADA architectures.
United States Oil and Gas Midstream Market Competitive Landscape
Integrated network operators and specialized fractionators split the market into consolidated infrastructure hierarchies. Enterprise-scale players control Gulf Coast terminal access while regional gatherers dominate Permian and Appalachian last-mile logistics. Three archetypes define competitive positioning: full-service midstream conglomerates with integrated transportation-processing-storage portfolios; NGL-focused fractionators anchored at Mont Belvieu; and gas transmission specialists with interstate FERC-regulated rate bases. Capacity expansion and strategic joint ventures for LNG export offtake represent the dominant competitive moves as developers secure 15-20 year transportation agreements before regulatory filings.
Within the full-service conglomerate tier, Enterprise Products Partners L.P. and Energy Transfer LP exemplify integrated operators with Gulf Coast terminal dominance. Kinder Morgan, Inc. occupies a distinct position as the gas transmission archetype with Northeast corridor exposure. These three entities anchor competitive dynamics as capital allocation shifts toward export-linked infrastructure and methane compliance retrofits under Inflation Reduction Act mandates.
| Leading Market Players |
|---|
| The Williams Companies, Inc. |
| Enterprise Products Partners L.P. |
| Kinder Morgan, Inc. |
| Energy Transfer LP |
| MPLX LP |
| ONEOK, Inc. |
| Cheniere Energy, Inc. |
| Targa Resources Corp. |
| Enbridge Inc. (U.S.) |
| Others |
Value Network & Pricing Analysis
Mont Belvieu fractionation capacity expansions are tightening NGL purity-product supply and amplifying pricing power for Gulf Coast terminal operators serving Cheniere and Venture Global offtake agreements. This geographic concentration of molecular transformation infrastructure feeds directly into contract-based long-term transportation rate negotiations across Texas and Louisiana corridors.
Pricing Analysis
Henry Hub-to-Mont Belvieu price spreads for ethane and propane are widening as Permian Basin associated gas production saturates existing fractionation capacity, compressing spot-market liquidity for purity products. Contract-based long-term offtake agreements with LNG export terminals anchor revenue visibility, while volume scale and compressor station proximity to Gulf Coast waterborne terminals drive price differentiation between pipeline operators. Pricing pressure stems from FERC cost-of-service ratemaking delays that stretch revenue recognition timelines for greenfield interstate investments. Industrial petrochemical buyers exhibit the least price sensitivity due to integrated supply chain links, while Northeast utilities facing electrification-driven demand erosion negotiate hardest on transmission tariffs.
Supply Chain Analysis
Bureau of Industry and Security export controls on advanced compressor and pipeline monitoring technologies constrain domestic midstream operators from sourcing certain digital monitoring equipment, forcing reliance on domestic IoT sensor manufacturers and European alternatives. Line pipe and specialty alloy inputs draw from integrated US steel mills, German seamless pipe producers, and Japanese metallurgical suppliers. Nickel and molybdenum price volatility constitutes the dominant supply chain risk, with commodity spikes during construction windows squeezing project returns. Distribution runs through FERC-regulated interstate certificate frameworks that govern capacity allocation across multi-state corridor investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against electrification-driven natural gas demand erosion in residential heating, requiring incumbents to harden revenue streams around industrial and export-linked offtake that resist near-term displacement.
For Market Incumbents: Build regulatory moats by front-loading EPA methane compliance investments and securing FERC certificates ahead of competitor filings. Compressor station retrofit programs for zero-bleed pneumatic devices should accelerate ahead of Inflation Reduction Act enforcement timelines. Backward integration into Mont Belvieu fractionation capacity anchors molecular transformation margins against pure-play transportation commoditization. For New Entrants and Emerging Players: Establish a beachhead in produced water gathering and saltwater disposal corridors across the Permian Basin, where Texas Railroad Commission permitting complexity deters incumbent expansion. Carbon capture and compression infrastructure linking ethanol plants to Gulf Coast sequestration formations represents the most penetrable white space. Go-to-market positioning should emphasize EPA 45Q tax credit structuring expertise as a differentiated service layer. For Investors and Strategic Acquirers: Long-term, this sits as a contracted-cash-flow infrastructure play because 15-20 year LNG export transportation agreements insulate pipeline returns from domestic demand fluctuations. Acquisition targets should display concentrated exposure to Gulf Coast terminal access and FERC-regulated interstate rate bases. The signal to watch is FERC certificate backlog resolution velocity, as administrative throughput determines project finance timelines more than capital availability.| Strategic Initiative | Industry Significance |
|---|---|
| Methane Compliance Retrofit Program | EPA Inflation Reduction Act mandates accelerate zero-bleed pneumatic replacements ahead of enforcement windows. |
| Mont Belvieu Fractionation Expansion | Enterprise Products Partners anchors NGL export capacity as Permian associated gas production saturates existing splitters. |
| Carbon Capture Network Development | 45Q tax credit expansion pulls investment toward CO2 compression linking ethanol plants to Gulf Coast sequestration. |
| LNG Export Terminal Offtake Contracting | Cheniere and Venture Global secure 15-20 year transportation agreements before FERC certificate filings compress project risk. |
| Digital Monitoring Infrastructure Deployment | IoT sensor networks displace manual leak detection surveys across PHMSA high-consequence area corridors. |
Research Methodology
Initial hypotheses were tested against primary input from midstream asset managers, FERC regulatory counsel, compressor station operations directors, and petrochemical procurement leads and refined through secondary validation against EIA production data, FERC interstate pipeline filings, EPA enforcement databases, and SEC 10-K infrastructure disclosures. Bottom-up capacity buildout modeling triangulated against top-down macro demand projections anchored the quantitative framework.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across service type, pipeline commodity, end-user contracting power, and technology adoption tier. CAGRs were derived from capacity utilization trajectories and capital deployment velocity across Mont Belvieu fractionation, Permian Basin gathering, and Gulf Coast export terminal buildouts. Forecast inputs incorporated FERC certificate approval timelines, EPA methane retrofit cost curves, and LNG export capacity commissioning schedules.
Stress conditions across steel and alloy input price volatility, FERC regulatory delay scenarios, and electrification-driven demand erosion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Permian production growth persistence and Gulf Coast petrochemical offtake expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Copper Mining Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Upstream Services Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Oil & Gas Static and Rotating Equipment Market