

Mechanical Shaft Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Shaft Seal Market Insights
Buyer concentration among oil refineries and chemical manufacturers is consolidating as integrated energy majors centralize procurement through preferred supplier programs. John Crane leverages its aftermarket service network to sustain long-term contracts with these consolidated buyers. EagleBurgmann anchors its position through specialized metal bellows seal engineering for high-temperature reactor applications.
A mechanical shaft seal is a precision-engineered device comprising stationary and rotating faces held in contact by spring or bellows force, typically manufactured from silicon carbide, tungsten carbide, or carbon graphite composites, designed to prevent fluid leakage along rotating pump and compressor shafts. Cartridge seals capture the dominant share of product type demand due to their pre-assembled configuration that reduces installation error and field failure rates. Gas seal technology is displacing conventional liquid-lubricated designs in centrifugal compressors across power generation units, driven by emissions reduction mandates and efficiency targets.
REACH and the EU F-Gas Regulation constrain fluoropolymer and elastomer material choices for seals sold into European chemical manufacturers and oil refineries. The EPA enforces leak detection and repair protocols that mandate seal performance thresholds in US petroleum refining operations. Stakeholders must monitor evolving API 682 and ISO 21049 standards as these specifications increasingly incorporate lifecycle carbon accounting and digital condition-monitoring compatibility requirements.
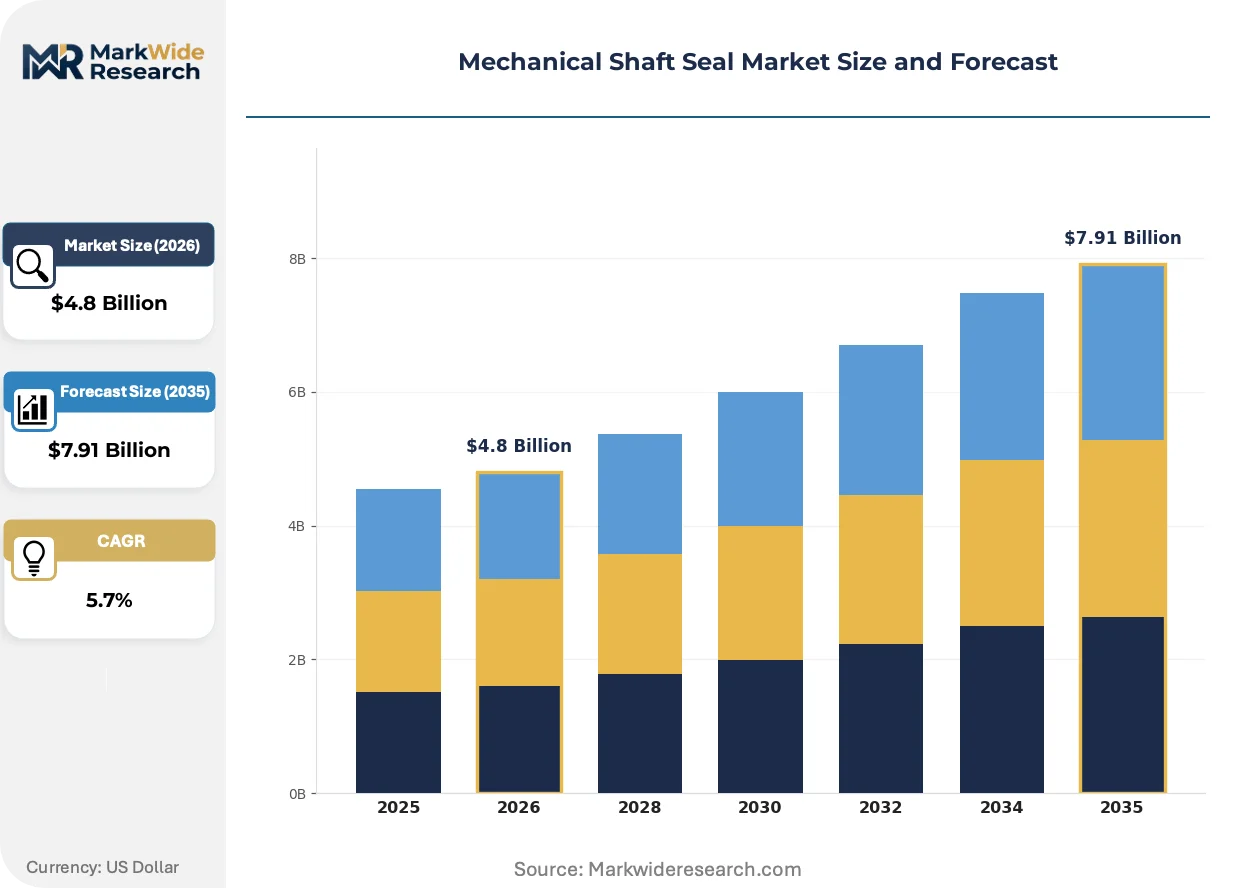
Market Dynamics
Gas seal technology is converging with digital condition-monitoring systems to displace conventional liquid-lubricated designs in centrifugal compressors, while REACH and API 682 tightening force material requalification cycles that compress supplier margins and consolidate procurement authority among integrated energy majors.
Growth Catalysts
- Emissions reduction mandates:EPA leak detection protocols in US petroleum refining operations mandate seal performance thresholds that accelerate replacement cycles for legacy designs.
- China infrastructure expansion:Petrochemical and power generation buildouts concentrate demand for cartridge seal configurations that reduce field installation errors.
- API 682 digital compatibility:The standard's evolving lifecycle carbon accounting requirements pull investment toward sensor-integrated seal systems.
Market Restraints
- Tungsten carbide supply concentration:Sintered hardmetal sourcing clusters in specific manufacturing regions create input cost volatility for seal face production.
- REACH fluoropolymer constraints:ECHA restrictions on perfluorinated elastomer compounds force reformulation of high-temperature seal grades for European chemical manufacturers.
- Metal bellows fabrication limits:Specialized welding and heat-treatment capabilities for high-alloy reactor seals concentrate among limited qualified suppliers.
Strategic Opportunities
- India petrochemical buildout:Reliance Industries and public-sector refiners expand capacity under PLI scheme incentives, creating greenfield seal specification windows.
- Hydrogen service sealing:Emerging electrolyzer and ammonia synthesis applications require material qualification for embrittlement-resistant metal bellows designs.
- Aftermarket service unbundling:Integrated majors are separating seal procurement from installation and predictive maintenance contracts, opening channel entry points.
Industry Challenges
- Cross-functional engineering talent scarcity:Seal design now requires tribology, materials science, and IoT integration expertise that outpaces vocational training pipelines.
- ISO 21049 certification timelines:Third-party qualification for high-pressure high-temperature service ratings extends product launch cycles by 12-18 months.
- Legacy pump retrofit integration:Cartridge seal conversions of aged ANSI and API process pumps encounter housing tolerance stack-up issues that complicate field installation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Shaft Seal Market Trends and Innovations
Active materials innovation and regulatory material restrictions are reshaping seal engineering priorities. Digital integration requirements in updated industry standards compress development timelines while opening service revenue streams.
Silicon carbide composite face technology is converging with thin-film diamond-like carbon coatings to extend dry-running tolerance in gas seal applications. Centrifugal compressor operators in North American gas processing facilities adopt these configurations ahead of scheduled maintenance turnarounds. The convergence is compressing acceptable leakage thresholds and forcing liquid-lubricated seal incumbents to reposition toward auxiliary systems.
EU F-Gas Regulation phase-down schedules constrain hydrofluorocarbon elastomer curing agents used in high-temperature seal grades. European chemical manufacturers now face supply discontinuities for legacy fluoroelastomer compounds that previously served reactor service. Seal suppliers are accelerating hydrogenated nitrile and perfluoroether material qualifications to maintain European refinery contract positions.
Integrated energy majors are consolidating rotating equipment procurement through preferred supplier programs that bundle seals, bearings, and condition-monitoring hardware. Equipment distributors and local seal rebuild shops lose specification influence as central engineering teams standardize on pre-engineered cartridge configurations. This concentration is most visible in US Gulf Coast and Rotterdam-Antwerp refining clusters where operator mergers have compressed vendor lists.
Mechanical Shaft Seal Market Segmentation
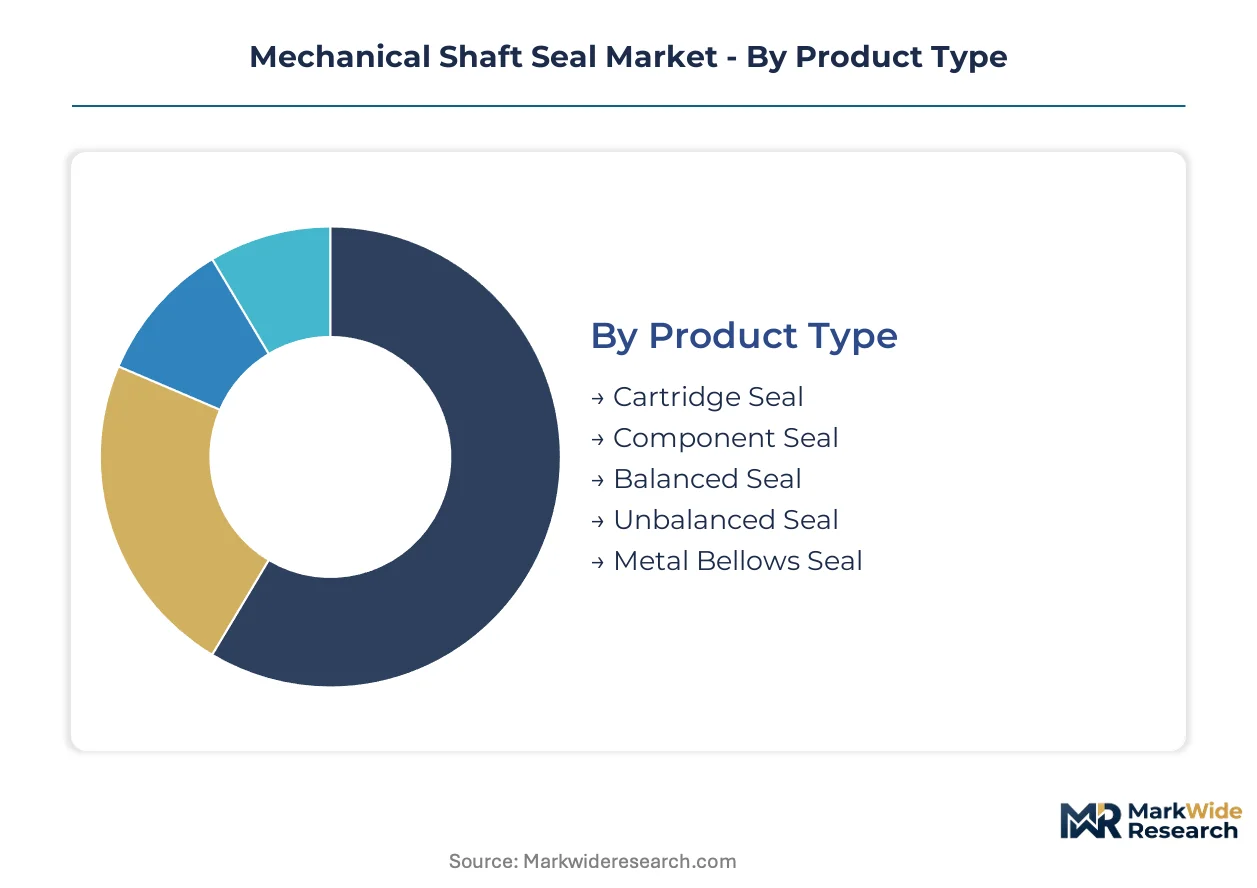
Mechanical shaft seal segmentation reflects divergent engineering requirements across pressure ratings, temperature extremes, and fluid chemistries. Procurement patterns vary sharply between maintenance-led replacement cycles and greenfield specification windows.
Product Type:
Technology and specification axes dominate buyer evaluation, with pre-assembled configurations commanding premium positioning against field-rebuild alternatives.
- Cartridge Seal:Factory-assembled unit integrating sleeve, seal faces, and springs into a single replaceable cartridge. Demand concentrates in China petrochemical buildouts where installation error reduction outweighs unit cost premiums. REACH compliance timelines accelerate specification shifts toward pre-qualified cartridge suppliers.
- Component Seal:Discrete parts requiring field assembly and face lapping. Legacy refinery maintenance programs in the US Gulf Coast sustain procurement volumes despite longer installation times. EPA leak detection mandates compress acceptable rebuild intervals, eroding cost advantages.
- Balanced Seal:Hydraulic pressure balancing reduces face loading for high-pressure service. Hydrocarbon processing applications specify these for pipeline pump stations above 1500 psi operating pressure.
- Unbalanced Seal:Simpler geometry suited to low-pressure water and light hydrocarbon duties. Municipal water treatment infrastructure drives steady replacement demand.
- Metal Bellows Seal:Welded metal bellows replace springs and O-rings for extreme temperature cycling. High-temperature reactor service in European chemical manufacturing requires specialized Inconel or Hastelloy bellows fabrication.
Cartridge Seal leads on scale; Metal Bellows Seal leads on momentum.
Technology:
Cost tier differentiation separates commodity elastomeric designs from engineered gas seal systems with integrated condition monitoring.
- Elastomeric:Nitrile, fluoroelastomer, and perfluoroether O-ring secondary seals dominate general-purpose pump applications. EU F-Gas Regulation phase-downs force material reformulation for European refinery contracts.
- Mechanical:Spring-loaded face contact designs remain the volume baseline across ANSI and API process pumps. Component standardization sustains price competition among distributors.
- Gas Seal:Dry-running face technology with lift-off geometry eliminates liquid barrier fluid systems. North American gas processing facilities adopt these ahead of emissions compliance deadlines, displacing liquid-lubricated alternatives fastest.
- Magnetic:Permanent magnet face loading eliminates springs for ultra-clean pharmaceutical and semiconductor fluid handling. Niche positioning limits volume despite premium pricing.
- Hydrodynamic:Spiral groove or Rayleigh step face patterns generate self-acting lift for high-speed compressor duty. API 682 compliance testing extends qualification timelines.
Mechanical technology anchors volume; Gas Seal technology captures the steepest expansion trajectory.
Application:
Application segmentation tracks rotating equipment duty cycles and criticality tiers in process plant hierarchies.
- Pumps:Centrifugal and positive displacement pumps represent the installed base majority. Chemical manufacturers specify cartridge conversions for ANSI process pumps during planned turnarounds.
- Compressors:Centrifugal gas compressors drive gas seal adoption for seal oil elimination. Power generation combined-cycle units prioritize dry gas seal reliability for availability guarantees.
- Mixers:Top-entry and side-entry agitators in blending tanks require extended shaft sealing runs. Specialty metal bellows designs address runout tolerance challenges.
- Agitators:Reactor vessel agitation combines pressure, temperature, and solids exposure. Polymerization reactor service demands hardened face materials against abrasive catalyst residues.
- Reactors:High-pressure high-temperature synthesis loops specify engineered metal bellows with dual seal arrangements. ISO 21049 certification requirements concentrate qualified supply.
Pumps dominate unit volume; Compressors drive technology substitution.
End User Industry:
Customer type segmentation reveals divergent procurement authority structures and specification influence patterns.
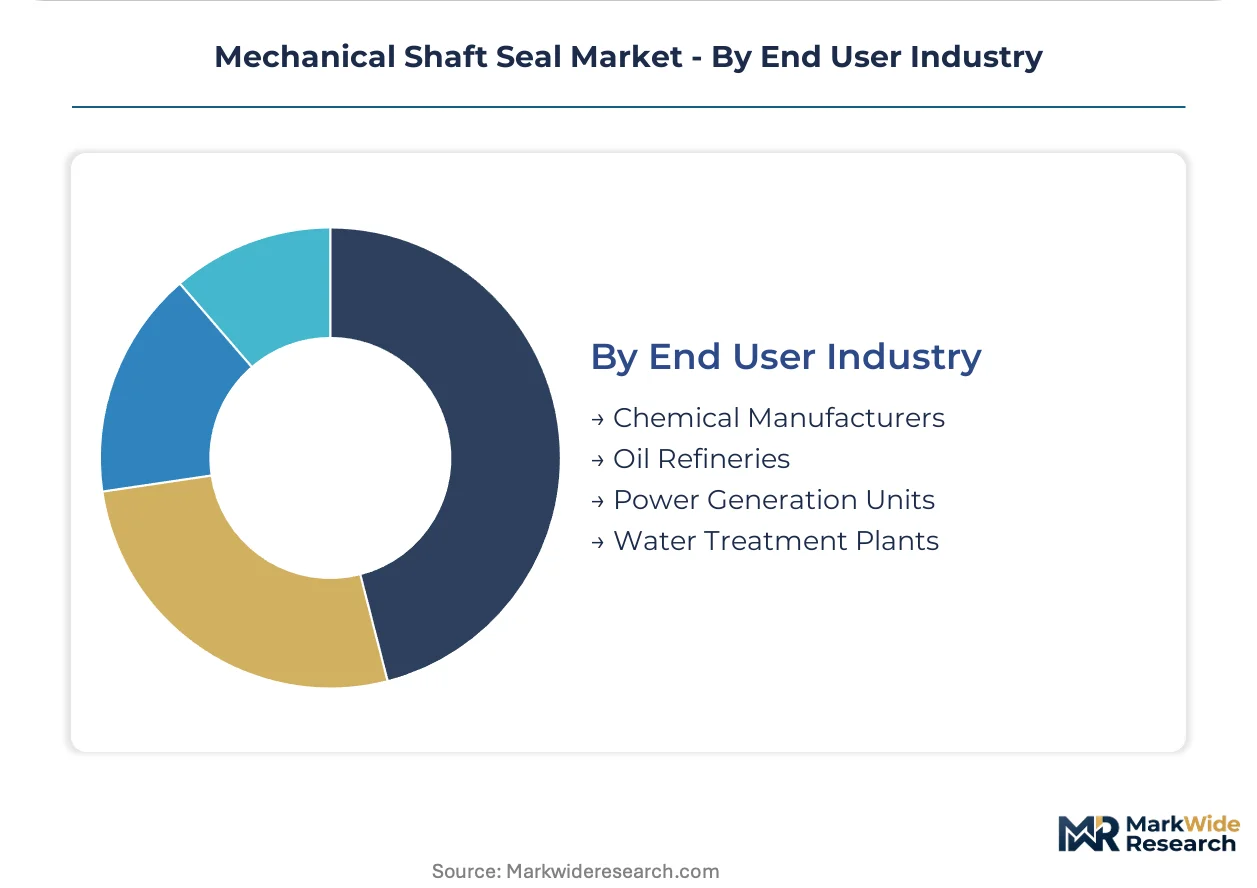
- Chemical Manufacturers:Integrated majors centralize rotating equipment procurement through preferred supplier programs. REACH material constraints force active supplier requalification for European production assets.
- Oil Refineries:Complexity and safety criticality sustain premium pricing for API 682 compliant designs. US Gulf Coast and Rotterdam-Antwerp clusters consolidate vendor lists through operator mergers.
- Power Generation Units:Combined-cycle gas turbines and nuclear cooling water systems specify for reliability-centered maintenance. Gas seal retrofits align with emissions reduction mandates.
- Water Treatment Plants:Municipal and industrial water infrastructure prioritizes lifecycle cost over initial purchase price. Component seal rebuild programs persist despite cartridge availability.
Oil Refineries anchor revenue concentration; Chemical Manufacturers drive specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians and tribology engineers concentrate in industrial corridors where petrochemical and power generation infrastructure demands precision sealing solutions. Their geographic clustering shapes regional supply capabilities and service response times.
United States
Gulf Coast refinery operators consolidate vendor lists through preferred supplier programs that bundle seals with predictive maintenance contracts. EPA leak detection and repair protocols mandate seal performance thresholds that accelerate replacement cycles for legacy liquid-lubricated designs. The Houston-Beaumont-Port Arthur corridor anchors North American demand as integrated majors centralize procurement authority.
Germany
REACH compliance timelines and EU F-Gas Regulation phase-downs force active supplier requalification for chemical manufacturing assets. ECHA restrictions on perfluorinated elastomer compounds compress material choices for high-temperature reactor service. The Ludwigshafen-Cologne industrial cluster concentrates metal bellows fabrication expertise for extreme temperature cycling applications.
China
Petrochemical and power generation buildouts under dual carbon goals concentrate demand for cartridge seal configurations that reduce field installation errors. MEE emissions standards tighten leakage thresholds for rotating equipment in refinery and chemical park expansions. The Ningbo-Zhoushan and Dalian industrial zones drive specification windows for pre-assembled seal systems.
India
Reliance Industries and public-sector refiners expand capacity under PLI scheme incentives, creating greenfield seal specification opportunities. BIS standards for pressure equipment increasingly reference API 682 compliance for imported rotating machinery. The Gujarat refining corridor and Maharashtra chemical zones anchor subcontinent demand concentration.
Saudi Arabia
Downstream petrochemical integration projects under Vision 2030 specify engineered seals for high-pressure synthesis loops and gas processing trains. The country's national standards body aligns pressure equipment regulations with API and ISO specifications for international contractor compatibility. The Jubail and Yanbu industrial cities concentrate demand for API 682 compliant designs in new buildouts.
Mechanical Shaft Seal Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale advantages clash with engineering depth. The market consolidates around integrated energy majors' preferred supplier programs that compress vendor lists in refining clusters. Three archetypes dominate: diversified industrial conglomerates with rotating equipment portfolios, specialized seal engineering houses with metal bellows expertise, and regional service-focused distributors. Competitive moves center on aftermarket service network expansion and strategic partnerships for digital condition-monitoring integration.
Among diversified industrial groups, Flowserve Corporation and SKF occupy positions spanning seals, bearings, and fluid control equipment that align with integrated procurement trends. John Crane and EagleBurgmann exemplify the engineering-intensive tier, anchoring specialized expertise in high-temperature reactor applications and gas seal technology. These named entities represent competitive archetypes rather than exhaustive market coverage, with their positioning reflecting the tension between breadth and depth in customer engagement models.
| Leading Market Players |
|---|
| John Crane |
| EagleBurgmann |
| Flowserve Corporation |
| A.W. Chesterton Company |
| AESSEAL |
| SKF |
| Freudenberg Sealing Technologies |
| Garlock |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Integrated energy majors centralizing procurement through preferred supplier programs have compressed vendor lists and shifted pricing power toward bundled service contracts over transactional component sales. This buyer concentration rewards seal manufacturers with aftermarket service networks while eroding distributor margins on standalone hardware.
Pricing Analysis
Bundled service contracts versus unbundled component procurement now defines the pricing landscape. Three-tier pricing structure across API 682 certified premium, standard cartridge, and economy component levels reflects certification grade and installation complexity. Cost compression in economy component tiers is intensifying because EPA leak detection mandates accelerate replacement cycles. Municipal water treatment plants exhibit highest price sensitivity due to lifecycle cost prioritization, while oil refineries accept premium positioning for reliability-centered maintenance guarantees.
Supply Chain Analysis
Single-source vulnerability sits with tungsten carbide sintered hardmetal feedstock concentrated in China and Germany. Silicon carbide composite faces and Inconel metal bellows assemblies draw from Japanese and American specialty ceramics foundries. Regulatory restriction through REACH fluoropolymer phase-downs threatens European supply continuity for high-temperature elastomer grades. Distribution runs through OEM-authorized service centers and direct millwright contracting channels, bypassing traditional industrial distributors in consolidated refining clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mechanical shaft seal market functions as a stable compounder anchored by emissions compliance mandates that institutionalize replacement cycles regardless of commodity cycles.
For Market Incumbents: Anticipate gas seal technology displacement of liquid-lubricated designs by accelerating sensor-integrated condition-monitoring development. Secure backward integration into silicon carbide face manufacturing to defend margin position against specialty ceramics suppliers. ISO 21049 certification investment creates switching costs that protect long-term refinery contracts. For New Entrants and Emerging Players: Capture hydrogen service sealing white space in electrolyzer and ammonia synthesis applications where material qualification gaps persist. India's petrochemical buildout under PLI scheme incentives offers the most penetrable geography for greenfield specification windows. Partner with regional EPC contractors for pre-qualification on rotating equipment packages rather than competing for direct seal procurement. For Investors and Strategic Acquirers: Diversified industrial conglomerates with rotating equipment portfolios are the most active acquirer in this space, seeking seal engineering capabilities to complete bundled offerings. Five-to-ten year viability rests on digital condition-monitoring integration depth rather than commodity hardware scale. Watch API 682 revision timelines incorporating lifecycle carbon accounting as the signal for technology inflection and acquisition premium justification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide | Captive supply of seal face material reduces exposure to sintered hardmetal price volatility from Chinese suppliers. |
| Gas Seal Technology Licensing | Dry-running compressor seal patents from John Crane and EagleBurgmann command premium positioning in North American gas processing. |
| Aftermarket Service Network Expansion | Millwright staffing in Houston-Beaumont-Port Arthur corridor shortens response times for integrated major turnaround contracts. |
| ISO 21049 Certification Investment | Third-party qualification for high-pressure high-temperature ratings extends product launch cycles but creates competitor exclusion. |
| Joint Venture for Indian Manufacturing | Local assembly in Gujarat refining corridor satisfies BIS pressure equipment standards for Reliance Industries procurement. |
Research Methodology
Multiple input streams — maintenance director interviews at US Gulf Coast refineries, procurement lead discussions at European chemical manufacturers, and aftermarket service head conversations — were reconciled against secondary validation. Plant engineers, OEM procurement teams, and distribution channel partners provided operational perspective. SEC 10-K filings, customs trade data, and API standards documentation supplied quantitative grounding. Bottom-up unit demand estimates and top-down industry spend analysis were cross-referenced for convergence.
Historical shipment patterns were cross-referenced against expert panel input to anchor projection assumptions across the analysis window. Segmentation modeling incorporated product type, technology tier, application criticality, and end-user industry procurement authority structure. CAGRs were derived from fitted growth curves applied to replacement cycle frequencies and greenfield capital expenditure trajectories. Hydrogen service material qualification timelines and REACH compliance phase-down schedules entered as scenario variables.
Regulatory enforcement intensity, raw material supply disruption, and integrated major merger activity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about replacement cycle acceleration and technology substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.