
 Europe Electro Hydraulic Servo Valve Market | 2026-2036
Europe Electro Hydraulic Servo Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electro Hydraulic Servo Valve Market Foresight
German hydraulic component producers is rebalancing capacity toward electro-hydraulic architectures as industrial automation accelerates across Central Europe. Bosch Rexroth leverages its Stuttgart engineering base to dominate high-response servo valve production for machine tool builders. Moog sustains aerospace-grade manufacturing precision for flight control systems supplied to Airbus and Safran. Parker Hannifin anchors its European servo valve portfolio through specialized distribution channels serving automotive OEMs in Bavaria and Baden-Württemberg.
An electro hydraulic servo valve converts low-power electrical signals into precise hydraulic flow and pressure modulation, typically achieving response times below 5 milliseconds with port diameters ranging from 4 mm to 32 mm for closed-loop position or force control in dynamic machinery. Proportional valve architectures now lead unit volume across European industrial automation installations due to their cost-efficiency in mid-precision positioning tasks. Servo controlled variants command premium positioning in aerospace and robotics applications where sub-micron accuracy justifies higher system expenditure. Direct control configurations occupy mature demand pockets within legacy marine hydraulics and conventional manufacturing equipment.
The EU Machinery Directive and CE marking requirements shape product certification pathways for valve manufacturers selling into European industrial supply chains. REACH compliance and RoHS substance restrictions constrain seal material selections and electrical connector specifications across the supplier base. EMA safety standards influence aerospace servo valve qualification protocols for European airframe programs. Stakeholders must monitor evolving CSRD disclosure obligations and EU Green Deal carbon intensity benchmarks as these frameworks begin penetrating Tier 2 hydraulic component procurement criteria.
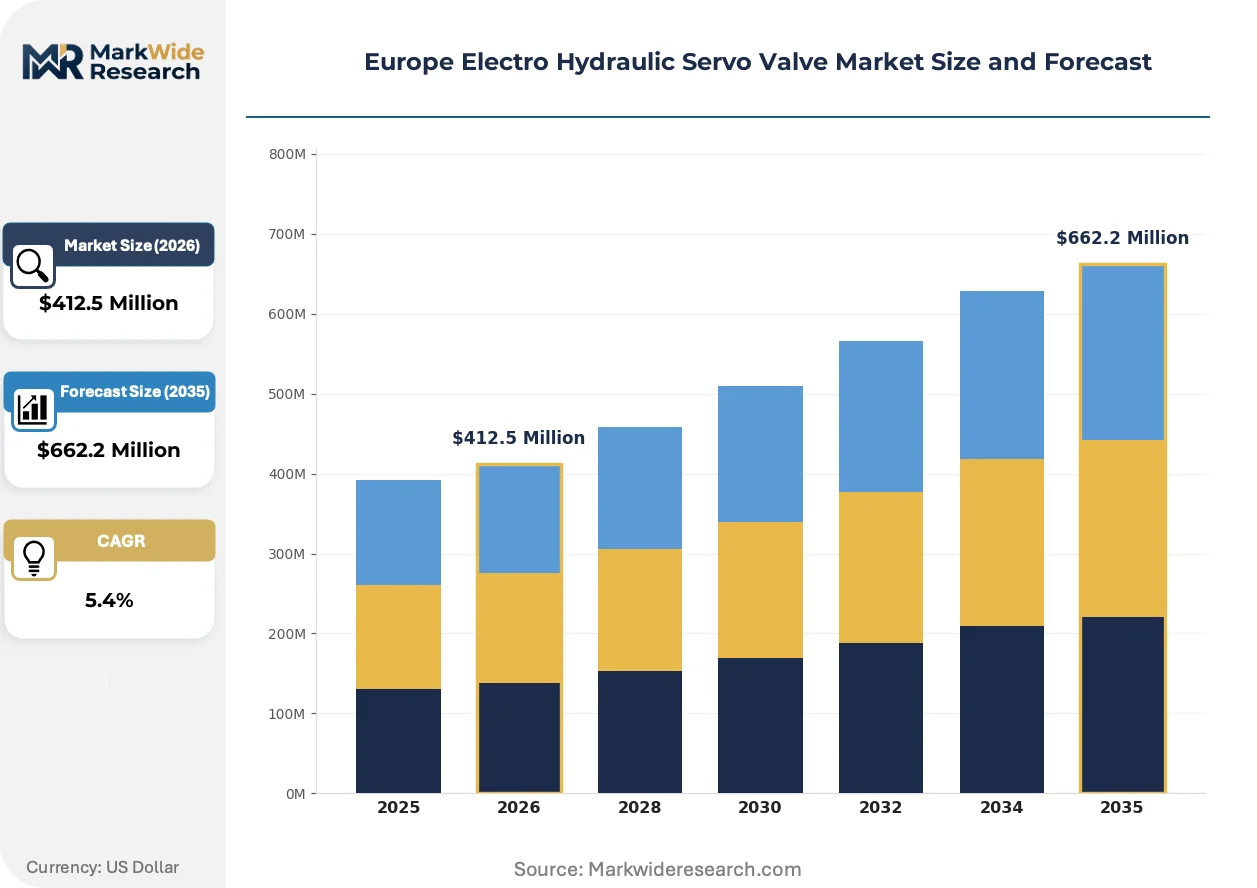
Market Dynamics
German aerospace procurement of precision hydraulic actuation systems is compressing supplier lead times while tightening qualification protocols. This demand concentration from Airbus and Safran programs is restructuring capacity allocation across Central European fluid power manufacturers.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbon fluids are accelerating retrofit demand for compatible servo valve architectures in industrial refrigeration and mobile hydraulics.
- Machine tool builders:Stuttgart-area automation integrators are specifying high-response electro-hydraulic valves for five-axis machining centers serving automotive powertrain production.
- Aerospace qualification protocols:EMA safety standards for European airframe programs are locking in multi-year supplier relationships with certified valve manufacturers.
Market Restraints
- Rare earth magnet supply:Torque motor assemblies depend on neodymium-iron-boron magnets concentrated in Chinese processing facilities, exposing European valve assemblers to price volatility and export restriction risk.
- REACH substance restrictions:Candidate list expansions for phthalate plasticizers and bisphenol derivatives are forcing seal compound reformulations with 18-24 month validation cycles.
- Proportional valve substitution:Cost-sensitive packaging machinery OEMs in Northern Italy are migrating to closed-loop proportional architectures for mid-precision positioning tasks.
Strategic Opportunities
- Polish industrial automation:Manufacturing investment in Lower Silesian automotive supplier parks is creating greenfield demand for servo-controlled press and injection molding systems.
- EU Green Deal carbon benchmarks:Tier 2 procurement criteria emerging from CSRD disclosure obligations are favoring suppliers with verified lifecycle emissions data for hydraulic components.
- Digital twin integration:Convergence of servo valve position feedback with edge computing platforms is enabling predictive maintenance contracts for wind turbine pitch control systems.
Industry Challenges
- Fluoropolymer seal expertise:Compound formulation chemists with aerospace qualification experience are concentrated at a handful of German and Swiss suppliers, constraining capacity expansion.
- Legacy marine hydraulics integration:Shipyard retrofit projects in Mediterranean ports require custom manifold adaptations to interface with 1970s-era piping standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electro Hydraulic Servo Valve Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Control, Servo Controlled, Proportional, Control Valve Application: Aerospace, Robotics, Industrial Automation, Marine End User: Manufacturing, Automotive OEMs, Construction, Oil & Gas Technology: Hydraulic, Electro-Mechanical, Electronic, Pneumatic |
| Companies Covered | Bosch Rexroth, Moog, Parker Hannifin, Atos, Danfoss, Voith, HAWE Hydraulik, Duplomatic Oleodinamica, Eaton, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electro Hydraulic Servo Valve Market Shifts & Advancements
Electro-hydraulic architectures are fragmenting into performance-tiered product families as end-use precision requirements diverge. This specialization is compressing development cycles while expanding the addressable application base beyond traditional aerospace and machine tool strongholds.
Direct drive valve technology is overtaking conventional nozzle-flapper architectures in next-generation flight control systems. Airbus Tier 1 suppliers are qualifying torque motor-free designs for primary surface actuation on narrow-body programs. This displacement is reducing parts count by 40% while eliminating hydraulic pilot stage contamination sensitivity.
EU Machinery Directive updates are mandating functional safety certification for servo valves deployed in collaborative robot workcells. German automation integrators in Bavaria are now requiring SIL 2 or PL d ratings for hydraulic axes operating near human workers. This regulatory compression is filtering valve suppliers unable to demonstrate MTTFd calculations and diagnostic coverage metrics.
Buyer concentration among automotive powertrain OEMs is compressing supplier negotiation cycles from annual to quarterly intervals. Tier 1 hydraulics distributors serving Stuttgart and Munich industrial clusters are unbundling engineering support from component supply to defend margin structures. This service separation is most visible in Baden-Württemberg, where machine tool builders now contract servo valve tuning separately from hardware procurement.
Europe Electro Hydraulic Servo Valve Market Segmentation
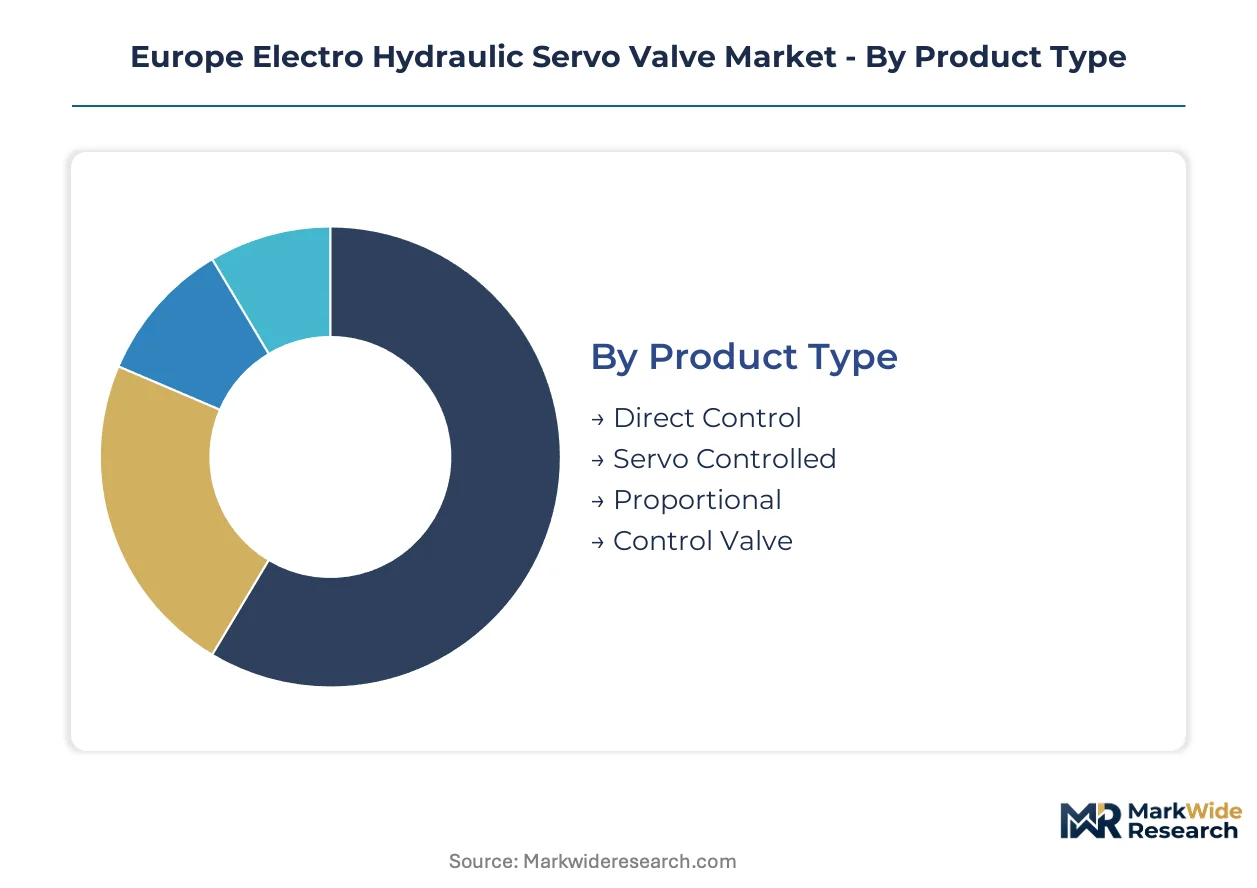
Electro hydraulic servo valve procurement in Europe fragments across performance tiers, end-use precision requirements, and certification burdens. Capital deployment and qualification timelines vary dramatically by segment, reshaping supplier portfolio strategies across German industrial clusters.
Product Type:
Capital intensity peaks in servo-controlled architectures requiring aerospace-grade torque motor assemblies and multi-stage qualification protocols.
- Servo Controlled:Multi-stage nozzle-flapper designs achieve sub-5 millisecond response times with aerospace-grade precision. Airbus and Safran programs in Toulouse and Hamburg concentrate demand, though direct drive displacement is compressing long-term growth trajectories.
- Proportional:Closed-loop spool configurations balance cost against positioning accuracy for mid-precision industrial tasks. Stuttgart-area machine tool builders specify these for automotive powertrain machining centers, driving volume concentration in Baden-Württemberg.
- Direct Control:Single-stage architectures dominate legacy marine installations and mature manufacturing equipment with minimal electronics.
- Control Valve:General-purpose pressure and flow regulation serves auxiliary hydraulic circuits across industrial infrastructure.
Proportional architectures absorb the bulk of installed capacity; servo-controlled variants are expanding most quickly in aerospace qualification pipelines.
Application:
Customer concentration patterns diverge sharply, with aerospace procurement consolidating around Airbus Tier 1 suppliers while industrial automation fragments across integrator networks.
- Aerospace:Flight control surface actuation demands EMA-certified architectures with traceable material pedigree. Hamburg and Toulouse assembly lines lock in multi-year supplier relationships through qualification protocols.
- Industrial Automation:Five-axis machining centers and press systems in Bavarian automotive supplier parks specify SIL-rated valves for collaborative robot workcells.
- Robotics:Cobot hydraulic axes require functional safety certification under updated EU Machinery Directive mandates.
- Marine:Mediterranean shipyard retrofits interface with 1970s-era piping through custom manifold adaptations.
Industrial automation anchors current revenue concentration; aerospace applications command the steepest expansion trajectory through narrow-body program ramp-ups.
End User:
Procurement sophistication stratifies by sector, with automotive OEMs imposing quarterly negotiation cycles and construction buyers tolerating longer lead times.
- Automotive OEMs:Powertrain machining demand from Stuttgart and Munich clusters compresses supplier margins through volume concentration and unbundled engineering contracts.
- Manufacturing:General machinery builders across Northern Italy and Poland prioritize cost-efficient proportional architectures for packaging and assembly equipment.
- Construction:Mobile hydraulics in German and Austrian equipment fleets face F-Gas Regulation retrofit timelines for compatible fluid architectures.
- Oil & Gas:North Sea maintenance programs and Eastern European pipeline infrastructure sustain demand for high-pressure rated configurations.
Automotive OEMs dominate premium segment procurement; manufacturing end users are gaining share fastest through Polish greenfield investments.
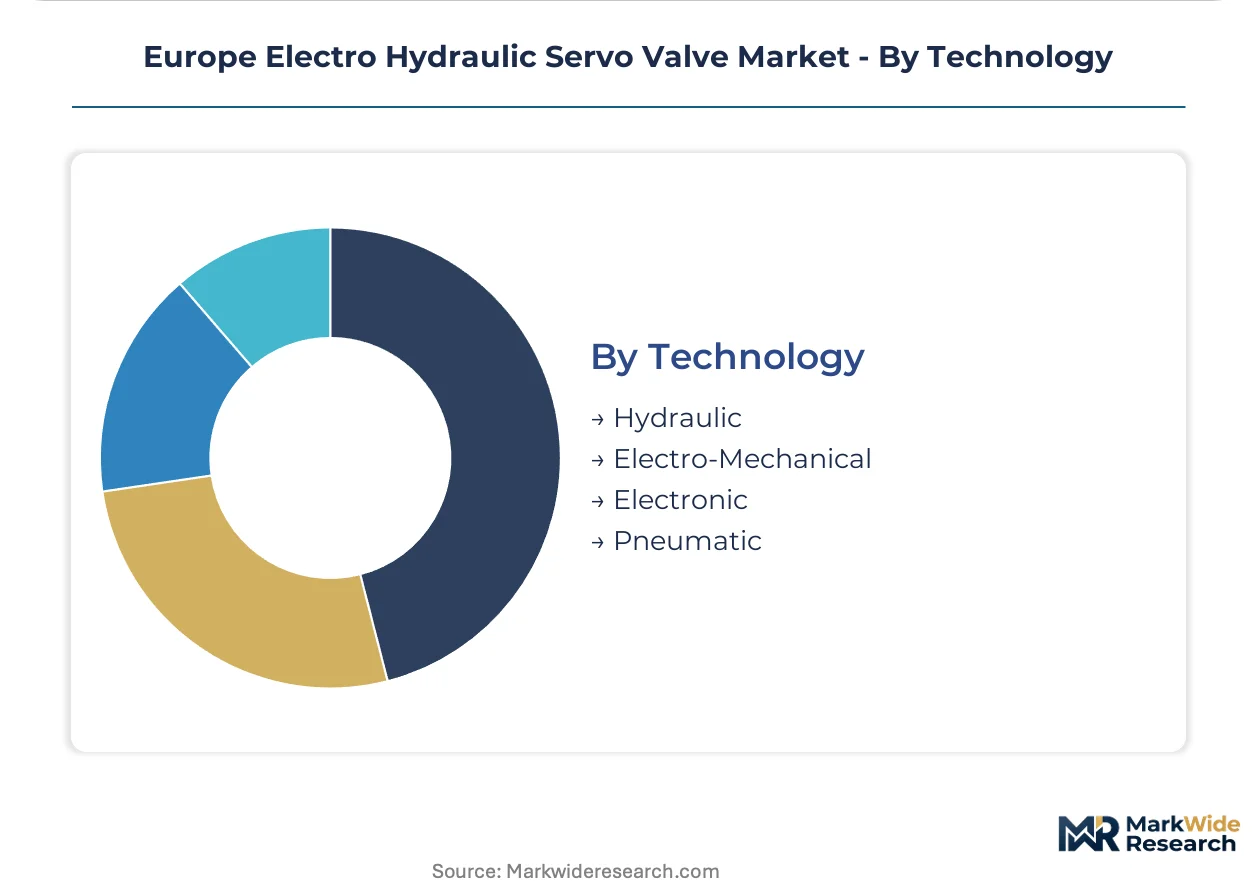
Technology:
Hybrid architectures are displacing pure hydraulic designs as electrification penetrates fluid power systems.
- Hydraulic:Conventional oil-based actuation retains installed base dominance in heavy machinery and marine applications.
- Electro-Mechanical:Servo motor and ball screw combinations compete for precision positioning tasks in cleanroom-sensitive environments.
- Electronic:Digital valve control with embedded position feedback enables predictive maintenance integration for wind turbine pitch systems.
- Pneumatic:Compressed air alternatives serve low-force, high-speed applications in food packaging and textile machinery.
Hydraulic technology retains the largest installed base; electronic control architectures are climbing the fastest through digital twin integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium-iron-boron magnet processing in Chinese facilities feeds European torque motor assembly lines. REACH substance restrictions and EU F-Gas Regulation phase-down schedules are compressing supplier qualification timelines across continental fluid power networks.
Germany
Baden-Württemberg and Bavaria host concentrated aerospace and automotive machining demand. The EU Machinery Directive and CE marking requirements shape product certification pathways for Stuttgart-area valve manufacturers. Bosch Rexroth anchors high-response servo valve production from its Stuttgart engineering base for machine tool builders.
France
Airbus assembly lines in Toulouse and Safran programs drive precision hydraulic actuation procurement. EMA safety standards influence aerospace servo valve qualification protocols for European airframe programs. Toulouse-area Tier 1 suppliers are locking in multi-year relationships through tightened qualification protocols.
Italy
Northern Italian packaging machinery OEMs are migrating to closed-loop proportional architectures for mid-precision positioning tasks. REACH candidate list expansions for phthalate plasticizers force seal compound reformulations with extended validation cycles. Emilia-Romagna industrial clusters concentrate cost-sensitive automation equipment demand.
Poland
Lower Silesian automotive supplier parks are creating greenfield demand for servo-controlled press and injection molding systems. EU Green Deal carbon intensity benchmarks are beginning to penetrate Tier 2 hydraulic component procurement criteria. Manufacturing investment in Wrocław-area industrial zones is accelerating fluid power system deployment.
United Kingdom
North Sea oil and gas maintenance programs sustain demand for high-pressure rated valve configurations. CSRD disclosure obligations are emerging as procurement criteria for hydraulic component suppliers serving infrastructure projects. Aberdeen-area energy service companies specify corrosion-resistant architectures for offshore platform retrofits.
Europe Electro Hydraulic Servo Valve Market Competitive Landscape
Global majors compete with regional champions across certification depth and application specialization. The vendor base stratifies into three tiers: aerospace-qualified precision specialists, industrial automation volume suppliers, and diversified fluid power conglomerates. Dominant competitive moves include strategic partnerships with machine tool builders and capacity rebalancing toward electro-hydraulic architectures.
Among Germany-based precision manufacturers, Bosch Rexroth and HAWE Hydraulik occupy positions within the high-response industrial tier. Moog exemplifies aerospace-grade manufacturing archetypes with sustained qualification protocols for flight control systems. Parker Hannifin anchors diversified portfolio positioning through specialized distribution channels serving automotive OEM clusters.
| Leading Market Players |
|---|
| Bosch Rexroth |
| Moog |
| Parker Hannifin |
| Atos |
| Danfoss |
| Voith |
| HAWE Hydraulik |
| Duplomatic Oleodinamica |
| Eaton |
| Others |
Supply & Pricing Matrix
Neodymium-iron-boron magnet costs cascade through European torque motor assembly lines into three distinct pricing tiers for servo valve procurement. REACH compliance validation cycles and rare earth price volatility compress margins at the component sourcing stage while aerospace qualification protocols sustain premium positioning for flight control architectures.
Pricing Analysis
Warranty and engineering support unbundling now separates hardware procurement from servo valve tuning contracts in Baden-Württemberg machine tool clusters. Three-tier pricing structure across premium, standard, and economy levels reflects EMA certification grade, volume scale, and after-sales service inclusion. Cost compression in mid-precision proportional architectures intensifies because Northern Italian packaging OEMs migrate to closed-loop alternatives. Automotive powertrain buyers exhibit highest price sensitivity through quarterly renegotiation cycles, while Airbus Tier 1 suppliers tolerate premium positioning for traceable material pedigree.
Supply Chain Analysis
Freight cost escalation from Chinese rare earth processing facilities to German torque motor assemblers amplifies working capital requirements across the supplier base. Manufacturing concentrates in Germany, France, and Switzerland for aerospace-grade qualification; China dominates upstream magnet feedstock. Seal compound formulation draws from fluoropolymer expertise concentrated at German and Swiss specialty chemical suppliers. Single-source vulnerability in neodymium processing exposes European valve assemblers to export restriction risk. Distribution runs through specialized fluid power distributors serving Stuttgart and Munich industrial clusters with unbundled technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
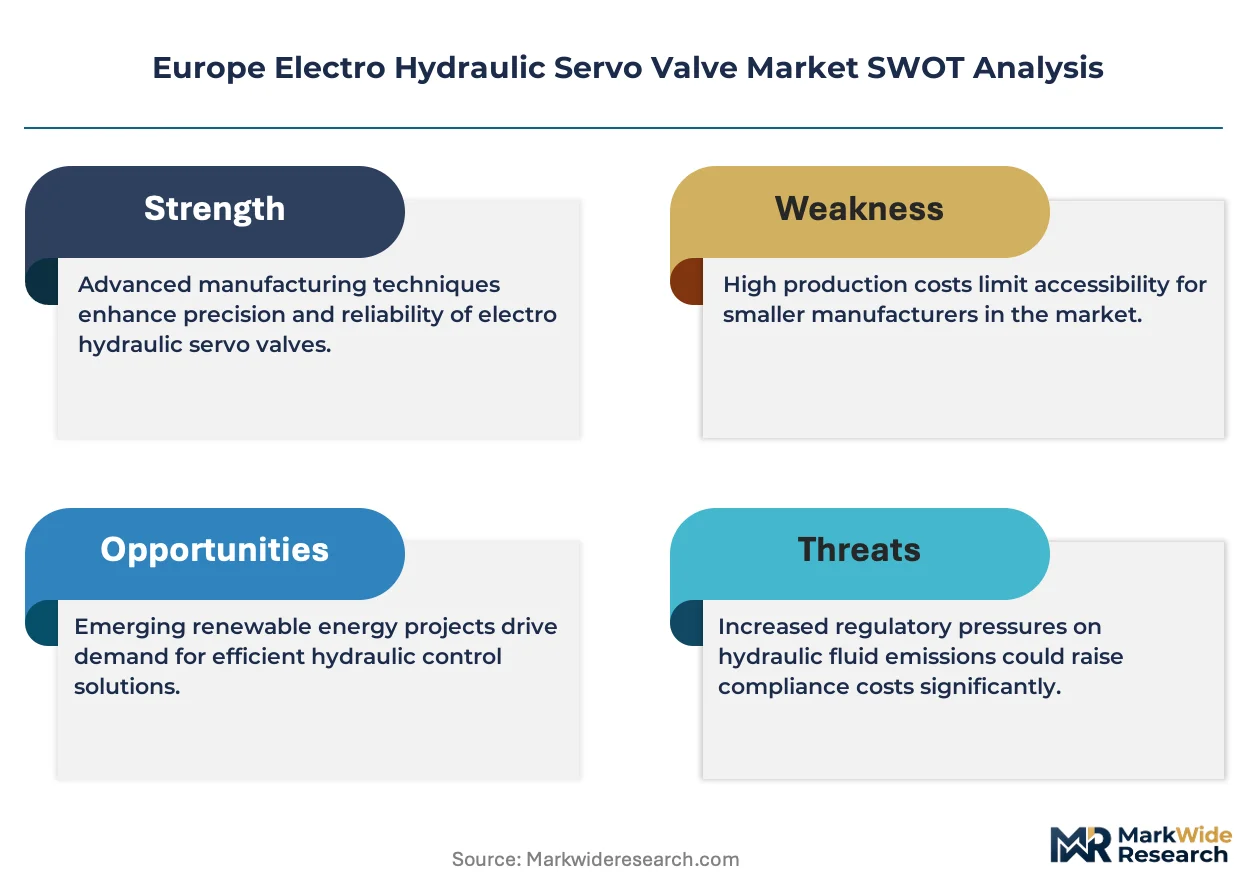
Fluoropolymer seal compound expertise scarcity props pricing power for qualified suppliers while constraining capacity expansion across European servo valve manufacturing. This bottleneck sustains margin structures for incumbent precision specialists.
For Market Incumbents: Hedge against direct drive valve displacement by accelerating torque motor-free architecture qualification with Airbus Tier 1 suppliers. Capture backward integration into seal compound formulation to reduce REACH validation cycle exposure. Channel control through exclusive distributor relationships in Bavarian automotive clusters defends against unbundled engineering service competition. For New Entrants and Emerging Players: The price-point gap between EMA-certified aerospace architectures and standard industrial proportional valves creates entry space for mid-tier performance positioning. Polish Lower Silesian automotive supplier parks offer the most penetrable geography for greenfield servo-controlled press system deployment. A go-to-market angle anchored in EU Green Deal carbon intensity benchmarking addresses emerging Tier 2 procurement criteria. For Investors and Strategic Acquirers: Direct drive valve qualification announcements from Hamburg-area Tier 1 suppliers are the leading indicator that nozzle-flapper architecture demand trajectories are shifting. Long-term viability favors vertically integrated specialists with captive seal formulation capability and established EMA certification pathways. The signal to monitor is Airbus narrow-body program supplier list updates reflecting torque motor-free design adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Formulation | REACH compliance cycles shorten from 18-24 months through captive fluoropolymer expertise. |
| Direct Drive Valve Qualification | Airbus Tier 1 supplier relationships lock in multi-year revenue through EMA-certified architectures. |
| Digital Twin Platform Integration | Edge computing convergence enables predictive maintenance contracts for wind turbine pitch control. |
| Polish Manufacturing Footprint Expansion | Lower Silesian automotive clusters generate greenfield demand for servo-controlled press systems. |
| Carbon Intensity Certification Investment | CSRD disclosure obligations penetrate Tier 2 procurement criteria for hydraulic components. |
Research Methodology
Document review covered EMA safety standards documentation, EU F-Gas Regulation phase-down schedules, and REACH candidate list expansions, complemented by interviews with fluid power distribution channel heads, aerospace procurement managers at Airbus Tier 1 suppliers, machine tool builder engineering directors, and seal compound formulation specialists. Secondary validation drew from SEC filings of listed fluid power conglomerates, German engineering association VDMA sector reports, and customs trade data for hydraulic component flows. Bottom-up installation base estimates triangulated against top-down OEM procurement disclosures.
Segment-level value outputs were derived through product-type, application, and end-user dimensional modeling across the projection horizon. CAGRs were computed from annualized growth rate convergence between historical trajectory analysis and forward-looking qualification pipeline assessment. Forecast inputs incorporated EU Machinery Directive SIL rating adoption curves and F-Gas Regulation retrofit demand timing.
Inputs from aerospace procurement managers and seal compound suppliers were available through the study window; gaps in direct drive valve commercialization timelines introduce uncertainty bands around nozzle-flapper displacement assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Safety Valve Test Benches Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Emergency Venting System Market
Valves
Steam Safety Valve Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Global Stainless Steel Control Valves Market
Valves
Oil Drain Valves Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Lined Valves Market
Valves
Pipeline Pigging System Market
Valves
Steam Trap Market
Valves
Global Valves in Chemical Market
Valves
Three Way Ball Valve Market
Valves
Backflow Preventers Market
Valves
Fluid Power Cylinder Market
Valves
Pipeline Pigging Equipment Market