
 Battery Safety Valve Market | 2026-2036
Battery Safety Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Safety Valve Market Insights
Solid-state battery prototyping is narrowing the tolerance window for conventional passive vent designs, forcing suppliers to engineer active pressure management interfaces. Bosch leverages its powertrain integration depth to bundle thermal runaway mitigation with valve hardware. Sensata Technologies anchors its position through sensor-vent fusion architectures that compete on response latency rather than mechanical reliability alone.
A battery safety valve is a pressure-activated sealing device, typically rated between 0.5 and 3.0 bar burst pressure, designed to vent electrolyte vapor and suppress thermal propagation during cell failure events. Pressure relief technology dominates current OEM specifications due to proven cycling durability, while flame arrestor configurations are gaining share in high-nickel chemistries where gas ignition risk escalates. Metal construction occupies the premium tier for automotive contracts, whereas plastic formulations sustain cost positioning in consumer electronics where lower operating temperatures apply.
The EU Battery Regulation and China's GB standards mandate traceable venting performance data, compelling manufacturers to embed verification protocols into production lines. NHTSA defect investigations in the United States have elevated thermal runaway containment from design preference to compliance threshold. Stakeholders must now decide whether to absorb certification costs internally or push downstream integration burdens onto cell producers.
Market Dynamics
The battery safety valve market is being fundamentally restructured by the transition from passive mechanical relief to sensor-integrated active pressure management systems, driven by OEM mandates for real-time thermal runaway detection.
Growth Catalysts
- EU Battery Regulation venting mandates:Traceable performance data requirements are forcing cell manufacturers to upgrade valve specifications across European EV supply chains.
- High-nickel cathode proliferation:NCM 811 and beyond chemistries generate more aggressive off-gas profiles, expanding demand for multi-stage flame-arresting valve architectures.
- South Korea cell manufacturing concentration:Domestic gigafactory buildouts by LG Energy Solution and Samsung SDI suppliers are localizing safety component procurement.
Market Restraints
- Stainless steel input volatility:316L and 17-4 PH alloy price swings compress margin predictability for metal valve producers serving automotive contracts.
- Technical sealing limitations:Conventional elastomer gaskets degrade above 150°C, creating reliability gaps for next-generation high-density pack designs.
- Substitution by solid-state architectures:Toyota and QuantumScape pressure-resistant cell housings may eventually eliminate external venting requirements entirely.
Strategic Opportunities
- India PLI scheme localization:Reliance Industries and Ola Electric battery ventures create first-mover advantage for valve suppliers establishing domestic production.
- Sensor-vent fusion convergence:Integration of pressure transducers with mechanical relief mechanisms enables predictive maintenance revenue streams.
- Grid storage application expansion:Utility-scale BESS projects in Texas and California are specifying enhanced venting for containerized lithium-ion installations.
Industry Challenges
- GB/T and UN 38.3 certification timelines:Dual validation requirements for China and international shipping create 8-14 month product qualification cycles.
- Cross-functional talent scarcity:Engineers combining battery electrochemistry expertise with precision metal forming capabilities command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Safety Valve Market |
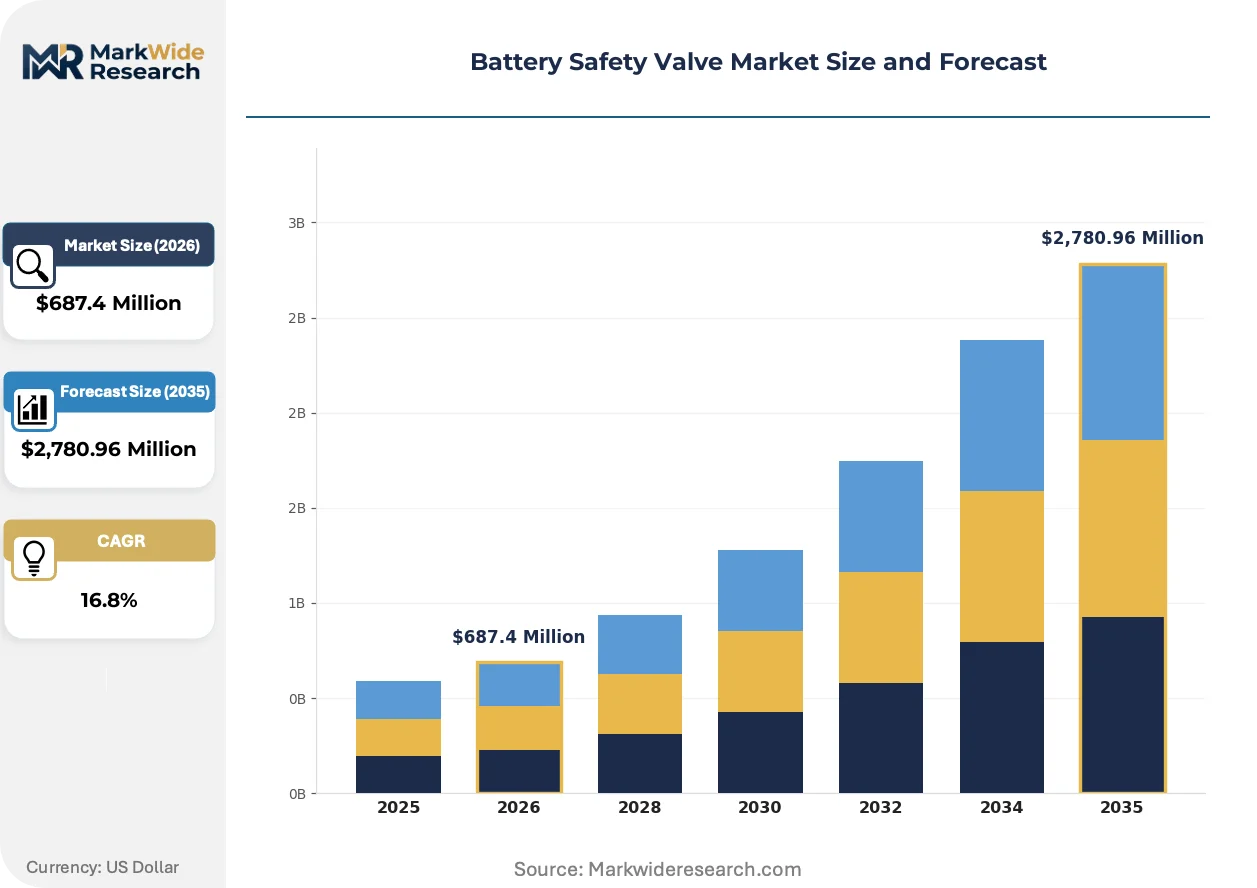
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $2,780.96 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pressure Relief, Flame Arrestor, Thermal Fuse, Safety Vent Material: Plastic, Metal, Glass, Composite Application: Electric Vehicles, Consumer Electronics, Renewable Energy, Industrial Equipment End User: OEMs, Aftermarket Providers, Research Institutions, Utilities |
| Companies Covered | Bosch (Robert Bosch GmbH), Johnson Controls, Sensata Technologies, SCHOTT AG, Zhejiang Sanhua Intelligent Controls Co., Ltd., Fike Corporation, Kautex Textron GmbH & Co. KG, Emerson Electric Co., LESER GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Safety Valve Market Trends and Innovations
Active pressure management is displacing passive mechanical designs across premium automotive segments, while regulatory traceability requirements are embedding verification electronics directly into valve hardware.
Multi-stage relief valve technology is hybridizing mechanical burst discs with electromechanical actuation to enable staged venting profiles. German and South Korean pack manufacturers are adopting these systems for 800V architectures. The technology is hybridizing cost structures upward while compressing response latency from milliseconds to microseconds.
China's GB/T 36276-2018 standard revisions are mandating documented cycling performance across temperature extremes. Domestic certification bodies are rejecting valve designs without embedded data logging. High-voltage passenger EV platforms are most affected, with BYD and CATL suppliers accelerating validation of smart vent prototypes.
Cell-to-pack architectures are eliminating module-level redundancy, concentrating venting responsibility at the pack level. Tier 1 integrators are specifying consolidated multi-cell relief systems rather than individual cell vents. This concentration is most visible in cylindrical cell applications, where Tesla's 4680 format and its imitators are driving specification consolidation.
Battery Safety Valve Market Segmentation
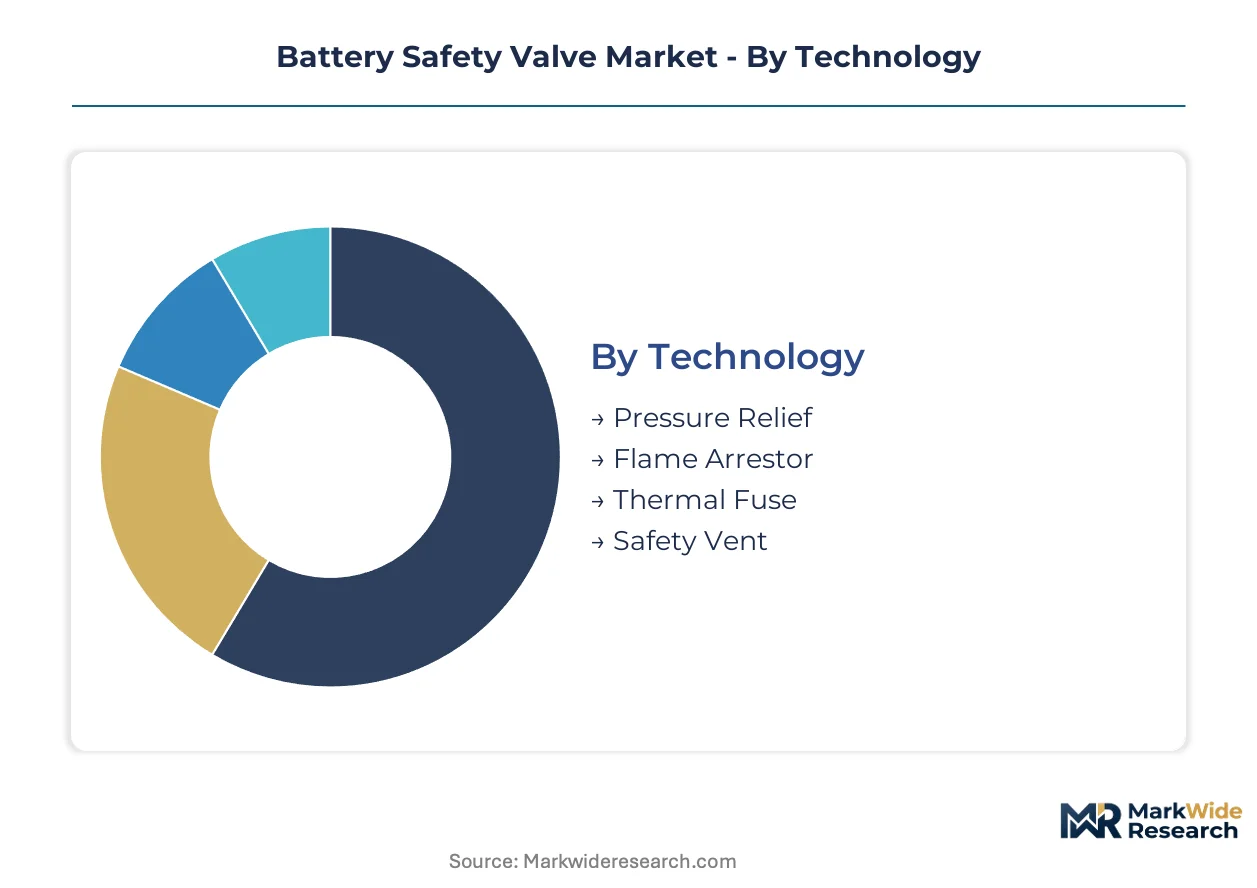
Battery safety valve procurement patterns diverge sharply across technology tiers and material specifications, with automotive OEMs demanding multi-year validation cycles while consumer electronics buyers prioritize rapid supplier switching. Understanding these segmentation fault lines reveals where margin compression concentrates versus where technical differentiation commands pricing power.
Technology:
After-sales service intensity varies dramatically by technology type, with active sensor-integrated systems requiring firmware updates and calibration protocols that passive mechanical designs never demand.
- Pressure Relief:Mechanical burst discs rated 0.5-3.0 bar dominate current OEM specifications due to proven cycling durability across temperature extremes. German automotive suppliers specify these for 800V architectures where electrolyte vapor venting must occur before thermal propagation initiates.
- Flame Arrestor:Multi-stage configurations incorporating sintered metal matrices and mesh barriers are gaining share in high-nickel NCM 811 chemistries where hydrogen off-gas ignition risk escalates dramatically. South Korean cell manufacturers specify these for cylindrical formats.
- Thermal Fuse:One-time activation devices isolate failed cells through conductive path interruption.
- Safety Vent:Reversible pressure-relief mechanisms suit consumer electronics with lower duty cycles.
Pressure Relief holds the largest share; momentum sits with Flame Arrestor.
Material:
Cost tier stratification separates premium automotive contracts from mass-market positioning, with metal construction absorbing stainless steel volatility while plastic formulations compete on landed cost.
- Metal:316L and 17-4 PH stainless steel constructions occupy the premium tier for automotive contracts requiring corrosion resistance and dimensional stability above 150°C. China's GB/T standards mandate documented cycling performance that metal designs satisfy more reliably.
- Plastic:Polyamide and PEEK formulations sustain cost positioning in consumer electronics where lower operating temperatures and shorter product lifecycles apply. These materials face sealing degradation thresholds that limit pack-level adoption.
- Glass:Hermetic sealing applications in solid-state battery prototyping.
- Composite:Hybrid metal-polymer constructions emerging for mid-tier industrial equipment.
Metal commands the revenue base; composites are climbing the fastest.
Application:
Volume concentration tracks electrification investment cycles, with electric vehicle procurement dwarfing other segments in unit value though not necessarily in shipment count.
- Electric Vehicles:Cell-to-pack architectures are eliminating module-level redundancy, concentrating venting responsibility at the pack level. Tier 1 integrators specify consolidated multi-cell relief systems rather than individual cell vents, with Tesla's 4680 format driving specification consolidation.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize compact form factors and rapid supplier qualification. These buyers accept lower burst pressure tolerances in exchange for cost minimization and supply chain flexibility.
- Renewable Energy:Utility-scale BESS projects in Texas and California specify enhanced venting for containerized lithium-ion installations.
- Industrial Equipment:Forklift and stationary power applications with moderate thermal management requirements.
Electric Vehicles anchors absolute revenue; Renewable Energy shows steepest expansion trajectory.
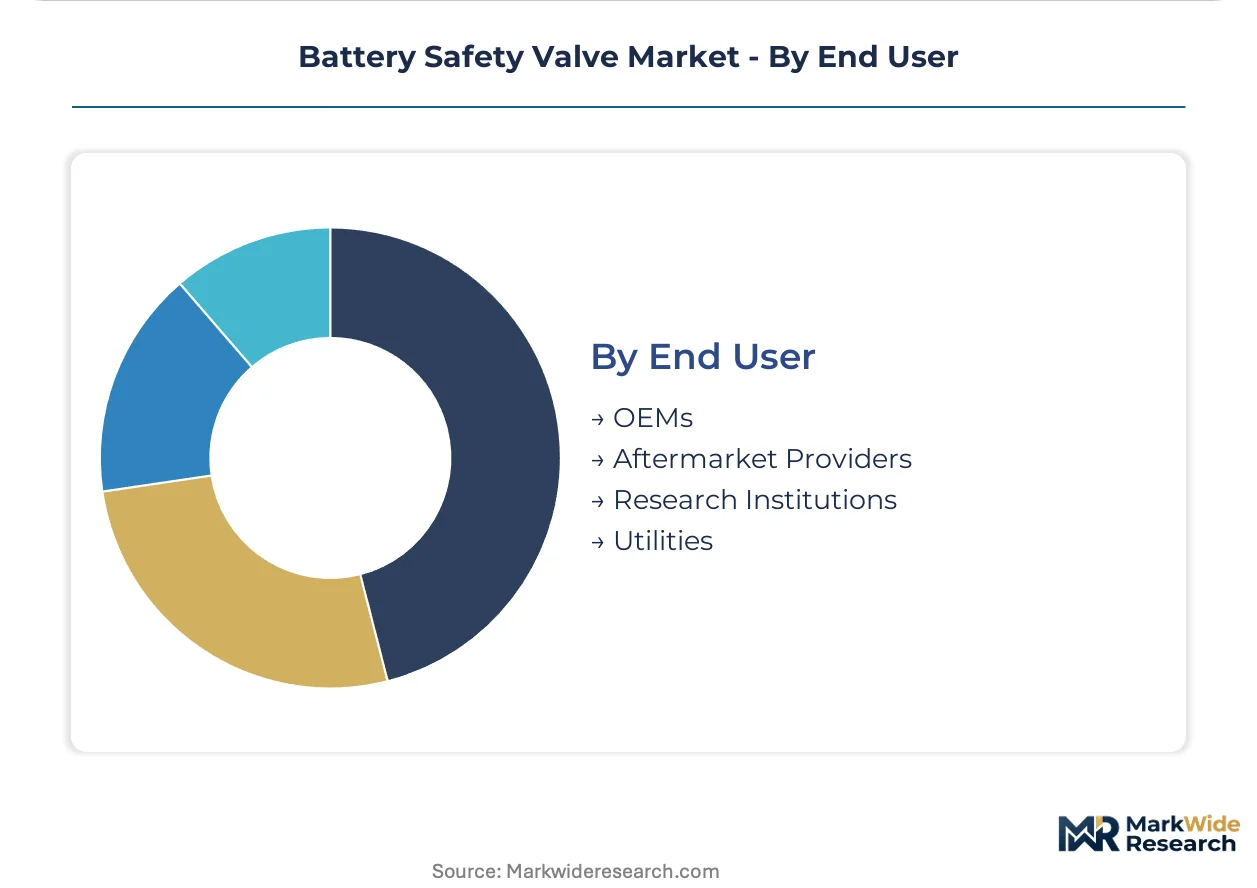
End User:
Customer type determines contract structure, with OEMs locking in multi-year supply agreements while aftermarket providers compete on inventory availability and technical documentation.
- OEMs:Battery pack manufacturers and automotive integrators dominate procurement volume, leveraging their scale to impose qualification protocols and traceability mandates. EU Battery Regulation venting requirements are forcing these buyers to upgrade valve specifications across European supply chains.
- Aftermarket Providers:Service networks and replacement part distributors focus on compatibility breadth and rapid fulfillment. These players absorb inventory risk from specification changes that OEMs push downstream.
- Research Institutions:Prototyping and validation testing with small-batch procurement.
- Utilities:Grid-scale storage operators specifying container-level venting systems.
OEMs control the demand base; Utilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers export multi-stage relief systems to South Korean cell manufacturers, creating a transcontinental procurement corridor that channels valve technology from Stuttgart and Munich toward Seoul's gigafactory belt.
China
CATL and BYD suppliers dominate domestic procurement of GB/T 36276-2018 certified valves. MIIT enforcement of traceable venting performance data compels manufacturers to embed verification electronics into production lines. The Yangtze River Delta cluster around Shanghai anchors high-volume fabrication for export-bound EV platforms.
Germany
Bosch and Continental integrate thermal runaway mitigation into powertrain contracts for 800V architectures. KBA mandates align with EU Battery Regulation venting requirements, forcing Tier 1 suppliers to upgrade specifications. The Baden-Württemberg automotive corridor concentrates validation laboratories and precision metal forming capacity.
South Korea
LG Energy Solution and Samsung SDI localize safety component procurement for cylindrical cell formats. MFDS-aligned testing protocols compress qualification timelines for flame-arrestor configurations. The Gyeonggi-Seoul manufacturing belt hosts dedicated valve production lines serving domestic gigafactory expansion.
United States
Tesla's 4680 format drives specification consolidation toward pack-level multi-cell relief systems. NHTSA defect investigations elevate thermal runaway containment to compliance threshold. The Texas-California BESS corridor specifies enhanced venting for utility-scale containerized installations.
India
Reliance Industries and Ola Electric battery ventures create first-mover positioning for suppliers establishing domestic production. PLI scheme localization incentives attract component manufacturers to Gujarat and Maharashtra. BIS certification requirements for automotive-grade valves remain under development.
Battery Safety Valve Market Competitive Landscape
On the supply side, the industry is bifurcated between diversified industrial conglomerates and specialized precision component fabricators. Tier 1 automotive suppliers leverage powertrain integration contracts to bundle valve hardware with thermal management systems. Three strategic archetypes dominate: sensor-vent fusion specialists, precision metal formers, and diversified industrial conglomerates. Capacity expansion and backward integration into stainless steel processing represent the dominant competitive moves.
Within the diversified industrial tier, Robert Bosch GmbH and Emerson Electric Co. exemplify conglomerate positioning through powertrain and automation integration depth. Sensata Technologies occupies a position among sensor-vent fusion specialists competing on response latency rather than mechanical reliability alone. Zhejiang Sanhua Intelligent Controls Co., Ltd. represents Chinese precision fabricators targeting cost positioning in high-volume procurement.
| Leading Market Players |
|---|
| Bosch (Robert Bosch GmbH) |
| Johnson Controls |
| Sensata Technologies |
| SCHOTT AG |
| Zhejiang Sanhua Intelligent Controls Co., Ltd. |
| Fike Corporation |
| Kautex Textron GmbH & Co. KG |
| Emerson Electric Co. |
| LESER GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta cluster around Shanghai anchors high-volume fabrication capacity that translates directly into pricing leverage for GB/T-certified valve suppliers serving export-bound EV platforms. Metal construction absorbs stainless steel alloy volatility while plastic formulations compete on landed cost for consumer electronics buyers with shorter qualification cycles.
Pricing Analysis
Active pressure management systems command a technology-generation pricing gap of roughly three-to-one against conventional passive mechanical designs, with sensor-integrated architectures carrying firmware development amortization and calibration protocol costs that burst discs never incur. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in plastic consumer electronics valves is intensifying because smartphone manufacturers prioritize rapid supplier switching over multi-year validation. Automotive OEMs show least price sensitivity due to thermal runaway liability exposure, while aftermarket providers absorb the highest margin pressure from specification volatility.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for valve producers serving dual-continent automotive contracts. Manufacturing concentrates in China, Germany, and South Korea, with 316L and 17-4 PH stainless steel sourcing drawing from specialty alloy mills in Japan and Austria. Single-source vulnerability sits with precision metal forming equipment for flame-arrestor mesh matrices. Distribution runs through Tier 1 automotive integrators who bundle valve hardware with thermal management system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The battery safety valve market is entering a cyclical recovery phase as EV production schedules normalize post-supply-constraint disruption and gigafactory buildouts accelerate procurement timelines.
For Market Incumbents: Build certification moats around GB/T and EU Battery Regulation traceability mandates before solid-state architectures eliminate external venting requirements entirely. Deepen backward integration into stainless steel processing to absorb 316L and 17-4 PH alloy price volatility. Lock multi-year supply agreements with South Korean cell manufacturers to defend position against Chinese precision fabricators targeting cost positioning.
For New Entrants and Emerging Players: Build out domestic production capacity in Gujarat and Maharashtra to capture India PLI scheme localization incentives before BIS certification requirements harden. Target utility-scale BESS projects in Texas and California where enhanced venting specifications for containerized lithium-ion installations remain underpenetrated by established automotive-focused suppliers. Lead with sensor-vent fusion prototypes that enable predictive maintenance revenue streams rather than competing on mechanical reliability alone.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-vent fusion specialists with electrochemistry-mechanical engineering cross-functional teams over diversified industrial conglomerates. Long-term viability hinges on active pressure management interface development ahead of solid-state battery commercialization. Watch Toyota and QuantumScape pressure-resistant cell housing timelines as the inflection signal for external venting demand destruction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Processing | Captive supply of 316L and 17-4 PH alloys insulates margin predictability from commodity volatility. |
| Sensor-Vent Fusion Product Development | Integration of pressure transducers with mechanical relief enables predictive maintenance revenue streams. |
| GB/T Certification Investment | MIIT enforcement of traceable venting performance data compels embedded verification electronics. |
| India Domestic Production Establishment | PLI scheme localization incentives attract component manufacturers to Reliance and Ola supply chains. |
| Utility-Scale BESS Specification Targeting | Texas and California containerized lithium-ion projects specify enhanced venting beyond automotive standards. |
Research Methodology
Operator-level perspectives from battery pack procurement managers, thermal runaway containment engineers, and precision metal forming plant managers anchored the qualitative base. Primary interviews with Tier 1 automotive supplier executives and cell manufacturer safety specification leads were cross-referenced against secondary validation from SEC filings, MIIT production license databases, and EU Battery Regulation implementation guidance. Bottom-up unit demand modeling and top-down market sizing triangulation reconciled volume estimates across technology tiers.
Scenario-bracketing around solid-state battery commercialization timelines and stainless steel alloy price trajectories bounded the forecast envelope across the analysis window. Segmentation dimensions modeled include pressure relief technology type, material specification grade, application sector, and end-user contract structure. CAGRs were derived from installed base growth rates and content-per-vehicle assumptions for 800V architectures. Forecast inputs incorporated NHTSA defect investigation outcomes and KBA mandate alignment timelines.
Stress conditions across solid-state substitution velocity, stainless steel input volatility, and EU-China regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cell-to-pack architecture adoption and high-nickel cathode chemistry proliferation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Fluid Transfer Solutions Market
Valves
Subsea Valves Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Magnetic Coupler Market
Valves
Top Drive Systems Market
Valves
Pneumatic Needle Valves Market
Valves
Europe Valves Market
Valves
Pressure Gauge Market
Valves
Global Pipeline Safety Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Safety Valve Market
Valves
Three Way Ball Valve Market
Valves
Safety Valve Test Benches Market
Valves
United States Valves Market
Valves
Global Valve Positioners Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market