
 Valve Manifold Box (VMB) Market | 2026-2036
Valve Manifold Box (VMB) Market Size, Share, and Industry Trends Forecast 2026-2036
Valve Manifold Box (VMB) Market Insights
Integration of electro-hydraulic actuation with IoT-enabled diagnostics is tilting how engineers specify fluid control architectures. Watts Water Technologies leverages its North American manufacturing footprint to anchor supply for water treatment infrastructure. Danfoss differentiates through advanced electro-hydraulic platforms that serve chemical processing and power generation clients. Viega sustains competitive positioning via precision-engineered compact manifold designs for European HVAC and industrial markets.
A valve manifold box is a prefabricated assembly housing multiple valves, ports, and instrumentation within a single enclosed structure, typically constructed from stainless steel or engineered polymers rated for pressures ranging from vacuum to 10,000 psi, designed to centralize fluid or gas distribution control in process-intensive environments. Its primary industrial purpose is to reduce leak points, simplify maintenance access, and enable modular expansion in systems where contamination control or safety isolation is critical. Compact valve manifold configurations now capture widening interest in aerospace systems and offshore oilfield equipment where space constraints and weight reduction override legacy mechanical preferences. Multi-port valve manifold architectures command margin concentration in semiconductor and pharmaceutical gas distribution, while pneumatic technology retains volume dominance across water treatment and conventional chemical processing installations.
EPA emissions regulations and OSHA process safety management requirements in the United States compel chemical plants and oil & gas operators toward sealed, instrumented manifold designs that minimize fugitive releases and enable remote monitoring. The EU Pressure Equipment Directive and ATEX standards shape product certification pathways for European suppliers, effectively filtering market access for non-compliant manufacturers. Stakeholders must weigh capital allocation between electro-hydraulic R&D and pneumatic platform refinement as end-user specifications diverge across energy transition timelines and legacy infrastructure replacement cycles.
Market Dynamics
Semiconductor fabrication expansion in East Asia is compressing specification cycles for ultra-high purity gas distribution systems, forcing manifold suppliers to accelerate electro-hydraulic platform development while maintaining pneumatic legacy compatibility.
Growth Catalysts
- EPA Emissions Standards:Tightened fugitive release mandates for chemical processing facilities are accelerating sealed manifold architecture deployment across Texas and Louisiana petrochemical corridors.
- Seoul-Shanghai Manufacturing Belt:Concentrated semiconductor fab construction is generating concentrated demand for multi-port VMB configurations rated to 10,000 psi.
- Electro-Hydraulic Convergence:Integration of servo-actuated valves with embedded pressure transducers is enabling real-time diagnostics in power generation turbine fuel systems.
Market Restraints
- Stainless Steel Input Volatility:316L and 316LN alloy price swings compress margin predictability for precision-welded manifold fabricators.
- Specialized Welder Scarcity:Orbital welding certification requirements limit qualified supplier base in North American fabrication shops.
- Polymer Substitution Pressure:High-performance PEEK manifold blocks are displacing metal in sub-3,000 psi water treatment applications.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO's tightened active pharmaceutical ingredient containment rules are creating first-mover advantage for sealed VMB suppliers in Hyderabad and Ahmedabad clusters.
- Hydrogen Fueling Infrastructure:700-bar pressure ratings required for heavy-duty vehicle dispensing stations favor compact manifold architectures over discrete valve assemblies.
- EU F-Gas Regulation Phase-Down:Refrigerant containment mandates are accelerating instrumented manifold adoption in commercial HVAC retrofit markets.
Industry Challenges
- ASME BPE Certification Timelines:Bioprocessing equipment validation cycles extend 14-18 months, freezing design iterations for pharmaceutical manifold suppliers.
- Legacy Pneumatic Integration:Brownfield chemical plants require hybrid architectures that bridge 4-20 mA analog controls with digital valve positioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valve Manifold Box (VMB) Market |
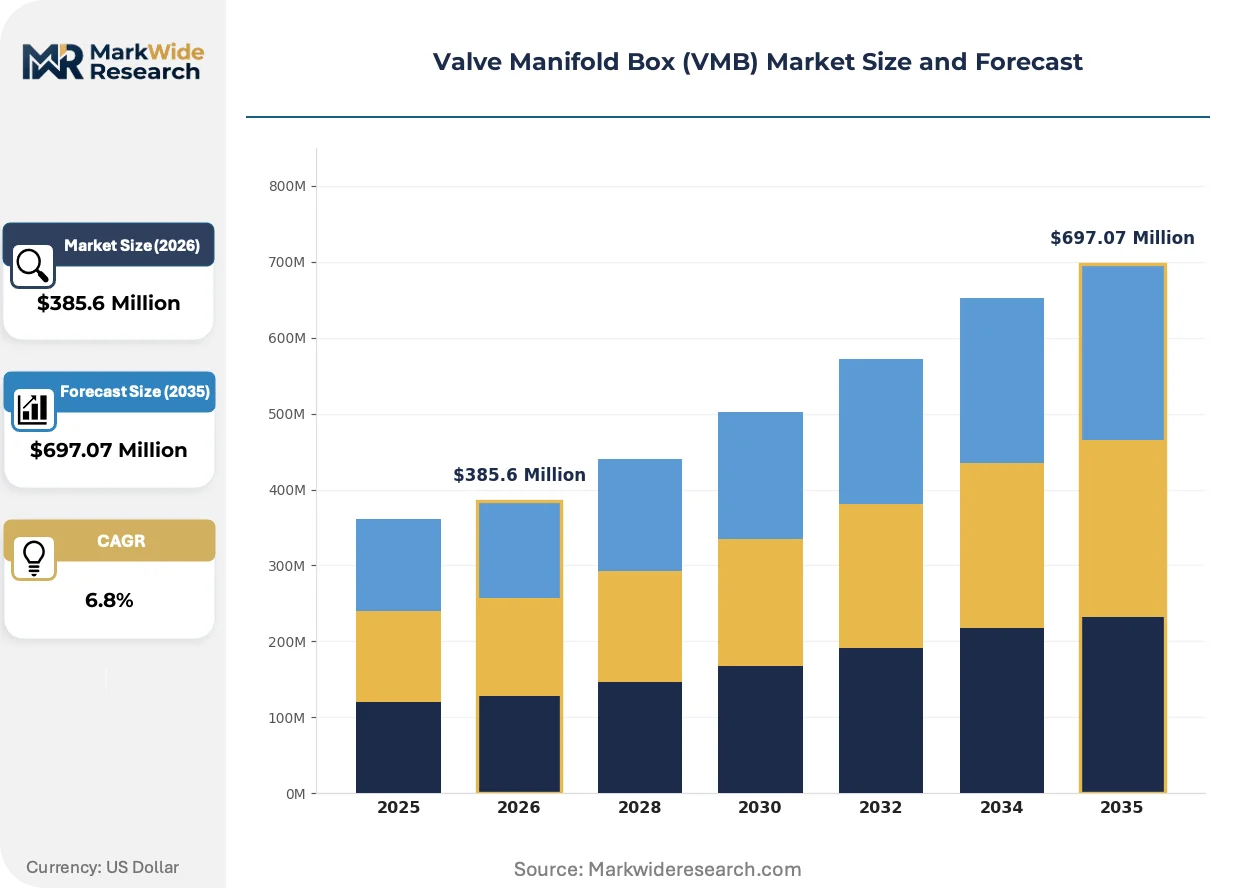
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Valve Manifold, Double Valve Manifold, Compact Valve Manifold, Multi-Port Valve Manifold Technology: Mechanical, Pneumatic, Electric, Hydraulic, Electro-Hydraulic Application: Oilfield Equipment, Chemical Processing, Power Generation, Water Treatment, Aerospace Systems End User: Oil & Gas Companies, Chemical Plants, Energy Providers, Water Utilities, Aerospace Manufacturers |
| Companies Covered | Watts Water Technologies, Giacomini, Uponor, Caleffi, Danfoss, REHAU, Oventrop, Resideo, Viega, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valve Manifold Box (VMB) Market Trends and Innovations
Fluid control architectures are undergoing simultaneous pressure for miniaturization and intelligence embedding, compressing the traditional separation between mechanical distribution hardware and process control electronics.
Edge-mounted sensor arrays with MEMS pressure transducers and thermal flow meters are digitizing manifold health monitoring. Semiconductor gas distribution engineers in South Korea are specifying these configurations for real-time purity verification. The technology is digitizing maintenance scheduling from calendar-based to condition-based intervals.
REACH substance restriction amendments are forcing stainless steel surface treatment substitutions across European pharmaceutical equipment supply chains. Hexavalent chromium elimination in passivation processes is elevating electropolishing costs. German and Swiss valve manufacturers are accelerating citric acid-based alternative qualification.
Integrated procurement of manifold assemblies with pre-configured instrumentation is displacing component-level sourcing in water treatment EPC contracts. Engineering firms are consolidating vendor panels to reduce interface risk. This consolidation is most visible in Australian desalination and Singapore water reuse project specifications.
Valve Manifold Box (VMB) Market Segmentation
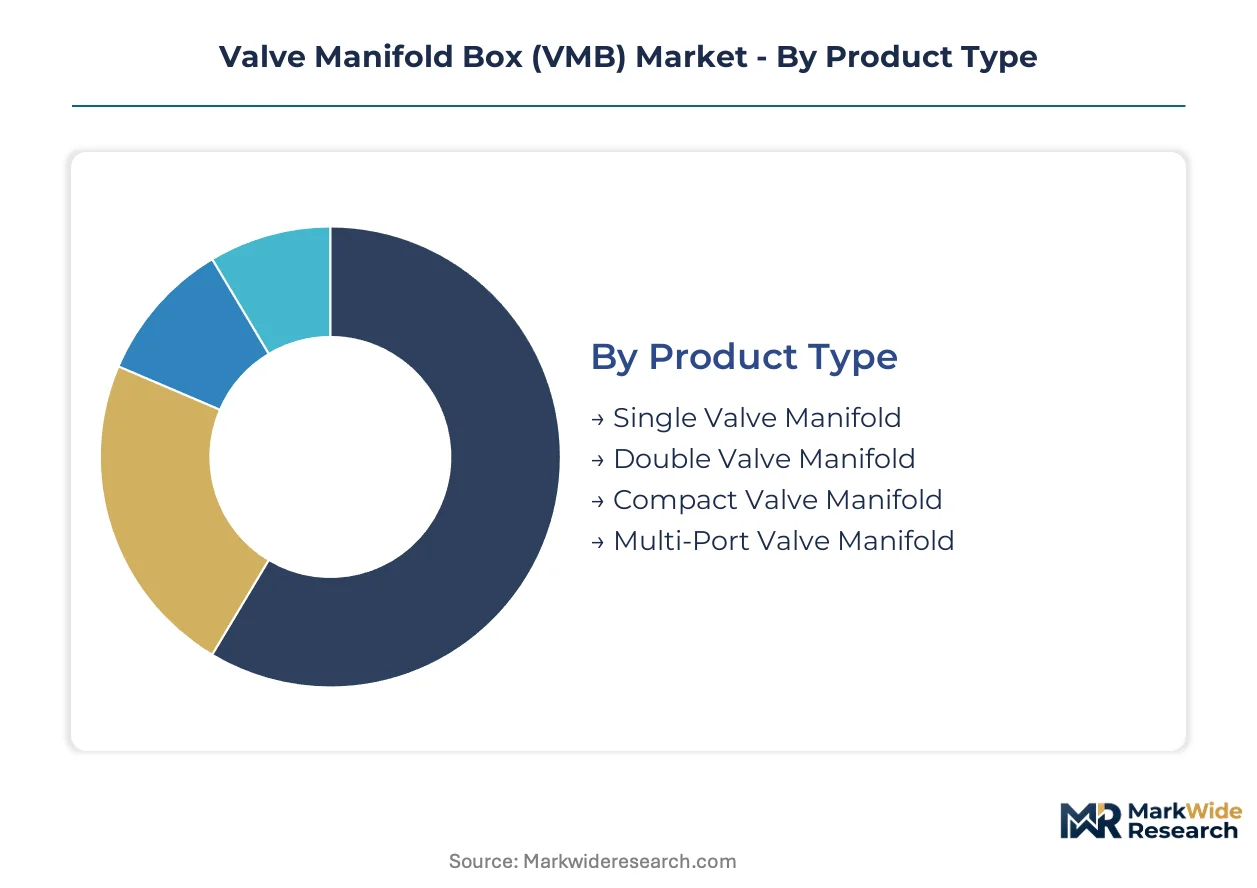
Valve manifold box procurement patterns diverge sharply across specification tiers, with after-sales service intensity varying from minimal field support for standard mechanical units to intensive calibration contracts for electro-hydraulic semiconductor systems. Engineers weight lifecycle service accessibility against capital expenditure differently across application environments, fragmenting supplier engagement models.
Product Type:
After-sales service intensity escalates with port complexity and pressure rating, driving multi-year service contracts for multi-port configurations while single valve units rely on spot replacement economics.
- Multi-Port Valve Manifold:Architectures integrating six or more valve positions with centralized instrumentation ports dominate semiconductor gas distribution in South Korea. Seoul-area fab operators specify these for ultra-high purity nitrogen and argon circuits where contamination control mandates sealed maintenance protocols. Service contracts typically span five-year intervals with quarterly calibration requirements.
- Compact Valve Manifold:Miniaturized assemblies rated to 10,000 psi capture aerospace hydraulic system retrofits where weight reduction overrides legacy mechanical preferences. Boeing and Airbus tier-one suppliers in Toulouse and Hamburg specify these for flight control redundancy circuits. The segment commands premium pricing through integrated sensor pre-qualification.
- Single Valve Manifold:Basic configurations serve isolated isolation points in conventional water treatment infrastructure.
- Double Valve Manifold:Redundant-seal designs address safety-critical isolation in Texas petrochemical corridors.
By volume, single valve configurations lead. By growth pace, multi-port architectures are expanding most quickly.
Technology:
Cost tier stratification separates commodity pneumatic installations from electro-hydraulic platforms where embedded diagnostics justify 3-4x hardware premiums.
- Electro-Hydraulic:Servo-actuated valve platforms with integrated pressure transducers and edge-mounted MEMS sensors enable real-time diagnostic feedback in power generation turbine fuel systems. Siemens Energy and GE Vernova specify these for combined-cycle plants in Germany and the United States where remote monitoring reduces outage frequency. The technology bridges mechanical reliability with digital control architectures.
- Pneumatic:Compressed-air actuation retains volume dominance across water treatment and conventional chemical processing installations where 4-20 mA analog controls suffice. Australian desalination EPC contracts specify pneumatic manifolds for membrane backwash sequencing. The segment benefits from lowest total installed cost and widest technician familiarity.
- Mechanical:Manual actuation persists in isolated safety isolation points with infrequent operation cycles.
- Electric:Motor-driven valves serve moderate-pressure HVAC and building automation applications.
- Hydraulic:High-force actuation dominates offshore oilfield BOP control systems.
By volume, pneumatic technology leads. By margin expansion, electro-hydraulic platforms are gaining share fastest.
Application:
Customer type concentration shapes specification rigor, with aerospace and semiconductor engineers demanding traceability documentation absent from utility procurement.
- Chemical Processing:Sealed manifold architectures rated for corrosive media address EPA fugitive emissions mandates across Louisiana and Texas petrochemical corridors. Dow and BASF facilities specify instrumented designs with remote leak detection. The application commands extended validation cycles but generates recurring instrumentation upgrade revenue.
- Aerospace Systems:Flight-critical hydraulic distribution requires AS9100-certified fabrication with 100% radiographic weld inspection. Safran and Collins Aerospace suppliers in France and Iowa specify compact multi-port configurations for landing gear and flight control circuits. Weight reduction specifications override cost minimization.
- Oilfield Equipment:Subsea and topside production systems specify high-pressure manifolds for wellhead control.
- Power Generation:Combined-cycle and renewable turbine fuel systems specify instrumented manifolds for combustion optimization.
- Water Treatment:Municipal and industrial desalination facilities deploy pneumatic manifolds for membrane process sequencing.
By volume, water treatment leads. By specification intensity, aerospace systems are climbing the fastest.
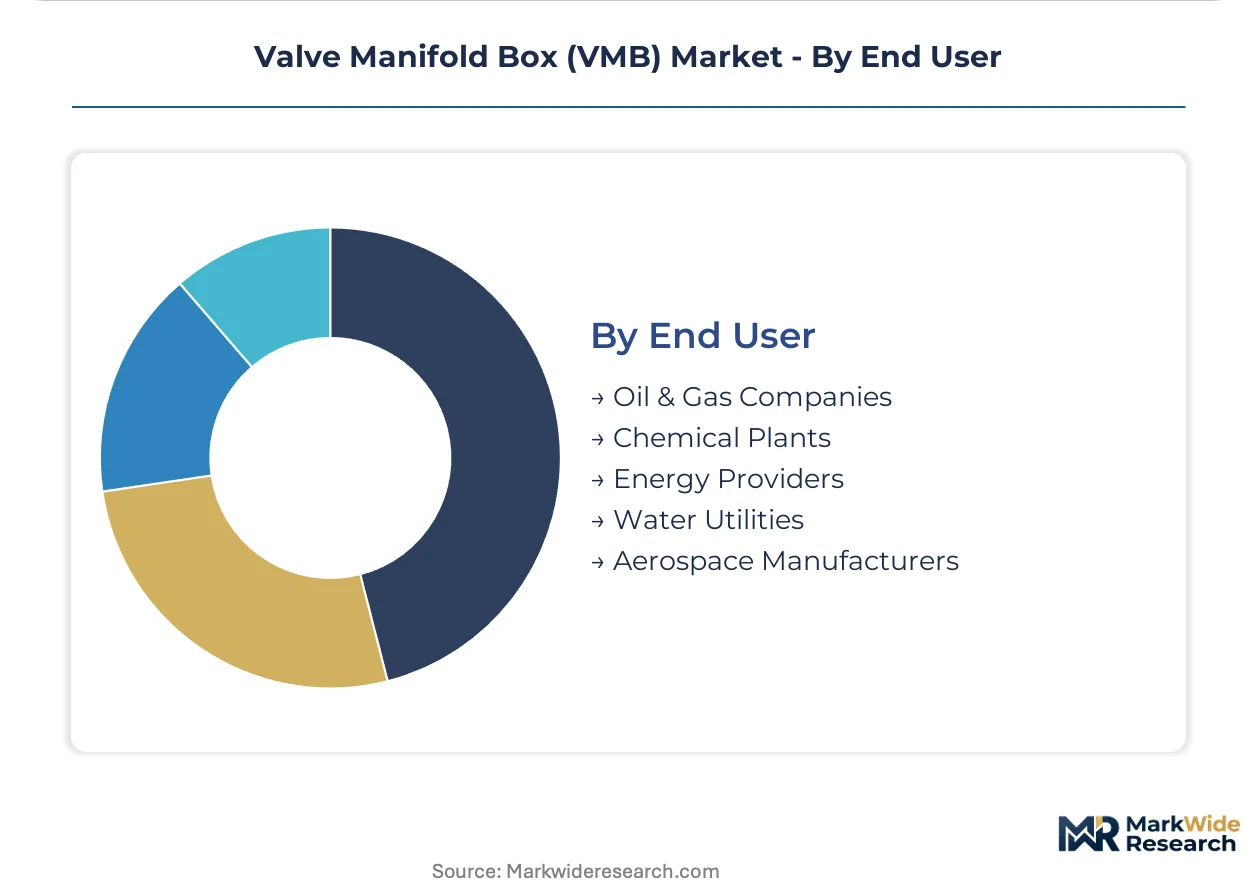
End User:
Geography concentration in East Asian manufacturing corridors compresses procurement cycles for semiconductor-focused energy providers while North American chemical plants extend replacement timelines.
- Oil & Gas Companies:Integrated operators and independents specify high-pressure manifolds for upstream production and midstream transmission. ExxonMobil and Shell facilities in the Gulf of Mexico deploy sealed architectures for platform safety systems. Procurement centralization at Houston headquarters reduces vendor count.
- Aerospace Manufacturers:Tier-one airframers and engine OEMs mandate AS9100 and NADCAP certification for all fluid control suppliers. Boeing Charleston and Airbus Hamburg facilities specify compact manifolds with pre-integrated sensors to reduce final assembly labor. The segment requires dedicated quality engineering support.
- Chemical Plants:Petrochemical and specialty chemical operators balance emissions compliance with capital constraints.
- Energy Providers:Utility and independent power producers specify instrumented manifolds for turbine efficiency optimization.
- Water Utilities:Municipal and regional authorities prioritize lowest lifecycle cost over technical differentiation.
By volume, water utilities lead. By contract value, aerospace manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Swiss valve manifold fabricators export precision-engineered assemblies to semiconductor fabrication facilities across South Korea and eastern China, while North American suppliers anchor petrochemical corridor demand through Houston-headquartered procurement networks.
United States
EPA fugitive emissions mandates and OSHA process safety requirements drive sealed manifold deployment across Texas and Louisiana petrochemical corridors. The Inflation Reduction Act provisions for industrial decarbonization accelerate instrumented architecture adoption. Houston anchors procurement centralization for Gulf of Mexico platform safety systems and onshore chemical processing facilities.
Germany
Combined-cycle power plant turbine fuel optimization and REACH substance restriction compliance shape electro-hydraulic specification trends. The EU Pressure Equipment Directive filters market access through certification pathway requirements. Bavarian and North Rhine-Westphalian industrial clusters concentrate fabrication capacity for pharmaceutical and chemical processing equipment.
South Korea
Semiconductor fabrication facility expansion for ultra-high purity gas distribution compresses specification cycles for multi-port configurations. MFDS pharmaceutical equipment standards influence containment architecture design for active ingredient manufacturing. Seoul-area fab operators drive concentrated demand for sealed maintenance protocols in nitrogen and argon distribution circuits.
China
Dual carbon goals and MEE emissions enforcement push chemical processing facilities toward instrumented manifold architectures. GB standards and SAMR certification requirements shape domestic supplier qualification. Yangtze River Delta manufacturing corridors concentrate demand for water treatment and industrial gas distribution infrastructure.
India
CDSCO tightened containment rules for active pharmaceutical ingredient manufacturing create specification windows for sealed VMB suppliers. PLI scheme incentives for specialty chemical production expand addressable market for high-purity gas distribution. Hyderabad and Ahmedabad clusters concentrate first-mover deployment for pharmaceutical-grade manifold systems.
Valve Manifold Box (VMB) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification tiers, producing a bifurcated structure where scale-driven water treatment suppliers anchor volume positions while precision-engineered semiconductor specialists capture margin concentration. The vendor base stratifies around three archetypes: diversified fluid control conglomerates with broad infrastructure exposure, precision fabrication specialists serving aerospace and pharmaceutical certification requirements, and regional water treatment equipment suppliers with localized service networks. Competitive moves center on backward integration into stainless steel fabrication capacity and technology licensing partnerships for electro-hydraulic platform development.
Among diversified fluid control conglomerates, Watts Water Technologies and Danfoss occupy positions spanning water treatment infrastructure and electro-hydraulic industrial applications. Viega anchors the precision fabrication specialist tier with compact manifold designs serving European HVAC and industrial certification requirements. These three companies exemplify the strategic archetypes competing across specification intensity gradients from commodity pneumatic installations to instrumented semiconductor gas distribution systems.
| Leading Market Players |
|---|
| Watts Water Technologies |
| Giacomini |
| Uponor |
| Caleffi |
| Danfoss |
| REHAU |
| Oventrop |
| Resideo |
| Viega |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Seoul container freight corridors transmit 316L stainless steel alloy volatility directly into VMB fabrication cost structures, compressing margins for precision-welded assemblies while amplifying price spreads between pneumatic commodity tiers and electro-hydraulic premium configurations. Contract manufacturers in these corridors face divergent buyer demands: water utilities prioritize lowest installed cost while semiconductor fabs accept 3-4x hardware premiums for sealed, instrumented architectures.
Pricing Analysis
Electro-hydraulic-to-pneumatic pricing gaps separate current-generation servo-actuated platforms from prior-generation compressed-air systems and emerging next-generation fully-integrated digital manifolds. Three-tier pricing structure across premium electro-hydraulic, standard pneumatic, and economy mechanical levels stratifies by certification grade and embedded diagnostics density. Cost compression in pneumatic tiers is intensifying because PEEK polymer substitution erodes metal-manifold volumes below 3,000 psi. Water utilities exhibit highest price sensitivity; semiconductor fabs demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with German precision fabricators, South Korean semiconductor equipment specialists, and North American water treatment assembly houses. Raw material sourcing draws from 316L/316LN stainless steel mills, high-performance PEEK resin producers, and MEMS sensor foundries. Single-source vulnerability concentrates in orbital welding certification capacity for ultra-high purity gas distribution. Distribution runs through Houston-headquartered procurement networks for petrochemical corridors and Seoul-area fab operator direct contracts for semiconductor systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital welding certification scarcity constrains qualified supplier expansion, creating defensive moats for incumbent precision fabricators while fragmenting competitive access for new entrants across pharmaceutical and semiconductor specification tiers.
For Market Incumbents: Insulate electro-hydraulic platform margins through captive supply of 316L stainless steel fabrication capacity and accelerated ASME BPE certification investment. PEEK polymer substitution in water treatment tiers threatens commodity pneumatic revenue; channel control via integrated instrumentation bundling defends positioning against regional assembly houses. For New Entrants and Emerging Players: India's pharmaceutical manufacturing corridors around Hyderabad and Ahmedabad present underpenetration for sealed VMB architectures under CDSCO containment mandates. First-mover deployment targeting active pharmaceutical ingredient gas distribution bypasses entrenched semiconductor supply relationships. Go-to-market angle: partner with European precision fabricators for technology licensing while establishing local orbital welding training programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified fluid control conglomerates seeking to divest non-core manifold fabrication units. Long-term viability favors precision specialists with pharmaceutical and aerospace certification depth over commodity water treatment suppliers facing polymer displacement. Monitor EPA emissions enforcement intensity in Texas and Louisiana petrochemical corridors as inflection indicator for sealed architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive 316L supply secures margin predictability against alloy price swings for precision-welded assemblies. |
| Electro-Hydraulic Platform Development Partnership | Siemens Energy and GE Vernova turbine fuel specifications drive real-time diagnostic integration requirements. |
| Orbital Welding Certification Program Expansion | ASME BPE validation cycles extend 14-18 months, freezing design iterations without qualified welder pipelines. |
| Pharmaceutical-Grade Containment Architecture Launch | CDSCO rules in Hyderabad and Ahmedabad clusters create specification windows for sealed VMB first-movers. |
| Hydrogen Fueling Infrastructure Compact Manifold Design | 700-bar pressure ratings for heavy-duty vehicle dispensing favor centralized architectures over discrete valve assemblies. |
Research Methodology
The analysis maps electro-hydraulic, pneumatic, mechanical, and hydraulic technology sub-sectors, each validated through procurement directors at semiconductor fabs, maintenance engineers at petrochemical facilities, and EPC contractors at water treatment projects. Primary interview insights combined with secondary validation from EPA enforcement databases, MFDS pharmaceutical equipment filings, and SEC 10-K disclosures for fluid control conglomerates. Bottom-up unit economics triangulated against top-down regional demand aggregation across the analysis window.
Assumption sets held stainless steel input volatility and regulatory enforcement timelines as variable inputs while fixing technology substitution rates and certification pathway durations. Segmentation dimensions modeled include product type complexity, actuation technology tier, application specification intensity, and end-user procurement centralization. CAGRs derived from installed base replacement cycles and capacity expansion announcements throughout the forecast period. Industry-specific inputs incorporate semiconductor fab construction pipelines and hydrogen fueling station deployment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic suppliers under SAMR localization mandates would shift outcomes through accelerated price competition in water treatment tiers. Quarterly review of 316L alloy futures, EPA emissions enforcement actions, and CDSCO pharmaceutical equipment rulemaking is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Choke and Kill Manifold Market
Valves
Reciprocating Compressor Components Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Emergency Venting System Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Steel Cylinder Market
Valves
Industrial Safety Valves Market
Valves
Subsea Valves Market
Valves
Harmonic Dampers Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Middle East and Africa Machined Seals Market
Valves
Subsea Control System Market
Valves
Air Jet Ejectors Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
GCC and MENA Valves Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market