
 Industrial Valves and Actuators Market | 2026-2036
Industrial Valves and Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Valves and Actuators Market Analytics
Power generation utilities are collapsing their historical preference for manual valve configurations as distributed control systems mandate remote actuation across combined-cycle and renewable-hybrid plants. Emerson Electric Co. leverages its integrated digital valve controller portfolio to anchor automation contracts with independent power producers in North America. Flowserve Corporation competes through specialized severe-service valve designs that sustain margins in high-temperature, high-pressure boiler feedwater applications.
Industrial valves and actuators encompass mechanical flow-control devices and their motorized, pneumatic, or hydraulic operators, typically constructed from carbon steel, stainless steel, or exotic alloys with pressure ratings from ANSI Class 150 to 4500 and temperature tolerances exceeding 650°C, serving to isolate, regulate, or throttle fluid streams in continuous-process industries. Control valves dominate value capture due to their integration with process control loops and higher engineering content, while electric actuator technology is displacing pneumatic alternatives in facilities prioritizing precision positioning and energy efficiency. Ball valves and butterfly valves occupy distinct niches—ball valves sealing bubble-tight in hydrocarbon service, butterfly valves offering lower-cost throttling in water treatment and HVAC applications.
The EPA enforces New Source Performance Standards that mandate low-emission valve technologies in petroleum refineries and chemical manufacturing, while the EU F-Gas Regulation restricts fluorinated greenhouse gas leakage from refrigeration and industrial process valves, compelling European manufacturers to certify products under updated CE marking protocols. China's NMPA and MEE coordinate national standards for pressure equipment safety and carbon intensity benchmarks that shape import eligibility and domestic procurement criteria. Stakeholders must monitor how divergent carbon-border adjustment mechanisms and local-content requirements reshape supplier qualification protocols across major demand centers.
Market Dynamics
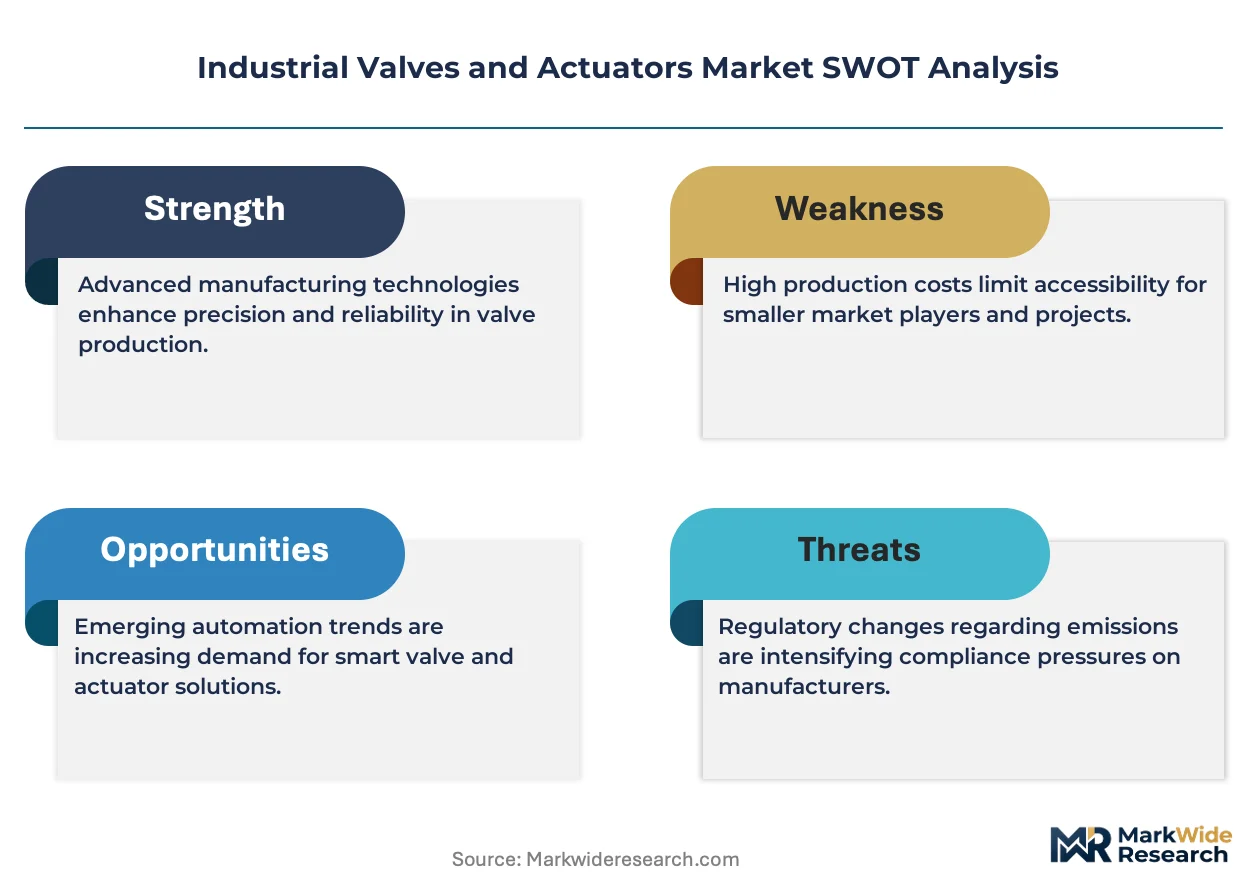
EPA fugitive emissions mandates and EU F-Gas Regulation are compressing product lifecycles across the Industrial Valves and Actuators Market, forcing simultaneous material upgrades and smart-actuator retrofits in installed bases.
Growth Catalysts
- Smart Distribution Networks:Water treatment utilities are deploying electric actuators with embedded diagnostics to enable predictive maintenance and reduce unplanned downtime in aging pipeline infrastructure.
- EPA New Source Performance Standards:Petroleum refineries must replace conventional packing with low-leak sealed bonnet designs, creating mandatory replacement demand regardless of commodity cycles.
- Dual Carbon Goals:China's state-backed petrochemical expansion is accelerating valve replacement cycles in refineries and power plants to meet carbon intensity benchmarks under MEE coordination.
Market Restraints
- Exotic Alloy Supply Concentration:Nickel-based superalloy sourcing concentrates in limited smelter capacity, exposing valve manufacturers to raw material volatility and extended lead times.
- CE Marking Protocol Complexity:Updated EU F-Gas certification requirements are extending product approval timelines by 8-14 months for European manufacturers seeking refrigerant service valve placement.
- Manual Valve Substitution:Pneumatic actuator retrofits face displacement pressure from all-electric alternatives in facilities prioritizing precision positioning and energy efficiency.
Strategic Opportunities
- Hydrogen Infrastructure White Space:Germany's KBA and EU Hydrogen Strategy are creating certified valve demand for high-pressure hydrogen transport and storage applications.
- Digital Twin Convergence:Integration of valve-mounted sensors with plant-wide digital twin platforms enables outcome-based service contracts and recurring revenue streams.
- Direct Utility Procurement:Municipal water authorities are bypassing traditional distribution channels through cooperative purchasing agreements, compressing margin capture for intermediaries.
Industry Challenges
- Actuator Firmware Integration:Legacy distributed control systems require custom protocol gateways to interface with modern intelligent valve positioners, extending commissioning timelines.
- Sealing Technology Certification:Bubble-tight qualification for severe-service ball valves demands extended third-party witnessed testing under API 6D and ISO 5208 protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Valves and Actuators Market |
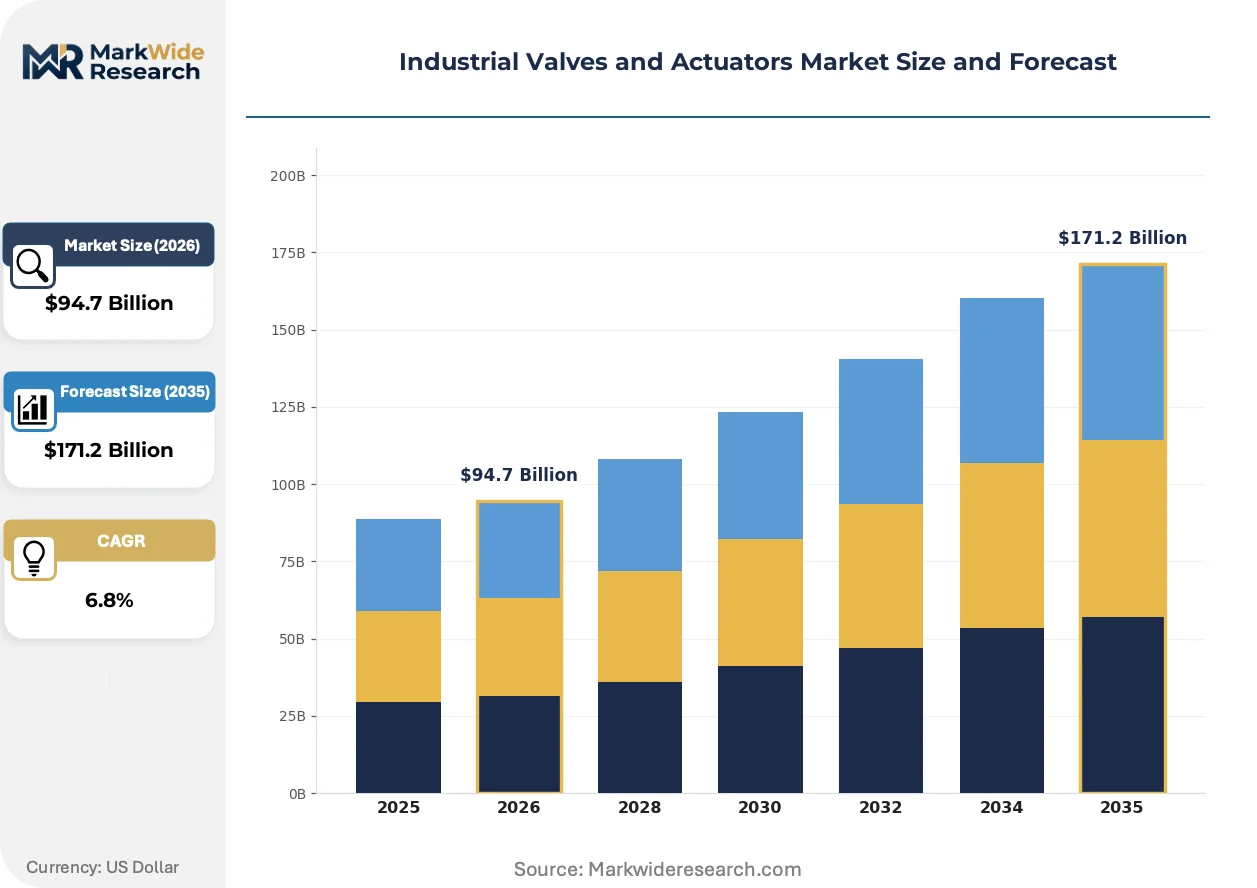
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $171.2 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Butterfly Valves, Control Valves Technology: Pneumatic, Hydraulic, Electric, Manual End User: Oil & Gas, Water Treatment, Power Generation, Chemicals Installation: Onshore, Offshore, Factory, Pipeline |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, ABB, Rotork, IMI, Alfa Laval, Parker Hannifin Corp, Honeywell International Inc., SLB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Valves and Actuators Market Evolving Landscape
Digital valve controllers are bifurcating the actuator installed base between precision-positioning electric units and legacy pneumatic systems, while regulatory pressure on fugitive emissions accelerates material science investment.
Electric actuator technology with integrated Hart or Foundation Fieldbus communication is bifurcating the market between high-precision positioning applications and cost-optimized pneumatic alternatives. Combined-cycle power plants and renewable-hybrid facilities are adopting these systems for remote valve manipulation from centralized control rooms. The technology is bifurcating supplier portfolios, forcing pneumatic specialists to develop electric product lines or cede premium positioning segments.
EU F-Gas Regulation restrictions on fluorinated greenhouse gas leakage are compelling valve manufacturers to certify products under updated CE marking protocols with enhanced packing test requirements. European refrigeration and industrial process valve producers must redesign bonnet seals and stem packings to meet tightened leakage thresholds. Chemical manufacturing facilities in Germany and France face the steepest compliance costs, accelerating sourcing shifts toward pre-certified sealed bonnet designs.
After-sales service unbundling is disrupting traditional valve procurement in North American power generation, where independent power producers now separate hardware purchase from commissioning and lifecycle support contracts. Specialized service providers are capturing recurring revenue streams previously retained by original equipment manufacturers. Texas and California independent power markets exhibit the most advanced disaggregation, with long-term actuator calibration and diagnostic contracts sold separately from initial valve supply.
Industrial Valves and Actuators Market Segmentation
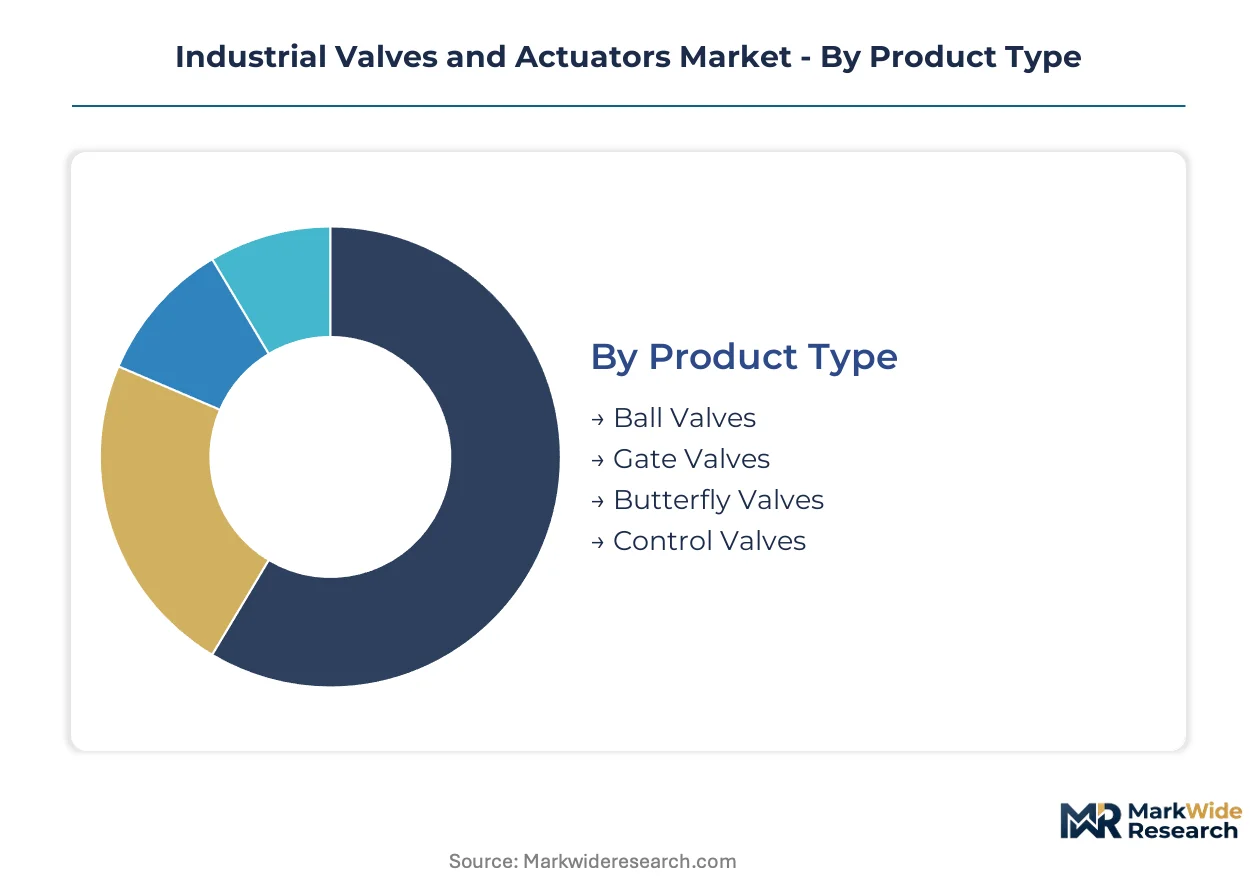
Segmentation in the Industrial Valves and Actuators Market reveals how margin pools concentrate around precision-engineered control systems and severe-service applications. Technology choices between electric and pneumatic actuation increasingly determine supplier profitability and customer switching costs.
Product Type:
Control valves command the highest engineering margins through integration with process control loops and digital positioning systems.
- Ball Valves:Quarter-turn isolation devices with floating or trunnion-mounted ball designs achieve bubble-tight sealing in hydrocarbon service. Refinery operators in China and the United States specify API 6D certified units for high-pressure pipeline isolation, driven by fugitive emissions enforcement under EPA and MEE regulations.
- Control Valves:Throttling devices with characterized trim designs integrate with distributed control systems for continuous process modulation. Combined-cycle power plants and petrochemical complexes in Germany and Texas prioritize these for boiler feedwater and reactor feed control, where precision positioning justifies premium pricing.
- Gate Valves:Linear-motion isolation devices with wedge or parallel-slide configurations serve in straight-flow applications with minimal pressure drop.
- Butterfly Valves:Quarter-turn throttling devices with concentric or eccentric disc designs offer cost-effective flow control in water treatment and HVAC systems.
The dominant share belongs to Control Valves, while Ball Valves is closing the gap fastest.
Technology:
Technology selection increasingly bifurcates between precision-positioning electric systems and legacy pneumatic infrastructure.
- Electric:Motor-driven actuators with integrated Hart or Foundation Fieldbus communication enable remote valve manipulation and predictive diagnostics. Renewable-hybrid power facilities and smart water distribution networks in California and the Netherlands specify these for energy efficiency and centralized control room integration.
- Pneumatic:Air-powered actuators with spring-return or double-acting configurations dominate existing installed bases in chemical manufacturing. European process plants under EU F-Gas Regulation face retrofit pressure as electric alternatives displace pneumatic units in new construction.
- Hydraulic:Fluid-power actuators deliver high torque output for severe-service isolation in subsea and high-pressure pipeline applications.
- Manual:Handwheel or lever-operated valves persist in low-cycle isolation duties and safety-critical bypass configurations.
Electric actuators hold the revenue lead, though Pneumatic retains volume dominance in replacement cycles.
End User:
End-use concentration varies sharply between regulated utilities and cyclical process industries.
- Oil & Gas:Upstream, midstream, and downstream operations require severe-service valves for high-pressure hydrocarbon containment. China's state-backed petrochemical expansion and U.S. Permian Basin infrastructure drive replacement demand for sealed bonnet designs meeting tightened emissions standards.
- Power Generation:Combined-cycle, renewable-hybrid, and thermal plants specify actuated valves for steam and feedwater systems. Independent power producers in Texas and Florida separate hardware procurement from long-term service contracts, reshaping supplier engagement models.
- Water Treatment:Municipal utilities deploy electric actuators with embedded diagnostics for smart distribution network automation.
- Chemicals:Process manufacturers in Germany and France face steep EU F-Gas compliance costs for refrigeration and process valve leakage containment.
Oil & Gas generates the largest absolute revenue, yet Power Generation is expanding most quickly through renewable-hybrid construction.
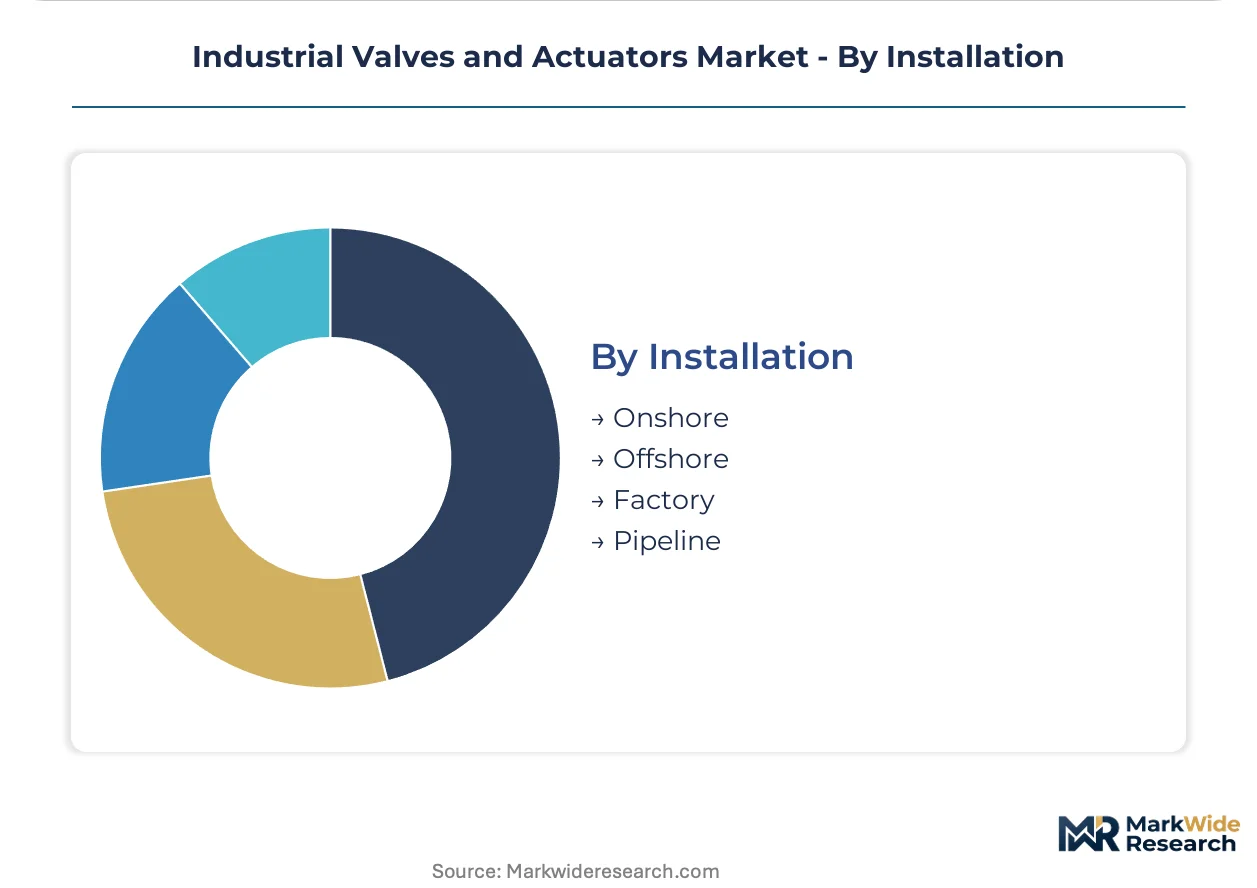
Installation:
Installation context determines material specification severity and service accessibility constraints.
- Pipeline:Long-distance transport systems require full-bore ball valves with pigging compatibility and emergency shutdown actuation. Cross-border infrastructure projects in Europe and North America specify API 6D certified units with extended design life for buried or subsea service.
- Offshore:Platform and subsea installations demand corrosion-resistant alloys and subsea-rated actuators for remote intervention. North Sea and Gulf of Mexico developments specify these for high-pressure wellhead and manifold isolation.
- Onshore:Surface facility installations in refineries and process plants allow standard material specifications with accessible maintenance access.
- Factory:Original equipment manufacturing integration supplies valves as skid-mounted packages for modular construction.
Pipeline installations command the premium pricing tier, while Offshore is gaining share fastest through subsea field development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Alaska Pipeline System and Gulf Coast petrochemical corridor anchor North American valve demand, while China's West-East Gas Pipeline network and Germany's hydrogen backbone reshape procurement patterns across three continents.
United States
Permian Basin midstream expansion and LNG export terminal construction drive severe-service valve procurement. EPA New Source Performance Standards mandate low-emission sealed bonnet designs in Texas and Louisiana refineries. Houston's Energy Corridor hosts the highest concentration of actuator retrofit contractors serving the Gulf Coast petrochemical cluster.
China
State-backed petrochemical capacity expansion along the Yangtze River Delta accelerates replacement cycles in legacy refineries. MEE carbon intensity benchmarks under dual carbon goals compel valve upgrades in Jiangsu and Zhejiang power plants. Ningbo-Zhoushan port infrastructure supports the largest import hub for nickel-based superalloy castings serving domestic valve fabricators.
Germany
EU Hydrogen Strategy implementation creates certified demand for high-pressure hydrogen transport valves. KBA certification requirements and EU F-Gas Regulation tighten leakage thresholds for chemical manufacturers in Ludwigshafen and Leverkusen. Ruhr industrial cluster utilities are retrofitting pneumatic actuators with electric alternatives in combined-cycle plants.
Saudi Arabia
Aramco expansion projects and downstream integration investments sustain procurement for API 6D certified pipeline valves. Domestic content requirements under Vision 2030 reshape supplier qualification for Jubail Industrial City developments. Ras Tanura refinery upgrades specify sealed bonnet designs meeting tightened fugitive emissions protocols.
India
City gas distribution network rollout under the PNGRB mandate drives smart actuator deployment for municipal utilities. BIS pressure equipment safety standards tighten import eligibility for refinery valve suppliers. Gujarat's Dahej PCPIR chemical hub concentrates demand for corrosion-resistant alloy valves in chlorine and caustic soda processing.
Industrial Valves and Actuators Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth, creating a tiered structure where scale-driven conglomerates anchor automation contracts while mid-cap fabricators defend margins in severe-service niches. The market fragments across three strategic archetypes: integrated digital platform providers, specialized severe-service designers, and regional alloy casting specialists. Consolidation pressure intensifies as electric actuator technology bifurcates portfolios, forcing legacy pneumatic specialists toward acquisition-led capability expansion or partnership-based technology licensing.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify contrasting positioning archetypes—one anchoring integrated digital valve controller portfolios, the other sustaining margins through specialized severe-service engineering. ABB occupies a position bridging automation hardware and process control software integration. These three entities represent the competitive tension between platform breadth and application depth that shapes contract award patterns across power generation and petrochemical verticals.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| ABB |
| Rotork |
| IMI |
| Alfa Laval |
| Parker Hannifin Corp |
| Honeywell International Inc. |
| SLB |
| Others |
Value Network & Pricing Analysis
API 6D certification requirements and EPA fugitive emissions mandates gate both supplier qualification and price differentiation simultaneously, forcing valve fabricators to absorb certification costs into tiered product lines while buyers face mandatory upgrade cycles regardless of commodity pricing cycles.
Pricing Analysis
Volume-discount tiering structures separate API 6D certified severe-service units from standard ANSI Class 150-300 commodity valves, with price differentiation anchored in nickel-based superalloy content and sealed bonnet engineering. Certification grade and after-sales service bundling drive premium capture for control valve integrators. Cost compression in mid-tier pneumatic actuators is intensifying because electric alternatives displace legacy systems in combined-cycle power plants. Municipal water utilities exhibit highest price sensitivity, while offshore petrochemical operators prioritize reliability over unit economics.
Supply Chain Analysis
Inbound logistics costs through Ningbo-Zhoushan and Rotterdam ports constrain nickel-based superalloy casting availability for European and North American valve fabricators. Supply concentrates in China, India, and Germany for precision castings, with actuator electronics sourcing anchored in South Korea and Japan. Raw material dependencies include nickel-chromium-molybdenum alloys, rare earth magnets for electric actuators, and fluoropolymer packing materials. Single-source vulnerability in superalloy smelter capacity exposes fabricators to extended lead times. Distribution runs through authorized distributor networks for project-based procurement, with direct utility purchasing compressing intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart actuator penetration in water treatment and renewable-hybrid power plants signals early-cycle expansion, with digital valve controller adoption creating recurring revenue pools that outpace hardware replacement cycles.
For Market Incumbents: Compound defensive positioning through backward integration into nickel-based superalloy casting capacity and captive supply of sealed bonnet assemblies. Certification investment in EU F-Gas and KBA hydrogen protocols anchors premium pricing against emerging electric actuator specialists. Capacity addition in Jiangsu province captures China's state-backed petrochemical expansion while insulating against tariff exposure. For New Entrants and Emerging Players: API 6D fast-track certification programs open white-space penetration in hydrogen transport valve segments underserved by legacy pneumatic specialists. Municipal smart water networks in California and the Netherlands represent the most penetrable geography for embedded diagnostic actuators. Direct engagement with cooperative purchasing agreements bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: EPA New Source Performance Standards enforcement reshapes the acquisition landscape toward sealed bonnet technology holders and electric actuator firmware developers. Five-to-ten year viability favors platform-integrated suppliers with digital twin service capabilities over commodity hardware fabricators. Watch for MEE carbon intensity benchmark acceleration as inflection signal for Chinese replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | Captive nickel-chromium supply secures margin control against raw material volatility in severe-service segments. |
| Digital Twin Platform Integration | Valve-mounted sensor convergence with Emerson and ABB control systems enables outcome-based service contracts. |
| Hydrogen Certification Fast-Track | KBA and EU Hydrogen Strategy compliance opens high-pressure transport valve demand in German industrial clusters. |
| Direct Utility Procurement Engagement | Cooperative purchasing agreements with Texas and Florida IPPs compress distributor margins while locking recurring calibration revenue. |
| Electric Actuator Product Line Expansion | Foundation Fieldbus compatibility displaces pneumatic legacy in renewable-hybrid power plants and smart water networks. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings, and API certification registries preceded structured interviews with plant engineers at combined-cycle facilities, procurement leads at petrochemical complexes, aftermarket service heads at valve distributors, and regulatory affairs directors at actuator OEMs. Primary fieldwork across the United States, Germany, and China validated secondary estimates from EIA power plant databases, IEA industrial efficiency reports, and MEE carbon intensity disclosures. Bottom-up unit shipment modeling triangulated against top-down industry value estimates.
Variance decomposition across technology, end-use, and installation segments shaped the analytical framework throughout the projection horizon. Modeled dimensions include actuator type, valve pressure class, material specification grade, and regional regulatory cluster. CAGRs derived from segment-level penetration curves and replacement cycle assumptions, with inputs from nickel price futures, power plant construction pipelines, and municipal water infrastructure budgets.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA enforcement and China's dual carbon goal implementation; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Electro Pneumatic Positioner Market
Valves
Sanitary Valves Market
Valves
Blow - Off Valves Market
Valves
Global Flow Control Market
Valves
North America Industrial Valves Market
Valves
Instrumentation Valves and Fittings Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Expansion Valves Market
Valves
Emergency Venting System Market
Valves
Servo Valves Market
Valves
Float Traps Market
Valves
Naval Actuators and Valves Market
Valves
North America Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Air Jet Ejectors Market
Valves
Safety Valve Market