
 Pharmaceutical Software Market | 2026-2036
Pharmaceutical Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Software Market Intelligence
The customer base for pharmaceutical software is consolidating as large pharmaceutical companies acquire smaller biotech firms, creating demand for enterprise-level integrated solutions. Veeva Systems specializes in cloud-based software for the life sciences industry, covering clinical, regulatory, and commercial functions. IQVIA leverages its extensive data assets to provide analytics and trial management platforms. Oracle Health competes with its suite of database management and clinical trial software for large-scale enterprise deployments.
Pharmaceutical software encompasses a range of digital tools designed to manage and automate processes across the drug lifecycle. These platforms must ensure data integrity and traceability, often complying with standards like the FDA's 21 CFR Part 11 for electronic records. Cloud-based and Software as a Service deployment models are displacing traditional on-premises installations due to scalability and lower upfront costs. Within solution types, Clinical Trial Management and Pharmacovigilance software represent high-growth categories, driven by complex global studies and post-market safety requirements.
Regulatory frameworks from the FDA, EMA, and China's NMPA mandate stringent data management and reporting standards for drug development and safety. These regulations directly shape software requirements for electronic submissions and pharmacovigilance. Compliance with GxP (Good Practice) guidelines is a fundamental prerequisite for market access. Consequently, vendor selection increasingly depends on a platform's ability to support multi-jurisdictional compliance and integrate seamlessly with other enterprise systems.
Market Dynamics
The central force shaping the market is the ongoing consolidation within the biopharmaceutical industry. As large pharmaceutical companies acquire smaller biotech firms, there is a heightened need for scalable, enterprise-level software platforms that can integrate disparate research, clinical, and regulatory data streams.
Growth Catalysts
- Decentralized Trial Guidance:Regulatory support from the FDA and EMA for decentralized clinical trials is creating direct demand for software platforms capable of remote data capture, patient monitoring, and electronic consent management.
- CRO Adoption:Contract Research Organizations are rapidly adopting advanced software to manage increasingly complex, multi-site global trials, seeking efficiency gains and improved data quality to serve their pharmaceutical clients.
- AI in Drug Discovery:The application of artificial intelligence and machine learning for target identification and lead optimization necessitates sophisticated software to process and analyze vast biological and chemical datasets.
Market Restraints
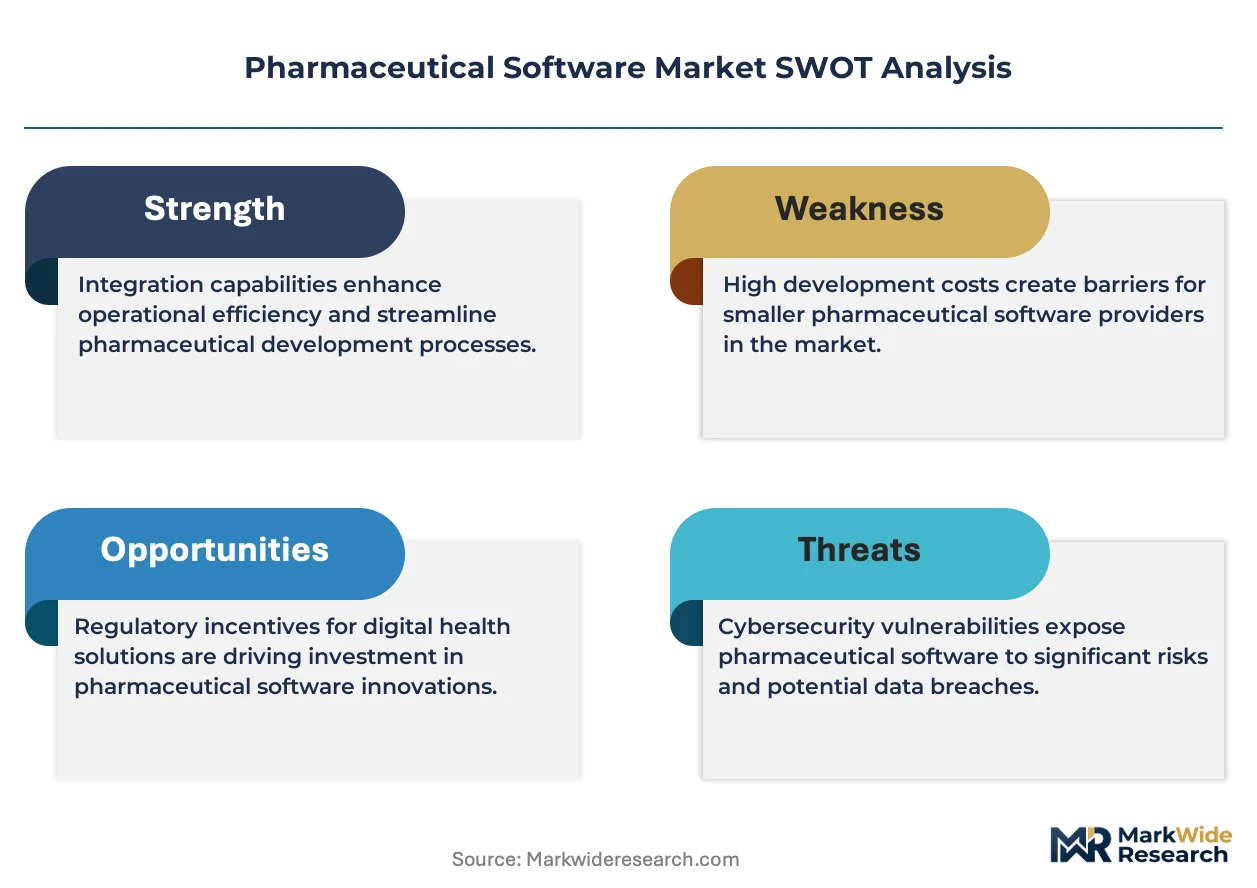
- High Validation Costs:The significant expense and time required to validate software to meet GxP and 21 CFR Part 11 compliance standards create a high barrier to entry and slow down implementation cycles.
- Interoperability Challenges:A lack of universal data standards across the industry hinders seamless integration between different software systems, such as EMR, CTMS, and EDC, creating data silos.
- Data Security Risks:The high value of clinical trial data and intellectual property makes pharmaceutical software a prime target for cyberattacks, requiring substantial and continuous investment in advanced security measures.
Strategic Opportunities
- Real-World Evidence Platforms:There is a growing opportunity for software that can aggregate and analyze real-world data from sources like electronic health records and wearables to support post-market surveillance and label expansion.
- Cell and Gene Therapy:Specialized software is needed to manage the complex, highly personalized manufacturing and supply chain logistics (chain of custody) for emerging cell and gene therapies.
- Blockchain for Data Integrity:The convergence of blockchain technology with clinical trial management systems offers a new method for ensuring immutable audit trails and enhancing data traceability, a key concern for regulators.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals with combined expertise in life sciences, regulatory affairs, and software engineering constrains vendor development and in-house implementation by pharma companies.
- Legacy System Modernization:Large pharmaceutical organizations face significant operational friction and cost when attempting to migrate from aging, on-premises legacy systems to modern, cloud-based software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Software Market |
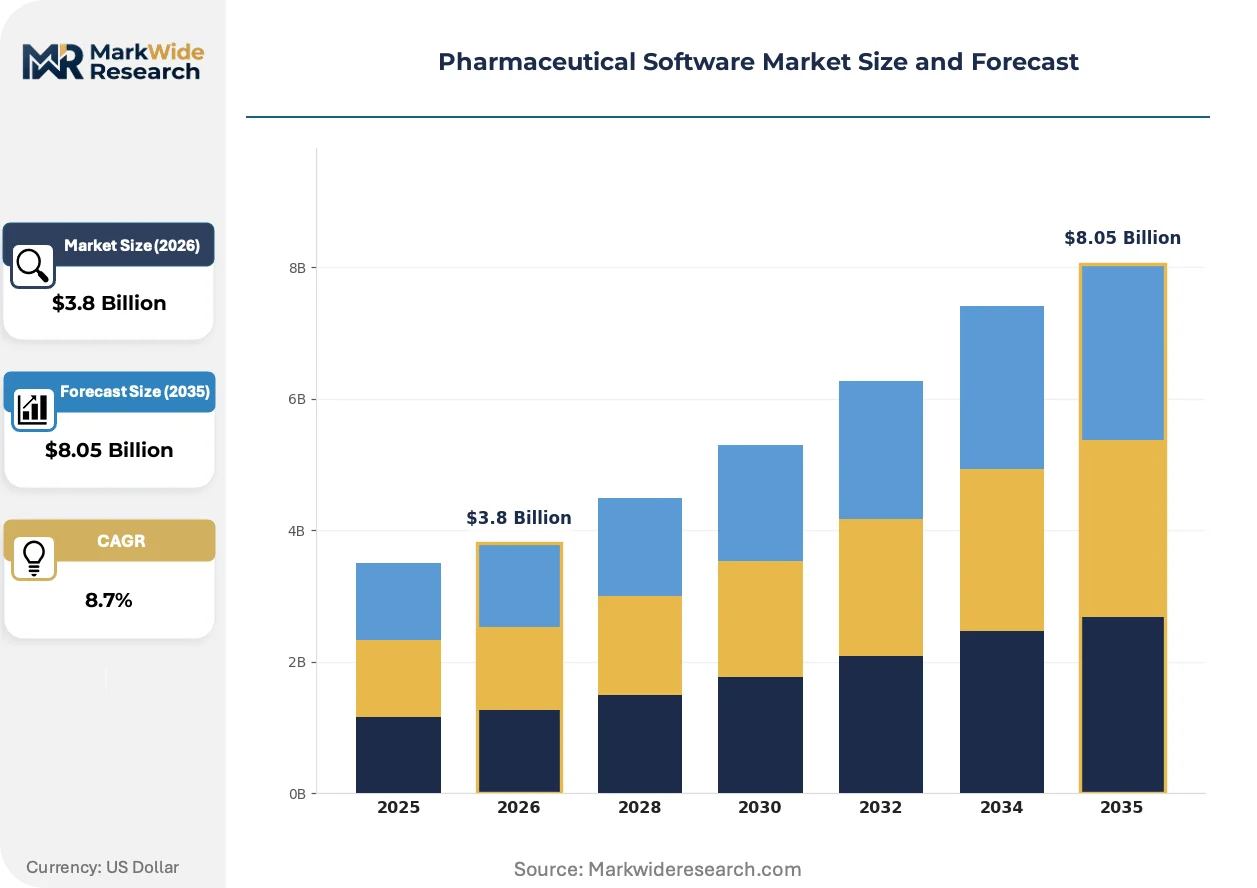
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Laboratory Information Management, Clinical Trial Management, Regulatory Compliance, Drug Safety Monitoring, Pharmacovigilance Deployment Model: On-Premises, Cloud-Based, Hybrid, Software as a Service, Hosted Solutions Application Area: Preclinical Research, Clinical Development, Post-Market Surveillance, Quality Assurance, Manufacturing Execution End User: Pharmaceutical Companies, Contract Research Organizations, Biotech Firms, Regulatory Agencies, Academic Institutions |
| Companies Covered | Epic Systems, athenahealth, Veeva Systems, Avenga, Accenture, IQVIA, GE HealthCare, eClinical Solutions, Oracle Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Software Market Strategic Shifts & Innovations
The evolution of pharmaceutical software is reshaping operational models, moving from siloed, function-specific tools toward integrated, intelligent platforms. This shift addresses demands for greater efficiency and data continuity across the entire drug development and commercialization lifecycle.
Artificial intelligence algorithms are being developed for predictive analytics in clinical trial design and patient stratification. Contract Research Organizations and large biopharma companies are adopting these tools to optimize study protocols and improve success rates. This technology is integrating with existing Clinical Trial Management Systems to enable more adaptive and efficient trial execution.
Regulatory frameworks are a primary influence on software design. The FDA's focus on data integrity and the EMA's Clinical Trials Regulation (CTR) mandate robust audit trails and centralized reporting capabilities. This directly impacts pharmacovigilance and clinical data management software, which must provide compliant electronic submission formats for agencies like Japan's PMDA.
A notable behavioral shift involves the move from perpetual software licenses toward subscription-based models. Buyers, especially small to mid-sized biotechs, are opting for Software as a Service (SaaS) to avoid large upfront capital outlays and gain scalability. This trend is most visible in North America and Europe, where a vibrant startup ecosystem requires flexible, cost-effective technology solutions.
Pharmaceutical Software Market Segmentation
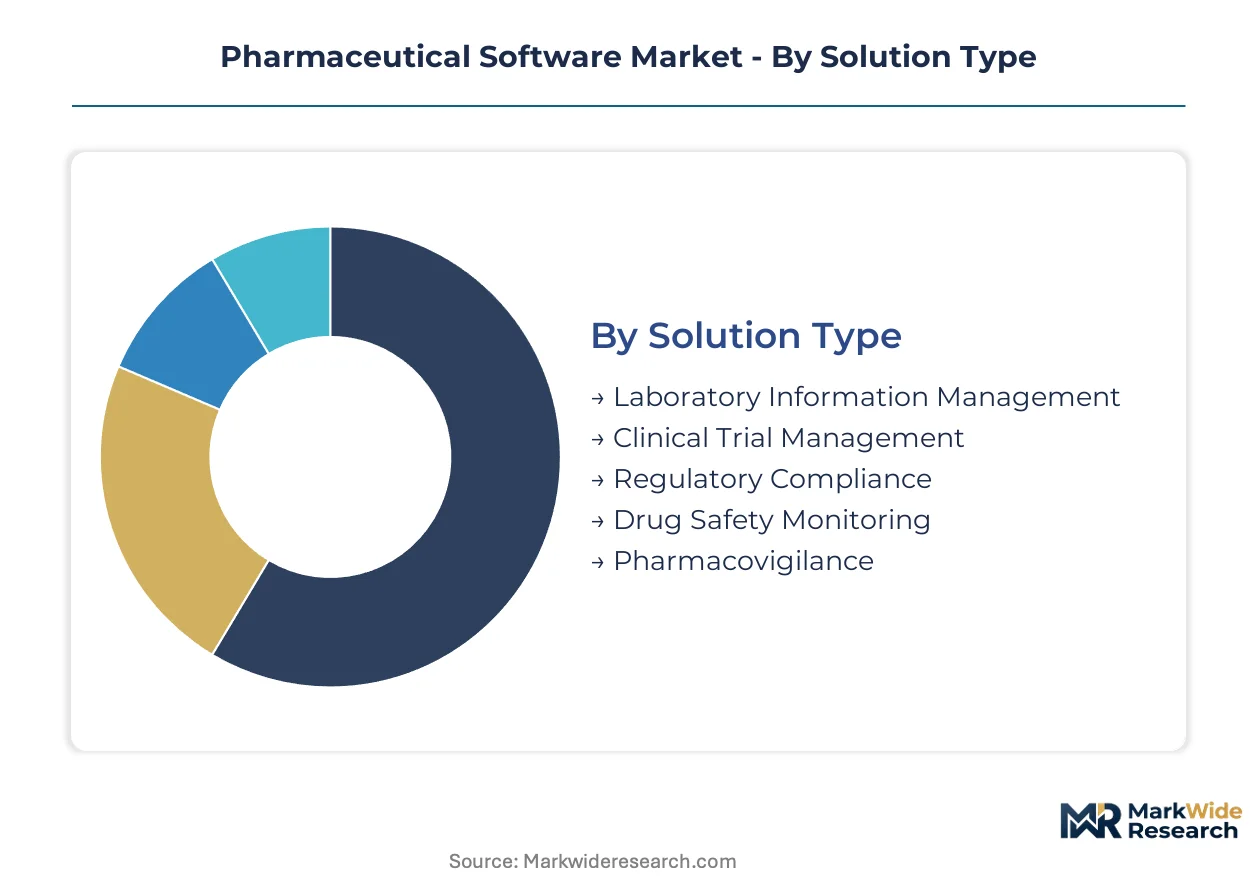
The pharmaceutical software market serves diverse operational needs across the drug development lifecycle. Understanding market segmentation provides crucial insights into specialized demand patterns and technological adoption within this complex industry. This analysis breaks down the market by solution type, deployment model, application area, and end user.
Solution Type:
Upgrading legacy systems drives significant investment in specific solution types, as organizations seek to replace outdated tools with more integrated and compliant platforms.
- Clinical Trial Management:These platforms manage the entire lifecycle of clinical studies, from planning and patient enrollment to data collection and reporting. Demand concentrates in the United States and Europe due to the high volume of complex, multi-site global trials.
- Pharmacovigilance:Software in this category focuses on collecting, monitoring, assessing, and preventing adverse drug reactions throughout a product's lifecycle. Post-market safety requirements from the FDA and EMA drive continuous platform enhancements.
- Laboratory Information Management:This software manages lab samples, experiments, and results, ensuring data integrity and traceability within research and development.
- Regulatory Compliance:These tools assist pharmaceutical companies in adhering to global regulatory standards like 21 CFR Part 11 and GxP guidelines for electronic records and submissions.
- Drug Safety Monitoring:Dedicated systems track and analyze safety data from various sources, supporting proactive risk management and regulatory reporting.
Clinical Trial Management sits at the top of the volume ranking, with Pharmacovigilance climbing the fastest.
Deployment Model:
The choice of deployment model often reflects an organization's IT infrastructure strategy and its approach to scalability and operational expenditure.
- Cloud-Based:This model delivers software over the internet, offering flexible access and reducing the need for extensive on-premises hardware and maintenance. Small to mid-sized biotechs in North America increasingly favor this approach for its agility.
- Software as a Service:SaaS solutions provide fully managed applications accessible via a subscription model, eliminating upfront capital outlays and simplifying IT management. This model is gaining significant traction across Europe due to its cost-effectiveness and scalability.
- On-Premises:Traditional on-premises installations require software and infrastructure to be hosted and maintained within the client's own data centers. Large pharmaceutical companies with stringent data control requirements historically preferred this model.
- Hybrid:Hybrid models combine elements of both on-premises and cloud deployments, allowing organizations to store sensitive data locally while leveraging cloud resources for other functions. This approach offers a balance between control and flexibility.
- Hosted Solutions:These involve a third-party provider hosting the software applications on their servers, often providing more customization than pure SaaS but less control than on-premises.
Cloud-Based deployment models hold the largest share, with Software as a Service solutions experiencing the steepest expansion trajectory.
Application Area:
Software adoption varies significantly across different stages of the drug development lifecycle, each requiring specialized functionalities for data management and process automation.
- Clinical Development:This segment encompasses software used during human clinical trials, including patient recruitment, data capture, and trial management. Regulatory guidance from the FDA and EMA for decentralized trials drives demand in this area.
- Post-Market Surveillance:Software here supports the ongoing monitoring of drug safety and efficacy after commercial launch, including adverse event reporting and real-world evidence collection. Compliance with global pharmacovigilance regulations is a primary driver.
- Preclinical Research:Tools in this area support early-stage drug discovery, target identification, and lead optimization, often integrating AI and machine learning capabilities.
- Quality Assurance:Software for quality assurance ensures compliance with GxP guidelines and other quality standards throughout the manufacturing and development processes.
- Manufacturing Execution:These systems manage and monitor pharmaceutical production processes, optimizing efficiency and ensuring product quality and batch traceability.
Clinical Development applications command the largest market share, while Post-Market Surveillance solutions are gaining share fastest.
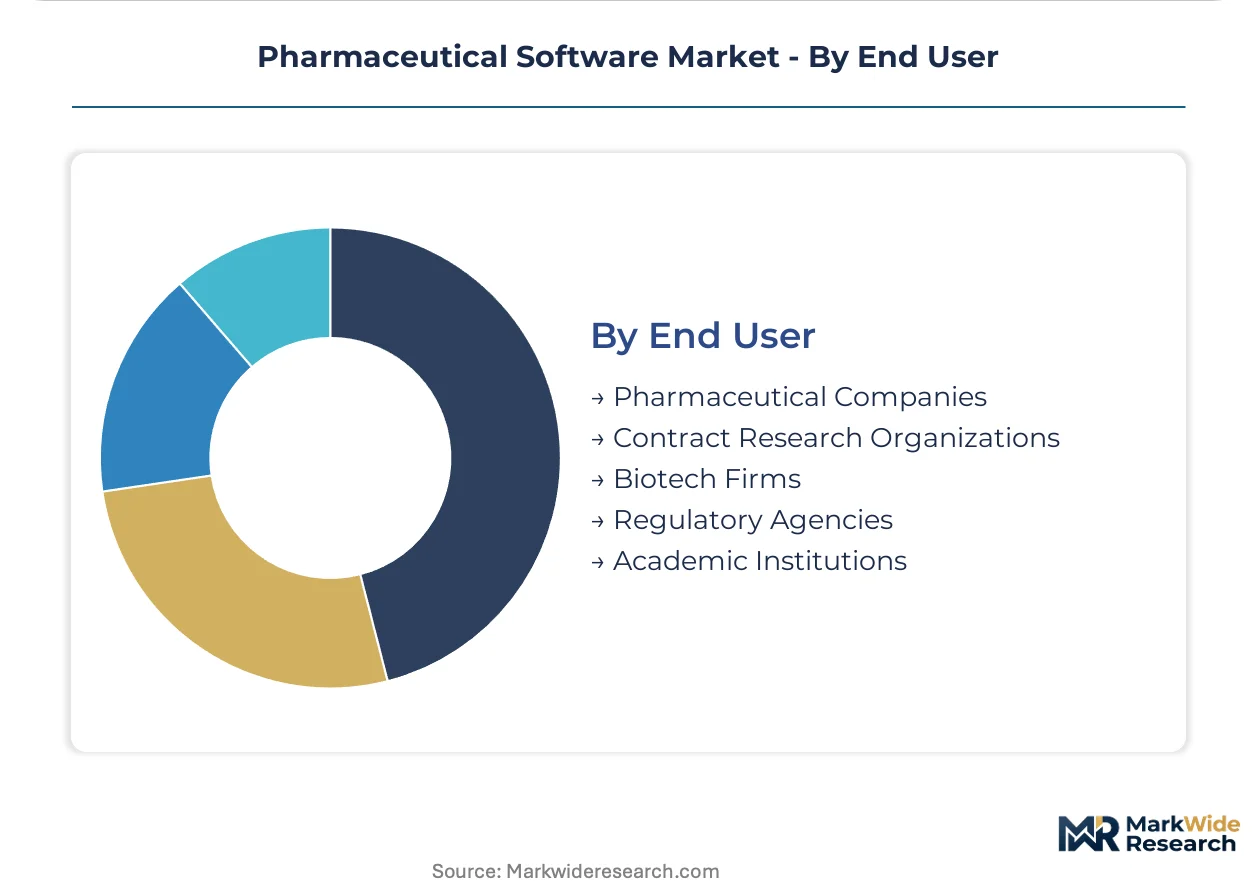
End User:
Different end-user segments exhibit distinct procurement behaviors and functional requirements, influencing software vendor specialization and product development.
- Pharmaceutical Companies:Large pharmaceutical organizations demand enterprise-level integrated solutions for managing complex global operations across research, clinical, and commercial functions. Market consolidation among these firms drives demand for scalable platforms.
- Contract Research Organizations:CROs utilize advanced software to manage increasingly complex, multi-site global trials for their pharmaceutical clients, seeking efficiency gains and improved data quality. Their rapid adoption is a major growth catalyst.
- Biotech Firms:Smaller biotech firms often opt for flexible, cloud-based SaaS solutions to avoid large upfront capital outlays and gain scalability for their specialized research and development efforts.
- Regulatory Agencies:These governmental bodies use software for managing submissions, monitoring compliance, and processing safety data from pharmaceutical companies.
- Academic Institutions:Universities and research centers employ pharmaceutical software for preclinical research, drug discovery, and managing smaller-scale clinical studies.
Pharmaceutical Companies represent the largest end-user segment, with Contract Research Organizations showing strong growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives significant demand for pharmaceutical software due to its large biopharmaceutical research ecosystem, Germany's market expansion is shaped by stringent data privacy and compliance mandates. These regional differences influence software adoption patterns and vendor specialization across various solution types. Regulatory frameworks from agencies like the FDA and EMA directly impact software requirements.
United States
The United States exhibits strong demand for advanced pharmaceutical software, driven by its extensive biopharmaceutical research and development activities. FDA guidance for decentralized clinical trials necessitates sophisticated platforms for remote data capture and electronic consent. The Boston/Cambridge biotech hub actively adopts AI and machine learning tools for target identification and lead optimization.
Germany
Germany's pharmaceutical software market is influenced by a robust manufacturing sector and stringent GxP compliance requirements. The EMA's Clinical Trials Regulation (CTR) mandates robust audit trails and centralized reporting, shaping software design. The Frankfurt/Rhine-Main region, a pharmaceutical cluster, increasingly seeks integrated enterprise solutions for data management.
Japan
Japan's market for pharmaceutical software is expanding due to an aging population and a focus on post-market surveillance. The PMDA's electronic submission formats directly impact regulatory compliance software. Major pharmaceutical companies in Tokyo are investing in AI-driven platforms to enhance drug discovery and development processes.
China
China experiences rapid growth in pharmaceutical software adoption, fueled by an expanding drug development pipeline and market access initiatives. The NMPA's stringent data management and reporting standards drive demand for compliant solutions. Shanghai's biopharmaceutical parks are modernizing legacy systems with cloud-based and SaaS offerings.
India
India's pharmaceutical software market is propelled by a burgeoning Contract Research Organization sector and significant generic drug manufacturing capabilities. CDSCO guidelines for clinical trials require robust data integrity and traceability features. Hyderabad's Pharma City leverages cloud-based solutions to manage complex multi-site global trials efficiently.
Pharmaceutical Software Market Key Industry Players
North American technology firms anchor one tier of the pharmaceutical software market, while European providers often specialize in regional compliance solutions. The market structure is tiered, featuring large enterprise solution providers alongside niche specialists offering targeted functionalities. Strategic archetypes include comprehensive platform providers, specialized regulatory compliance vendors, and data analytics-focused companies. Dominant competitive moves involve strategic partnerships for market access and mergers and acquisitions for portfolio expansion.
Within the enterprise-level integration archetype, Veeva Systems exemplifies cloud-based solutions for life sciences, covering clinical, regulatory, and commercial functions. IQVIA, leveraging extensive data assets, represents analytics and trial management platforms. Oracle Health sits within the large-scale enterprise deployment segment, offering database management and clinical trial software for complex organizational needs.
| Leading Market Players |
|---|
| Epic Systems |
| athenahealth |
| Veeva Systems |
| Avenga |
| Accenture |
| IQVIA |
| GE HealthCare |
| eClinical Solutions |
| Oracle Health |
| Others |
Cost & Logistics Intelligence
Specialized software engineers concentrated in North American and European tech hubs drive higher labor costs, directly influencing premium pricing tiers for advanced pharmaceutical software solutions. This talent concentration creates a competitive advantage for vendors able to attract and retain top-tier development teams.
Pricing Analysis
Capacity additions in India's IT services sector are reshaping price floors, particularly for custom development and maintenance contracts. Subscription-based SaaS models dominate the market, offering flexible access and reducing upfront capital outlays for buyers. Price differentiation stems from the level of customization required and the depth of regulatory compliance certifications, such as FDA 21 CFR Part 11. Pricing softness reflects intense competition among cloud-based providers, especially for standard functionalities. Small-to-mid-sized biotech firms exhibit the highest price sensitivity, often favoring cost-effective SaaS options.
Supply Chain Analysis
The cost of secure data transmission and cloud infrastructure forms a significant component of the pharmaceutical software supply chain. Geographic supply concentration for software development talent centers on the United States, Ireland, and India. Key dependencies include highly skilled software developers and robust cloud hosting services from providers like Amazon Web Services or Microsoft Azure. Data security breaches represent a critical structural risk, necessitating continuous investment in advanced cybersecurity measures. Distribution runs primarily through direct sales channels and strategic partnerships with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical software market functions as a stable compounder, driven by the continuous digital transformation mandated by evolving regulatory frameworks in drug development. This enduring shift provides a resilient foundation for sustained expansion.
For Market Incumbents: Deepen platform integration capabilities across clinical, regulatory, and commercial functions to meet the demand for enterprise-level solutions. Focus on embedding advanced AI and machine learning tools into existing offerings to counter the threat from specialized niche providers. Investing in robust GxP compliance features and interoperability standards strengthens market position against emerging competitors. Strategic acquisitions of smaller firms with innovative technologies can accelerate portfolio expansion.
For New Entrants and Emerging Players: Specialized system integrators offer a viable entry point for new software vendors targeting the pharmaceutical sector. Focus on white-space opportunities such as real-world evidence platforms or highly specialized software for cell and gene therapy manufacturing logistics. The small-to-mid-sized biotech segment in North America and Europe remains highly penetrable due to its preference for flexible, cost-effective SaaS solutions. A go-to-market strategy emphasizing rapid deployment and demonstrable ROI will resonate with these agile firms.
For Investors and Strategic Acquirers: Large pharmaceutical companies are the most active acquirers in this space, seeking to enhance their digital capabilities and streamline operations. The market exhibits long-term viability given the essential nature of software in drug discovery, clinical trials, and regulatory compliance over the next decade. Target niche solution providers with strong intellectual property in high-growth areas like AI-driven drug discovery or blockchain for data integrity. Increased M&A activity by large technology firms entering the healthcare sector signals market consolidation and future growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate data streams, enhancing operational efficiency and regulatory compliance across the drug lifecycle. |
| AI/ML Product Development | Accelerates drug discovery and optimizes clinical trial design, improving success rates for pharmaceutical companies. |
| Regulatory Compliance Enhancement | Ensures adherence to evolving global standards like FDA 21 CFR Part 11 and EMA CTR, crucial for market access. |
| Strategic Partnership | Expands market reach and combines complementary expertise, particularly for specialized functionalities or geographic penetration. |
| Geographic Expansion | Captures new demand in rapidly growing markets like China and India, leveraging local regulatory knowledge. |
Research Approach
Bottom-up pharmaceutical company modeling reconciled against top-down software vendor tracking forms the analytical core of this study. This approach combines primary interviews with industry stakeholders, including R&D executives, clinical trial managers, regulatory affairs specialists, and IT procurement officers. Secondary validation draws from sources such as FDA filings, EMA guidance documents, ClinicalTrials.gov, and relevant industry association reports.
An input-output matrix underpins the forecast framework, systematically mapping market dynamics over the projection horizon. Segmentation dimensions modeled include solution type, deployment model, application area, end user, and regional regulatory clusters. Compound annual growth rates are derived through regression analysis and expert consensus, incorporating key industry-specific forecast inputs like drug development pipeline size and regulatory approval rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rapid technological shifts and regulatory changes. All forecasts reflect assumptions regarding market evolution and stakeholder behavior. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Global Dental Software Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Healthcare AIDC Market