
 Asia-Pacific Healthcare Cold Chain Logistics Market | 2026-2036
Asia-Pacific Healthcare Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Healthcare Cold Chain Logistics Market Outlook
IoT-enabled real-time temperature monitoring is reconfiguring pharmaceutical transport protocols across the Asia-Pacific region. DHL Group leverages its integrated sensor networks to sustain end-to-end visibility for vaccine shipments. Nippon Express anchors Japanese biologics distribution through specialized pharmaceutical facilities in Osaka and Tokyo. SF Express dominates last-mile cold delivery in China's tier-one cities with proprietary refrigerated fleet infrastructure.
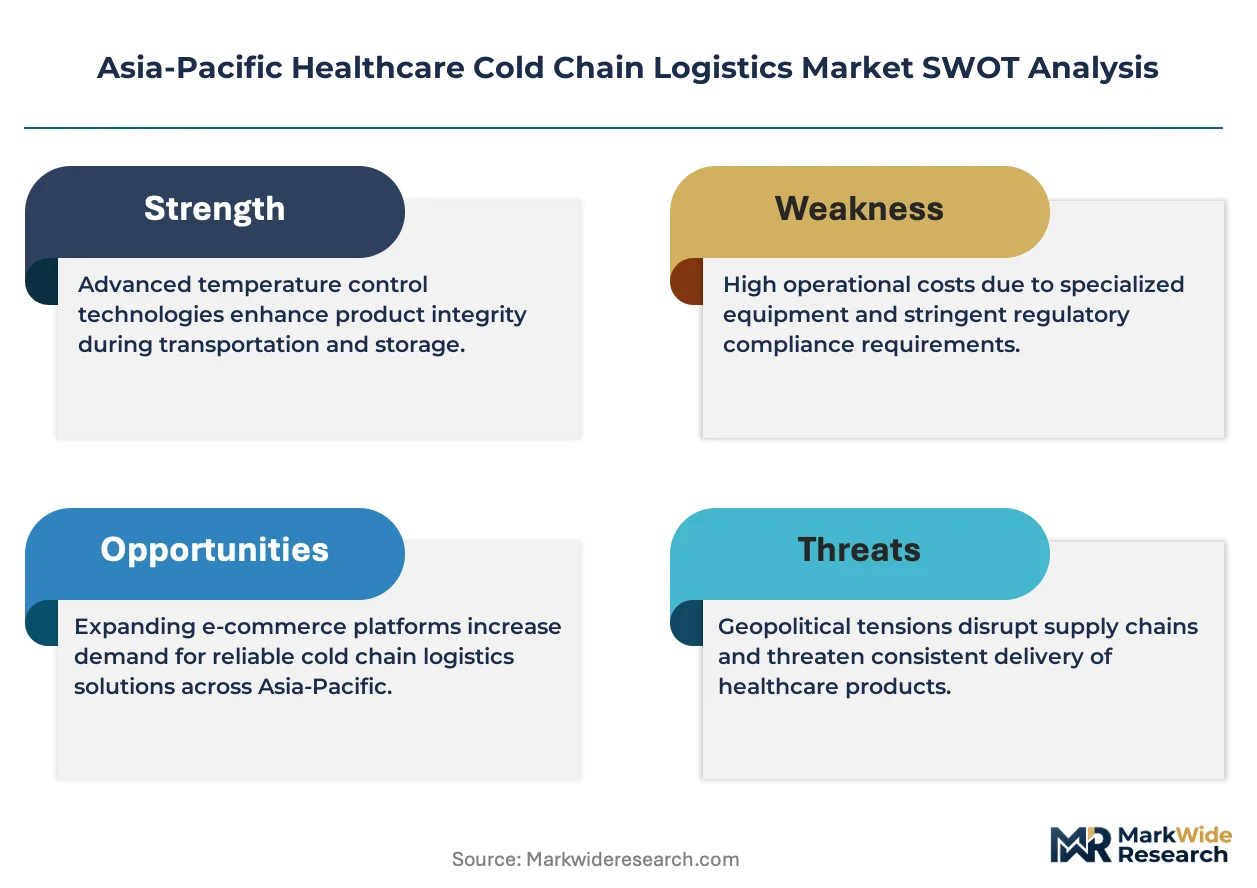
Healthcare cold chain logistics encompasses the temperature-controlled storage, handling, and distribution of pharmaceutical products, vaccines, blood products, and biologics within a specified range, typically 2°C to 8°C for standard vaccines and -80°C for certain mRNA therapeutics, ensuring product efficacy from manufacture to patient administration. Biologics represent the fastest-expanding product category as cell and gene therapies require cryogenic handling protocols that command premium service margins. Air delivery mode captures the highest value per kilogram for time-sensitive shipments, while road transport handles the volume base for domestic distribution networks across archipelagic and continental geographies.
Japan's PMDA enforces stringent GDP guidelines that mandate continuous temperature documentation for imported pharmaceuticals, while Australia's TGA requires cold chain validation studies for all vaccine distribution pathways. India's CDSCO has tightened traceability requirements under revised Schedule M provisions, compelling logistics providers to upgrade monitoring infrastructure. Stakeholders must evaluate which regulatory convergence patterns between national health authorities will create compliance barriers or standardization opportunities for cross-border pharmaceutical movements.
Market Dynamics
IoT-enabled temperature monitoring systems are compressing response times for pharmaceutical excursions across the Asia-Pacific region, while biologics manufacturers demand cryogenic handling capabilities that reconfigure fleet and warehouse infrastructure requirements.
Growth Catalysts
- MFDS cold chain certification mandates:South Korea's pharmaceutical regulator now requires validated thermal packaging for all temperature-sensitive exports, accelerating investment in qualified container systems.
- Cell therapy manufacturing expansion:Biologics producers in Singapore and Australia are scaling cryogenic storage networks to support autologous treatment workflows.
- China's pharmaceutical corridor concentration:Demand clusters along the Shanghai-Beijing axis are driving dedicated cold chain lane development with specialized handling protocols.
Market Restraints
- Liquid nitrogen supply volatility:Cryogenic logistics depend on concentrated industrial gas production that faces periodic shortage events in Southeast Asian markets.
- Refrigerated fleet capital intensity:Specialized vehicle procurement and maintenance requirements create barrier thresholds that limit mid-tier logistics provider participation.
- Cross-border customs harmonization gaps:Divergent documentation requirements between CDSCO, PMDA, and TGA protocols generate clearance friction for multi-country distribution networks.
Strategic Opportunities
- Vietnam and Indonesia biopharma manufacturing:Emerging production hubs in these markets lack mature cold chain infrastructure, creating first-mover positioning for integrated service providers.
- mRNA vaccine platform standardization:Ultra-low temperature handling protocols developed during pandemic response are now applicable to oncology and infectious disease pipelines.
- Blockchain-IoT convergence:Immutable temperature logging combined with real-time sensor networks enables outcome-based service contracting with pharmaceutical manufacturers.
Industry Challenges
- Cryogenic technician certification timelines:Specialized handling of cell therapies requires trained personnel whose qualification programs create workforce pipeline constraints.
- Legacy warehouse retrofit requirements:Existing ambient facilities face structural limitations for installing validated cold rooms with redundant backup systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Healthcare Cold Chain Logistics Market |
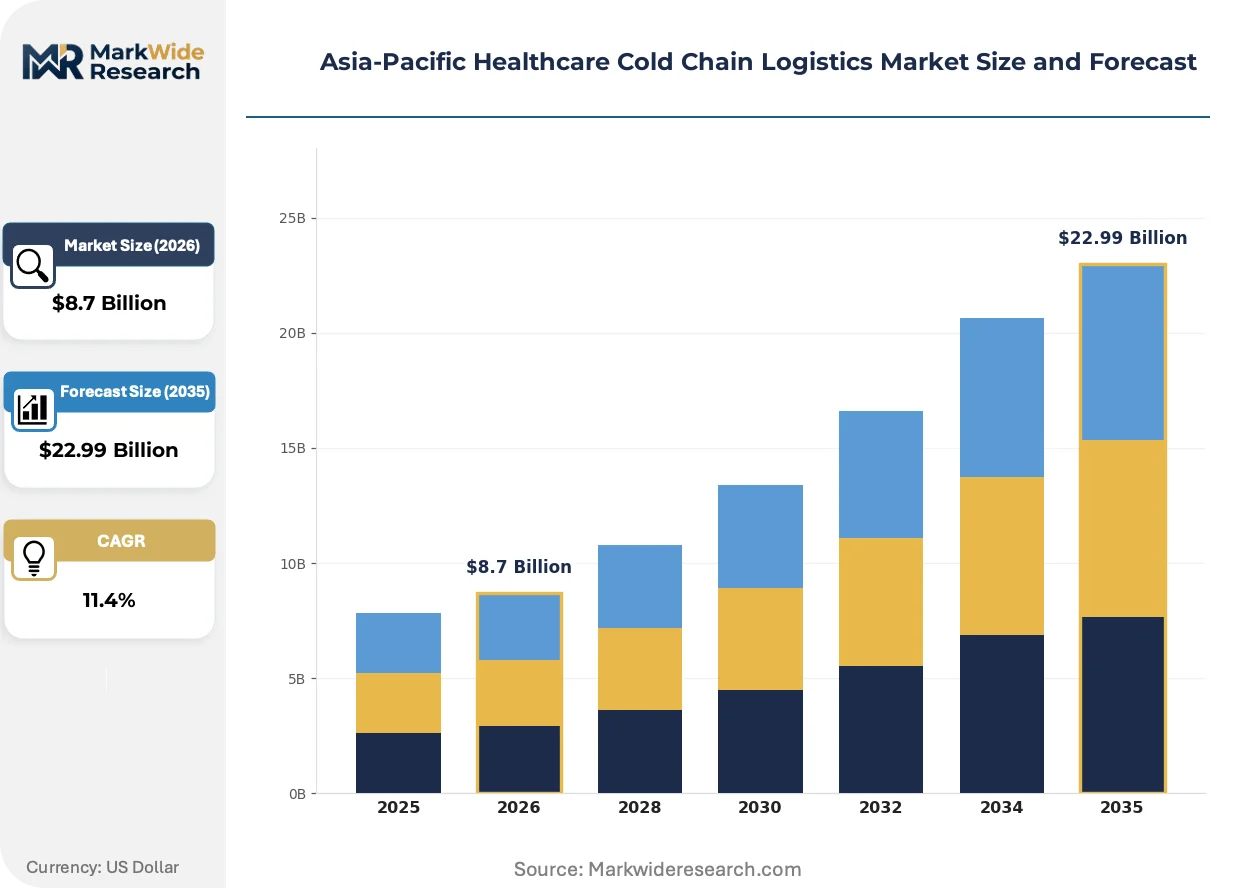
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Vaccines, Blood Products, Biologics Delivery Mode: Rail, Air, Sea, Road End User: Hospitals, Clinics, Pharmacies, Research Institutes Packaging Type: Insulated Containers, Thermoscontainers, Refrigerated Trucks, Cold Boxes |
| Companies Covered | DHL Group, Yusen Logistics, SF Express, JWD Group, Nippon Express, CEVA Logistics, FedEx Corporation, Cardinal Health, Kuehne+Nagel, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Healthcare Cold Chain Logistics Market Strategic Shifts
Digital traceability infrastructure is displacing paper-based documentation across pharmaceutical supply chains, while regulatory authorities tighten validation requirements for temperature excursion investigations.
Passive thermal packaging with phase-change materials is migrating from international air freight to domestic road distribution as biologics manufacturers seek to reduce single-use shipping container costs across shorter haul distances. Pharmaceutical distributors in Australia and Japan are piloting reusable PCM systems for inter-city vaccine movements. This technology is compressing per-shipment packaging expenditures while maintaining GDP compliance.
CDSCO's revised Schedule M provisions now mandate electronic temperature logging for all vaccine transport within India, compelling logistics providers to deploy integrated monitoring hardware. The regulation affects both domestic distributors and international shippers serving Indian import channels. Cold chain operators are responding by consolidating sensor vendor relationships to streamline validation documentation.
Hospital and clinic procurement of cold chain services is consolidating toward integrated logistics contracts that bundle storage, transport, and last-mile delivery under single-provider accountability. This displaces fragmented arrangements where pharmacies managed separate warehousing and courier relationships. The shift is most pronounced in China's tier-one cities where health system consolidation has concentrated buying power.
Asia-Pacific Healthcare Cold Chain Logistics Market Segmentation
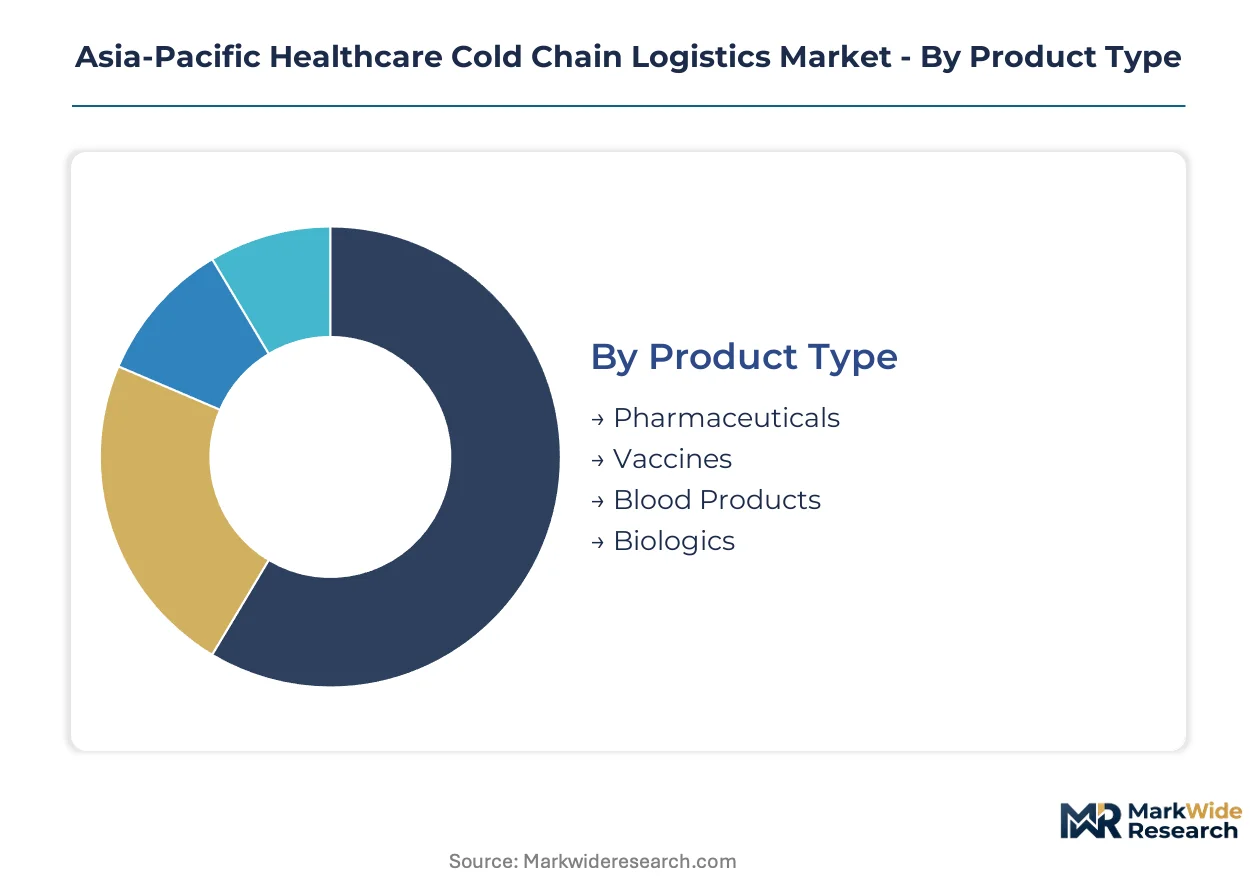
Healthcare cold chain logistics demands granular segmentation because temperature requirements vary dramatically across product categories and transport distances. Pharmaceutical manufacturers configure supply chains differently for cryogenic biologics versus standard 2-8°C vaccines, while delivery mode selection hinges on regulatory urgency and infrastructure maturity across the Asia-Pacific region.
Product Type:
Application determines handling protocols, with each product category commanding distinct equipment specifications and certification requirements.
- Pharmaceuticals:Small-molecule drugs requiring 15-25°C controlled ambient conditions dominate shipment volumes across domestic distribution networks. India's CDSCO mandates continuous temperature documentation for all pharmaceutical movements, compelling logistics providers to deploy sensor infrastructure even for less stringent thermal profiles.
- Vaccines:Standard 2-8°C cold chain products represent the volume anchor for regional immunization programs and private healthcare channels. China's pharmaceutical corridor linking Shanghai to Beijing concentrates vaccine distribution demand, with provincial CDCs consolidating procurement toward integrated logistics contracts.
- Blood Products:Plasma derivatives and whole blood require validated cold chain with temperature alarms and redundant backup systems. Japanese Red Cross facilities in Osaka and Tokyo maintain specialized blood product warehouses with PMDA-certified GDP compliance.
- Biologics:Cell and gene therapies demand cryogenic handling at -150°C to -196°C using liquid nitrogen vapor phase storage. Singapore's biologics manufacturing expansion is driving investment in cryogenic technician training programs and specialized fleet infrastructure.
Pharmaceuticals hold installed capacity. Biologics is rotating up the share rankings.
Delivery Mode:
Cost tier and speed requirements segment transport selection, with premium air freight commanding margins against road volume economics.
- Rail:Bulk pharmaceutical movements between Chinese manufacturing hubs leverage refrigerated rail cars for cost-efficient long-haul distribution. The Shanghai-Beijing pharmaceutical corridor has established dedicated cold chain rail services with validated thermal mapping.
- Air:Time-sensitive biologics and emergency vaccine shipments capture premium pricing per kilogram through temperature-controlled cargo holds and qualified container systems. Australia's TGA requires air freight validation studies for all temperature-sensitive imports, adding compliance layers to international movements.
- Sea:Ocean freight handles non-urgent pharmaceutical bulk with reefers and passive thermal containers for intercontinental lanes. Port infrastructure limitations in Southeast Asian markets create bottlenecks for sea-borne cold chain, constraining modal share expansion.
- Road:Last-mile delivery and domestic distribution networks rely on refrigerated fleet infrastructure with real-time GPS and temperature monitoring. SF Express dominates tier-one Chinese cities with proprietary refrigerated vehicles, while Nippon Express anchors Japanese pharmaceutical road distribution.
Road transport holds installed capacity. Air freight is rotating up the share rankings.
End User:
Customer type determines service bundling complexity, with consolidated health systems demanding integrated accountability versus fragmented independent channels.
- Hospitals:Large health systems in China's tier-one cities are consolidating cold chain procurement under single-provider contracts covering storage, transport, and last-mile delivery. Hospital pharmacy departments require validated receiving protocols with temperature excursion investigation capabilities.
- Clinics:Outpatient facilities generate dispersed demand for smaller shipment quantities with flexible delivery windows. India's CDSCO Schedule M provisions now mandate electronic temperature logging for all vaccine deliveries to clinic endpoints, eliminating paper-based documentation.
- Pharmacies:Retail and hospital-affiliated dispensaries require frequent replenishment of temperature-sensitive inventory with short shelf-life products. Australian pharmacy chains are piloting reusable phase-change material systems for inter-city vaccine movements to reduce packaging costs.
- Research Institutes:Clinical trial logistics and cell therapy manufacturing facilities demand cryogenic handling with chain-of-custody documentation. Singapore and Australian research hubs are scaling autologous treatment workflows requiring specialized biorepository partnerships.
Hospitals hold installed capacity. Research institutes are rotating up the share rankings.
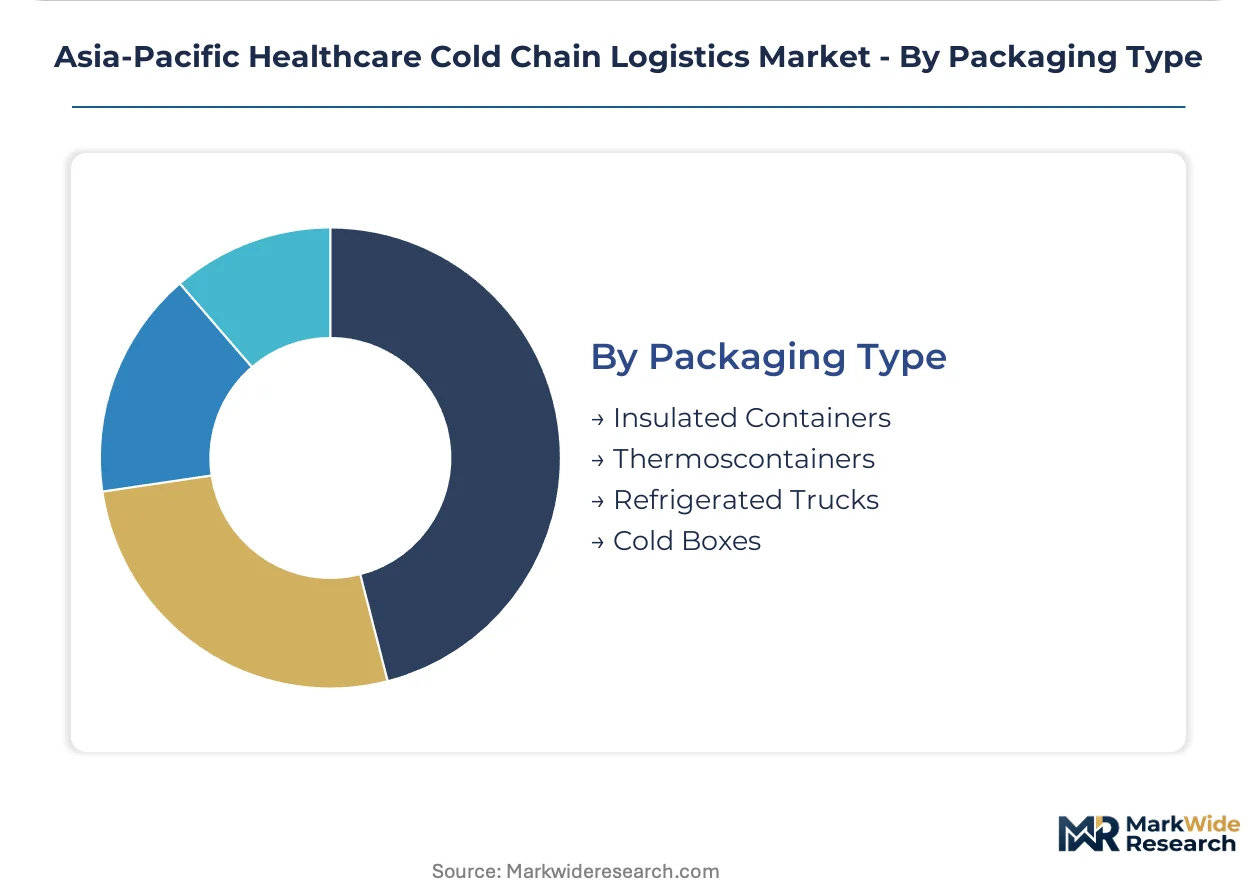
Packaging Type:
Maturity and reusability dimensions segment packaging selection, with passive systems gaining traction for cost reduction across shorter haul distances.
- Insulated Containers:Polystyrene and polyurethane boxes with gel packs provide economical short-duration protection for 2-8°C products. Domestic vaccine distribution in India and Southeast Asia relies heavily on insulated containers for last-mile segments where mechanical refrigeration is unavailable.
- Thermoscontainers:Vacuum-insulated vessels with phase-change materials extend thermal protection duration for international air freight and remote deliveries. Japanese pharmaceutical distributors are piloting reusable thermoscontainer systems for inter-city movements to comply with PMDA GDP guidelines.
- Refrigerated Trucks:Mechanically refrigerated vehicles with redundant compressor systems handle high-volume pharmaceutical distribution across established road networks. Fleet capital intensity creates barrier thresholds limiting mid-tier logistics provider participation in this segment.
- Cold Boxes:Passive cooling devices with ice packs or conditioned cold plates serve outreach immunization programs and emergency response scenarios. WHO-prequalified cold boxes remain essential for vaccine campaigns in archipelagic geographies with limited cold chain infrastructure.
Insulated containers hold installed capacity. Thermoscontainers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows across Asia-Pacific cold chain networks concentrate pharmaceutical movements between manufacturing hubs in China, India, and South Korea, with import demand anchoring in Australia and Japan where domestic biologics production remains insufficient for therapeutic consumption.
China
Domestic vaccine distribution and biologics manufacturing anchor cold chain demand along the Shanghai-Beijing pharmaceutical corridor. NMPA mandates electronic temperature documentation for all temperature-sensitive pharmaceutical imports, compelling logistics providers to deploy integrated monitoring infrastructure. Provincial CDCs in Jiangsu and Zhejiang provinces are consolidating procurement toward single-provider contracts covering storage through last-mile delivery.
Japan
Imported biologics and cell therapies drive premium cold chain service demand as domestic manufacturing concentrates on small-molecule pharmaceuticals. PMDA enforces stringent GDP guidelines requiring continuous temperature validation for all imported temperature-sensitive products. Osaka and Tokyo maintain specialized pharmaceutical distribution facilities with certified cold rooms serving hospital and clinic networks.
India
Vaccine export manufacturing and domestic immunization programs generate parallel cold chain requirements across disparate infrastructure quality levels. CDSCO's revised Schedule M provisions mandate electronic temperature logging for all vaccine transport, eliminating paper-based documentation. Maharashtra and Gujarat pharmaceutical clusters are upgrading warehouse monitoring systems to comply with tightened traceability requirements.
South Korea
Biologics export manufacturing expansion is driving investment in qualified thermal packaging and cryogenic handling capabilities. MFDS now requires validated container systems for all temperature-sensitive pharmaceutical exports, accelerating certification programs for logistics providers. Seoul-Incheon biopharma corridor facilities are scaling liquid nitrogen vapor phase storage for cell therapy manufacturing workflows.
Australia
Import-dependent biologics consumption and clinical trial logistics sustain premium cold chain service demand across vast continental distances. TGA requires cold chain validation studies for all vaccine distribution pathways, adding compliance layers to international movements. Sydney and Melbourne pharmaceutical import gateways are consolidating toward integrated logistics contracts bundling customs clearance, storage, and hospital delivery.
Asia-Pacific Healthcare Cold Chain Logistics Market Competitive Environment
On the supply side, the industry is consolidating around integrated logistics providers capable of delivering end-to-end temperature accountability from manufacturing through patient administration. Three strategic archetypes dominate competitive positioning: global express networks with pharmaceutical certifications, regional specialists with cryogenic handling capabilities, and domestic road freight operators with proprietary refrigerated fleet infrastructure. Competitive moves concentrate on strategic partnerships with biologics manufacturers and geographic expansion into emerging biopharma production hubs lacking mature cold chain infrastructure.
Within the global integrated logistics tier, DHL Group and FedEx Corporation represent archetypes of sensor-enabled end-to-end visibility systems, while Nippon Express occupies a position exemplifying regional pharmaceutical specialization with certified GDP facilities. SF Express anchors the domestic-scale archetype with proprietary refrigerated fleet infrastructure concentrated in tier-one Chinese cities. These three company types collectively illustrate how competitive positioning stratifies across international express, regional pharmaceutical, and domestic road freight capabilities.
| Leading Market Players |
|---|
| DHL Group |
| Yusen Logistics |
| SF Express |
| JWD Group |
| Nippon Express |
| CEVA Logistics |
| FedEx Corporation |
| Cardinal Health |
| Kuehne+Nagel |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Beijing pharmaceutical corridor anchors regional cost dynamics, where concentrated biologics manufacturing capacity enables premium pricing power for cryogenic handling services while road freight operators compete on volume economics across shorter domestic lanes.
Pricing Analysis
Current-generation IoT-enabled sensor networks command premium service margins against prior-generation passive monitoring systems, while next-generation blockchain-IoT convergence platforms remain in pilot phases. Three-tier pricing structure across certified GDP-compliant, standard temperature-monitored, and basic insulated container services separates pharmaceutical manufacturers by risk tolerance and regulatory exposure. Pricing pressure stems from refrigerated fleet capital intensity as mid-tier logistics providers struggle to amortize specialized vehicle procurement across limited shipment volumes. Hospital procurement committees demonstrate highest price sensitivity for standard vaccine distribution, while cell therapy manufacturers accept premium cryogenic rates for validated chain-of-custody documentation.
Supply Chain Analysis
Tariff exposure between China and key export destinations dominates supply chain risk planning for temperature-sensitive pharmaceutical movements. Manufacturing concentration in China, India, and South Korea feeds regional distribution networks, while liquid nitrogen supply volatility in Southeast Asian markets creates periodic shortage events for cryogenic logistics. Raw material dependencies span phase-change materials for passive packaging, specialized refrigerants for mechanical systems, and industrial gases for vapor-phase storage. Distribution runs through integrated logistics contracts bundling storage, customs clearance, and last-mile delivery under single-provider accountability structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare cold chain logistics is approaching a platform-economics inflection as sensor-network interoperability standards enable outcome-based contracting between pharmaceutical manufacturers and logistics providers.
For Market Incumbents: Insulate core pharmaceutical corridors through backward integration into cryogenic technician training programs and certified GDP warehouse networks. DHL Group and Nippon Express demonstrate defensive positioning by consolidating sensor vendor relationships to streamline CDSCO, PMDA, and TGA validation documentation. Capacity addition in Vietnam and Indonesia biopharma manufacturing zones counters emerging entrant threats from regional specialists lacking cryogenic handling credentials. For New Entrants and Emerging Players: Mid-tier city hospital networks in India's Maharashtra and Gujarat pharmaceutical clusters represent the most penetrable entry point for domestic cold chain operators lacking international certification. Indonesia's archipelagic vaccine distribution gaps and Vietnam's emerging biologics manufacturing zones offer white-space positioning before infrastructure consolidation accelerates. Go-to-market execution should emphasize reusable phase-change material systems to compress per-shipment packaging costs against established insulated container incumbents. For Investors and Strategic Acquirers: Regional pharmaceutical specialists with certified GDP facilities and established biologics manufacturer relationships present acquisition targets with defensive moats against platform commoditization. Long-term viability across the analysis window hinges on regulatory convergence patterns between national health authorities creating either compliance barriers or standardization opportunities. The signal to watch is MFDS, CDSCO, and TGA mutual recognition agreement momentum as an inflection indicator for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Certification | MFDS-validated container systems unlock South Korean biologics export manufacturing contracts. |
| Blockchain-IoT Platform Integration | Immutable temperature logging enables outcome-based service contracting with pharmaceutical manufacturers. |
| Reusable Thermal Packaging Deployment | PCM systems compress per-shipment costs for PMDA-compliant inter-city vaccine movements in Japan. |
| Cryogenic Technician Training Programs | Singapore's autologous treatment workflows require qualified personnel pipelines for cell therapy logistics. |
| Integrated Logistics Contract Consolidation | China's provincial CDCs bundle storage, transport, and last-mile delivery under single-provider accountability. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold chain logistics directors, pharmaceutical regulatory affairs leads, hospital procurement managers, and biologics manufacturing supply chain executives. Secondary validation drew from CDSCO Schedule M filings, PMDA GDP inspection reports, TGA cold chain validation studies, and MFDS export certification databases. Bottom-up shipment volume modeling triangulated against top-down pharmaceutical production value estimates across the analysis window.
Calibration against historical regulatory implementation timelines and infrastructure investment cycles anchored the analytical framework. Segmentation dimensions spanned product type, delivery mode, end user, packaging type, and regional regulatory cluster complexity. CAGRs were derived from slope-intercept modeling of installed capacity expansion against demand growth trajectories, incorporating liquid nitrogen supply elasticity and refrigerated fleet depreciation schedules as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical trade policy, industrial gas pricing volatility, or healthcare procurement budget cycles would shift the trajectory. Forecasts reflect assumptions around regulatory harmonization momentum and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Transitional Care Management Services Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
Healthcare CRO Services Market
Healthcare Services
Global Retirement Home Services Market
Healthcare Services
US Care Services Market
Healthcare Services
United States Senior Living Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Funeral and Cremation Services Market
Healthcare Services
Audiology Services Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Medical Second Opinion Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
US Healthcare Staffing Market