
 US Medical Sector Contract Electronic Manufacturing Market | 2026-2036
US Medical Sector Contract Electronic Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Sector Contract Electronic Manufacturing Market Outlook
Mid-sized medical device startups is collapsing reliance on in-house manufacturing floors as capital efficiency pressures mount. Benchmark Electronics leverages captive cleanroom capacity across multiple US sites to anchor high-mix, low-volume production for Class II and III devices. Flex sustains R&D intensity through dedicated medical innovation centers that prototype next-generation diagnostic platforms. Jabil dominates high-volume consumables assembly, competing on automated PCB insertion lines that reduce labor content per unit.
US medical sector contract electronic manufacturing encompasses the outsourced production of printed circuit board assemblies, cable harnesses, and fully integrated electromechanical systems bound by biocompatibility, traceability, and sterilization compatibility requirements. Surface mount technology dominates output volume, though custom manufacturing commands superior margin pools due to engineering intensity and regulatory documentation burden. Diagnostic equipment applications lead revenue contribution within the product type dimension, while cardiology-focused box build assemblies represent the fastest-growing application segment as electrophysiology devices proliferate.
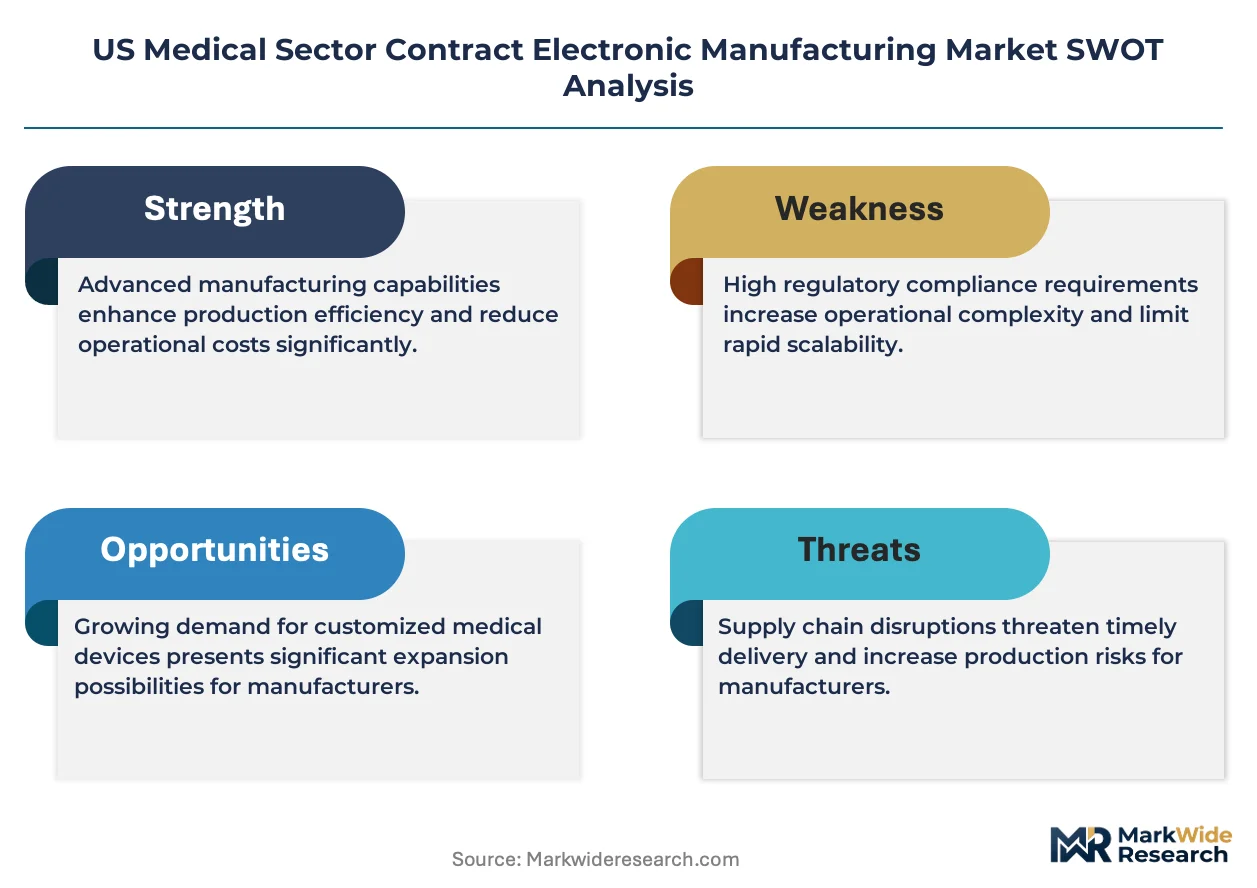
FDA quality system regulation enforcement and ISO 13485 certification mandates determine supplier qualification thresholds, effectively filtering out generalist electronics manufacturers from medical-grade opportunities. NHTSA-adjacent patient transport electronics and FCC electromagnetic compatibility standards for wireless-enabled implants add layered compliance complexity that rewards established specialists. Stakeholders must monitor how FDA's evolving cybersecurity guidance for connected devices reshapes contract manufacturer technical capabilities and liability allocation.
Market Dynamics
Original equipment manufacturers are collapsing in-house manufacturing footprints as FDA cybersecurity guidance for connected devices forces contract partners to absorb liability for wireless-enabled implantable systems.
Growth Catalysts
- ISO 13485 Certification Mandates:FDA quality system regulation enforcement filters generalist electronics manufacturers from medical-grade opportunities, concentrating qualified supplier pools and elevating pricing power for certified contract manufacturers serving Class II and III devices.
- Electrophysiology Device Proliferation:Cardiology-focused box build assemblies represent the fastest-growing application segment as ablation systems and mapping catheters demand complex PCB integration with biocompatibility traceability.
- Minnesota's Medical Alley:Demand concentrates in this corridor where diagnostic equipment OEMs cluster, creating localized supplier ecosystems that reduce logistics costs and accelerate prototype-to-production cycles for electromechanical systems.
Market Restraints
- Specialized Cleanroom Infrastructure:Captive cleanroom capacity requires capital intensity that limits mid-tier contract manufacturers from entering Class III device assembly, consolidating production among established players with multi-site US footprints.
- Semiconductor Component Volatility:Custom ASIC lead times for diagnostic platforms extend beyond 52 weeks, forcing contract manufacturers to absorb inventory risk or lose qualified supplier status with OEMs.
- NHTSA-Adjacent Compliance Layering:Patient transport electronics must satisfy both FDA biocompatibility requirements and NHTSA crashworthiness standards, adding documentation burden that excludes pure-play medical specialists from ambulance-mounted monitoring systems.
Strategic Opportunities
- Massachusetts Route 128 Corridor Expansion:Underpenetrated surgical robotics OEMs in this cluster seek contract partners with ISO 13485 certification and cable harness integration capabilities for next-generation minimally invasive platforms.
- FCC Cybersecurity Guidance Evolution:FDA's draft guidance on premarket submissions for wireless-enabled devices creates technical capability gaps that contract manufacturers can fill through embedded security engineering services.
- Sterilization Compatibility Convergence:Gamma-stable PCB substrates and autoclave-resistant connector technologies enable contract manufacturers to capture value from OEMs consolidating multi-modal sterilization supply chains.
Industry Challenges
- Biomedical Electronics Engineering Talent Scarcity:Contract manufacturers compete with OEMs for professionals skilled in both IPC-A-610 workmanship standards and ISO 14971 risk management, compressing margins through wage inflation.
- Dual Certification Timeline Compression:FDA 510(k) clearance and FCC equipment authorization processes run on parallel tracks with incompatible documentation formats, forcing contract manufacturers to maintain redundant quality system infrastructures.
- Legacy MES Integration Friction:OEM demand for real-time production traceability conflicts with decades-old manufacturing execution systems at established contract facilities, requiring costly middleware development.
Report Scope
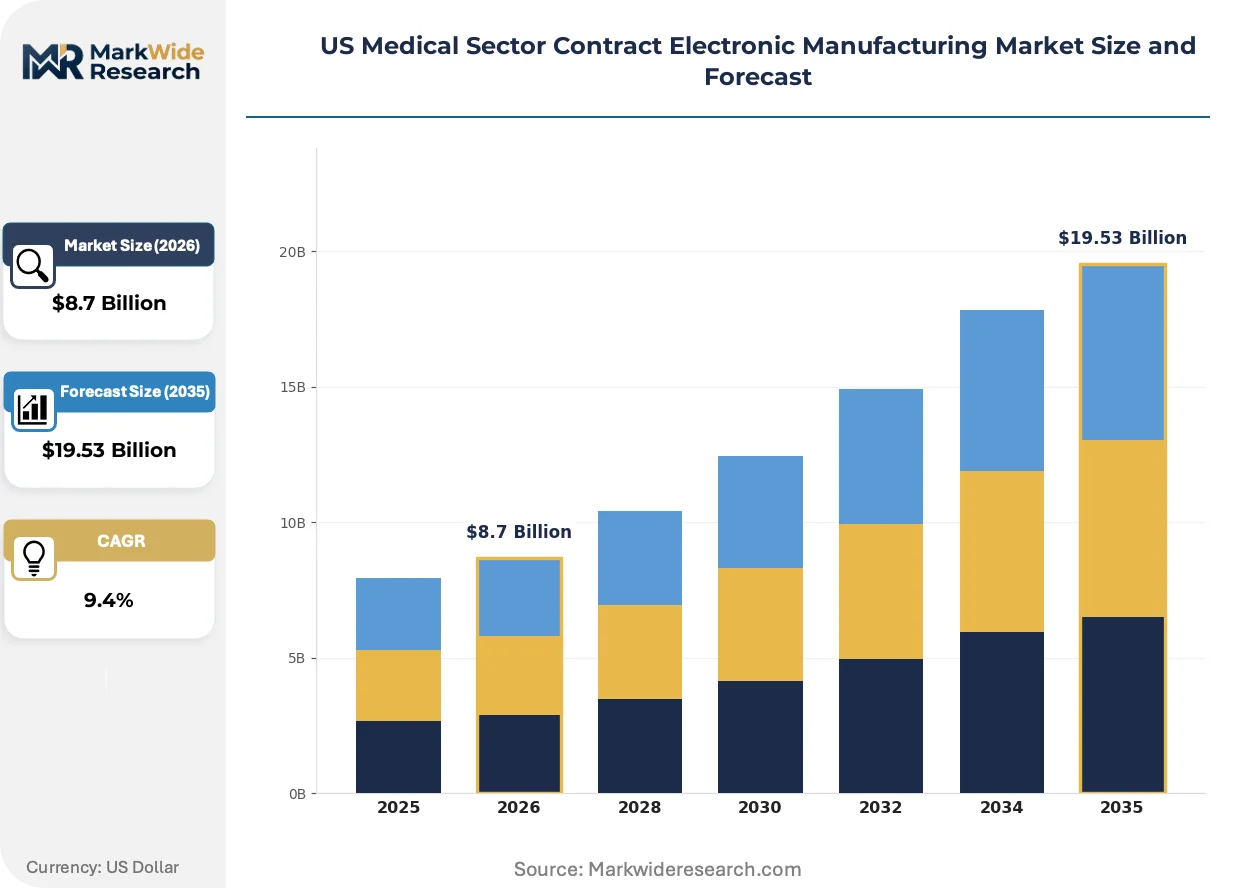
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Sector Contract Electronic Manufacturing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Diagnostic Equipment, Surgical Instruments, Wearable Technology Technology: PCB Assembly, Surface Mount Technology, Custom Manufacturing, Box Build End User: Hospitals, Diagnostics Labs, OEMs, Rehabilitation Centers Application: Cardiology, Orthopedics, Neurology, Hematology |
| Companies Covered | Benchmark Electronics, Flex, Celestica, Jabil, Sanmina Corporation, Plexus, Nortech Systems, Forefront Medical Technologies, Qualitel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Sector Contract Electronic Manufacturing Market Strategic Shifts
Surface mount technology dominance is eroding as diagnostic equipment OEMs demand custom manufacturing with engineering intensity that automated PCB insertion lines cannot satisfy.
Additive manufacturing of conformal cooling channels for injection-molded device housings is fragmenting traditional subtractive tooling supply chains. Medical device OEMs adopting metal 3D-printed mold inserts reduce lead times from sixteen weeks to four for complex geometries. Contract manufacturers without hybrid manufacturing capabilities are losing diagnostic platform contracts to competitors with captive additive capacity.
FDA's evolving cybersecurity guidance for connected devices is compressing supplier qualification timelines. The draft premarket guidance requires contract manufacturers to demonstrate secure software development lifecycle processes and vulnerability management protocols. Diagnostic equipment applications face the steepest compliance burden as wireless-enabled imaging systems proliferate, forcing contract partners to hire embedded security engineers or subcontract to specialized cybersecurity firms.
Hospital procurement consolidation is rotating contract manufacturer selection criteria toward total cost of ownership models. Integrated delivery networks in Texas and Florida now evaluate suppliers on sterilization validation support and field service logistics, not unit pricing alone. This behavioral shift favors contract manufacturers with captive aftermarket capabilities over pure production specialists, compressing margins for assemblers without service infrastructure.
US Medical Sector Contract Electronic Manufacturing Market Segmentation
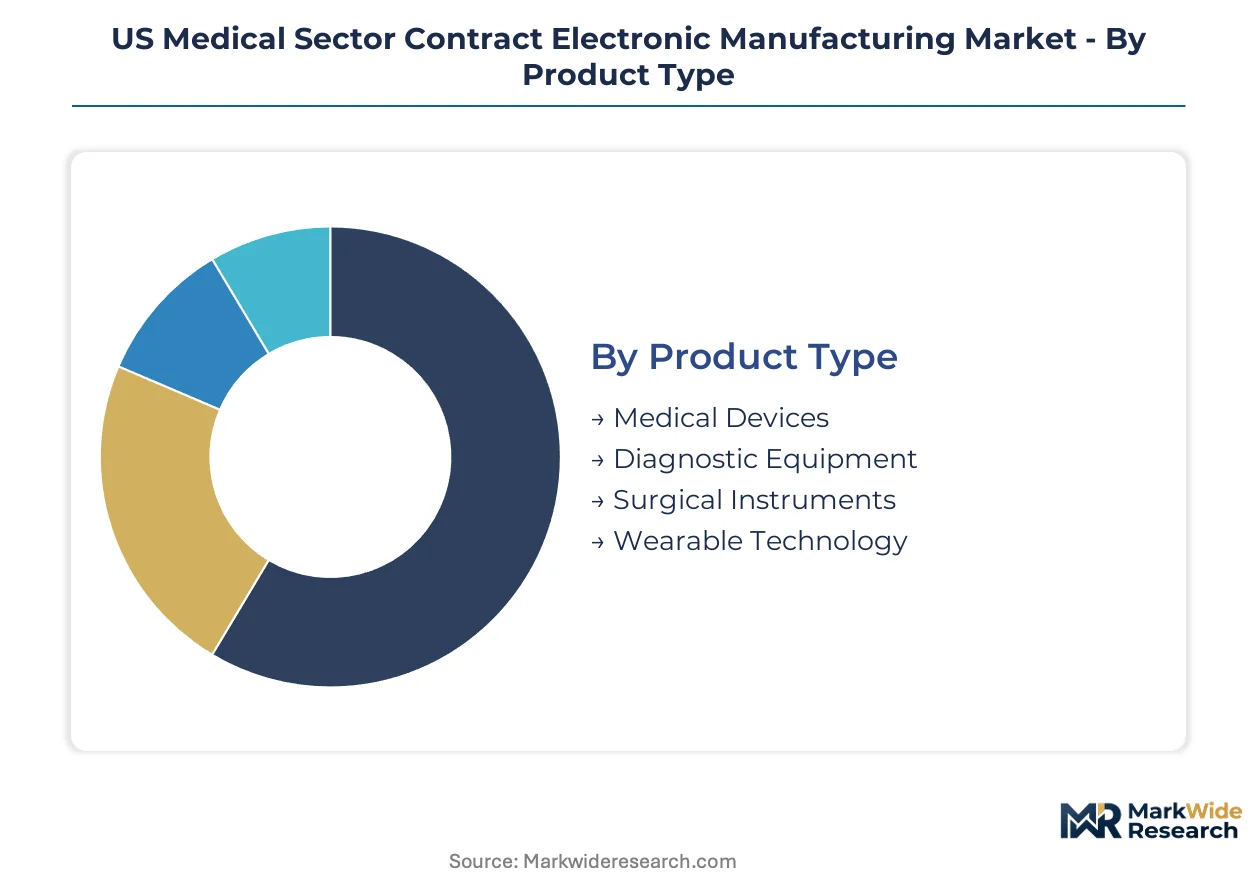
Contract manufacturers in the US medical electronics sector face divergent margin profiles across product and technology segments. FDA regulatory intensity varies by device classification, creating tiered qualification barriers that reshape competitive positioning within each category.
Product Type:
Diagnostic equipment faces the strongest substitution pressure from point-of-care platforms that bypass traditional centralized testing infrastructure entirely.
- Diagnostic Equipment:Complex electromechanical systems integrating PCB assemblies with optical sensors and fluid handling modules. Demand concentrates in Minnesota's Medical Alley where imaging OEMs cluster, driven by electrophysiology device proliferation requiring biocompatibility traceability.
- Medical Devices:Class II and III electromechanical assemblies ranging from infusion pumps to patient monitors. Massachusetts Route 128 corridor anchors demand for next-generation minimally invasive platforms, constrained by ISO 13485 certification mandates that filter generalist manufacturers from qualified supplier pools.
- Surgical Instruments:Powered and non-powered devices requiring sterilization-compatible materials and gamma-stable substrates.
- Wearable Technology:Wireless-enabled biosensors and remote patient monitoring devices subject to FCC electromagnetic compatibility standards.
Diagnostic equipment anchors the volume base while wearable technology gains share at the steepest rate.
Technology:
Cost tier stratification separates commodity assembly from engineering-intensive custom work that commands premium pricing.
- Custom Manufacturing:Engineering-intensive production of low-volume, high-complexity assemblies with extensive regulatory documentation. FDA cybersecurity guidance for connected devices forces contract partners to absorb liability, elevating technical capability requirements and pricing power for qualified specialists.
- Surface Mount Technology:Automated PCB placement dominating high-volume consumables assembly. Jabil and Flex compete on automated insertion lines that reduce labor content per unit, though margin compression limits growth in commoditized segments.
- PCB Assembly:Printed circuit board production ranging from rigid to flexible substrates with biocompatibility requirements.
- Box Build:Fully integrated electromechanical systems combining cable harnesses, enclosures, and final test.
Surface mount technology captures the highest shipment volumes while custom manufacturing delivers the steepest margin expansion.
End User:
Procurement centralization among hospital systems is rotating selection criteria toward total cost of ownership models.
- OEMs:Original equipment manufacturers outsourcing complex electronics assembly to contract partners. Mid-sized medical device startups are collapsing reliance on in-house manufacturing floors as capital efficiency pressures mount, concentrating demand among established contract manufacturers with multi-site US footprints.
- Hospitals:Integrated delivery networks in Texas and Florida evaluating suppliers on sterilization validation support and field service logistics.
- Diagnostics Labs:Centralized and decentralized testing facilities requiring equipment with traceability documentation.
- Rehabilitation Centers:Long-term care and physical therapy facilities with specialized device requirements.
OEMs dominate contract value while hospitals are expanding their direct procurement fastest.
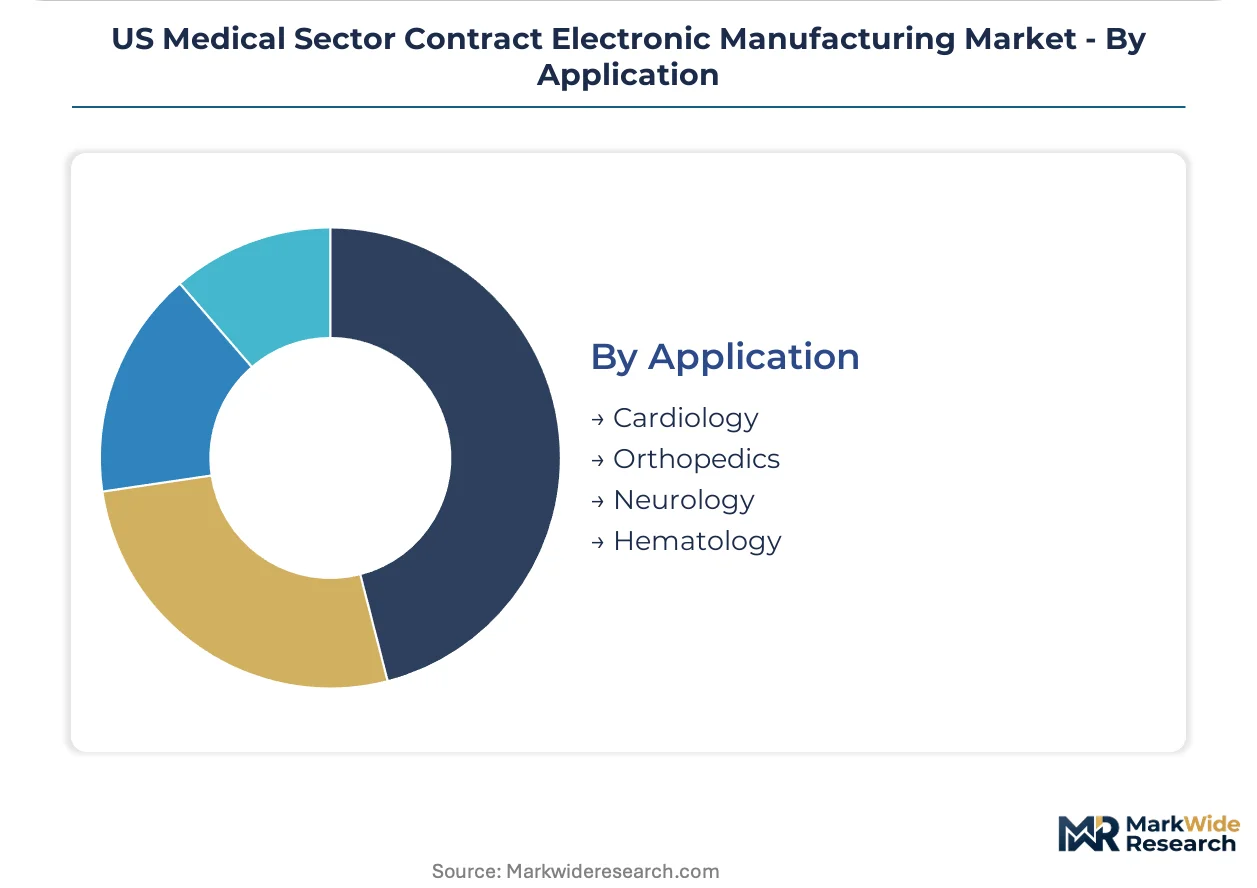
Application:
Clinical outcome differentiation separates high-growth therapeutic areas from mature replacement markets.
- Cardiology:Electrophysiology devices including ablation systems and mapping catheters demanding complex PCB integration. This segment climbs the fastest as minimally invasive cardiac procedures displace open surgical alternatives.
- Neurology:Deep brain stimulators and neurostimulation devices requiring hermetic sealing and biocompatibility certification.
- Orthopedics:Powered surgical tools and patient-specific implant electronics with sterilization compatibility requirements.
- Hematology:Blood analysis and cell counting instrumentation with optical and fluidic system integration.
Cardiology anchors revenue concentration while neurology gains share fastest among emerging therapeutic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic equipment OEMs and surgical robotics developers concentrate purchasing power in three distinct US manufacturing corridors. FDA quality system regulation enforcement and ISO 13485 certification requirements filter contract manufacturer qualification to established multi-site operators.
Minnesota Medical Alley
Electrophysiology device manufacturers and imaging system OEMs anchor demand in this corridor. FDA 510(k) clearance timelines compress supplier selection to partners with captive cleanroom infrastructure. Minneapolis-St. Paul hosts Benchmark Electronics and Nortech Systems facilities serving Class III cardiac ablation systems.
Massachusetts Route 128
Surgical robotics startups and minimally invasive platform developers drive contract manufacturing growth. Massachusetts state tax incentives for medical device R&D attract OEM engineering centers. Cambridge and Lowell clusters concentrate Plexus and Forefront Medical Technologies operations focused on cable harness integration.
California Bay Area-San Diego Corridor
Digital health and wireless-enabled diagnostic platforms proliferate in this region. FCC equipment authorization requirements for connected devices add compliance layers that favor contract manufacturers with embedded security capabilities. San Jose and San Diego host Flex medical innovation centers prototyping next-generation biosensors.
Texas Medical Center Vicinity
Hospital procurement consolidation across integrated delivery networks rotates supplier selection toward total cost of ownership models. Texas state medical device manufacturing tax abatements attract OEM assembly operations. Houston and Austin clusters concentrate Jabil high-volume consumables production for diagnostic consumables.
Florida Southeast Cluster
Rehabilitation device manufacturers and patient monitoring system OEMs concentrate demand in this region. Florida's lack of state income tax attracts medical device corporate headquarters. Tampa and Miami corridors host Qualitel Corporation and regional contract manufacturers serving Class II electromechanical assemblies.
US Medical Sector Contract Electronic Manufacturing Market Competitive Environment
Player mix skews toward diversified electronics manufacturing services providers with dedicated medical verticals. Tiered structure separates premium engineering-intensive specialists from scale-driven consumables assemblers. Three archetypes dominate: captive cleanroom operators, automated high-volume producers, and hybrid manufacturing integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs consolidate qualified supplier pools.
Among diversified manufacturing services providers, Benchmark Electronics, Flex, and Jabil represent distinct positioning vectors. Benchmark Electronics exemplifies the captive cleanroom archetype with multi-site US medical-grade capacity. Flex occupies the innovation-centric tier through dedicated medical R&D infrastructure. Jabil anchors high-volume automated production for disposable diagnostic components.
| Leading Market Players |
|---|
| Benchmark Electronics |
| Flex |
| Celestica |
| Jabil |
| Sanmina Corporation |
| Plexus |
| Nortech Systems |
| Forefront Medical Technologies |
| Qualitel Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with ISO 13485-certified contract manufacturers lock in both cleanroom access and unit cost visibility for Class II and III device OEMs navigating FDA quality system enforcement. These arrangements concentrate pricing power among multi-site operators with captive infrastructure while squeezing pure-play assemblers unable to guarantee sterilization-compatible substrate supply.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate high-volume diagnostic consumables, shielding Jabil and Flex from ASIC volatility while passing resin and copper trace cost swings to OEM buyers. Three-tier pricing structure across FDA-certified premium, ISO-standard mid-tier, and non-medical economy levels separates Class III cardiac ablation systems from Class II patient monitors and consumer-grade wellness devices. Pricing pressure stems from hospital procurement consolidation demanding total cost of ownership models that bundle sterilization validation with unit pricing. Integrated delivery networks in Texas and Florida exhibit acute price sensitivity, whereas Minnesota Medical Alley electrophysiology OEMs prioritize traceability documentation over per-unit discounts.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port complexes have compressed margins for California Bay Area contract manufacturers dependent on Asian PCB substrate shipments. Taiwan, South Korea, and Japan anchor semiconductor wafer supply for diagnostic imaging ASICs, while Mexico and Costa Rica feed cable harness assembly for surgical robotics. Custom biocompatible resin and gamma-stable substrate sourcing rests on petrochemical corridors in Texas and Louisiana. Single-source vulnerability concentrates in 52-week lead time custom ASICs for electrophysiology mapping systems. Distribution runs through OEM direct procurement with hospital GPO overlay, bypassing traditional electronics distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA cybersecurity guidance for wireless-enabled implants is reshaping competitive positioning, forcing liability absorption capabilities to become a non-negotiable supplier qualification threshold. This regulatory inflection compresses the qualified vendor pool and elevates capital requirements for market participation.
For Market Incumbents: Consolidate multi-site cleanroom footprints through targeted acquisition of regional ISO 13485-certified operators in Massachusetts Route 128 and Minnesota Medical Alley corridors. Deepen backward integration into gamma-stable PCB substrate production to offset petrochemical price volatility and defend margin position against automated high-volume competitors from Mexico. Prioritize embedded security engineering headcount to meet FDA premarket submission requirements for connected diagnostic platforms. For New Entrants and Emerging Players: Lead with sterilization compatibility convergence as a service wedge, offering gamma and autoclave validation support to mid-sized device startups collapsing in-house manufacturing. Target underpenetrated surgical robotics OEMs in the Massachusetts corridor seeking cable harness integration partners with ISO 13485 certification and rapid prototype-to-production cycles. Establish go-to-market presence through hospital procurement consortiums in Texas and Florida emphasizing field service logistics over unit pricing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hybrid manufacturing integrators with captive additive capacity and embedded security capabilities. Five-to-ten year viability hinges on cybersecurity liability infrastructure becoming a durable moat rather than a compliance cost center. Target acquisition archetype: mid-tier contract manufacturers with ISO 13485 certification and underutilized cleanroom capacity in FDA-corridor geographies. Signal to monitor: FDA finalization of premarket cybersecurity guidance and its liability allocation language for contract manufacturing agreements.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Filters generalist electronics manufacturers from FDA-qualified supplier pools serving Class II and III devices. |
| Embedded Security Engineering Buildout | Addresses FDA cybersecurity guidance requirements for wireless-enabled implantable and diagnostic systems. |
| Captive Additive Manufacturing Integration | Captures diagnostic platform contracts through conformal cooling channel production for injection-molded housings. |
| Hospital GPO Partnership Development | Aligns supplier selection criteria with Texas and Florida integrated delivery network procurement consolidation. |
| Multi-Site Cleanroom Capacity Expansion | Secures electrophysiology device contracts requiring biocompatibility traceability across Minnesota and Massachusetts clusters. |
Study Parameters
A standing panel of biomedical engineering directors, hospital GPO contracts managers, FDA regulatory affairs leads, and contract manufacturing procurement officers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, FCC equipment authorization filings, hospital procurement contract repositories, and ISO 13485 certification registries. Bottom-up assembly cost modeling triangulated against top-down OEM outsourcing spend estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology, end user, and application segmentation dimensions. CAGRs were derived from installed base growth rates for diagnostic and therapeutic device categories, cross-referenced with OEM outsourcing intensity surveys. Forecast inputs incorporated semiconductor lead time volatility, FDA inspection enforcement trends, and hospital consolidation patterns across corridor geographies.
Forecasts assume regulatory continuity in FDA quality system regulation and FCC electromagnetic compatibility regimes; material policy shifts would require re-modeling. Cybersecurity guidance finalization, NHTSA patient transport electronics rule changes, or state-level medical device tax modifications represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Respiratory Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Biologic Injectors Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Pleural Catheters Market
Medical Devices
Intrathecal Pumps Market
Medical Devices
Cellular Encapsulation Market