
 Global Personal Health Records Software Market | 2026-2036
Global Personal Health Records Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Health Records Software Market Foresight
A shift from single-source enterprise contracts toward multi-source ecosystem integration is broadening procurement flexibility for health systems. Epic Systems leverages deep EHR interoperability to anchor hospital-centric deployments across North American academic medical centers. Cerner Corporation sustains competitive positioning through extensive federal health system relationships and VA modernization contracts. Seqster differentiates via patient-mediated data aggregation across disparate source systems including wearables and genomics labs.
Personal health records software constitutes a digital health platform enabling individuals to aggregate, manage, and share clinical data from multiple care settings through standardized APIs such as FHIR R4 and SMART on FHIR protocols. The primary commercial purpose centers on reducing information fragmentation, improving care coordination, and empowering patient engagement through longitudinal health data visibility. Cloud-based deployment leads solution adoption as health systems prioritize scalability and reduced infrastructure overhead over capital-intensive on-premises installations. Integrated solution types capture expanding margin pools by embedding PHR functionality within broader EHR and population health management workflows rather than standalone patient portals.
The US FDA and ONC enforce interoperability mandates through information-blocking provisions and certified health IT requirements, directly shaping vendor product roadmaps and health system procurement criteria. Europe's EMA coordinates with national regulators under the EU Health Data Space framework to establish cross-border patient data portability standards. Stakeholders must monitor evolving FHIR implementation guidance and reimbursement policy shifts that determine whether patient-generated health data achieves clinical workflow integration or remains siloed in consumer-facing applications.
Market Dynamics
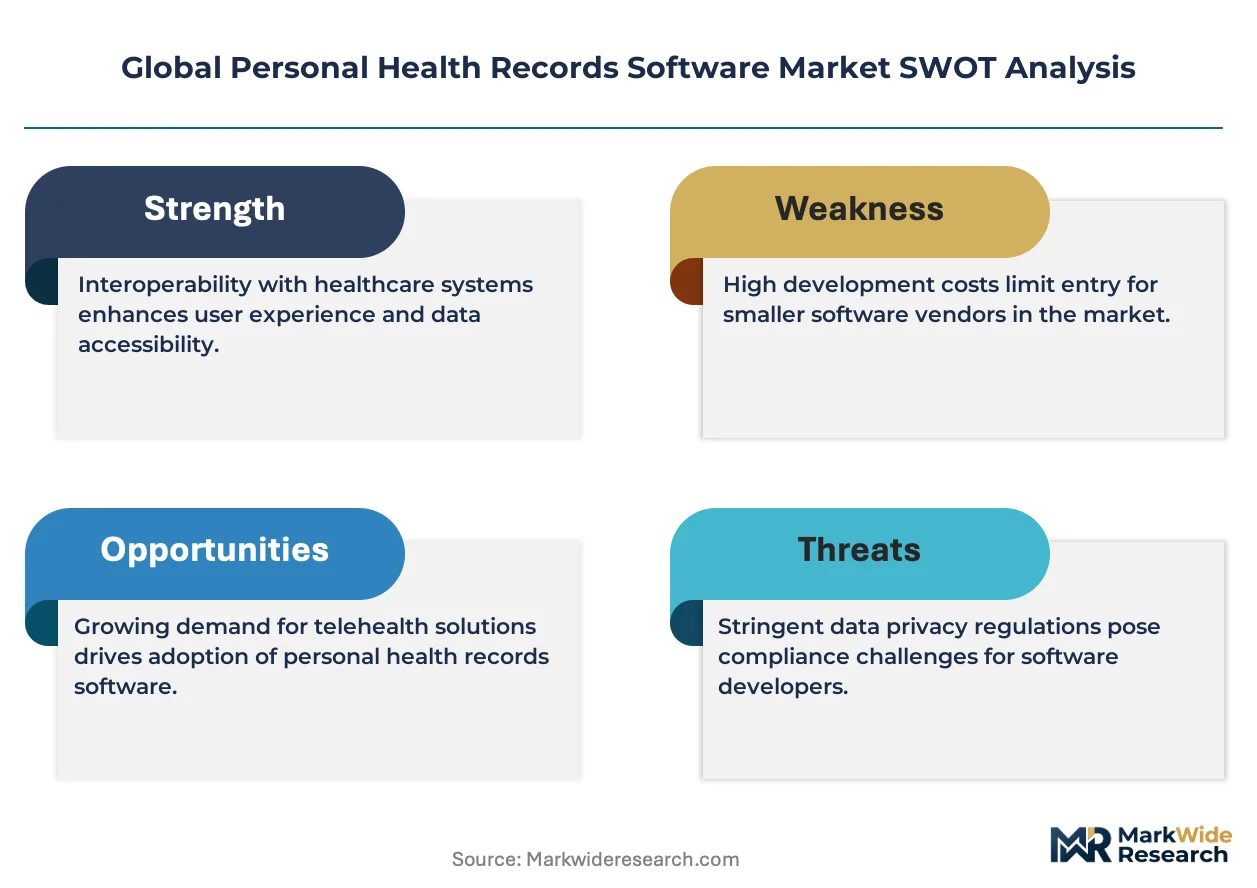
FHIR R4 API standardization is compressing integration timelines and forcing vendors to abandon proprietary data formats in favor of interoperable architectures. This technical shift is restructuring procurement criteria across hospital systems and ambulatory networks.
Growth Catalysts
- US 21st Century Cures Act mandates:Information-blocking penalties are compelling EHR vendors to open patient data access, accelerating PHR platform deployments across integrated delivery networks.
- Wearable device proliferation:Continuous glucose monitors and consumer fitness trackers are generating patient-mediated data streams that PHR platforms aggregate into longitudinal records.
- Germany's digital health applications (DiGA) fast-track:Reimbursement pathways for prescribed health apps are normalizing patient-facing software within statutory health insurance frameworks.
Market Restraints
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud dominate health data hosting, creating single-point vulnerability for multi-tenant PHR deployments.
- Legacy EHR upgrade cycles:Cerner and Epic on-premises installations require 18-36 month replacement timelines, delaying API-native PHR integration.
- Genomic data storage costs:Whole-exome sequencing files exceed 100GB per patient, multiplying cloud expenditure for precision medicine-enabled PHR platforms.
Strategic Opportunities
- Japan's Society 5.0 health data integration:METI's cross-sector data sharing frameworks are opening PHR linkages to insurance, pharmaceutical, and research institutions.
- FHIR and blockchain convergence:Immutable audit trails for patient consent management are emerging as a differentiated architecture for data sovereignty.
- Direct-to-employer contracting:Self-insured corporations are procuring PHR platforms as workforce health benefits, bypassing traditional payer channels.
Industry Challenges
- Interoperability engineer scarcity:Health informaticists with dual competency in HL7 FHIR and SMART on FHIR protocols command premium compensation, constraining vendor scaling.
- State-level privacy fragmentation:California's CCPA, Illinois' BIPA, and Washington's My Health My Data Act create conflicting compliance matrices for national PHR rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Health Records Software Market |
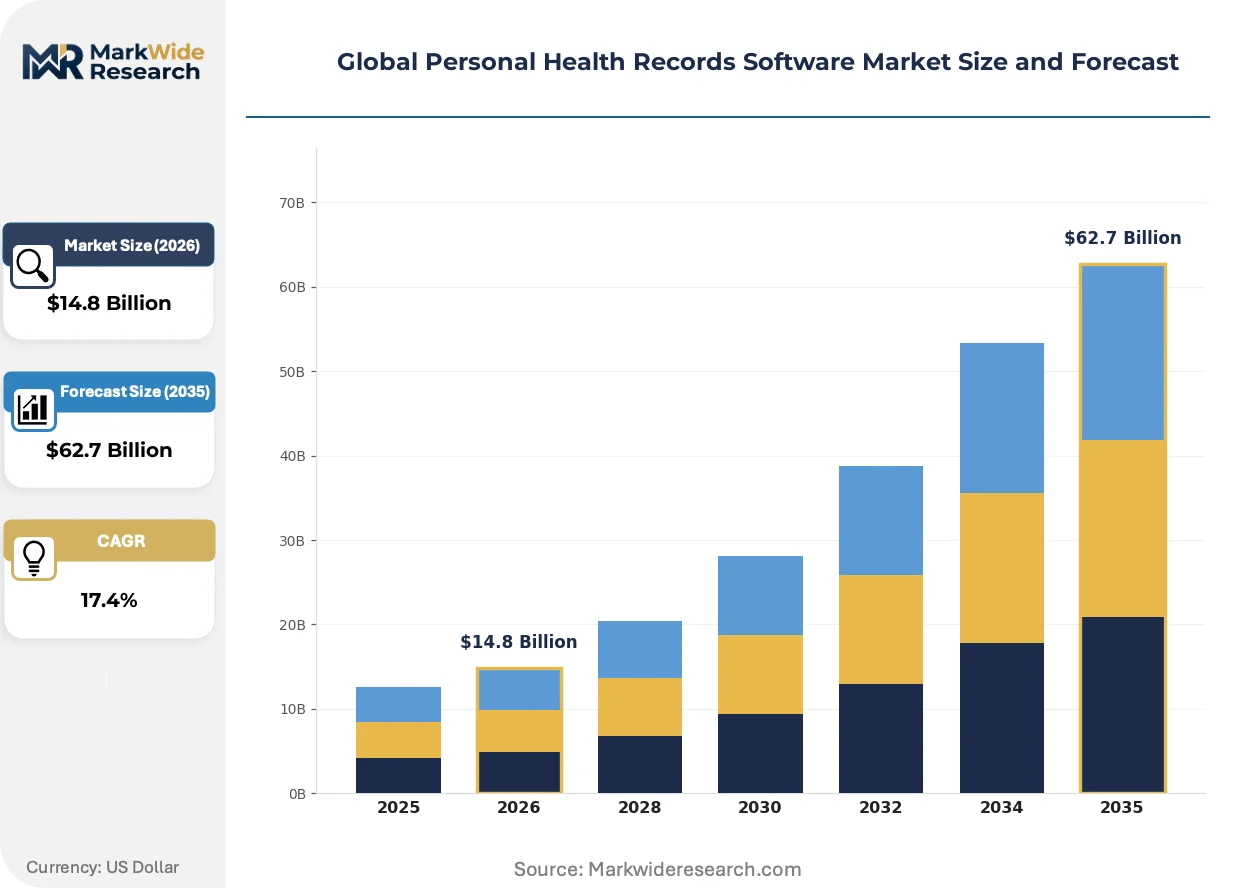
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $62.7 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based Solution Type: Standalone, Integrated, Mobile Application, Enterprise Solution, Modular End User: Patients, Healthcare Providers, Research Institutions, Insurance Companies, Wellness Centers Application: Chronic Disease Management, Wellness Tracking, Medical History Storage, Medication Management, Preventive Care |
| Companies Covered | Epic Systems, Oracle Health, Athenahealth, Cerner Corporation, Allscripts Healthcare Solutions, Seqster, Validic, Innovaccer, NoMoreClipboard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Health Records Software Market Shifts & Advancements
Artificial intelligence inference at the edge is compressing latency for real-time clinical decision support within patient-facing interfaces. This architectural shift is redefining where computation occurs in the PHR data flow.
Generative AI documentation tools are electrifying patient-provider communication workflows. Ambient clinical voice capture from companies like Nuance and Suki is integrating directly into PHR portals, enabling automated visit summarization. Health systems in the United States are piloting these capabilities within Medicare Advantage populations, where risk-adjustment documentation requirements intensify data capture demands. The structural consequence is a compression of manual patient portal update cycles from days to hours.
The EU AI Act's risk classification framework is mandating conformity assessments for PHR features incorporating diagnostic algorithms. High-risk AI applications must demonstrate clinical validation and post-market surveillance, extending time-to-market for predictive analytics modules. German and French health technology assessment bodies are incorporating these requirements into hospital procurement evaluations, favoring vendors with established notified body relationships.
Subscription-based PHR access is displacing perpetual license models in employer-sponsored health benefits. Large self-insured corporations in the United States are negotiating per-employee-per-month contracts that bundle PHR functionality with telehealth and care navigation services. This bundling is most advanced among technology sector employers with concentrated workforces in Seattle, Austin, and Raleigh-Durham, where competitive benefits packages drive rapid vendor switching.
Global Personal Health Records Software Market Segmentation
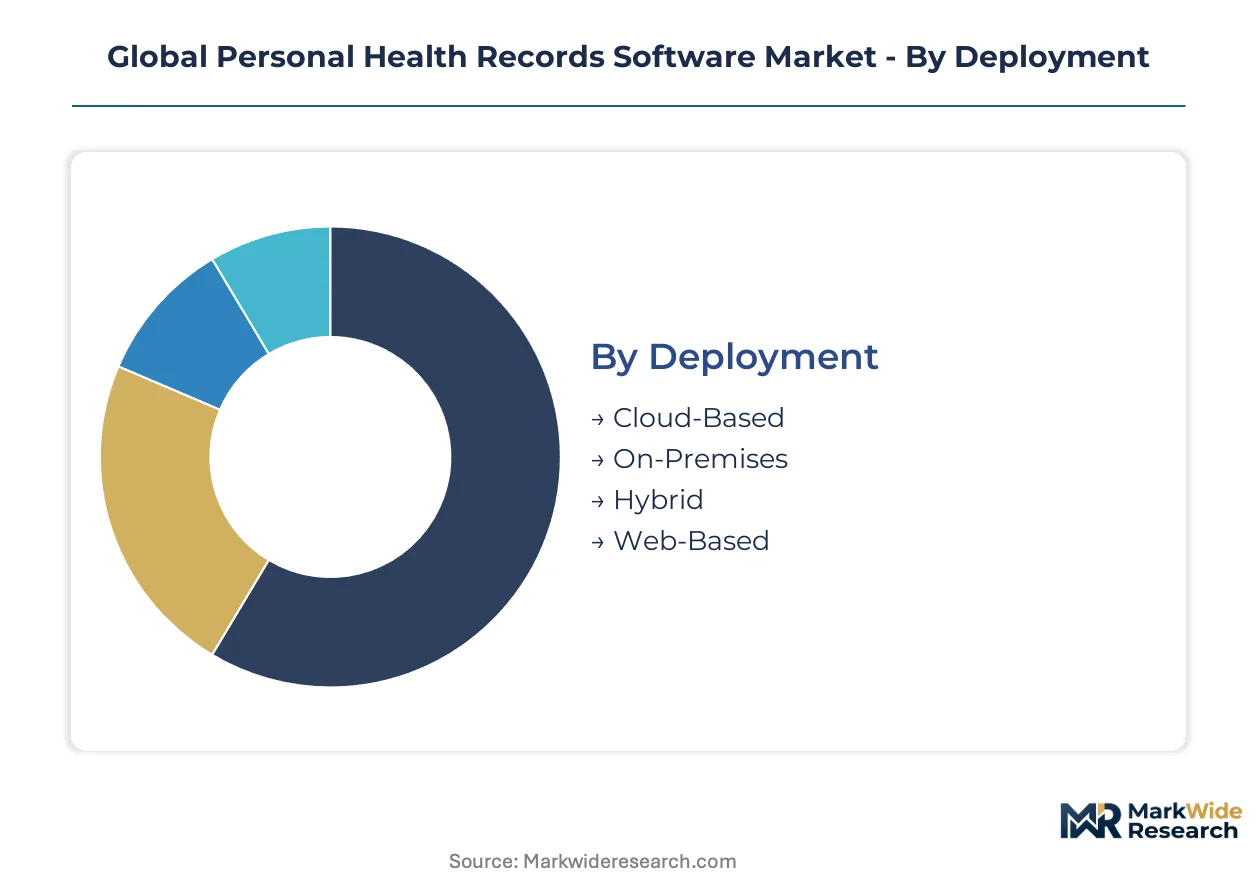
Personal health records software segmentation reveals divergent procurement logics across deployment architectures and user constituencies. Cloud-native platforms attract health systems prioritizing scalability, while integrated solutions embed within existing EHR workflows to minimize change management overhead.
Deployment:
Procurement decisions pivot on capital expenditure tolerance versus operational flexibility requirements.
- Cloud-Based:Multi-tenant architectures leverage AWS, Microsoft Azure, and Google Cloud infrastructure to eliminate on-premises hardware maintenance. Hospital systems in the United States and Germany favor this model for rapid scaling across ambulatory networks without 18-36 month infrastructure procurement cycles.
- On-Premises:Legacy Cerner and Epic installations persist in federal health systems and VA facilities where data sovereignty requirements override cloud migration incentives. These deployments demand dedicated IT staff and carry higher total cost of ownership.
- Hybrid:Sensitive genomic data remains on-premises while administrative functions migrate to cloud tiers, balancing compliance with cost optimization.
- Web-Based:Browser-accessible portals minimize client-side software distribution for patient populations with heterogeneous device ecosystems.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as precision medicine workloads expand.
Solution Type:
Margin capture concentrates where PHR functionality embeds within broader clinical workflow platforms rather than standalone implementations.
- Integrated:Epic Systems and Cerner Corporation anchor hospital-centric deployments by embedding PHR portals within comprehensive EHR environments. Academic medical centers across the United States, Germany, and Japan prioritize these solutions to maintain single-vendor accountability.
- Standalone:Specialized vendors target ambulatory clinics and small physician practices lacking enterprise EHR contracts. These platforms emphasize rapid implementation and lower per-seat pricing.
- Mobile Application:Native iOS and Android clients dominate patient-mediated data capture for wearable device integration.
- Enterprise Solution:Multi-hospital integrated delivery networks deploy centralized PHR instances across dozens of facilities.
- Modular:Component-based architectures allow selective activation of genomics, telehealth, or billing modules.
Revenue concentrates in Integrated solutions; expansion is steepest in Mobile Application deployments as smartphone-native patient engagement becomes standard.
End User:
Demand fragmentation across user categories creates divergent feature prioritization and pricing architectures.
- Healthcare Providers:Hospitals and physician practices drive procurement for care coordination tools, medication reconciliation, and referral management. The US FDA's 21st Century Cures Act interoperability mandates compel these investments.
- Patients:Direct-to-consumer platforms aggregate data from multiple source systems including wearables and direct-to-consumer genomics labs. Seqster's patient-mediated aggregation model exemplifies this segment.
- Research Institutions:Academic medical centers and pharmaceutical sponsors require de-identified longitudinal datasets for clinical trial recruitment and real-world evidence generation.
- Insurance Companies:Payers deploy PHR platforms for risk stratification and wellness program administration.
- Wellness Centers:Corporate and commercial wellness programs integrate PHR functionality with biometric screening and coaching services.
Procurement volume centers on Healthcare Providers; patient-directed platforms are gaining share fastest as consumer health data sovereignty expectations intensify.
Application:
Clinical use case specificity determines API complexity and regulatory scrutiny intensity.
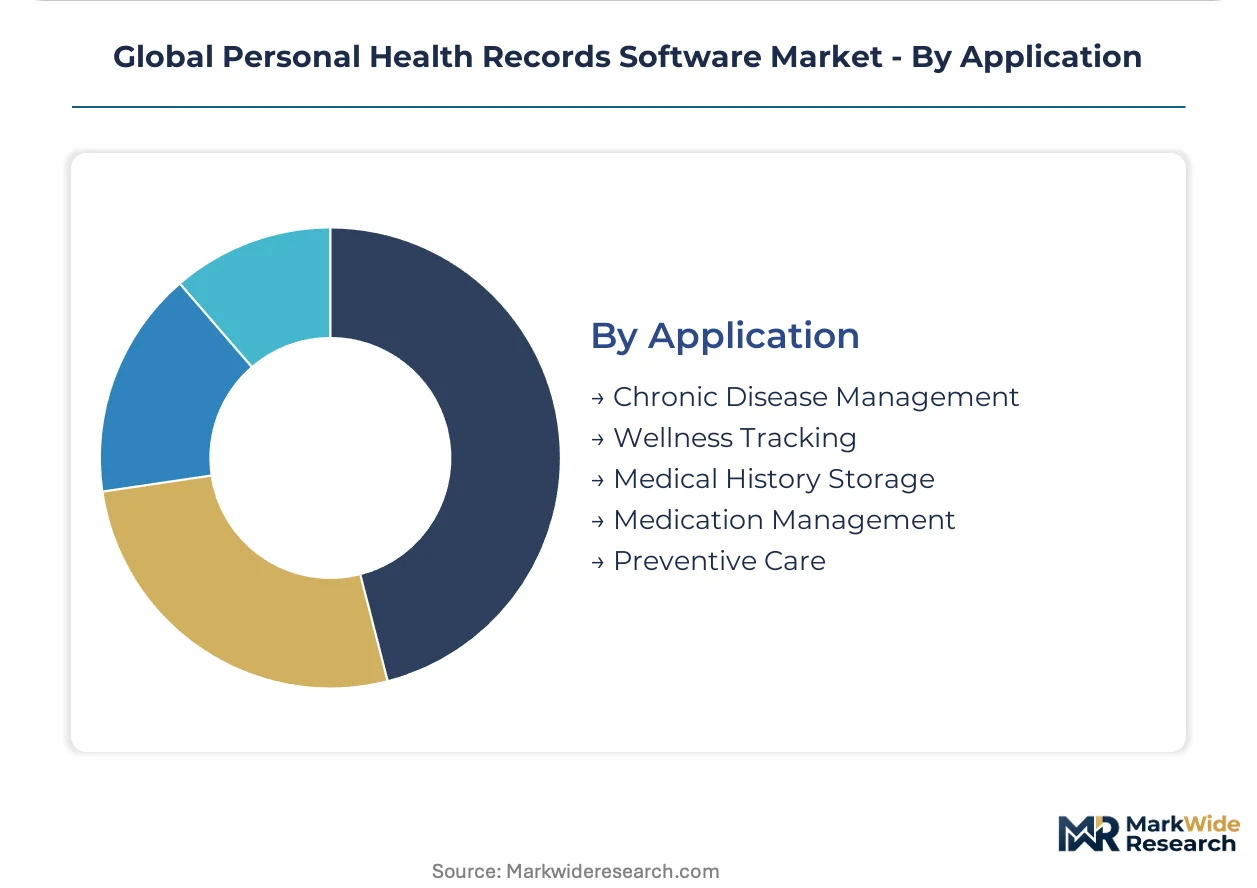
- Chronic Disease Management:Continuous glucose monitors, blood pressure cuffs, and pulse oximeters feed automated data streams into PHR platforms for diabetes, hypertension, and heart failure populations. Medicare Advantage plans in the United States pilot these capabilities for risk-adjustment documentation.
- Wellness Tracking:Consumer fitness devices and nutrition applications generate patient-mediated data with limited clinical workflow integration.
- Medical History Storage:Longitudinal record consolidation from disparate EHR sources remains the foundational PHR use case.
- Medication Management:Adherence tracking and drug interaction alerting require pharmacy system interoperability.
- Preventive Care:Screening reminders and immunization scheduling leverage demographic and claims data integration.
Deployment density is highest in Medical History Storage; Chronic Disease Management shows the steepest expansion trajectory as remote patient monitoring reimbursement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems account for the largest procurement volume, driven by federal interoperability mandates and Medicare Advantage risk-adjustment documentation requirements. Germany and Japan follow as statutory frameworks normalize patient-facing software reimbursement.
United States
Integrated delivery networks in Boston and the Research Triangle prioritize cloud-native PHR deployments for rapid ambulatory scaling. The FDA enforces information-blocking penalties under 21st Century Cures Act provisions, compelling Epic and Cerner to open patient data APIs. Academic medical centers in Nashville and Pittsburgh anchor hospital-centric implementations with embedded patient portals.
Germany
Statutory health insurers in Berlin and Munich fast-track DiGA prescriptions for patient-facing chronic disease management tools. The BfArM maintains the central registry for approved digital health applications, establishing reimbursement pathways that rival pharmaceutical formularies. Healthcare IT clusters in Bavaria concentrate FHIR-native platform development for cross-border EU Health Data Space compatibility.
Japan
Metropolitan hospital systems in Tokyo and Osaka deploy PHR platforms under METI's Society 5.0 cross-sector data integration frameworks. The PMDA coordinates with the Ministry of Health, Labour and Welfare on software-as-medical-device classifications for diagnostic algorithms. Pharmaceutical sponsors in Kansai leverage patient-mediated data linkages for real-world evidence generation and clinical trial recruitment.
United Kingdom
NHS trusts in London and Manchester pilot patient-facing record access through the NHS App infrastructure, consolidating data from fragmented legacy systems. NHS Digital mandates FHIR R4 compliance for all certified health IT suppliers, compressing vendor integration timelines. Health technology assessment bodies in Oxford and Cambridge incorporate EU AI Act risk classifications into procurement evaluations for predictive analytics modules.
India
Corporate hospital chains in Bengaluru and Hyderabad deploy PHR platforms for medical tourism patient coordination and NABH accreditation compliance. The Ministry of Health and Family Welfare's National Digital Health Mission establishes unique health identifiers for longitudinal record linkage. Health-tech startups in the National Capital Region concentrate on modular, low-cost implementations for tier-2 and tier-3 city expansion.
Global Personal Health Records Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to anchor hospital-centric deployments and expand patient-mediated data aggregation capabilities. The vendor base concentrates around three tiers: comprehensive EHR-integrated platforms, specialized patient-facing aggregation tools, and modular API-native specialists. Two strategic archetypes define competitive positioning—enterprise incumbents leveraging deep interoperability relationships and agile challengers exploiting FHIR standardization to bypass legacy upgrade cycles. M&A activity and technology licensing agreements constitute the primary competitive moves, with acquirers targeting FHIR engineering talent and established federal health system relationships.
Within the enterprise-integrated tier, Epic Systems and Cerner Corporation exemplify hospital-centric positioning through embedded PHR portals within comprehensive EHR environments. Oracle Health occupies a transitional position following its Cerner acquisition, consolidating federal system relationships while migrating cloud infrastructure. Seqster represents the patient-mediated aggregation archetype, specializing in multi-source data consolidation across wearables, genomics labs, and disparate EHR systems rather than single-vendor workflow embedding.
| Leading Market Players |
|---|
| Epic Systems |
| Oracle Health |
| Athenahealth |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| Seqster |
| Validic |
| Innovaccer |
| NoMoreClipboard |
| Others |
Supply & Pricing Matrix
FHIR engineering talent scarcity in the Research Triangle and Boston corridors widens pricing-tier spreads between premium-certified and economy-tier PHR deployments, as labor-cost differentials compound cloud infrastructure expenditure gaps.
Pricing Analysis
Warranty and service bundling separates enterprise-grade implementations from unbundled SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against FDA 21st Century Cures Act compliance timelines and customization depth. Cost compression in the economy tier is intensifying because hyperscaler compute pricing erodes margin buffers for multi-tenant architectures. Self-insured employers show the least price sensitivity given workforce health benefit budgets, while standalone ambulatory clinics face acute procurement constraints.
Supply Chain Analysis
Reverse-logistics flows for decommissioned on-premises EHR hardware create secondary equipment markets that extend legacy system lifecycles. Supply concentrates in the United States, Germany, and Japan for FHIR-native platform development, drawing from specialized health informatics labor pools and academic medical center innovation clusters. Cloud infrastructure dependency on AWS, Microsoft Azure, and Google Cloud creates single-source vulnerability for multi-tenant deployments. Distribution runs through direct enterprise sales teams for integrated EHR-embedded solutions and channel partners for standalone ambulatory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA information-blocking penalties and ONC certification requirements erect barrier-to-entry moats favoring established vendors with federal health system relationships.
For Market Incumbents: Hedge against FHIR-native challengers by accelerating patient-mediated data aggregation capabilities and securing exclusive GPO contracts with academic medical centers. Oracle Health's Cerner consolidation demonstrates cloud migration urgency. Vertical integration into genomic data storage infrastructure addresses precision medicine margin expansion. For New Entrants and Emerging Players: Edge AI inference modules for real-time clinical decision support offer a technology-first wedge into Medicare Advantage risk-adjustment documentation workflows. White-space targets include direct-to-employer contracting in technology sector clusters and DiGA-fast-tracked chronic disease management tools for German statutory insurers. A channel partnership with benefits administration platforms accelerates workforce health benefit penetration. For Investors and Strategic Acquirers: Re-rating potential sits with FHIR engineering specialists given ONC certification backlog compression and hospital system procurement urgency. Long-term viability hinges on patient data sovereignty architecture durability. Acquisition target archetype: modular API-native vendors with established VA or NHS relationships. Monitor EU AI Act conformity assessment timelines for predictive analytics module revenue recognition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Platform Certification | ONC certification unlocks hospital system procurement eligibility under Cures Act mandates. |
| Genomic Data Infrastructure Partnership | Whole-exome sequencing storage alliances address precision medicine cloud cost multiplication. |
| Direct-to-Employer Channel Development | Self-insured corporations in Seattle and Austin bypass traditional payer distribution. |
| EU AI Act Conformity Assessment | Notified body relationships accelerate German and French hospital procurement evaluations. |
| Patient-Mediated Aggregation Acquisition | Wearables and DTC genomics lab integration deepens longitudinal record completeness. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with health system CIOs, FHIR integration specialists, hospital procurement committee chairs, and GPO contracts managers. HIMSS analytics, CMS Medicare claims databases, FDA 510(k) submissions, and ONC certification records provided validation triangulation against bottom-up vendor sizing and top-down health IT expenditure models.
Data-stream reconciliation across deployment architecture, solution type, end-user category, and clinical application dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate synthesis and macro health IT expenditure elasticity modeling. Forecast inputs incorporated DiGA prescription volume trajectories, Medicare Advantage risk-adjustment documentation intensity, and METI Society 5.0 cross-sector data linkage adoption curves.
Several conditions sit outside the modeled scope, including proprietary EHR vendor API roadmap changes and state-level privacy law fragmentation effects. Forecasts reflect documented assumptions regarding FHIR implementation guidance stability and reimbursement policy continuity for patient-generated health data. Practitioners should monitor FDA enforcement discretion patterns and EU Health Data Space cross-border portability deadlines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market