
 Hospital Capacity Management Solutions Market | 2026-2036
Hospital Capacity Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Capacity Management Solutions Market Outlook
Hospital IT procurement is fragmenting as health networks bypass traditional group purchasing organizations to negotiate directly with specialized software vendors. Epic Systems Corporation leverages its dominant position in electronic health records to bundle capacity management modules, while Cerner Corporation competes through cloud-native architectures that promise faster deployment cycles. TeleTracking Technologies Inc. anchors its market presence with deep specialization in real-time patient flow analytics.
Hospital capacity management solutions encompass integrated software platforms that synchronize bed availability, staff scheduling, and patient throughput across acute care facilities, typically processing HL7 FHIR data feeds with sub-minute latency to support operational command centers. The technology dimension tilts toward cloud-based deployments as hospitals seek elastic compute for surge capacity modeling, while the end-user base shifts toward integrated health networks rather than standalone hospitals, reflecting consolidation in buyer structures. Platform offerings command margin premiums over pure analytics tools by embedding predictive algorithms for length-of-stay forecasting.
The FDA's interoperability mandates and the ONC's information blocking rules compel vendors to certify against standardized APIs, reshaping product roadmaps toward open architecture. Germany's Hospital Future Act and the EU's NIS2 Directive impose cybersecurity and resilience standards that filter market access for non-compliant suppliers. Stakeholders must weigh the capital efficiency of public cloud deployment against emerging data sovereignty requirements in European jurisdictions.
Market Dynamics
The hospital capacity management market is reconfiguring around real-time data interoperability mandates, with the FDA's 21st Century Cures Act and ONC information blocking rules forcing vendors to rebuild platforms around standardized HL7 FHIR APIs rather than proprietary data architectures.
Growth Catalysts
- Interoperability Mandates:The FDA's 21st Century Cures Act compels health networks to replace siloed capacity systems with platforms certified for standardized data exchange, accelerating replacement cycles for legacy installations.
- Federal Funding Channels:Germany's Hospital Future Act directs federal reimbursement toward integrated capacity planning systems, creating procurement pull for vendors with EU cybersecurity certification under the NIS2 Directive.
- Cloud Elasticity:Surge capacity modeling for pandemic preparedness is driving adoption of cloud-native architectures that scale compute resources dynamically during demand spikes.
Market Restraints
- Data Sovereignty Requirements:European jurisdictions are imposing residency restrictions on patient data, complicating multi-tenant cloud deployments and forcing redundant infrastructure investments.
- Legacy System Entrenchment:Deep integration with existing EHR installations creates switching costs that extend sales cycles and favor incumbent vendors with established hospital relationships.
- Cybersecurity Certification Burden:The EU's NIS2 Directive and Germany's BSI baseline protection standards filter market access for non-compliant suppliers, raising compliance overhead for specialized vendors.
Strategic Opportunities
- Ambulatory Network Extension:Post-acute and outpatient facilities remain underpenetrated for capacity optimization, offering expansion paths beyond saturated inpatient markets.
- Predictive Algorithm Licensing:Length-of-stay forecasting modules can be unbundled and sold to third-party platforms, creating recurring revenue streams from intellectual property.
- Staffing Integration:Convergence of bed management with nurse scheduling and float pool optimization addresses labor cost pressures that now exceed capital efficiency concerns for hospital CFOs.
Industry Challenges
- Interoperability Engineering Talent:Scarce expertise in HL7 FHIR implementation and SMART on FHIR app frameworks constrains vendor development timelines and inflates compensation costs.
- Legacy Data Migration Complexity:Extracting historical patient flow data from decades-old mainframe systems without disrupting live operations requires phased cutover strategies that extend project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Capacity Management Solutions Market |
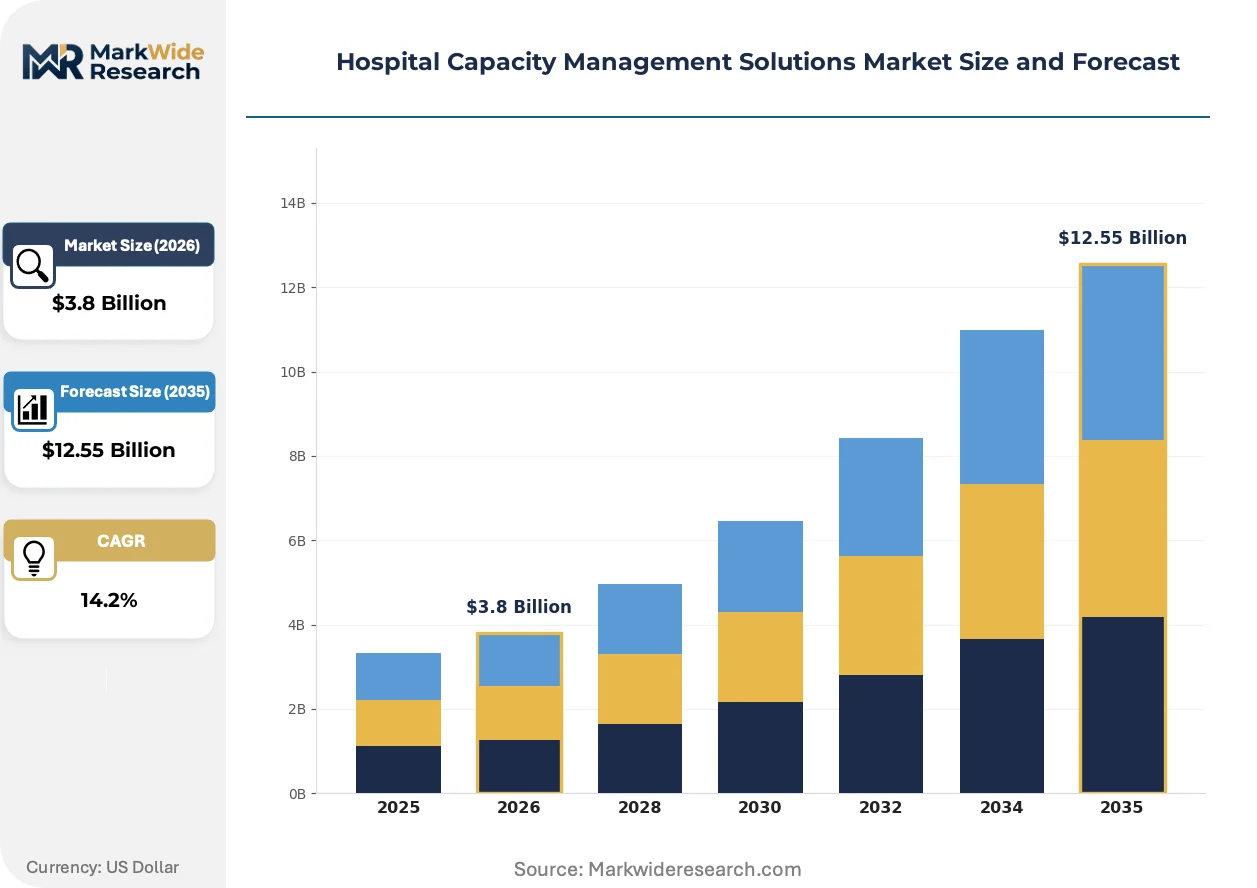
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Analytics Tool, Dashboard Technology: Cloud-Based, On-Premise, Hybrid, Mobile Application End User: Hospitals, Clinics, Emergency Departments, Health Networks Deployment: Public Cloud, Private Cloud, Community Cloud, Onsite |
| Companies Covered | Koninklijke Philips N.V., McKesson Corporation, GE HealthCare Technologies Inc., Siemens Healthineers AG, Allscripts Healthcare Solutions Inc., TeleTracking Technologies Inc., Cerner Corporation, Oracle Health, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Capacity Management Solutions Market Strategic Shifts
Hospital capacity platforms are pivoting from retrospective reporting to predictive command centers, embedding machine learning models that anticipate bottlenecks before they materialize and automate resource reallocation protocols.
Real-time patient flow analytics is migrating from standalone departmental dashboards to enterprise-wide operational command centers. Integrated health networks in the United States are consolidating previously siloed emergency department, surgical suite, and inpatient unit visibility into unified platforms. This technology compression is collapsing the vendor landscape by favoring platforms with embedded predictive capabilities over pure-play analytics tools.
The EU's NIS2 Directive imposes mandatory incident reporting and supply-chain security requirements on critical healthcare infrastructure operators. Vendors must now certify components against European cybersecurity frameworks to maintain market access in Germany, France, and Benelux markets. Hospital procurement committees are inserting NIS2 compliance clauses into RFP evaluations, filtering supplier pools before technical assessments begin.
Health networks are consolidating vendor relationships and bypassing traditional group purchasing organizations to negotiate directly with specialized software providers. Direct contracting allows buyers to demand customized SLA terms for sub-minute latency guarantees and dedicated implementation support. This channel disintermediation is most visible in the United States, where IDN consolidation has concentrated purchasing power among fewer decision-makers with specialized IT procurement expertise.
Hospital Capacity Management Solutions Market Segmentation
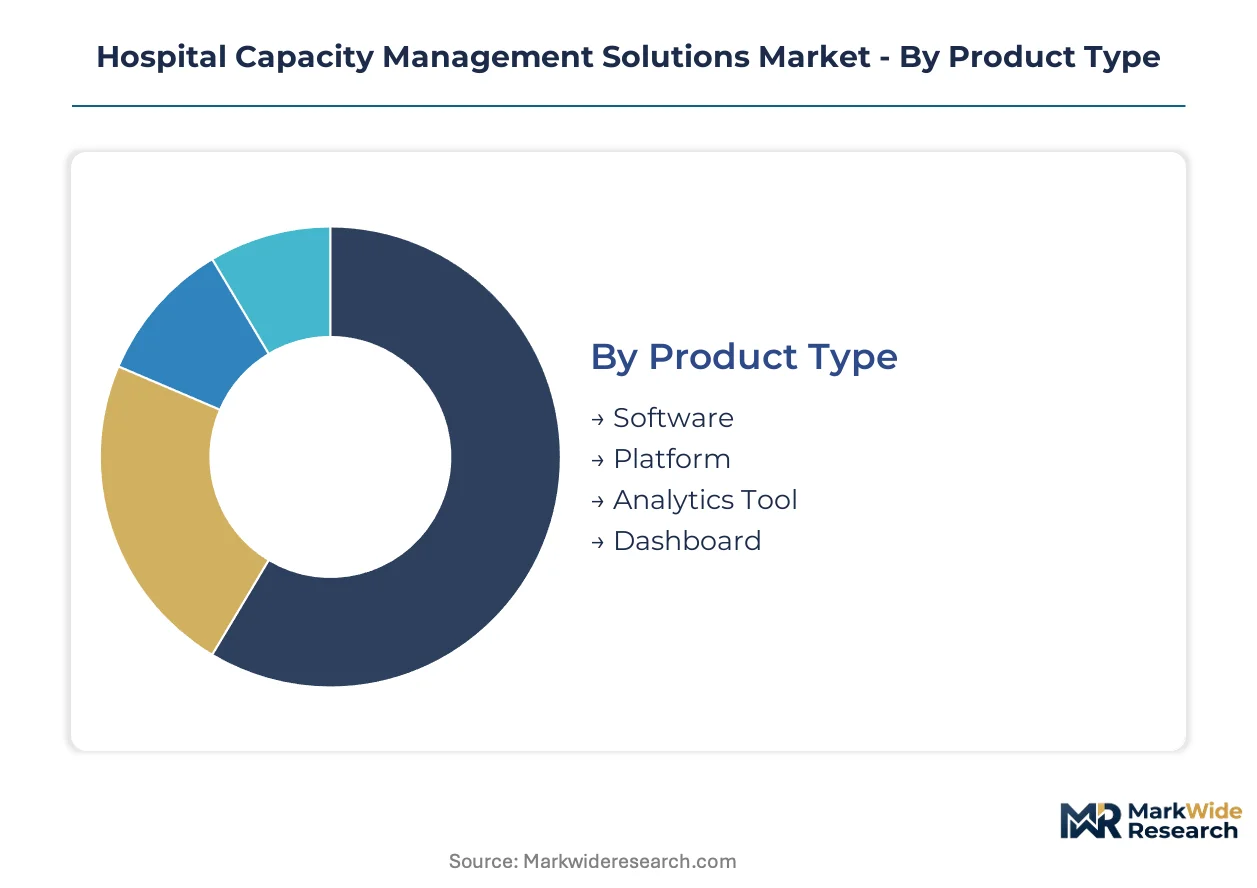
Hospital capacity management solutions segment across product architecture, infrastructure model, buyer organization, and hosting environment. These dimensions determine integration complexity, procurement authority, and compliance requirements for vendors navigating fragmented health system structures.
Product Type:
Cost tier separates comprehensive platforms from specialized point solutions, with pricing and implementation scope varying dramatically across the spectrum.
- Software:Modular applications addressing specific workflows such as bed turnover or discharge planning. Health networks in Germany prioritize these for phased digitization under federal reimbursement programs.
- Platform:Integrated systems unifying patient flow, staff scheduling, and resource allocation through HL7 FHIR data exchange. The steepest expansion runs through health networks consolidating previously siloed departmental systems.
- Analytics Tool:Purpose-built forecasting engines for length-of-stay prediction and demand modeling. Demand concentrates among academic medical centers with dedicated data science teams.
- Dashboard:Visualization layers presenting real-time capacity metrics to operational command centers. Smaller community hospitals favor these for rapid deployment without core system replacement.
Platform offerings command margin premiums through embedded predictive capabilities. Software modules represent the fastest path to revenue for specialized entrants.
Technology:
Deployment architecture determines scalability, data sovereignty compliance, and total cost of ownership for health system infrastructure teams.
- Cloud-Based:Elastic compute resources scaling dynamically for surge capacity modeling during pandemic or mass casualty events. European jurisdictions impose data residency restrictions that complicate multi-tenant configurations.
- On-Premise:Locally hosted installations maintaining physical control over patient data. German hospitals under BSI baseline protection standards favor these for cybersecurity certification.
- Hybrid:Split architectures processing sensitive data onsite while leveraging cloud analytics for non-identifiable operational metrics. The steepest expansion runs through mid-sized health networks balancing agility with compliance.
- Mobile Application:Point-of-care interfaces enabling bed management from smartphones or tablets. Emergency department physicians drive adoption for real-time patient flow decisions.
Cloud-based deployments attract the newest procurement cycles. Hybrid configurations retain the largest installed base among risk-averse buyers.
End User:
Buyer organization type shapes purchasing process complexity, integration requirements, and vendor relationship structures.
- Hospitals:Individual acute care facilities with standalone IT procurement authority. These buyers increasingly bypass group purchasing organizations for direct vendor negotiation.
- Clinics:Outpatient and ambulatory settings with lighter capacity optimization needs. Post-acute network expansion targets this underpenetrated segment.
- Emergency Departments:High-velocity environments where sub-minute bed assignment latency directly impacts throughput. The steepest expansion runs through departments integrating surgical suite and inpatient visibility.
- Health Networks:Consolidated integrated delivery networks with centralized IT governance. These buyers demand enterprise-wide command centers replacing departmental silos.
Health networks concentrate purchasing power and drive platform consolidation. Emergency departments represent the most technically demanding implementation environment.
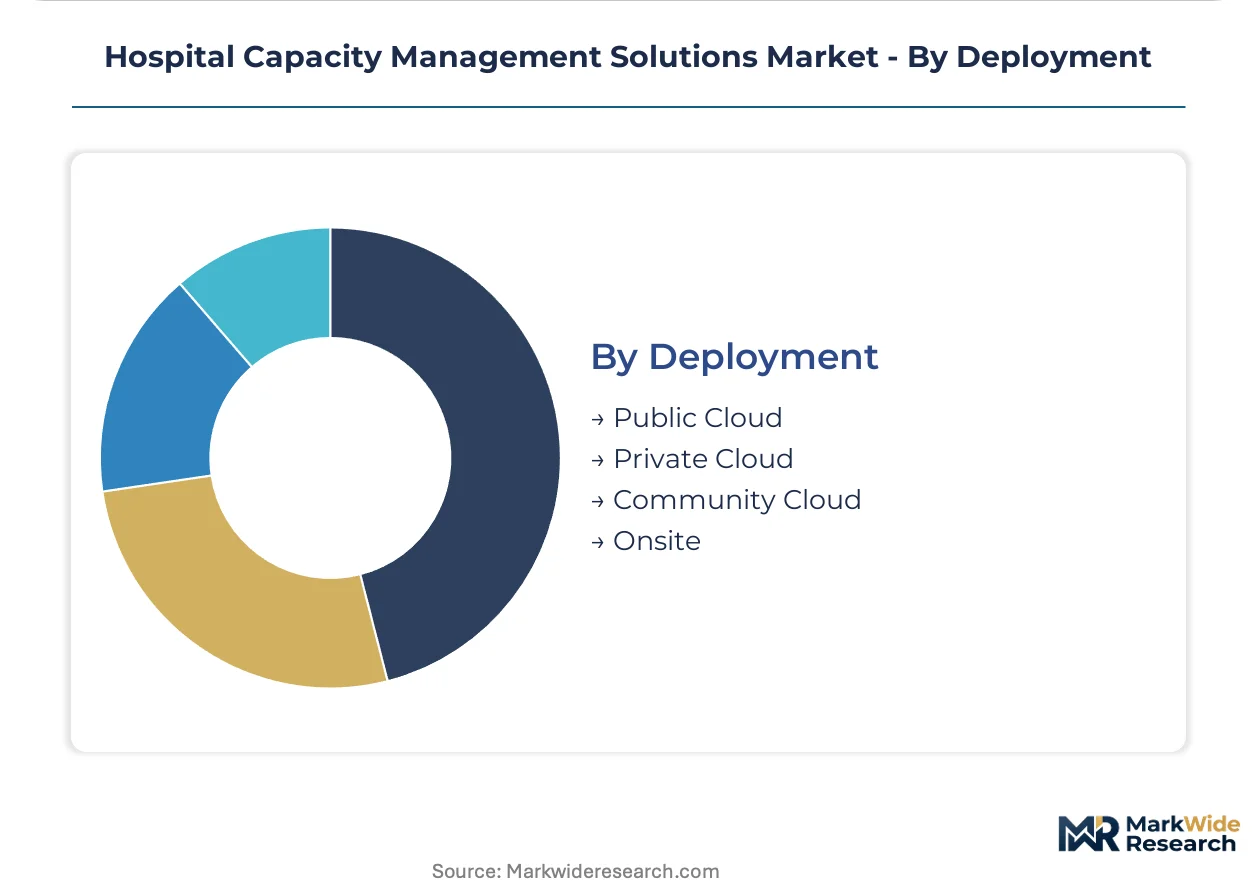
Deployment:
Hosting environment selection reflects tradeoffs between operational control, capital efficiency, and regulatory compliance across jurisdictions.
- Public Cloud:Shared infrastructure delivering lowest unit economics for variable workloads. Germany's NIS2 Directive and data sovereignty requirements filter supplier eligibility.
- Private Cloud:Dedicated tenant environments isolating patient data while retaining cloud operational models. The steepest expansion runs through European health systems navigating residency restrictions.
- Community Cloud:Collaborative infrastructure shared among regional health systems with mutual compliance frameworks. Rural hospital alliances in the United States favor these for cost pooling.
- Onsite:Traditional data center installations with full hardware ownership. Legacy system entrenchment extends replacement cycles for these configurations.
Private cloud deployments gain share fastest among compliance-sensitive buyers. Public cloud retains cost advantages for non-regulated operational analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA interoperability mandates anchor the United States market, while Germany's Hospital Future Act channels federal reimbursement toward digitized capacity systems. These regulatory frameworks concentrate procurement authority among integrated health networks seeking enterprise-wide command centers.
United States
Health networks in Texas and California consolidate previously siloed emergency department and surgical suite visibility into unified platforms. The FDA's 21st Century Cures Act compels replacement of proprietary data architectures with HL7 FHIR-certified systems. The Greater Boston cluster drives adoption of predictive length-of-stay forecasting among academic medical centers with dedicated data science teams.
Germany
Federal funding under the Hospital Future Act reimburses integrated capacity planning systems at hospitals in Bavaria and North Rhine-Westphalia. The NIS2 Directive and BSI baseline protection standards filter supplier eligibility, favoring vendors with EU cybersecurity certification. Berlin-Brandenburg health systems favor on-premise deployments to maintain physical data control under national resilience frameworks.
United Kingdom
NHS integrated care systems in London and the Midlands consolidate vendor relationships through direct negotiation rather than traditional procurement frameworks. The NHS Long Term Plan mandates operational command centers linking acute and community capacity. Manchester and Birmingham health economies pilot cloud-native surge modeling for pandemic preparedness.
France
Regional health agencies in Île-de-France and Auvergne-Rhône-Alpes channel public hospital modernization funds toward real-time patient flow platforms. ANSM guidance on medical device cybersecurity intersects with CNIL data protection requirements for patient tracking systems. The Lyon-Grenoble cluster concentrates academic hospital demand for predictive analytics modules.
Japan
Metropolitan Tokyo and Osaka prefectures drive demand for mobile point-of-care interfaces enabling bed management from smartphones. METI's Society 5.0 healthcare digitization roadmap accelerates hospital IT procurement cycles. The Nagoya-Chubu region concentrates mid-sized hospital adoption of hybrid cloud architectures balancing agility with data residency requirements.
Hospital Capacity Management Solutions Market Competitive Environment
Electronic health record incumbents and specialized patient flow vendors split the market between bundled platform strategies and deep workflow specialization. The vendor landscape compresses around two dominant archetypes: diversified health IT conglomerates leveraging installed base relationships, and focused specialists commanding premium positioning through real-time analytics expertise. Competitive dynamics center on cloud-native architecture races and direct contracting bypass of traditional group purchasing organizations.
Within the diversified health IT tier, Epic Systems Corporation and Cerner Corporation exemplify platform bundling strategies that embed capacity management within broader electronic record ecosystems. TeleTracking Technologies Inc. occupies the specialist archetype, anchoring market presence through dedicated patient flow analytics. Koninklijke Philips N.V. and Siemens Healthineers AG represent medical device conglomerates extending into operational software through hardware-software integration. These three strategic groupings—EHR bundlers, workflow specialists, and device-to-software extenders—collectively shape procurement committee evaluations across North American and European health systems.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| McKesson Corporation |
| GE HealthCare Technologies Inc. |
| Siemens Healthineers AG |
| Allscripts Healthcare Solutions Inc. |
| TeleTracking Technologies Inc. |
| Cerner Corporation |
| Oracle Health |
| Epic Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on HL7 FHIR-certified engineering talent concentrates pricing power among established vendors while compressing margins for specialized entrants, simultaneously forcing supply chain restructuring toward EU-certified development centers and away from tariff-exposed offshore delivery models.
Pricing Analysis
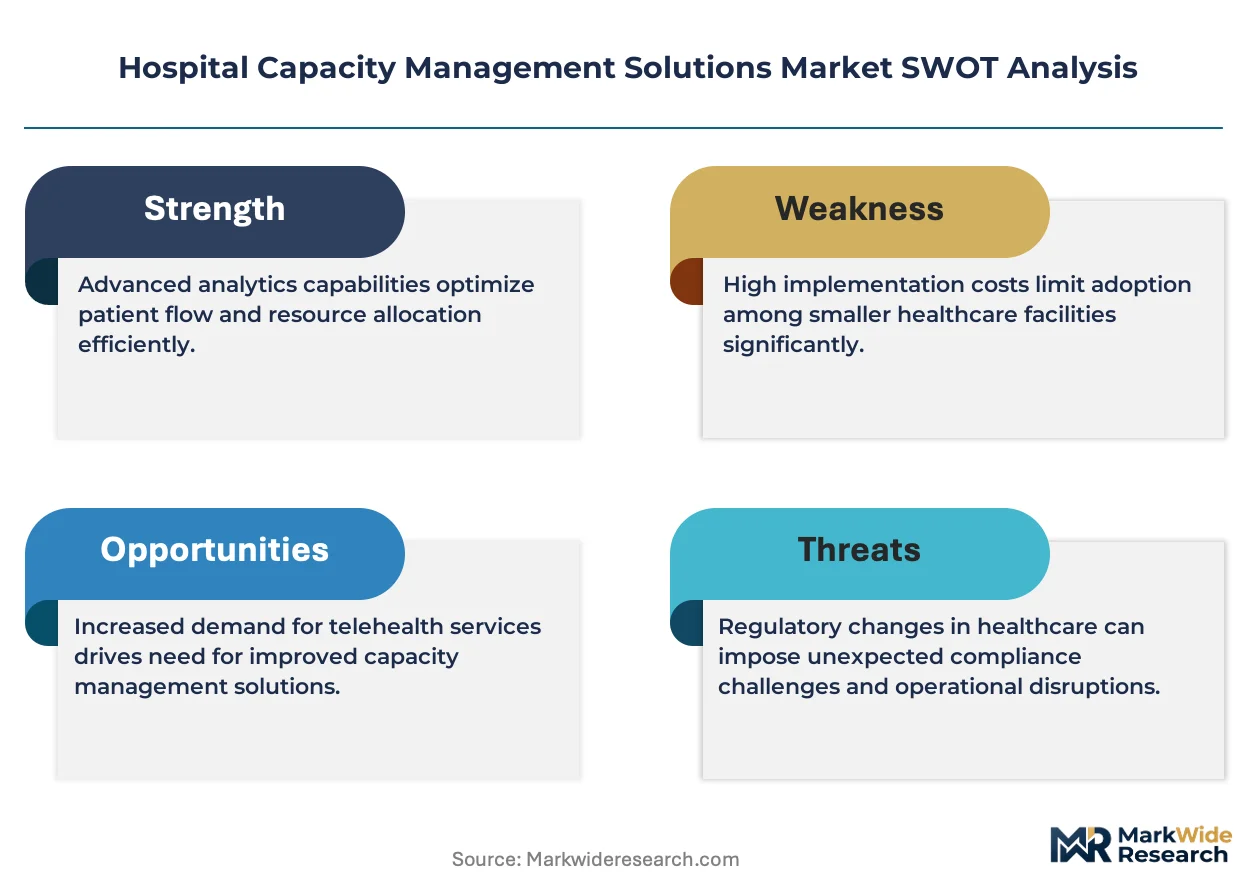
Configured-to-order pricing for platform deployments commands premiums of 40-60 percent above standard SaaS tiers due to embedded predictive modules and custom SLA guarantees for sub-minute latency. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth, with FDA 21st Century Cures Act compliance and EU NIS2 cybersecurity certification as the primary differentiation drivers. Cost compression in the standard tier intensifies because cloud-native entrants are undercutting legacy on-premise vendors. Community hospitals and standalone clinics exhibit the highest price sensitivity, while integrated health networks prioritize total cost of ownership over license fees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for hardware-dependent edge computing components used in operational command centers. Software development concentrates in the United States, Germany, and India, with Indian delivery centers facing escalating BSI baseline protection compliance costs for German hospital contracts. The technology stack draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform for elastic compute, alongside specialized HL7 FHIR middleware from domestic vendors. Distribution runs through direct vendor contracts with health networks, bypassing traditional group purchasing organizations as procurement authority consolidates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hospital capacity management market sits at an inflection where FDA interoperability mandates and EU NIS2 cybersecurity rules are simultaneously forcing platform rebuilds and filtering supplier pools, creating asymmetric opportunity for compliant vendors.
For Market Incumbents: Harden defensive moats by acquiring HL7 FHIR engineering specialists to address talent scarcity, and deepen backward integration into cloud infrastructure to control latency guarantees for health network SLAs. Cloud-native entrants with faster deployment cycles represent the primary substitution threat, while EU cybersecurity certification costs are compressing margins for non-compliant product lines. For New Entrants and Emerging Players: Establish a beachhead in ambulatory network capacity optimization, the most penetrable segment where post-acute facilities remain underserved by inpatient-focused incumbents. Target community cloud deployments for rural hospital alliances in the United States, where cost-pooling creates procurement entry points without direct competition from Epic and Cerner. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized workflow vendors with embedded predictive IP over diversified health IT conglomerates. Length-of-stay forecasting algorithm licensing and surge capacity modeling capabilities signal long-term viability across a 5-10 year window. Watch for FDA enforcement actions on information blocking as the inflection indicator that accelerates replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies patient flow, staff scheduling, and resource allocation through HL7 FHIR exchange for health networks. |
| EU Cybersecurity Certification | BSI baseline protection and NIS2 compliance filter supplier eligibility in Germany, France, and Benelux markets. |
| Acquisition of Specialist Firm | HL7 FHIR engineering talent scarcity makes targeted acquisitions faster than organic capability building. |
| Geographic Expansion | Post-acute and outpatient facilities in ambulatory networks offer white-space growth beyond saturated inpatient markets. |
| Strategic Partnership | Direct contracts with integrated delivery networks bypass group purchasing organizations and capture margin premiums. |
Study Parameters
A standing panel of hospital CIOs, health network procurement directors, HL7 FHIR implementation specialists, and GPO contracts managers provided ongoing calibration across primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract registries, and EU NIS2 implementation guidance documents. Bottom-up sizing of vendor installations triangulated against top-down health IT spending estimates from national hospital associations.
Scenario-bracketing around interoperability mandate timelines and cybersecurity certification rollout schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, deployment model, buyer organization type, and regional regulatory cluster. CAGRs were derived from installation growth rates weighted by average contract value expansion. Forecast inputs incorporated federal reimbursement program allocations under Germany's Hospital Future Act and cloud infrastructure capex disclosures from major hyperscalers.
Sensitivities concentrate around FDA enforcement intensity for information blocking violations, EU NIS2 implementation variance across member states, and health network consolidation velocity affecting procurement authority concentration. Forecasts reflect assumptions about regulatory compliance timelines and technology adoption curves. Macroeconomic pressure on hospital capital budgets, regulatory deviation from published guidance, or breakthrough displacement by AI-native platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Aged Care Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Epharmacy Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
US Dental Clearing Houses Market