
 AI-Based Clinical Trials Solution Provider Market | 2026-2036
AI-Based Clinical Trials Solution Provider Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Based Clinical Trials Solution Provider Market Intelligence
Pharmaceutical companies is pivoting toward AI-native trial infrastructure as legacy electronic data capture systems prove inadequate for decentralized study models. IQVIA leverages its real-world data ecosystem to anchor protocol optimization services across North America and Europe. Saama competes through cloud-native analytics architectures that compress database lock timelines for mid-tier sponsors. Deep6.ai specializes in NLP-driven patient-trial matching that extracts structured eligibility criteria from unstructured clinical notes.
AI-based clinical trials solution providers deliver algorithmic platforms that automate patient identification, site selection, and adaptive protocol design through machine learning models trained on historical trial data, electronic health records, and genomic repositories. These systems reduce screening failure rates and enable continuous risk-based monitoring across distributed investigator sites. Machine Learning dominates current deployment, with Natural Language Processing representing the fastest-expanding technology layer as vendors parse free-text pathology reports and physician notes for eligibility signals. Patient Recruitment commands the largest addressable spend pool, while Protocol Optimization captures the highest marginal value per contract due to its direct impact on trial duration and regulatory submission timing.
The FDA's evolving guidance on AI/ML-based software as a medical device shapes product validation requirements and submission pathways for algorithmic trial tools. The EMA's qualification opinion process for novel methodologies and the FDA's decentralized clinical trial guidance collectively determine market access velocity across transatlantic development programs. Stakeholders must monitor regulatory divergence between FDA risk-based frameworks and EMA qualification pathways when architecting multi-regional platform deployments.
Market Dynamics
The FDA's draft guidance on AI/ML-enabled medical devices compresses vendor qualification timelines while pharmaceutical sponsors demand integrated data platforms that legacy electronic data capture systems cannot support for decentralized trials.
Growth Catalysts
- Decentralized trial mandates:The FDA's decentralized clinical trial guidance accelerates platform adoption as sponsors replace site-centric infrastructure with remote monitoring capabilities.
- Real-world data integration:Electronic health record connectivity enables algorithmic patient matching that reduces screening failure rates across oncology and rare disease protocols.
- EMA qualification pathways:The agency's novel methodology opinions create regulatory clarity for adaptive protocol designs in transatlantic development programs.
Market Restraints
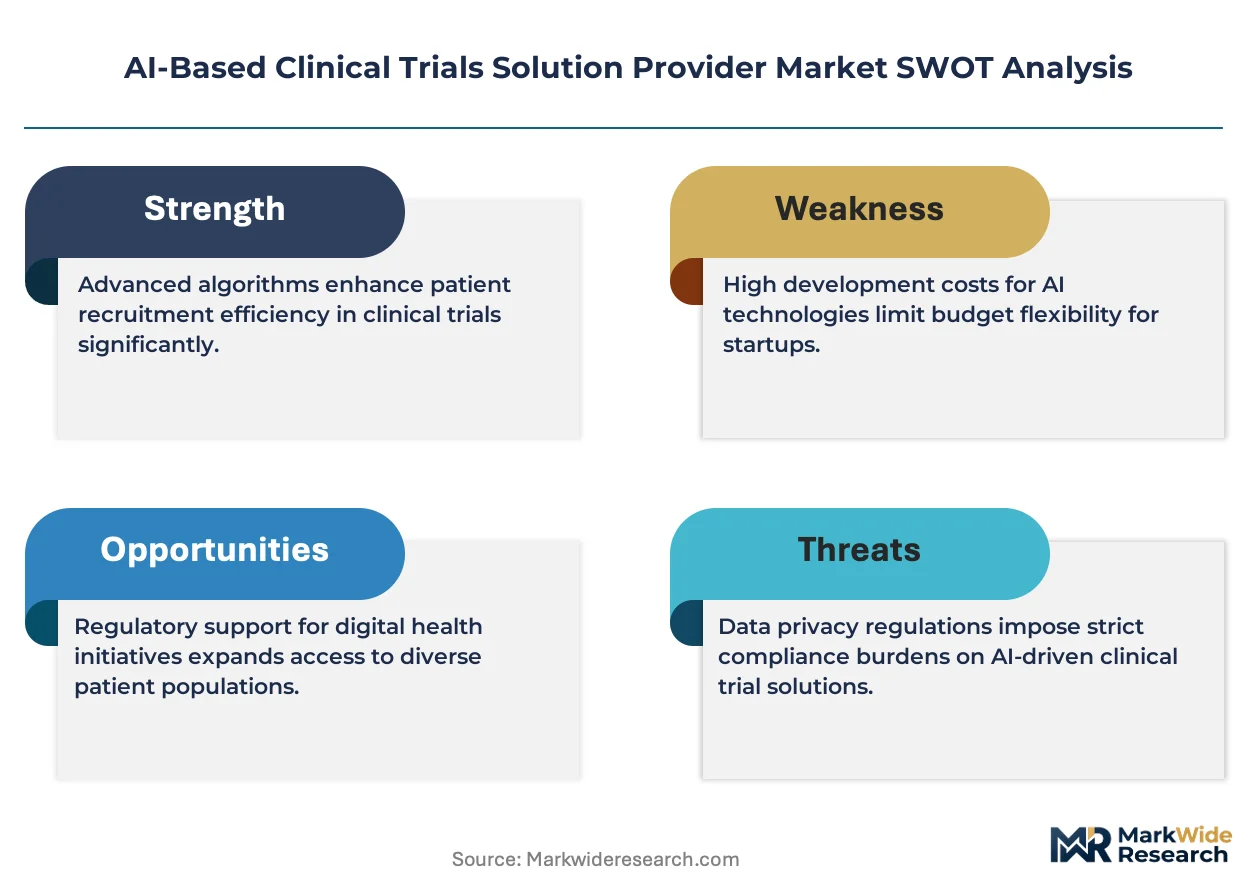
- Algorithm validation costs:FDA software-as-medical-device requirements impose extensive clinical performance studies that strain mid-tier vendor R&D budgets.
- Data silo fragmentation:Hospital system interoperability gaps limit NLP-driven patient matching effectiveness in community oncology networks.
- Specialized talent scarcity:Computational biology and regulatory science skill shortages constrain platform engineering velocity across vendor development teams.
Strategic Opportunities
- Asia-Pacific expansion:Japan's PMDA digital health guidance and South Korea's MFDS fast-track pathways create first-mover positioning for adaptive trial platforms.
- Genomic data convergence:Integration of machine learning models with CRISPR biomarker repositories enables precision protocol design for cell therapy trials.
- Site-less trial models:Direct-to-patient logistics partnerships bypass traditional investigator site bottlenecks in cardiovascular and metabolic disease recruitment.
Industry Challenges
- Legacy system integration:Electronic data capture migration projects face data mapping complexity and protocol amendment synchronization delays.
- Interoperability standardization:FHIR implementation gaps between health systems and trial platforms create manual data reconciliation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Based Clinical Trials Solution Provider Market |
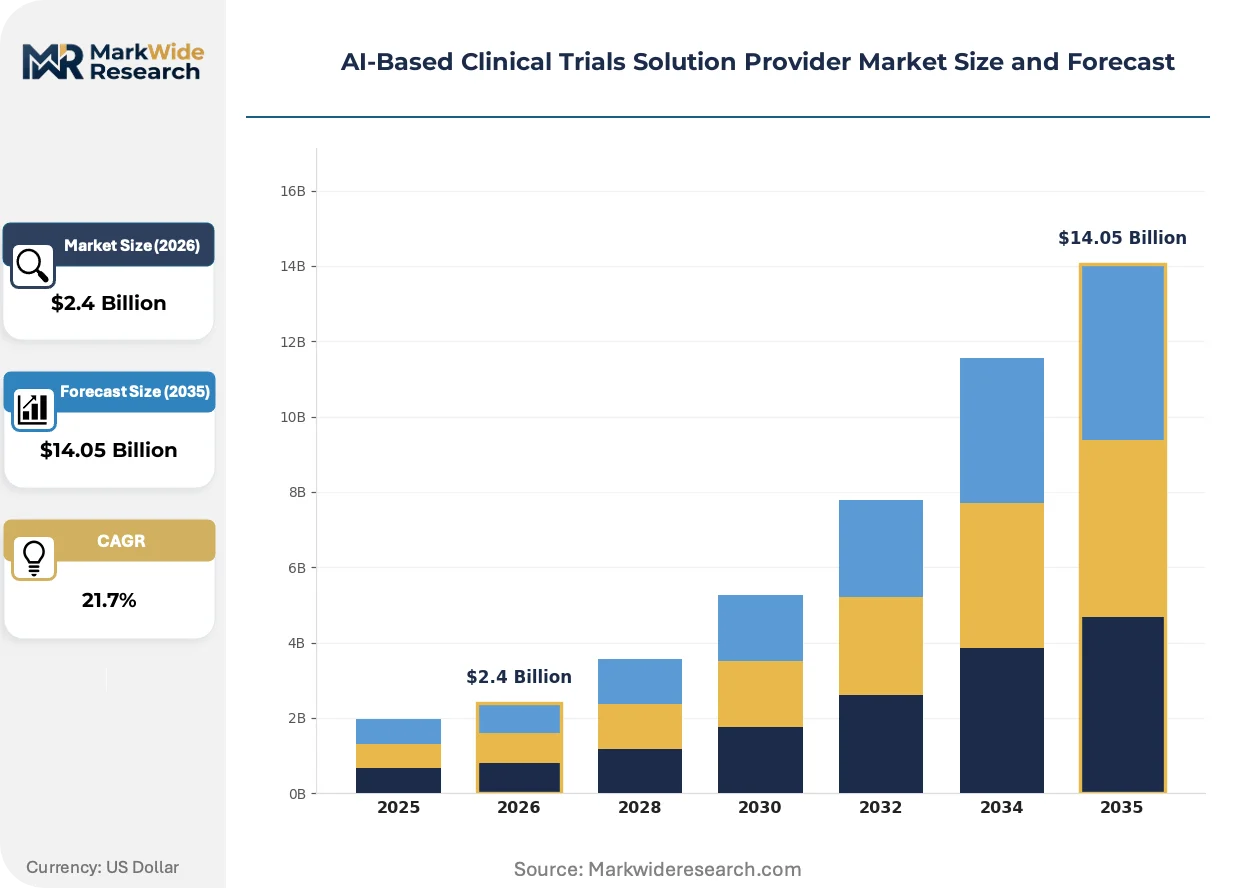
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analytics, Patient Recruitment, Risk Management, Protocol Optimization Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Cloud Computing End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Healthcare Providers Application: Disease Management, Treatment Protocol Development, Patient Engagement, Compliance Monitoring |
| Companies Covered | Unlearn.ai, Inc., Saama, Antidote Technologies, Inc., Medidata, IQVIA, Deep6.ai, Innoplexus, Mendel.ai, Phesi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Based Clinical Trials Solution Provider Market Strategic Shifts & Innovations
Natural language processing capabilities are reshaping how unstructured clinical data becomes actionable trial intelligence. Algorithmic platforms now parse pathology reports and physician notes at scale.
Federated learning architectures enable multi-site model training without centralizing protected health information. Pharmaceutical sponsors deploy these systems across hospital networks to preserve data sovereignty while refining patient eligibility algorithms. The technology is expanding into rare disease indications where single-site data volumes prove insufficient for standalone model development.
EMA's qualification opinion process for novel methodologies creates regulatory precedents for synthetic control arms and digital biomarkers. Sponsors filing transatlantic submissions now align protocol designs with both FDA risk-based frameworks and EMA methodological guidance. European mid-tier biotechs accelerate platform adoption to meet these dual compliance requirements.
Biopharma procurement teams consolidate vendor relationships around integrated platform suites rather than point solutions. Mid-tier sponsors particularly favor cloud-native architectures that compress database lock timelines and reduce IT infrastructure overhead. This concentration pattern is most visible in United States-based oncology and immunology development programs.
AI-Based Clinical Trials Solution Provider Market Segmentation
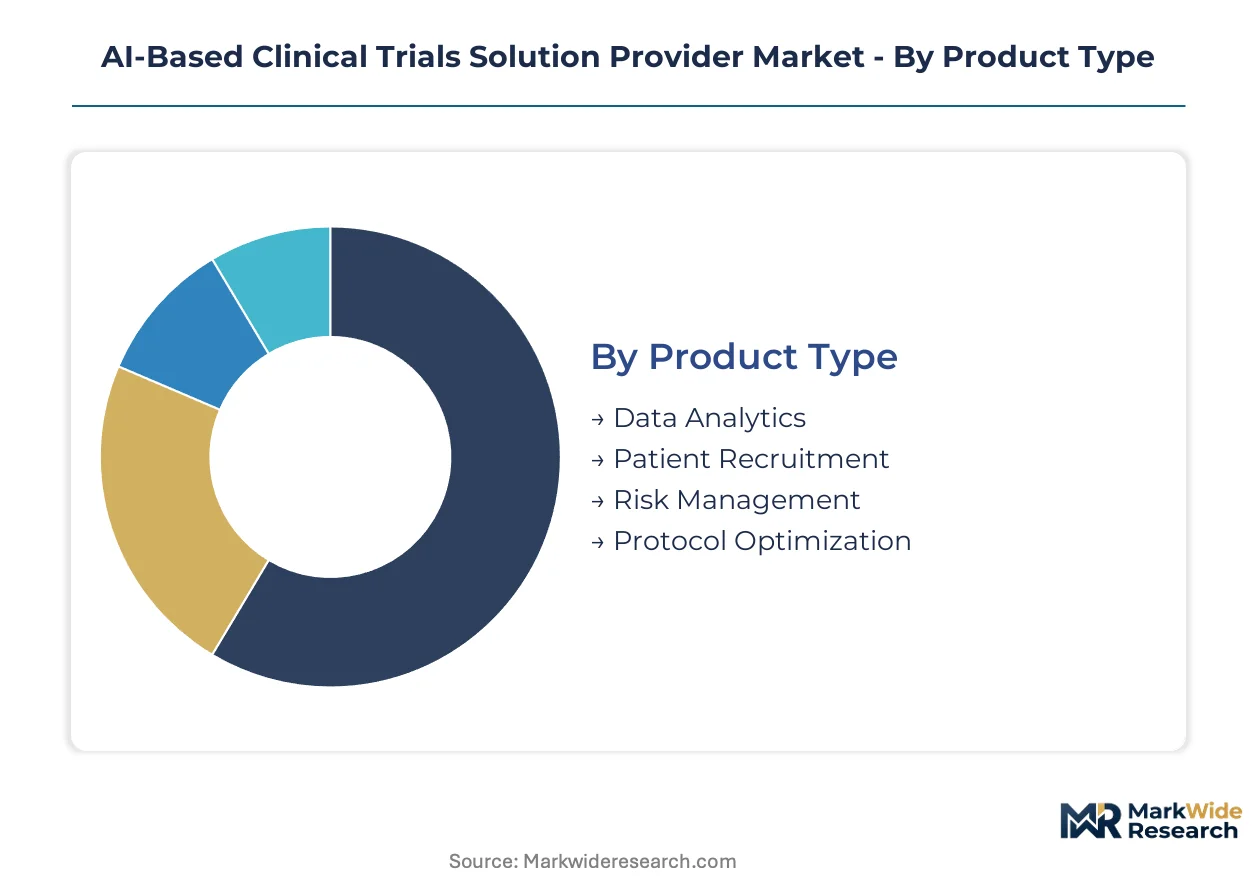
Segmentation reveals where capital deployment concentrates and which solution architectures command premium pricing. Vendors prioritize segments with the highest integration complexity and regulatory validation burdens.
Product Type:
Capital intensity varies sharply across product categories, with algorithmic validation and real-world data infrastructure demanding the heaviest upfront investment.
- Data Analytics:Platforms aggregate electronic health records, genomic repositories, and historical trial data into unified analytical environments. Pharmaceutical sponsors in the United States deploy these systems to compress database lock timelines and enable continuous risk-based monitoring across distributed sites.
- Patient Recruitment:NLP-driven matching engines parse unstructured clinical notes and pathology reports to identify eligible candidates. Demand concentrates in oncology networks where screening failure rates traditionally exceed 50%, with sponsors prioritizing tools that integrate directly with Epic and Cerner deployments.
- Risk Management:Algorithmic surveillance systems flag protocol deviations and safety signals through machine learning models trained on adverse event databases.
- Protocol Optimization:Adaptive design tools simulate enrollment trajectories and endpoint variability to refine inclusion criteria before site activation.
Most installed capacity flows through Data Analytics. Expansion is steepest in Patient Recruitment.
Technology:
Technology selection determines regulatory pathway complexity and talent acquisition costs for vendor engineering teams.
- Machine Learning:Supervised and unsupervised models power patient stratification, site feasibility scoring, and predictive enrollment forecasting. Deployment concentrates among top-20 biopharma sponsors with sufficient historical trial volumes to train proprietary algorithms.
- Natural Language Processing:Transformer architectures extract structured eligibility criteria from free-text physician notes and radiology reports. Community oncology networks in Texas and Florida drive adoption as these systems bridge interoperability gaps between hospital EHRs and trial databases.
- Predictive Analytics:Statistical models forecast trial duration, dropout rates, and regulatory submission timing.
- Cloud Computing:Elastic infrastructure enables federated learning across hospital networks without centralizing protected health information.
Machine Learning absorbs the largest share of vendor R&D expenditure. Natural Language Processing is climbing the fastest as unstructured data volumes expand.
End User:
Customer type dictates contract structure, with enterprise pharmaceutical sponsors demanding outcome-based pricing while mid-tier buyers prefer subscription models.
- Pharmaceutical Companies:Sponsors deploy integrated platform suites spanning patient matching through regulatory submission. IQVIA and Saama anchor procurement decisions among North American and European developers with decentralized trial mandates.
- Contract Research Organizations:CROs license white-label analytics tools to differentiate site selection and monitoring services. Mid-tier CROs in the United States favor cloud-native architectures that reduce IT infrastructure overhead.
- Academic Institutions:University medical centers pilot federated learning models for rare disease indications.
- Healthcare Providers:Hospital systems purchase patient matching modules to increase trial accessibility for underserved populations.
Pharmaceutical Companies account for the majority of contract value. Healthcare Providers are gaining share fastest as site-less trial models expand.
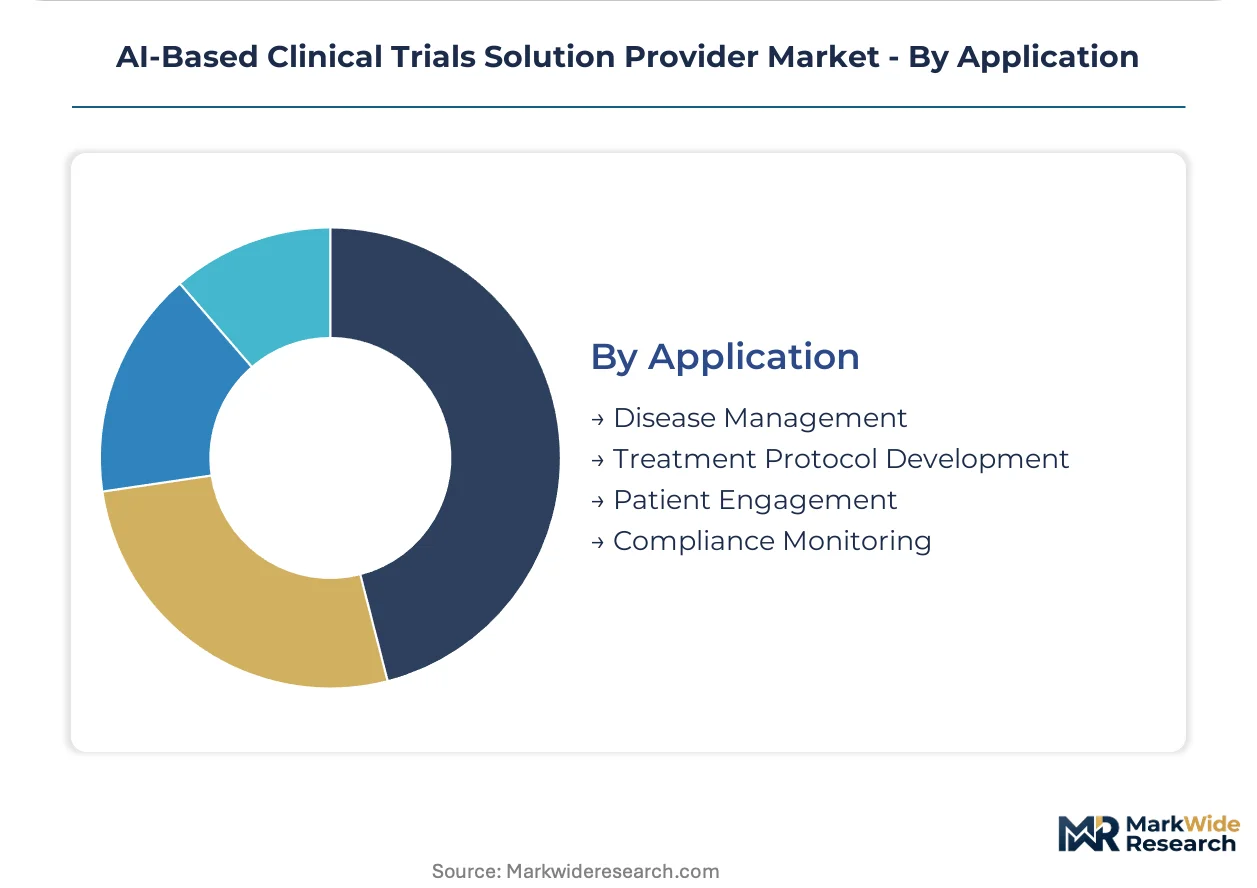
Application:
Application focus shapes regulatory validation requirements, with disease management tools facing FDA software-as-medical-device scrutiny.
- Disease Management:Platforms track biomarker trajectories and symptom progression to refine dosing schedules and intervention timing. Oncology and immunology programs in the United States drive deployment as sponsors integrate real-world evidence into regulatory submissions.
- Treatment Protocol Development:Simulation engines model dose-response relationships and population heterogeneity to optimize phase II designs. Rare disease developers leverage these tools where historical control data proves insufficient for traditional randomized designs.
- Patient Engagement:Mobile applications and wearable integrations capture electronic patient-reported outcomes.
- Compliance Monitoring:Automated systems verify protocol adherence through pharmacy records and site visit documentation.
Disease Management carries the heaviest regulatory validation burden. Treatment Protocol Development is expanding most quickly as adaptive trial designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor jurisdictions with streamlined AI/ML validation pathways, drawing platform development toward the United States and select European markets while Asia-Pacific regulators accelerate digital health guidance to capture biopharma investment flows.
United States
FDA draft guidance on AI/ML-enabled medical devices compresses vendor qualification timelines, attracting platform engineering investment. The agency's decentralized clinical trial guidance creates compliance clarity for remote monitoring architectures. Boston and San Francisco anchor development clusters where IQVIA and Deep6.ai refine NLP-driven patient matching for oncology networks.
Germany
EMA qualification opinions for novel methodologies establish regulatory precedents that German sponsors leverage for adaptive protocol designs. The country's national pharmaceutical regulator aligns with EU AI Act requirements for algorithmic transparency in clinical decision support. Heidelberg and Munich concentrate vendor engineering teams serving mid-tier European biotechs.
United Kingdom
MHRA recognition of FDA validation studies reduces duplicate clinical performance burdens for transatlantic platform deployments. The country's life sciences strategy prioritizes federated learning infrastructure for rare disease indications. London's Golden Triangle clusters academic medical centers piloting multi-site model training without centralizing protected health information.
Japan
PMDA digital health guidance creates first-mover positioning for adaptive trial platforms in cell therapy and regenerative medicine. The regulator's fast-track pathways for AI-enabled medical devices accelerate market access velocity. Tokyo and Osaka host biopharma procurement teams consolidating vendor relationships around integrated platform suites.
South Korea
MFDS fast-track pathways for software-as-medical-device products attract cloud-native analytics vendors seeking Asia-Pacific expansion. The country's national pharmaceutical regulator emphasizes real-world evidence integration for regulatory submissions. Seoul's digital health corridor concentrates engineering talent for federated learning architectures serving hospital networks.
AI-Based Clinical Trials Solution Provider Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical sponsors consolidating procurement around integrated platform suites while mid-tier buyers license point solutions. The vendor base concentrates among data-centric incumbents with real-world data ecosystems and cloud-native challengers compressing implementation timelines. Three archetypes dominate: legacy CROs with captive technology assets, pure-play AI vendors with NLP specializations, and health IT platforms extending into trial infrastructure. Competitive moves center on federated learning partnerships with hospital networks and outcome-based pricing models tied to screening failure rate reductions.
Within the pure-play AI tier, Unlearn.ai, Inc. and Deep6.ai occupy positions exemplifying algorithmic specialization in patient matching and synthetic control arm generation. Saama anchors the cloud-native challenger archetype for mid-tier sponsors seeking compressed database lock timelines. IQVIA represents the integrated incumbent model, leveraging proprietary real-world data assets across North American and European deployments. These three company structures illustrate the strategic segmentation between point-solution depth and platform breadth that shapes vendor selection criteria.
| Leading Market Players |
|---|
| Unlearn.ai, Inc. |
| Saama |
| Antidote Technologies, Inc. |
| Medidata |
| IQVIA |
| Deep6.ai |
| Innoplexus |
| Mendel.ai |
| Phesi |
| Others |
Cost & Logistics Intelligence
Computational biology and regulatory science talent scarcity in the United States and Germany widens pricing spreads between premium integrated platforms and economy-tier point solutions, as labor-cost differentials in algorithm development and FDA validation studies cascade through vendor cost structures.
Pricing Analysis
Direct-to-pharma pricing bypasses distributor markups for enterprise sponsors, while mid-tier buyers absorb channel margins through CRO intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates outcome-based contracts with screening-failure guarantees from subscription SaaS tiers and per-study licensing. Cost compression in economy tiers is intensifying because cloud-native challengers commoditize basic NLP matching capabilities. Mid-tier biotechs exhibit highest price sensitivity, while top-20 pharmaceutical sponsors prioritize outcome certainty over per-seat costs.
Supply Chain Analysis
Cloud infrastructure freight costs are negligible, yet data sovereignty requirements fragment compute deployment across the United States, Germany, and Japan. Algorithm training draws from electronic health record repositories, genomic databases, and historical trial archives. Single-source vulnerability concentrates in proprietary real-world data ecosystems controlled by incumbent vendors. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors, with channel partners serving academic medical centers and regional hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive advantage, with the FDA's draft guidance on AI/ML-enabled medical devices accelerating vendor qualification timelines and concentrating procurement among pre-qualified platform providers.
For Market Incumbents: To counter cloud-native challengers compressing implementation timelines, IQVIA and data-centric incumbents should deepen captive supply of proprietary real-world data assets through exclusive hospital network partnerships, while accelerating FDA software-as-medical-device pre-certification investments to extend qualification timelines for mid-tier entrants. For New Entrants and Emerging Players: The premium-to-economy price-point gap in patient recruitment modules creates white-space opportunity for NLP specialists targeting community oncology networks in Texas and Florida with Epic-integrated deployment models, using federated learning architectures as the go-to-market differentiator against centralized data platforms. For Investors and Strategic Acquirers: Pharmaceutical technology divisions are the most active acquirer in this space, seeking cloud-native analytics capabilities to modernize legacy electronic data capture infrastructure. Long-term viability hinges on regulatory validation moats rather than algorithmic novelty alone. Acquisition targets should display FDA qualification progress or EMA novel methodology opinions. The signal to watch is biopharma procurement consolidation velocity around integrated platform suites versus point-solution fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Investment | Accelerates vendor qualification timelines for AI/ML-enabled trial tools under FDA draft guidance. |
| Federated Learning Partnership | Preserves data sovereignty across hospital networks while refining patient eligibility algorithms. |
| Real-World Data Acquisition | Captures proprietary electronic health record repositories to anchor protocol optimization services. |
| Cloud-Native Architecture Deployment | Compresses database lock timelines for mid-tier sponsors replacing legacy electronic data capture. |
| EMA Qualification Alignment | Creates regulatory clarity for adaptive protocol designs in transatlantic development programs. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with drug development executives, regulatory affairs leads, clinical data scientists, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and biopharma vendor contract disclosures. Bottom-up and top-down triangulation cross-validates platform deployment counts against sponsor R&D expenditure patterns.
Rate-of-change decomposition separates volume expansion in patient recruitment modules from value capture in protocol optimization services across the analysis window. Segmentation dimensions modeled include product type, technology layer, end-user category, and therapeutic area regulatory cluster. CAGRs derive from algorithmic adoption curves weighted by FDA guidance implementation phases and EMA qualification opinion timelines, with inputs from biopharma procurement survey data and vendor revenue attribution by solution category.
Caveats apply where regulatory divergence between FDA risk-based frameworks and EMA qualification pathways could materially shift the outlook, or where hospital system interoperability gaps stall NLP-driven patient matching effectiveness. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Humanized Mice Model Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
India CRO Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Ecoa, Esource & Clinical Trials Market