
 Patient Registry Software Market | 2026-2036
Patient Registry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Registry Software Market Intelligence
Expertise in clinical data science and regulatory compliance is unwinding the traditional, siloed approach to patient data management. This shift creates opportunities for specialized vendors. Oracle leverages its extensive database infrastructure to offer integrated solutions. IQVIA differentiates through its deep domain expertise in clinical trials and real-world evidence, while IBM competes using its advanced analytics and AI platforms.
Patient registry software is a specialized application designed to collect uniform clinical and patient-reported data for a specific population. These systems must support longitudinal data collection and adhere to interoperability standards like HL7 FHIR. Cloud-based deployments lead the market, offering scalability to end-users such as pharmaceutical companies. Among applications, chronic condition management and rare disease tracking are significant, reflecting focused research and drug development pipelines.
Regulatory frameworks from the FDA in the United States and the EMA in Europe set stringent requirements for data integrity and patient privacy. Compliance with mandates like GDPR and HIPAA is non-negotiable for market participants. The software's ability to support real-world evidence generation while ensuring interoperability with electronic health records will determine future vendor success.
Market Dynamics
The central force shaping the patient registry software market is the dual pressure from regulatory bodies demanding stringent data integrity and from pharmaceutical sponsors requiring agile, evidence-based insights for drug development and post-market surveillance.
Growth Catalysts
- Real-World Evidence Mandates:Regulatory bodies like the FDA and EMA are increasingly emphasizing the use of real-world evidence (RWE) for drug approval and post-market safety monitoring, directly stimulating demand for compliant registry platforms.
- Interoperability Standards:The adoption of data standards such as HL7 FHIR enables seamless data exchange between registry software and electronic health record (EHR) systems, reducing data silos and improving the quality of longitudinal data.
- Rare Disease Research Focus:Pharmaceutical and biotechnology firms are intensifying research on rare diseases, which necessitates specialized registries to identify patient cohorts, track disease progression, and support clinical trial recruitment.
Market Restraints
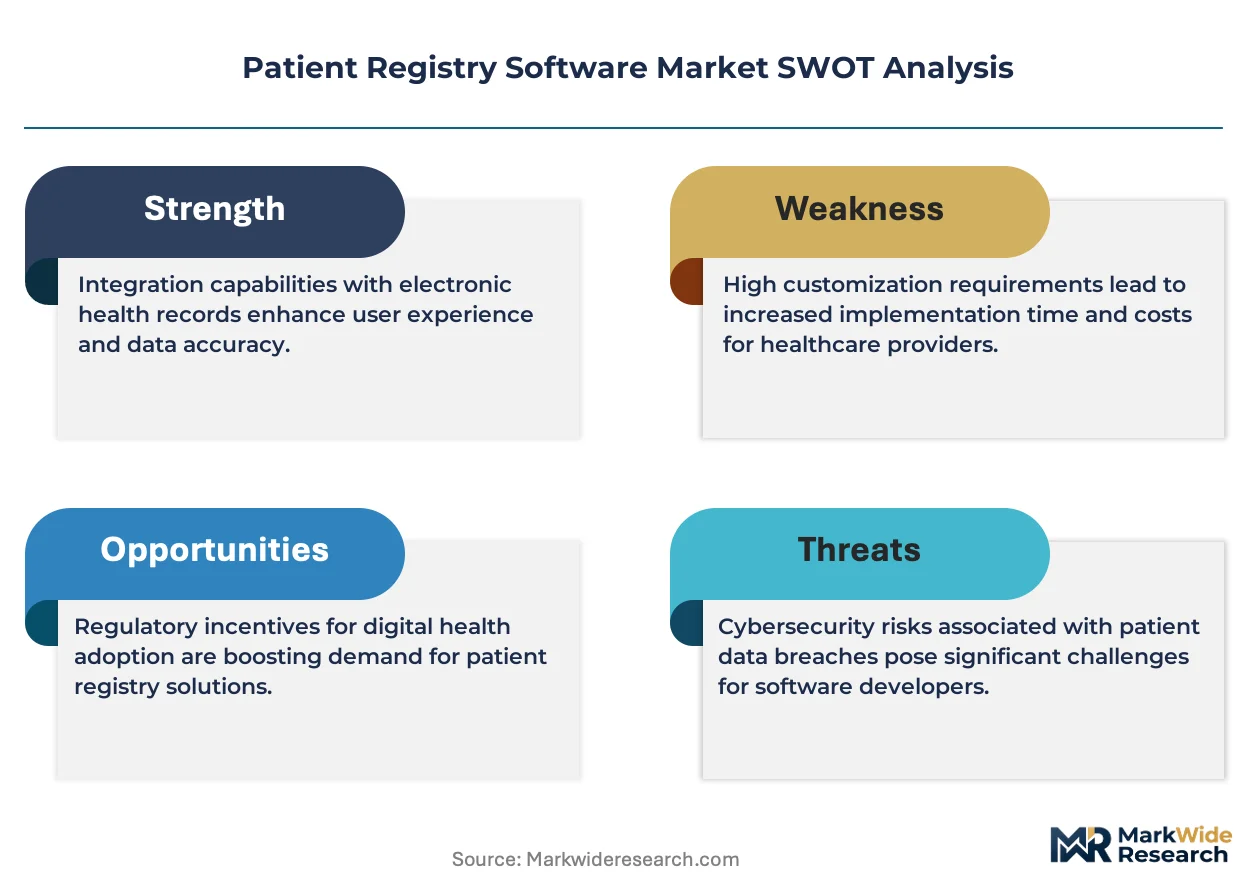
- High Implementation Costs:The initial investment for deploying, customizing, and validating patient registry software, particularly to meet strict HIPAA and GDPR compliance standards, presents a significant financial barrier for smaller research institutions.
- Legacy System Integration:Integrating modern, cloud-based registry platforms with older, heterogeneous legacy EHR systems within hospitals remains a major technical and operational hurdle, often causing data migration challenges.
- Fragmented Data Privacy Laws:Navigating the complex and often conflicting web of international, national, and state-level data privacy regulations, such as the EU's GDPR versus various US state laws, complicates multi-site studies.
Strategic Opportunities
- Emerging Market Penetration:Expanding clinical trial activities in regions like Latin America and Southeast Asia present an opportunity for vendors to offer scalable, cost-effective registry solutions tailored to local regulatory and infrastructure needs.
- Patient-Centric Data Models:The shift towards patient-centricity in drug development opens a market for modules focused on patient-reported outcomes (PROs) and data from wearables, enabling a more holistic view of the patient journey.
- AI and Predictive Analytics:Integrating artificial intelligence and machine learning algorithms with registry data can unlock predictive insights into disease progression, treatment efficacy, and patient risk stratification, offering high-value services.
Industry Challenges
- Clinical Informatics Talent Gap:A persistent shortage of professionals possessing hybrid expertise in clinical research, data science, and evolving global regulatory frameworks like GxP creates an operational bottleneck for both vendors and end-users.
- Data Source Harmonization:The operational difficulty of standardizing and harmonizing data collected from diverse sources, including labs, pharmacies, and patient mobile apps, challenges the creation of a single, reliable longitudinal record.
- Cybersecurity Threats:As patient registries centralize sensitive health information, they become high-value targets for cyberattacks, demanding constant investment in advanced security protocols to protect data integrity and patient privacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Registry Software Market |
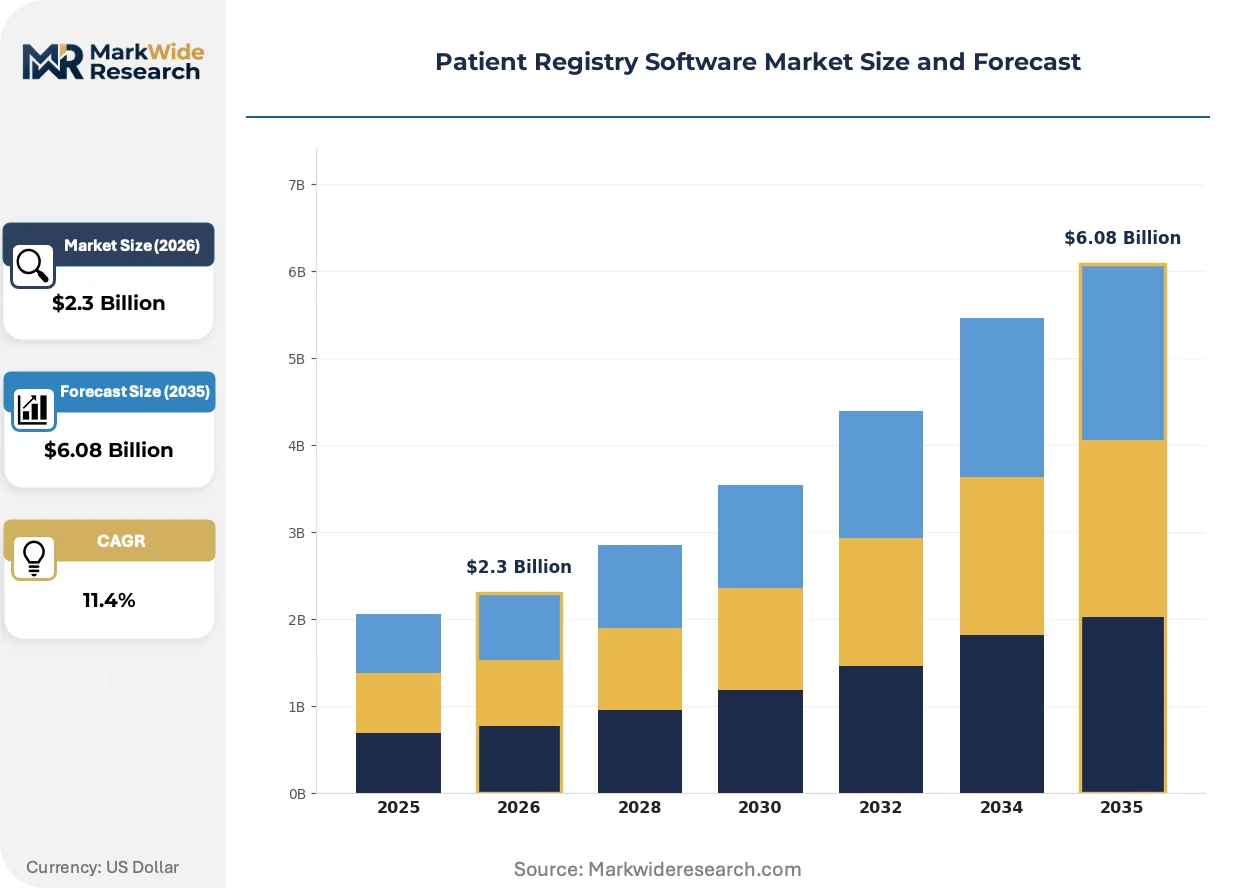
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $6.08 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
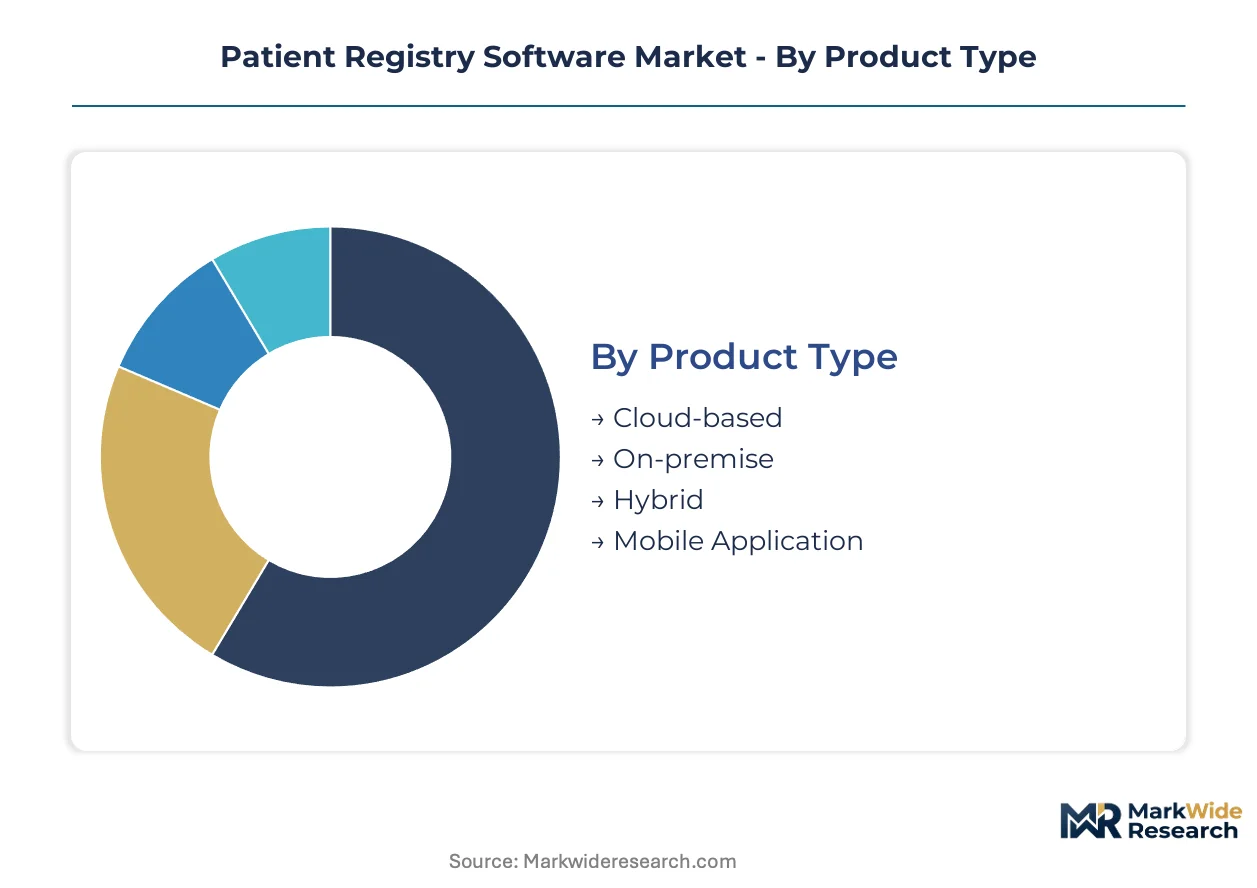
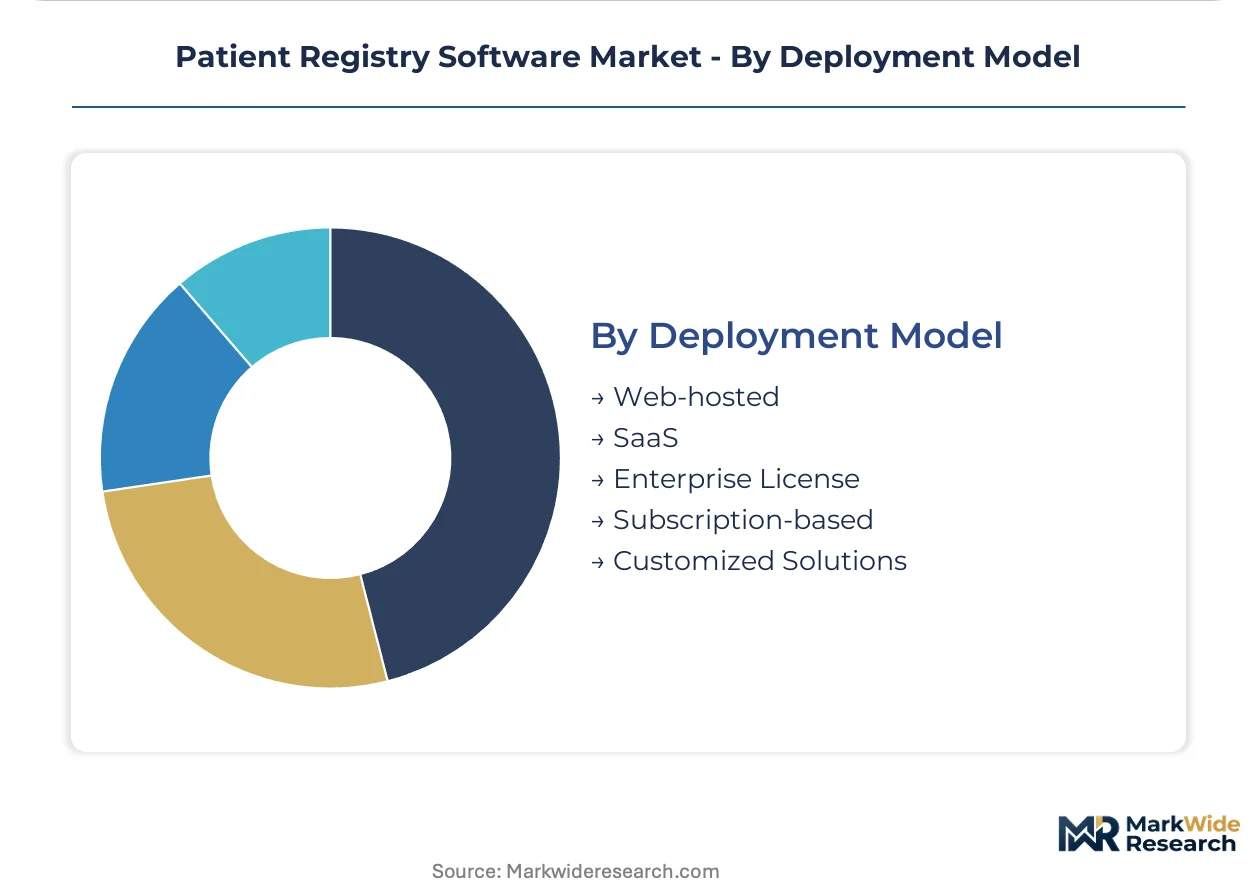
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile Application Application: Rare Disease Tracking, Cancer Monitoring, Chronic Condition Management, Post-market Surveillance, Epidemiological Studies End User: Pharmaceutical Companies, Clinical Research Organizations, Government Agencies, Academic Institutions, Patient Advocacy Groups Deployment Model: Web-hosted, SaaS, Enterprise License, Subscription-based, Customized Solutions |
| Companies Covered | Oracle, IQVIA, IBM, Health Catalyst, Veradigm, UnitedHealth Group, Conduent, Medical Information Technology, ImageTrend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Registry Software Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from passive data repositories to active intelligence platforms. This change is driven by technological advancements that enable more dynamic data analysis while adhering to increasingly strict global privacy and security mandates.
Containerization technology, such as Docker, provides a method for packaging software applications and their dependencies into isolated units. Life sciences organizations and academic research centers are adopting this for more flexible and scalable registry deployments. This approach is miniaturizing the traditional monolithic software architecture into discrete, manageable microservices that can be updated or scaled independently, accelerating development cycles.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for post-market surveillance and clinical evidence. The regulation compels device manufacturers to proactively collect and analyze real-world performance data throughout the product lifecycle. Consequently, the segment for post-market clinical follow-up (PMCF) registries is expanding, with vendors enhancing platforms to meet EMA reporting criteria and data collection mandates.
A notable shift in data access models is altering how research organizations collaborate. Federated learning frameworks are gaining traction, displacing traditional data-sharing agreements that required centralizing sensitive patient information. In this model, algorithms are sent to distributed data sources to be trained locally, with only aggregated, non-identifiable results being shared, mitigating privacy risks under regulations like GDPR.
Patient Registry Software Market Segmentation
Understanding the varied segments within the patient registry software market is crucial for vendors to tailor solutions and for end-users to identify platforms aligning with specific research and compliance needs. This segmentation reflects the diverse requirements of clinical research, regulatory mandates, and technological preferences across the healthcare ecosystem. Each category highlights distinct functional areas or deployment strategies that influence software design and adoption.
Product Type:
Regulatory differentiation significantly influences the development and adoption of patient registry software product types, particularly concerning data residency and control requirements.
- Cloud-based:These platforms host data and applications on remote servers, accessible via the internet, offering scalable infrastructure and reduced operational overhead. Pharmaceutical companies increasingly adopt cloud solutions for post-market surveillance due to their global accessibility and rapid deployment capabilities.
- Hybrid:Hybrid models combine elements of both on-premise and cloud deployments, allowing organizations to maintain sensitive data locally while leveraging cloud resources for scalability. This approach appeals to academic institutions managing diverse data sets under varying institutional IT policies.
- On-premise:On-premise software is installed and run on local servers within an organization's own data center, providing maximum control over data security and infrastructure. Government agencies often prefer on-premise solutions to meet stringent national data sovereignty regulations.
- Mobile Application:These applications are designed for use on smartphones and tablets, facilitating patient-reported outcome collection and remote data entry. Clinical research organizations utilize mobile apps for enhancing patient engagement in decentralized trials.
Cloud-based solutions handle the majority of throughput; Hybrid models are the fastest mover on share.
Application:
The specific application of patient registry software directly impacts its functional requirements, dictating features for data collection, analysis, and reporting.
- Rare Disease Tracking:These applications focus on collecting comprehensive longitudinal data for patient populations with extremely low prevalence, often supporting drug development for orphan indications. Biotechnology firms heavily invest in these specialized registries for patient identification and natural history studies.
- Post-market Surveillance:Software for post-market surveillance collects real-world evidence on approved medical products to monitor safety and effectiveness after commercial launch. Regulatory bodies like the FDA and EMA mandate such data collection from pharmaceutical companies.
- Cancer Monitoring:Registries dedicated to cancer monitoring track incidence, treatment outcomes, and survival rates for various oncological conditions. Academic institutions and research hospitals leverage these for epidemiological studies and clinical trial recruitment.
- Chronic Condition Management:These platforms assist in managing long-term diseases by collecting patient-reported data, clinical metrics, and treatment adherence information. Healthcare providers use these tools for population health management and care coordination.
- Epidemiological Studies:Software supporting epidemiological studies gathers population-level health data to investigate disease patterns, causes, and risk factors. Public health agencies rely on these systems for disease outbreak tracking and prevention strategies.
Rare Disease Tracking applications demand highly specialized functionalities; Post-market Surveillance is experiencing the steepest expansion trajectory.
End User:
Customer type determines the procurement patterns and the desired level of integration with existing enterprise systems for patient registry software.
- Pharmaceutical Companies:These organizations utilize patient registries extensively for clinical trial recruitment, post-market drug safety monitoring, and real-world evidence generation. Oracle and IQVIA provide integrated solutions to meet complex pharmaceutical research demands.
- Clinical Research Organizations:CROs deploy registry software to manage multi-site clinical studies, streamline data collection, and ensure regulatory compliance for their sponsor clients. These firms prioritize interoperability with electronic health record systems.
- Government Agencies:Public health bodies use registries for population health surveillance, disease control programs, and policy formulation. Compliance with national data privacy laws like HIPAA is a primary concern for these entities.
- Academic Institutions:Research universities and medical centers employ registries for investigator-initiated studies, rare disease research, and training future clinical data scientists. Flexibility and customization options are important for academic users.
- Patient Advocacy Groups:These groups establish registries to empower patient communities, facilitate research, and advocate for specific disease populations. Ease of data contribution and patient privacy are key considerations for advocacy groups.
Pharmaceutical Companies represent the largest customer base; Patient Advocacy Groups are increasingly influencing software design for patient-centric data models.
Deployment Model:
Operational flexibility and IT infrastructure capabilities drive the selection of different deployment models for patient registry software.
- SaaS:Software-as-a-Service models offer subscription-based access to fully managed applications hosted by the vendor, reducing client IT burden. This model is highly favored by pharmaceutical companies for its scalability and rapid deployment in global studies.
- Customized Solutions:These involve tailor-made software development or significant modifications to existing platforms to meet unique organizational workflows or complex research protocols. Large academic research centers often require customized solutions for specific longitudinal studies.
- Web-hosted:Web-hosted solutions are accessible through a web browser, with the software residing on a vendor's server, offering convenience without full SaaS management. Smaller clinical research organizations often opt for web-hosted options due to lower initial costs.
- Subscription-based:This model provides access to software licenses for a recurring fee, which can be applied to various deployment types including cloud or on-premise. Many vendors offer subscription pricing across their portfolio to align with operational budgets.
- Enterprise License:An enterprise license grants an organization the right to use software across multiple users or departments, typically for a fixed, perpetual fee. Large hospital networks often procure enterprise licenses for broad internal deployment.
SaaS deployment models dominate the market for their agility; Customized Solutions command premium pricing due to specialized development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's emphasis on real-world evidence for drug approvals significantly drives demand for patient registry software in the United States. This regulatory push encourages pharmaceutical companies to invest in robust platforms for post-market surveillance and clinical data collection. Consequently, North America remains a primary market for these specialized solutions.
United States
The United States market experiences strong demand from its vast pharmaceutical industry and numerous clinical research organizations. HIPAA compliance and FDA mandates for real-world evidence generation compel investment in sophisticated registry platforms. The Boston-Cambridge biotech hub actively utilizes these systems for advanced drug development and patient cohort management.
Germany
Germany exhibits substantial demand for patient registry software, particularly in chronic disease management and academic research. Strict GDPR regulations and EMA guidelines necessitate secure and compliant data management solutions. Bavaria's medical technology sector innovates with registry platforms to support post-market surveillance of medical devices.
Japan
Japan's aging population and increasing focus on rare disease research contribute to sustained demand for specialized registries. The PMDA's evolving requirements for post-market data collection influence software adoption among pharmaceutical firms. Tokyo's pharmaceutical companies are actively integrating these platforms for advanced clinical trial management.
India
India's expanding clinical trial landscape and diverse patient population fuel demand for cost-effective and scalable patient registry software. CDSCO guidelines for drug development and local data privacy norms shape platform requirements for data integrity. Bengaluru's IT and healthcare innovation cluster develops tailored solutions for large-scale epidemiological studies.
United Kingdom
The United Kingdom shows significant demand from its robust academic research institutions and the National Health Service's data integration efforts. UK GDPR and MHRA frameworks for real-world evidence drive adoption for post-market surveillance. London's vibrant health tech ecosystem fosters innovation in patient-centric data models and mobile applications.
Patient Registry Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the patient registry software market. The market exhibits a tiered structure, encompassing established enterprise software providers, specialized clinical data management firms, and innovative cloud-native startups. Strategic archetypes include large technology conglomerates leveraging existing infrastructure, niche clinical research solution providers with deep domain expertise, and agile startups focusing on specific functionalities. Dominant competitive moves involve strategic partnerships for enhancing interoperability and targeted acquisitions to expand application portfolios and geographic reach.
On the enterprise-scale vector, Oracle represents a major technology conglomerate, leveraging its robust database infrastructure to offer integrated solutions. IBM, another significant technology firm, occupies a position focused on advanced analytics and AI platforms, addressing complex data management needs. IQVIA, with its deep domain expertise in clinical trials and real-world evidence, exemplifies a specialized solution provider within the market. These entities collectively anchor different segments of the patient registry software landscape, showcasing diverse strategic approaches to product development and market penetration.
| Leading Market Players |
|---|
| Oracle |
| IQVIA |
| IBM |
| Health Catalyst |
| Veradigm |
| UnitedHealth Group |
| Conduent |
| Medical Information Technology |
| ImageTrend |
| Others |
Cost & Logistics Intelligence
Subscription-based contracts for patient registry software lock in both supply access and price visibility for end-users. This structure encourages long-term relationships between vendors and clients, particularly for complex, longitudinal data collection initiatives. The inherent service component of these platforms further intertwines pricing with ongoing support and compliance updates.
Pricing Analysis
Geographic disparities in pricing for patient registry software are pronounced, reflecting varying regulatory landscapes and market maturity. The dominant pricing model is subscription-based SaaS, offering tiered access based on features, data volume, and user count. Price differentiation stems from the level of customization required for specific research protocols and the vendor's certifications for compliance with mandates like HIPAA and GDPR. Pricing softness in the mid-tier segment reflects increasing competition from open-source alternatives. Academic institutions often exhibit the highest price sensitivity, while pharmaceutical companies prioritize functionality and compliance over cost.
Supply Chain Analysis
The lead times for deploying complex patient registry solutions often extend due to customization requirements and integration with existing IT infrastructure. Supply concentration for core development and cloud hosting centers in the United States, India, and Ireland. The supply chain relies heavily on cloud infrastructure services from major providers like AWS and Azure, alongside a critical dependency on specialized clinical data science talent. Cybersecurity threats represent a significant structural risk, demanding constant investment in robust security protocols. Distribution runs primarily through direct sales channels and cloud marketplaces, with some vendors utilizing strategic channel partners for localized support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The patient registry software market faces a critical capability gap in clinical informatics talent, which impacts both development and deployment. Strategic recommendations focus on leveraging technology to bridge this gap and address evolving regulatory demands.
For Market Incumbents: Shield core market share by deepening vertical integration into specialized data analytics and AI capabilities. This move helps counter the threat from agile, niche startups focusing on specific disease areas or data models. Invest in advanced interoperability features to maintain competitive advantage against emerging open-source solutions. Prioritize GxP compliance certifications as a lever to reinforce trust with pharmaceutical and government clients.
For New Entrants and Emerging Players: Differentiate on specialized domain expertise in underserved application areas, such as rare disease tracking or specific chronic conditions. The most penetrable segment for new players is academic research institutions, which often seek flexible, cost-effective solutions for investigator-initiated studies. A compelling go-to-market angle involves offering modular, cloud-native platforms that can integrate seamlessly with existing EHR systems while ensuring compliance with regional data privacy laws.
For Investors and Strategic Acquirers: Capital is best deployed toward platforms offering robust federated learning capabilities and strong compliance frameworks for GDPR and HIPAA. The long-term viability favors vendors that can demonstrate clear pathways to real-world evidence generation and predictive analytics. An ideal acquisition target archetype would be a mid-sized firm with proprietary AI algorithms for clinical data analysis or a strong presence in emerging markets. Watch for increased regulatory emphasis on RWE as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with EHRs | Seamless data exchange improves data quality and reduces manual effort for clinical research organizations. |
| Acquisition of Specialist AI Firm | Integrates advanced predictive analytics into registry platforms, offering high-value insights to pharmaceutical companies. |
| Strategic Partnership with Cloud Providers | Enhances scalability and security for global deployments, benefiting end-users like government agencies. |
| Product Launch: Federated Learning Module | Addresses data privacy concerns by enabling distributed data analysis without centralizing sensitive patient information. |
| Geographic Expansion into Southeast Asia | Taps into expanding clinical trial activities and growing demand for cost-effective solutions in emerging markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive understanding of the patient registry software market. Primary interviews with clinical data scientists, pharmaceutical R&D heads, regulatory compliance officers, and IT procurement managers provided qualitative insights. These findings were triangulated with secondary research from sources such as FDA filings, EMA submissions, ClinicalTrials.gov, and peer-reviewed academic journals, ensuring a robust bottom-up and top-down validation process.
The analysis window for this market extends over the projection horizon, focusing on key segmentation dimensions including product type, application, end user, deployment model, and the regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived by modeling historical trends and projecting future demand drivers. Real-world evidence mandates and the widespread adoption of interoperability standards like HL7 FHIR served as critical forecast inputs for market expansion.
Material uncertainties — evolving data privacy laws, rapid technological shifts — sit outside the modeled envelope of this report. Forecasts reflect assumptions documented through extensive research and expert consultations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Secure Messaging in Healthcare Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market