
 Global Telepharmacy Market | 2026-2036
Global Telepharmacy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telepharmacy Market Foresight
Premium telepharmacy platforms that integrate real-time clinical decision support is decoupling from basic remote dispensing services that merely automate pill counting. CVS Health leverages its nationwide retail footprint to sustain last-mile medication delivery networks. Teladoc Health anchors its position through virtual care integration that bundles pharmacist consultations with primary care encounters. McKesson Corporation differentiates via upstream control over wholesale drug distribution that feeds directly into automated dispensing infrastructure.
Telepharmacy encompasses the remote provision of pharmaceutical care through digital communication channels, requiring HIPAA-compliant encryption, real-time video resolution standards, and integration with electronic health record systems to enable prescription verification and patient counseling without physical co-location. Its primary commercial purpose is to extend pharmacist reach into medically underserved areas while reducing medication errors through centralized expert oversight. Remote dispensing systems currently lead in installed base across community pharmacies, though cloud-based platforms represent the fastest-growing technology segment as health systems consolidate vendor relationships. Patient counseling services command stronger margins than prescription verification due to reimbursement advantages under value-based care contracts, while long-term care facilities emerge as the most concentrated application segment for medication therapy management programs.
FDA oversight of 503B compounding facilities and HIPAA security rule enforcement by the Office for Civil Rights jointly shape platform architecture requirements and liability frameworks for telepharmacy operators. India's CDSCO and the EU's EMA are developing parallel guidance on cross-border prescription validation that will determine market access for multinational platform providers. Stakeholders must monitor evolving state-level scope-of-practice laws that determine whether pharmacy technicians can perform remote dispensing under off-site pharmacist supervision.
Market Dynamics
Centralized prescription verification platforms are compressing the geographic radius of pharmacist coverage, forcing health systems to consolidate vendor relationships around cloud-native architectures that can scale across state licensing boundaries.
Growth Catalysts
- CDSCO centralized review framework:India's tier-2 cities now permit remote pharmacist oversight for community pharmacies, unlocking demand in previously underserved urban clusters.
- Remote dispensing automation:Health systems deploy robotic dispensing cabinets with integrated video counseling to extend specialist pharmacist reach into rural counties.
- Value-based care reimbursement:Medication therapy management programs earn enhanced payments under Medicare Advantage contracts, accelerating platform investment by long-term care operators.
Market Restraints
- State-level scope-of-practice fragmentation:Inconsistent technician supervision rules across US jurisdictions force platform operators to maintain jurisdiction-specific compliance modules.
- HIPAA security rule enforcement:Office for Civil Rights audit protocols require end-to-end encryption upgrades that extend procurement cycles for mid-sized pharmacy chains.
- Cross-border prescription validation gaps:Absence of mutual recognition agreements between FDA and EMA prevents seamless platform deployment across North American and European facilities.
Strategic Opportunities
- Long-term care facility concentration:Skilled nursing operators in the US seek bundled telepharmacy and remote patient monitoring services to reduce hospital readmission penalties.
- EMA parallel guidance development:Emerging frameworks for cross-border prescription validation will enable first-mover platform providers to establish pan-European operations.
- AI-powered clinical decision support:Integration of real-time drug interaction engines with EHR systems creates premium service tiers distinct from basic verification offerings.
Industry Challenges
- Pharmacist licensing reciprocity complexity:Multi-state credentialing requirements delay platform rollout timelines and inflate compliance staffing costs.
- Legacy EHR integration friction:Proprietary data formats in dominant hospital information systems necessitate costly custom interface development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telepharmacy Market |
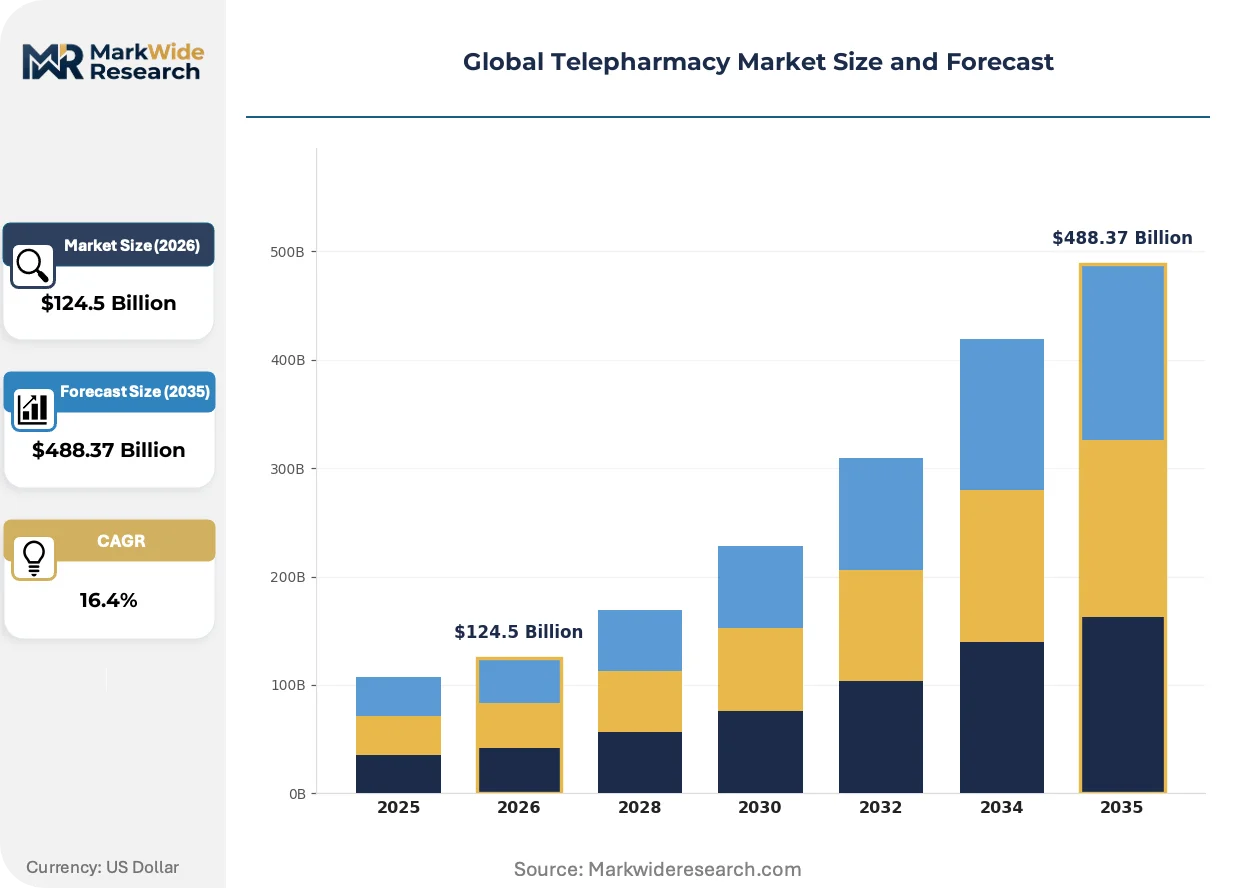
| Market Size in 2026 | $124.5 Billion |
| Market Size in 2035 | $488.37 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Dispensing, Medication Therapy Management, Patient Counseling, Prescription Verification, Clinical Consultation Application: Community Pharmacies, Long-term Care Facilities, Hospitals, Correctional Facilities, Outpatient Clinics Technology: Video Conferencing, Electronic Prescription Systems, Automated Dispensing Cabinets, Mobile Health Apps, Cloud-based Platforms End User: Pharmacists, Healthcare Providers, Patients, Pharmacy Technicians, Insurance Providers |
| Companies Covered | Teladoc Health, CVS Health, McKesson Corporation, Cardinal Health, PipelineRx, TelePharm, Medication Review, CarepathRx, Walgreens Boots Alliance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telepharmacy Market Shifts & Advancements
Telepharmacy infrastructure is pivoting from standalone dispensing automation toward integrated clinical workflows that embed pharmacist expertise directly into care team coordination.
Cloud-native medication therapy management platforms is converging with real-time biometric monitoring feeds from connected inhalers and insulin pens. Chronic disease management programs at US health systems adopt these converged stacks to trigger pharmacist interventions before adverse events. The resulting compression of emergency department utilization is reshaping contract structures with Medicare Advantage plans.
EMA guidance on centralized compounding oversight is mandating video-verified sterile preparation for 503B facilities across EU member states. This industrial consequence forces outsourcing compounders to deploy telepharmacy stations in each production suite. German hospital pharmacies lead response adoption, integrating these verification feeds directly into their pharmacy information management systems.
Buying committees at US rural health systems now unbundle telepharmacy procurement from EHR vendor bundles, selecting best-of-breed platforms with superior clinical decision support engines. This channel disintermediation displaces legacy hardware-centric dispensing contracts. The pattern is most visible in the Mountain West region where critical access hospitals prioritize pharmacist retention over single-vendor convenience.
Global Telepharmacy Market Segmentation
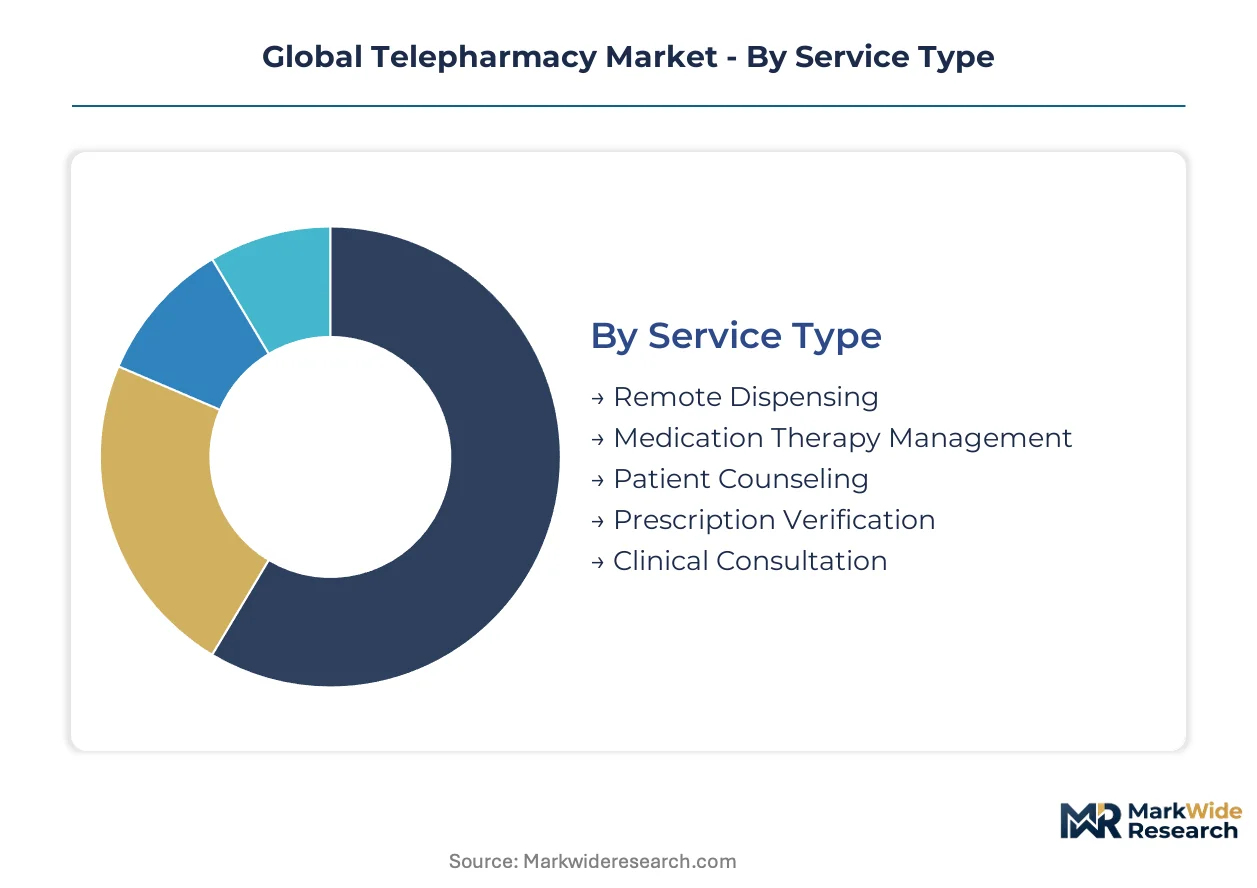
Telepharmacy procurement decisions pivot on service maturity, with buyers weighing regulatory compliance depth against integration complexity. Segmentation reveals divergent margin structures across service tiers and technology architectures.
Service Type:
Buyers prioritize reimbursement pathways when selecting service tiers, with value-based contracts favoring clinical intensity over transactional efficiency.
- Remote Dispensing:Robotic dispensing cabinets with integrated video verification enable centralized oversight of medication distribution across multiple sites. US rural health systems deploy these systems to address pharmacist shortages in counties with populations below 50,000, though FDA 503B compliance requirements extend procurement cycles.
- Medication Therapy Management:Comprehensive medication reviews with documented outcomes support Medicare Advantage quality metrics and readmission reduction programs. Long-term care operators in the US concentrate demand here, as bundled payments reward pharmacist-led chronic disease optimization.
- Patient Counseling:HIPAA-compliant video sessions deliver adherence coaching and side-effect management directly to patients.
- Prescription Verification:Remote pharmacist review of dispensing accuracy through high-resolution imaging and barcode cross-checks.
- Clinical Consultation:Specialist pharmacist input on complex therapeutic decisions, including oncology and infectious disease protocols.
Volume sits with Remote Dispensing; growth tilts toward Medication Therapy Management.
Application:
Facility type dictates platform configuration, with acute care settings demanding EHR integration that ambulatory sites can bypass.
- Long-term Care Facilities:Skilled nursing and assisted living operators seek bundled telepharmacy services to reduce hospitalization penalties under Medicare Advantage contracts. India's tier-2 cities show emerging concentration as CDSCO centralized review frameworks enable remote oversight of community pharmacy networks serving these facilities.
- Community Pharmacies:Independent and chain retail locations deploy telepharmacy to extend pharmacist hours without full-time staffing. US Mountain West critical access hospitals unbundle procurement from EHR vendors to prioritize clinical decision support quality.
- Hospitals:Inpatient settings require 24/7 pharmacist coverage for therapeutic drug monitoring and formulary management.
- Correctional Facilities:Secure environments with controlled medication access and limited on-site clinical staff.
- Outpatient Clinics:Federally qualified health centers and specialty clinics integrating pharmacist consultations into primary care workflows.
Community Pharmacies dominate installed base; Long-term Care Facilities show steepest expansion trajectory.
Technology:
Architecture choices reflect IT infrastructure maturity, with cloud-native platforms displacing on-premise hardware in consolidated health systems.
- Cloud-based Platforms:Scalable SaaS architectures enable multi-state deployment without jurisdiction-specific server installations. German hospital pharmacies lead European adoption, integrating EMA-mandated video verification feeds directly into pharmacy information management systems.
- Automated Dispensing Cabinets:Robotic units with biometric access control and real-time inventory tracking anchor physical infrastructure.
- Video Conferencing:HIPAA-compliant encrypted channels with resolution standards sufficient for pill identification.
- Electronic Prescription Systems:Direct integration with prescriber workflows to eliminate transcription errors.
- Mobile Health Apps:Patient-facing interfaces for medication reminders, refill requests, and asynchronous pharmacist messaging.
Automated Dispensing Cabinets hold current volume; Cloud-based Platforms are gaining share fastest.
End User:
Workflow design varies sharply by credential level, with technician-supervised models requiring distinct compliance architectures.
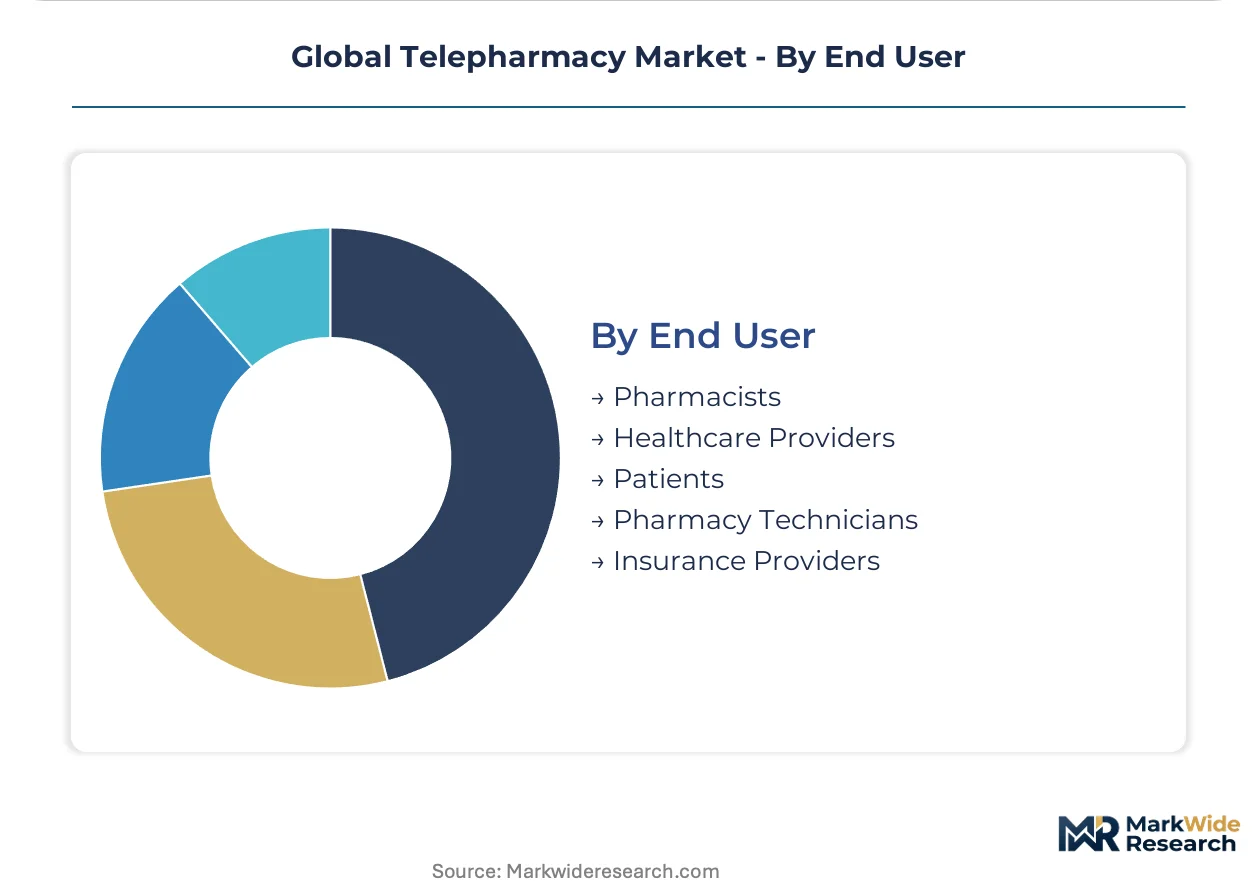
- Pharmacists:Licensed practitioners performing remote verification, counseling, and clinical consultation across state boundaries. Multi-state credentialing complexity inflates compliance staffing costs and delays platform rollout timelines.
- Pharmacy Technicians:Personnel performing dispensing preparation under off-site pharmacist supervision where state scope-of-practice laws permit. US jurisdiction fragmentation forces platform operators to maintain modular compliance systems.
- Healthcare Providers:Physicians and nurses accessing pharmacist expertise for therapeutic decision support.
- Patients:Direct recipients of counseling and adherence services through consumer-facing interfaces.
- Insurance Providers:Payers contracting for medication therapy management outcomes and cost containment.
Pharmacists anchor current utilization; Pharmacy Technicians show strongest growth potential as supervision frameworks standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors telepharmacy platform development through CDSCO's centralized review framework, which permits remote pharmacist oversight for community pharmacies serving tier-2 urban clusters across India.
United States
Critical access hospitals in the Mountain West deploy robotic dispensing cabinets with integrated video counseling to address pharmacist shortages in counties below 50,000 population. FDA 503B compounding oversight and HIPAA security rule enforcement by the Office for Civil Rights shape platform architecture requirements. Rural health systems in Montana and Wyoming unbundle procurement from EHR vendors to prioritize clinical decision support quality.
Germany
Hospital pharmacies in Bavaria and Baden-Württemberg integrate EMA-mandated video verification feeds into pharmacy information management systems for sterile compounding oversight. German regulators are developing parallel guidance on cross-border prescription validation that will determine market access for multinational platform providers. Berlin-based health systems lead European adoption of cloud-native medication therapy management platforms.
India
Tier-2 cities including Pune, Jaipur, and Lucknow concentrate demand as CDSCO regulations now permit centralized prescription review for community pharmacies. The country's national pharmaceutical regulator is expanding remote oversight frameworks to address medically underserved urban clusters. Hyderabad and Bengaluru anchor platform development through health technology clusters serving domestic and export markets.
United Kingdom
London and Manchester health systems pilot integrated clinical workflows that embed pharmacist expertise directly into care team coordination. The country's national pharmaceutical regulator is aligning with EMA frameworks on centralized compounding oversight. NHS trusts in the Southeast prioritize cloud-native architectures that scale across regional licensing boundaries.
Australia
Sydney and Melbourne health systems adopt converged telepharmacy and remote patient monitoring stacks for chronic disease management programs. The country's national pharmaceutical regulator is developing guidance on multi-state pharmacist credentialing reciprocity. Queensland rural health networks deploy video counseling platforms to extend specialist pharmacist reach into remote communities.
Global Telepharmacy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across clinical decision support integration depth. The vendor base organizes around three strategic archetypes: retail pharmacy chains leveraging physical footprint for last-mile delivery, wholesale distributors controlling upstream drug supply, and virtual care platforms bundling pharmacist consultations with primary care. Consolidation pressures favor cloud-native architectures that scale across state licensing boundaries. Dominant competitive moves include strategic partnerships with EHR vendors and portfolio diversification into medication therapy management.
Within the integrated health services tier, Teladoc Health exemplifies virtual care bundling while CVS Health occupies a position anchored to nationwide retail infrastructure. McKesson Corporation represents wholesale distribution control feeding automated dispensing infrastructure. These three entities illustrate how vertical positioning upstream or downstream from the pharmacy counter determines platform economics.
| Leading Market Players |
|---|
| Teladoc Health |
| CVS Health |
| McKesson Corporation |
| Cardinal Health |
| PipelineRx |
| TelePharm |
| Medication Review |
| CarepathRx |
| Walgreens Boots Alliance |
| Others |
Supply & Pricing Matrix
Clinical decision support depth separates premium telepharmacy platforms from commodity remote dispensing services, with that bifurcation driving divergent margin structures and supply chain configurations. Cloud-native architectures with integrated EHR decision engines command subscription premiums from US health systems, while basic dispensing automation faces price erosion from hardware-centric vendors in India's tier-2 markets.
Pricing Analysis
Value-based pricing anchored to medication therapy management outcomes dominates US long-term care contracts, with Medicare Advantage quality metrics determining reimbursement tiers. Price differentiation rests on clinical decision support integration depth and HIPAA certification grade, with cloud-native SaaS platforms capturing premiums over on-premise hardware. Cost compression in basic remote dispensing intensifies as Indian CDSCO frameworks standardize centralized review capabilities. Community pharmacy chains show highest price sensitivity, while integrated health systems prioritize clinical outcomes over per-seat licensing costs.
Supply Chain Analysis
Direct-to-health-system channels handle enterprise telepharmacy deployments, with cloud infrastructure providers and EHR integration specialists feeding platform development. Geographic supply concentration centers on the United States, Germany, and India for software development, with hardware components sourced from China and Taiwan for automated dispensing cabinets. Raw material dependencies include encryption chipsets, high-resolution imaging sensors, and HIPAA-compliant server infrastructure. Single-source vulnerability in EHR integration middleware creates supply chain risk. Distribution runs through health technology distributors and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
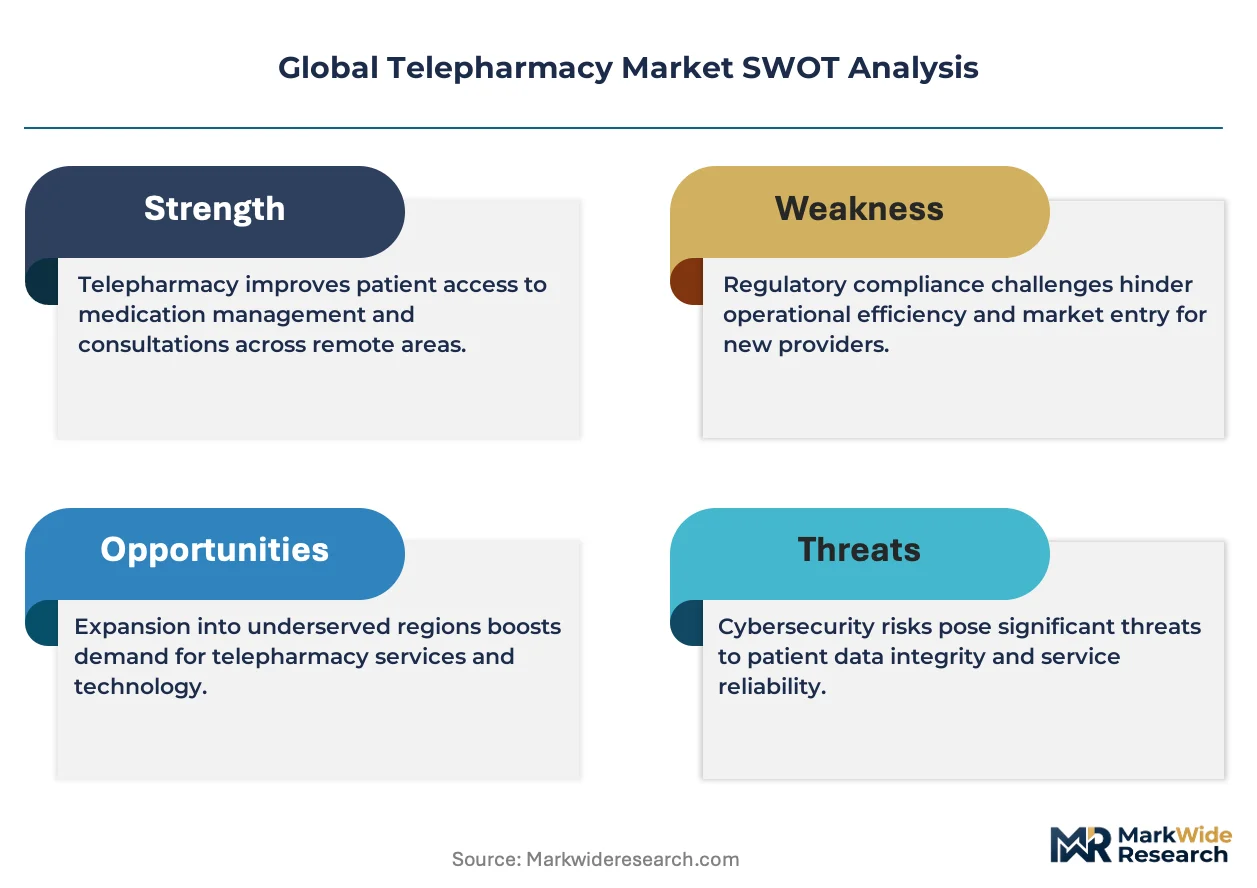
Telepharmacy market entry costs are structurally inflated by HIPAA security rule enforcement and FDA 503B compounding oversight, creating compliance moats that protect incumbent positions while filtering out undercapitalized challengers.
For Market Incumbents: Deploy multi-state licensing reciprocity frameworks to compress rollout timelines across US jurisdictions. Consolidate vendor relationships around cloud-native architectures that scale across state boundaries, defending against emerging pure-play SaaS entrants with superior clinical decision support engines. Capture long-term care facility concentration through bundled medication therapy management and remote patient monitoring services. For New Entrants and Emerging Players: Begin with India's tier-2 cities where CDSCO centralized review frameworks lower regulatory barriers relative to US HIPAA complexity. Target community pharmacy networks in underserved urban clusters with lightweight prescription verification platforms that bypass EHR integration friction. Pursue white-label partnerships with existing health technology distributors to bypass direct enterprise sales infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native platform providers given EMA parallel guidance development on cross-border prescription validation. Long-term viability favors vendors with demonstrated HIPAA audit resilience and established multi-state pharmacist credentialing operations. Monitor state-level scope-of-practice standardization as the inflection signal for technician-supervised model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with EHR Systems | Epic and Cerner interoperability unlocks enterprise health system procurement committees. |
| Multi-State Pharmacist Licensing Expansion | Reciprocity agreements with Montana and Wyoming rural health networks accelerate deployment velocity. |
| AI Clinical Decision Support Development | Real-time drug interaction engines differentiate premium tiers from basic verification services. |
| Long-Term Care Facility Partnership | Medicare Advantage bundled contracts reward medication therapy management outcomes with enhanced payments. |
| EMA Cross-Border Validation Compliance | German hospital pharmacy integration positions first-movers for pan-European platform expansion. |
Research Methodology
Document review covered FDA 503B guidance documents, CDSCO regulatory circulars, and EMA centralized oversight frameworks, complemented by interviews with telepharmacy platform executives, hospital pharmacy directors, long-term care operators, and health system procurement managers. Secondary validation drew from CMS Medicare Advantage contract data, HIPAA Office for Civil Rights audit protocols, and health technology vendor SEC filings. Bottom-up deployment estimates across US critical access hospitals were triangulated against top-down market sizing from cloud infrastructure spending disclosures.
Segment-level revenue projections across the analysis window were generated through modeled adoption curves for remote dispensing, medication therapy management, and patient counseling services. Segmentation dimensions included service type maturity, technology architecture, application facility type, and end-user credential level. CAGRs were derived from regression analysis of historical health technology procurement cycles and regulatory enablement timelines. Forecast inputs incorporated state-level scope-of-practice legislative tracking and CDSCO framework expansion schedules.
Underlying measurement precision varies by segment; cloud-based platform deployments carry tighter precision than legacy hardware installations due to greater vendor disclosure transparency. Forecasts reflect assumptions regarding HIPAA enforcement intensity and EMA guidance finalization timelines. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty in cross-border prescription validation and potential state-level technician supervision rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Radiation Dose Optimisation Software Market