
 Healthcare Technology Management Market | 2026-2036
Healthcare Technology Management Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Technology Management Market Outlook
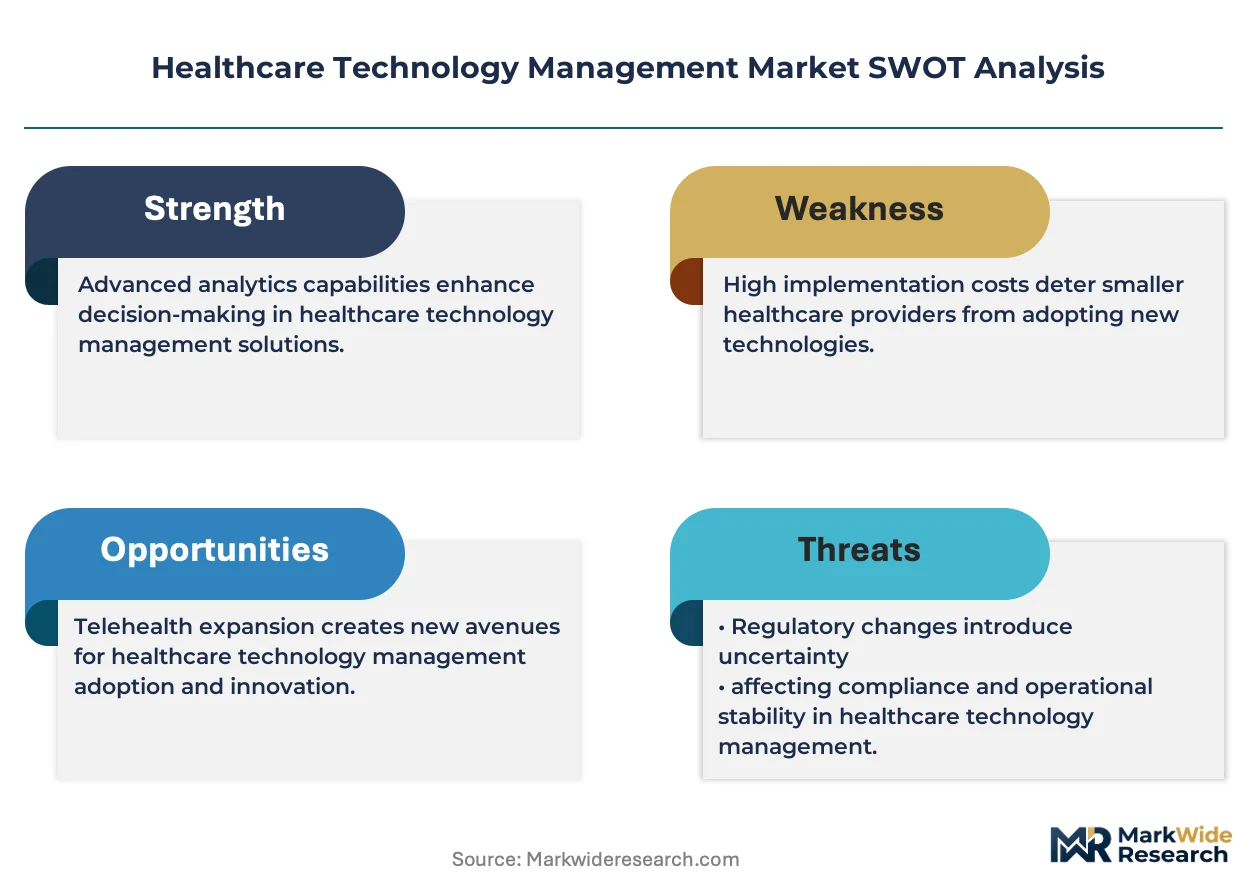
Cloud-native infrastructure is consolidating around legacy on-premise hospital IT architectures, reducing total cost of ownership for multi-site health systems. GE Healthcare leverages its Edison platform to anchor predictive analytics across imaging modalities. Philips Healthcare sustains competitive positioning through integrated service contracts that bundle hardware with remote monitoring. Siemens Healthineers differentiates via in-house production of digital twin diagnostics for CT and MRI fleet optimization.
Healthcare technology management encompasses the lifecycle governance of clinical assets, from procurement and deployment through maintenance, cybersecurity patching, and end-of-life disposition, typically governed by ISO 13485 quality protocols and IEC 62304 software safety standards. Its primary purpose is ensuring continuous clinical availability while controlling capital expenditure and regulatory compliance burden. Maintenance services commands the largest margin pool among service types due to recurring revenue structures and technical certification barriers. Artificial Intelligence within the technology dimension represents the fastest-expanding capability, though Cloud Computing retains dominant deployment share among mid-sized hospital networks.
The FDA enforces cybersecurity guidance under Section 524B of the FD&C Act, compelling manufacturers to submit software bill of materials and vulnerability management plans prior to market authorization. EMA's MDR transition continues to reshape conformity assessment pathways for legacy devices, elevating documentation burdens on European Economic Area distributors. Stakeholders must monitor evolving FDA premarket submission requirements for AI-enabled devices while calibrating service organization investments against shifting notified body capacity constraints.
Market Dynamics
Hospital systems are consolidating technology management under single-vendor enterprise platforms, compressing procurement cycles and elevating cybersecurity compliance as a non-negotiable selection criterion alongside clinical uptime guarantees.
Growth Catalysts
- ISO 13485 quality protocols:Medical device manufacturers across Germany and the United States are accelerating third-party certification to maintain EU MDR market access, expanding audit and remediation service demand.
- Predictive maintenance algorithms:Imaging fleet operators in university hospital networks are deploying AI-enabled failure prediction to reduce unplanned downtime below 2% annual targets.
- Remote monitoring infrastructure:Cloud-native telemetry platforms are penetrating mid-sized health systems in India and Brazil, enabling centralized oversight of distributed device portfolios.
Market Restraints
- Specialized biomedical engineering talent:Certification requirements for MRI and CT service engineers create 18-24 month hiring pipelines, constraining independent service organization expansion.
- Legacy device cybersecurity patching:Manufacturers face liability exposure under FDA Section 524B for end-of-life systems lacking software bill of materials documentation.
- Notified body capacity bottlenecks:EU MDR conformity assessment backlogs are delaying technology management contract renewals for European Economic Area distributors.
Strategic Opportunities
- Enterprise asset management standardization:German university hospital networks are consolidating fragmented CMMS platforms into unified deployments spanning 50+ site installations.
- Digital twin diagnostics convergence:CT and MRI fleet optimization is integrating physics-based simulation with real-time operational data, creating premium service tier differentiation.
- Outcome-based contracting models:North American integrated delivery networks are piloting availability-guarantee structures that shift vendor compensation from hourly labor to clinical uptime metrics.
Industry Challenges
- IEC 62304 software safety certification:In-house development of connected maintenance platforms requires documentation rigor that stretches 12-18 month product release timelines.
- Interoperability with proprietary OEM protocols:Independent service organizations face technical barriers accessing diagnostic data from locked imaging system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Technology Management Market |
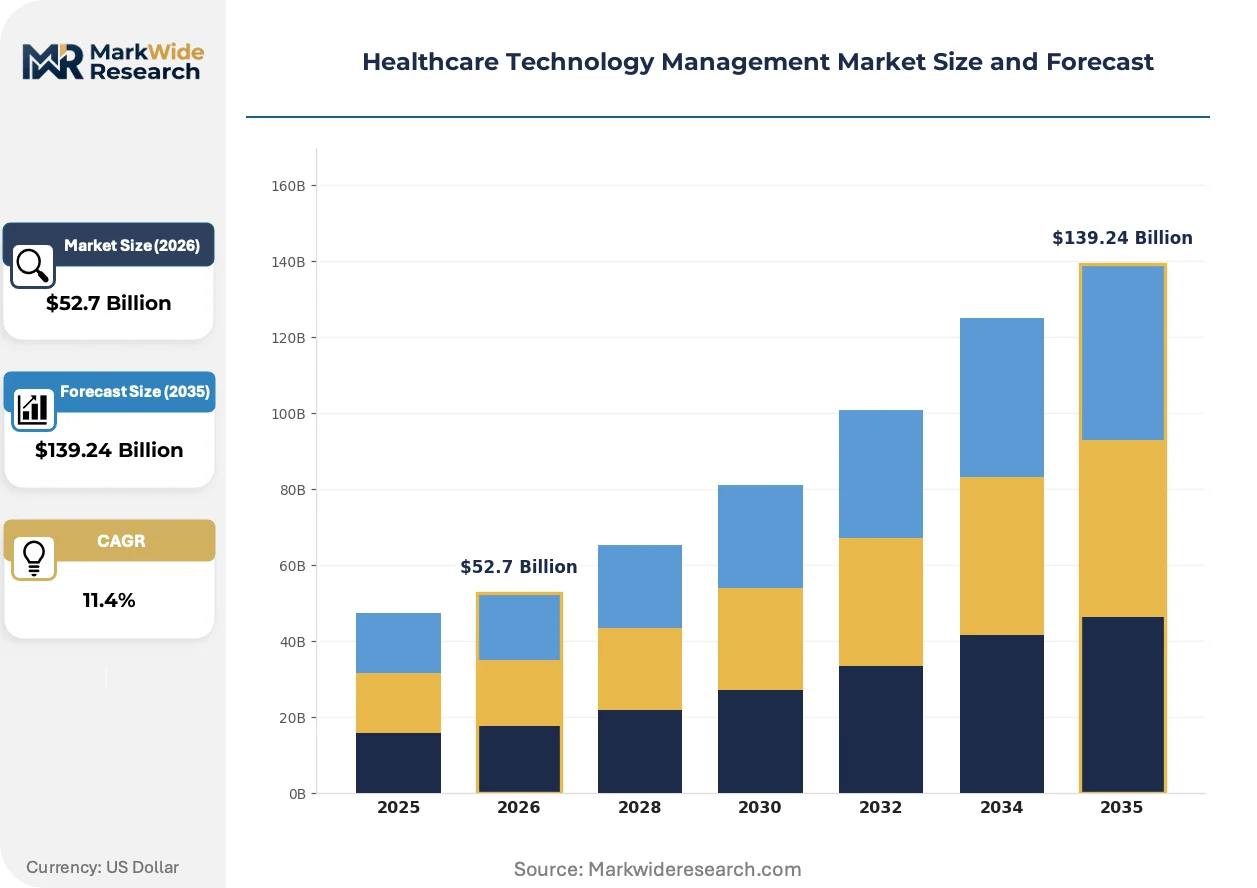
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Imaging Systems, Wearable Technology, Monitoring Systems End User: Hospitals, Clinics, Laboratories, Home Care Providers Technology: Cloud Computing, IoT, Artificial Intelligence, Data Analytics Service Type: Consulting Services, Maintenance Services, Implementation Services, Training Services |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Medtronic, Nuvolo, TRIMEDX, ServiceNow, Oracle, Sodexo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Technology Management Market Strategic Shifts
Artificial intelligence is embedding into every layer of clinical asset lifecycle management, from procurement optimization algorithms through autonomous predictive maintenance, while regulatory frameworks harden cybersecurity and quality documentation requirements.
Edge computing architectures are decentralizing data processing for imaging fleet monitoring, enabling real-time anomaly detection without cloud dependency. Rural hospital networks in the United States and Canada are adopting these distributed systems to overcome bandwidth constraints. The shift is decentralizing service delivery models, allowing regional technicians to execute complex diagnostics without specialist dispatch from central hubs.
EU MDR Article 120 transition timelines are forcing legacy device manufacturers to reclassify service activities as economic operator functions subject to notified body oversight. European distributors are restructuring quality management systems to accommodate post-market surveillance documentation burdens. High-risk imaging modalities face the steepest compliance cost escalation, prompting service contract repricing across the European Economic Area.
Integrated delivery networks are unbundling hardware procurement from multi-year service agreements, compressing vendor switching cycles from seven-year lock-ins to three-year competitive rebids. Group purchasing organizations are aggregating technology management demand across 15-20 hospital systems to extract volume-based pricing concessions. This purchasing pattern shift is most pronounced in Texas and California health systems, where consolidation has created 10+ facility networks with standardized device fleets.
Healthcare Technology Management Market Segmentation
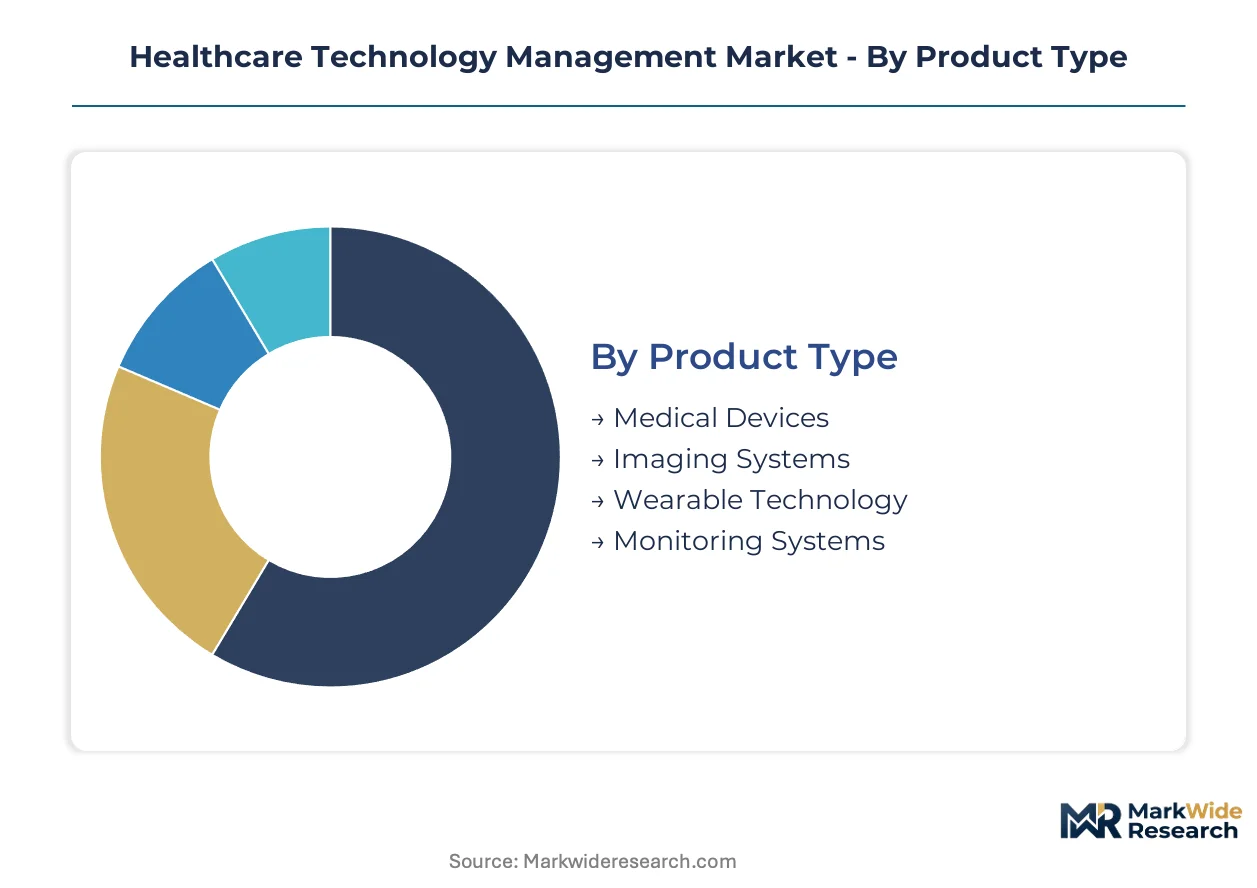
Healthcare technology management vendors configure product portfolios around four intersecting dimensions. Procurement patterns diverge sharply between integrated health systems seeking enterprise platforms and independent facilities prioritizing point solutions.
Product Type:
Standalone systems dominate capital budgets while embedded modules penetrate retrofit installations.
- Medical Devices:Lifecycle governance spans infusion pumps, ventilators, and surgical equipment requiring ISO 13485-compliant maintenance protocols. German university hospital networks are consolidating procurement for anesthesia workstations and patient monitors under single-vendor enterprise contracts.
- Imaging Systems:CT, MRI, and ultrasound fleets command premium service margins due to specialized field engineering requirements and uptime-critical clinical workflows. Predictive maintenance algorithms are penetrating university hospital networks in Germany and the United States to reduce unplanned downtime below 2% annual targets.
- Wearable Technology:Continuous glucose monitors and cardiac event recorders require cloud-native telemetry infrastructure for real-time data ingestion.
- Monitoring Systems:Central station architectures and bedside devices integrate with electronic health record platforms through HL7 FHIR interfaces.
Imaging Systems leads volumes today; Wearable Technology is gaining share fastest.
End User:
Facility scale determines service contract structure and cybersecurity compliance burden.
- Hospitals:Multi-site health systems deploy enterprise asset management platforms spanning 50+ facilities with centralized procurement authority. Integrated delivery networks in Texas and California are unbundling hardware procurement from service agreements, compressing vendor switching cycles to three-year competitive rebids.
- Clinics:Ambulatory surgery centers and specialty practices prioritize remote monitoring over on-site biomedical engineering staff.
- Laboratories:In-vitro diagnostic equipment requires IEC 62304 software safety certification for connected maintenance platforms.
- Home Care Providers:Distributed patient monitoring creates telemetry infrastructure demands across rural geographies with bandwidth constraints.
Hospitals anchor revenue concentration today; Home Care Providers show the steepest expansion trajectory.
Technology:
Deployment architecture choices shape total cost of ownership and regulatory compliance pathways.
- Cloud Computing:Native SaaS platforms reduce infrastructure capital expenditure for mid-sized hospital networks. Cloud-native telemetry is penetrating health systems in India and Brazil, enabling centralized oversight of distributed device portfolios.
- IoT:Sensor networks and connected device gateways generate real-time operational data streams for predictive algorithms.
- Artificial Intelligence:Machine learning models embed into failure prediction, procurement optimization, and autonomous maintenance scheduling. AI-enabled diagnostics are integrating with physics-based simulation for CT and MRI fleet optimization.
- Data Analytics:Business intelligence platforms aggregate asset performance metrics across multi-vendor device fleets.
Cloud Computing retains dominant deployment share; Artificial Intelligence is climbing the fastest.
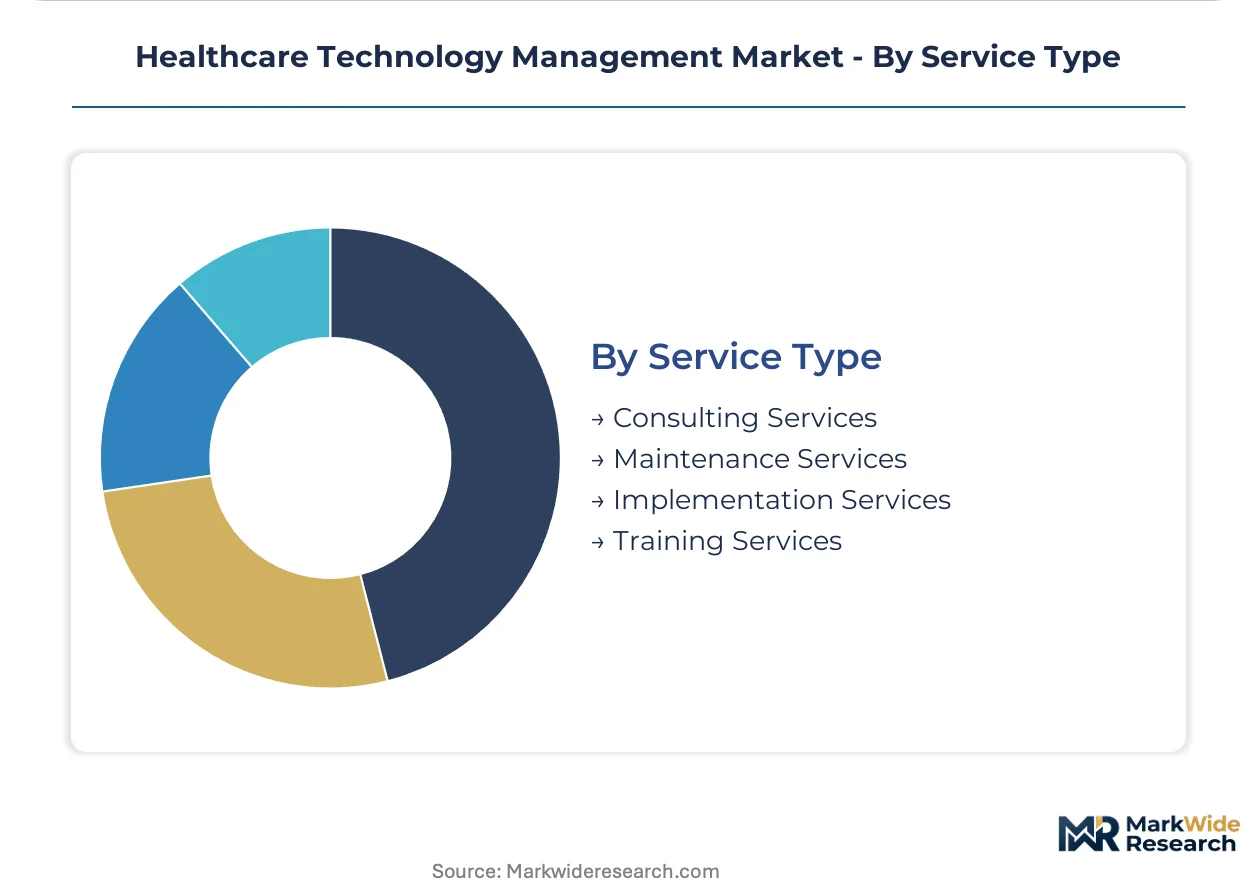
Service Type:
Margin structures vary with technical certification barriers and revenue recurrence predictability.
- Maintenance Services:Recurring revenue contracts for preventive and corrective maintenance command the largest margin pool due to technical certification requirements and clinical uptime guarantees. Outcome-based availability-guarantee structures are shifting vendor compensation from hourly labor to clinical uptime metrics in North American integrated delivery networks.
- Consulting Services:Enterprise asset management standardization and regulatory remediation engagements address EU MDR transition timelines and FDA Section 524B cybersecurity documentation requirements.
- Implementation Services:System deployment and integration with legacy hospital IT architectures require 12-18 month project timelines.
- Training Services:Biomedical engineering certification programs address 18-24 month hiring pipelines for MRI and CT service engineers.
Maintenance Services leads margins today; Consulting Services is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital networks are standardizing enterprise asset management platforms across multi-site installations, driving concentration in predictive maintenance procurement and regulatory compliance services.
United States
Integrated delivery networks in Texas and California are unbundling hardware procurement from seven-year service lock-ins, compressing vendor switching cycles to three-year competitive rebids. FDA Section 524B cybersecurity guidance compels manufacturers to submit software bill of materials prior to market authorization. The Greater Boston cluster anchors digital twin diagnostics development for CT and MRI fleet optimization.
Germany
University hospital networks in Baden-Württemberg and Bavaria are consolidating fragmented CMMS platforms into unified deployments spanning 50+ facilities. EU MDR Article 120 transition timelines force legacy device manufacturers to reclassify service activities as economic operator functions. The Rhine-Ruhr metropolitan region concentrates independent service organization consolidation amid notified body capacity bottlenecks.
India
Cloud-native telemetry platforms are penetrating mid-sized health systems in Maharashtra and Karnataka, enabling centralized oversight of distributed device portfolios. CDSCO medical device rules impose registration requirements on imaging equipment importers and service providers. The Hyderabad-Telangana corridor hosts remote monitoring infrastructure deployment for rural hospital networks with bandwidth constraints.
Brazil
ANVISA medical device regulations are elevating documentation burdens for technology management contract renewals across São Paulo and Rio de Janeiro health systems. Outcome-based availability-guarantee structures are shifting vendor compensation from hourly labor to clinical uptime metrics. The São Paulo metropolitan area concentrates predictive maintenance algorithm adoption for imaging fleet operators.
United Kingdom
NHS trust consolidation is driving enterprise platform standardization across London and Southeast England hospital networks. MHRA post-market surveillance requirements reshape conformity assessment pathways for legacy imaging devices. The Cambridge-Oxford-London triangle anchors AI-enabled failure prediction development for reducing unplanned downtime below 2% annual targets.
Healthcare Technology Management Market Competitive Environment
Global majors compete with regional champions across predictive analytics platforms and integrated service contract structures. The vendor base organizes around three tiers: full-stack imaging OEMs with captive service arms, independent service organizations with specialized engineering certifications, and cloud-native software platforms with multi-vendor interoperability. Competitive positioning hardens through M&A consolidation of independent service organizations and strategic partnerships between software vendors and regional biomedical engineering networks.
Within the full-stack OEM tier, GE Healthcare, Philips Healthcare, and Siemens Healthineers exemplify integrated service contract structures that bundle hardware with remote monitoring capabilities. These entities occupy positions where predictive analytics platforms anchor enterprise-wide technology management deployments. Independent service organizations such as TRIMEDX and Nuvolo sit within a specialized tier focused on multi-vendor CMMS standardization and cybersecurity compliance remediation. Cloud-native entrants including ServiceNow represent software-centric archetypes penetrating mid-sized health systems through SaaS-based asset management platforms.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Medtronic |
| Nuvolo |
| TRIMEDX |
| ServiceNow |
| Oracle |
| Sodexo |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up independent service organizations dominate mid-market maintenance contracts, compressing pricing discipline through standardized labor rates while amplifying procurement leverage across multi-site hospital networks.
Pricing Analysis
Input-cost pass-through from certified biomedical engineer wages and OEM spare parts tariffs shapes contract pricing across maintenance tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified predictive maintenance from corrective-only coverage and basic break-fix arrangements. Price differentiation hinges on certification level and geographic delivery cost, with rural hospital networks absorbing 15-25% premiums for specialist dispatch. Pricing pressure stems from group purchasing organization aggregation squeezing vendor margins. Ambulatory surgery centers exhibit highest price sensitivity; university hospital networks with captive engineering staff show least.
Supply Chain Analysis
Specialized imaging components rest on concentrated production in Germany, Japan, and the United States for CT tubes, MRI magnets, and ultrasound transducers. Raw material dependencies include rare earth elements for MRI superconducting coils, high-purity silicon for detector arrays, and specialty alloys for radiation shielding. Single-source vulnerability pervades proprietary OEM diagnostic software and encrypted service tool access. Distribution runs through authorized dealer networks and direct OEM service arms, with independent service organizations penetrating via aftermarket parts brokers and reverse-engineered interoperability modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in healthcare technology management rests on cloud-native platform standardization reducing field engineering intensity, alongside outcome-based contracting shifting revenue toward premium availability guarantees.
For Market Incumbents: Anchor predictive analytics capabilities through Edison-platform-class infrastructure investments that lock hospital systems into multi-modality data integration. Defend against cloud-native software entrants by bundling remote monitoring with ISO 13485-certified field engineering networks. Prioritize backward integration into digital twin diagnostics development to differentiate CT and MRI fleet optimization services from commodity maintenance. For New Entrants and Emerging Players: SaaS-based asset management platforms offer the lowest-friction entry vector for mid-sized hospital networks seeking CMMS consolidation without seven-year OEM lock-ins. Target Indian and Brazilian health systems where cloud-native telemetry penetration remains below North American saturation levels. Lead with HL7 FHIR interoperability and multi-vendor dashboard consolidation rather than competing head-to-head on imaging modality expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among independent service organizations with specialized MRI and CT engineering certifications but undigitized back-office infrastructure. Long-term viability favors targets with recurring maintenance revenue above 70% of total and demonstrated EU MDR compliance remediation capabilities. Watch FDA Section 524B enforcement intensity as the inflection signal for cybersecurity documentation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | GE Healthcare's Edison deployment anchors AI-enabled failure prediction across imaging fleets. |
| EU MDR Compliance Remediation Service | Notified body capacity bottlenecks force European distributors toward third-party documentation support. |
| Digital Twin Diagnostics Development | Siemens Healthineers integrates physics-based simulation with real-time CT and MRI operational data. |
| Cloud-Native CMMS Partnership | ServiceNow penetrates mid-sized health systems through SaaS-based multi-vendor asset management. |
| Outcome-Based Contracting Pilot | Texas integrated delivery networks shift vendor compensation from hourly labor to clinical uptime metrics. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific emerging markets, with primary inputs from each region validated against secondary documentation. Primary interviews incorporated hospital purchasing committee directors, biomedical engineering managers at university hospital networks, GPO contracts managers, independent service organization executives, and regulatory affairs leads at imaging OEMs. Secondary sources triangulated FDA 510(k) filings, EMA MDR transition guidance documents, CMS Medicare cost report data, hospital procurement databases, and ISO 13485 certification registries. Bottom-up service contract value aggregation cross-checked against top-down market sizing from capital equipment installation bases.
Rate-of-change decomposition across the analysis window separates volume effects from price-mix shifts and technology substitution patterns. Segmentation modeling incorporated product type, end-user facility scale, deployment architecture, and service contract structure dimensions. CAGR derivation weighted historical maintenance revenue recurrence rates against projected cloud-native platform adoption curves and regulatory compliance service demand spikes. Forecast inputs specifically tracked imaging fleet age distributions and EU MDR Article 120 transition timelines.
The model assumes a particular technology adoption path; alternative pathways for edge computing architectures in rural bandwidth-constrained networks would alter the outlook. Forecasts reflect assumptions regarding FDA cybersecurity enforcement continuity and notified body capacity normalization. Regulatory timeline delays, OEM proprietary protocol hardening, or acute biomedical engineering labor shortages represent revision triggers. A small set of named triggers—FDA Section 524B audit intensity, German university hospital network consolidation pace, and Indian cloud infrastructure investment cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Patient Registry Software Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
United States Pharmacy Management System Market