
 Vital Signs Monitoring Devices Market | 2026-2036
Vital Signs Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vital Signs Monitoring Devices Market Intelligence
The ISO 13485 quality management standard is reorganizing the competitive landscape by setting stringent requirements for market entry. GE Healthcare leverages its extensive hospital network to secure large-volume contracts for integrated monitoring solutions. Masimo differentiates through its specialization in advanced non-invasive monitoring technologies, particularly in pulse oximetry. Medtronic sustains its market position through significant R&D investment in next-generation wearable and remote monitoring devices.
Vital signs monitoring devices are medical instruments designed to measure, display, and record a patient's core physiological parameters. These devices, such as pulse oximeters that measure blood oxygen saturation (SpO2), are critical for clinical decision-making in acute and chronic care settings. Within the product mix, pulse oximeters and blood pressure monitors constitute the largest segments due to their routine use in hospitals. The technology segment featuring wearable sensors and wireless monitoring systems represents the fastest-growing category, driven by the expansion of home care.
Regulatory approvals from bodies like the US FDA and China's NMPA are mandatory for market access. The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements, raising compliance costs. These frameworks directly influence device design, labeling, and data security protocols. Stakeholder success will depend on navigating divergent regional approval pathways while managing cybersecurity risks inherent in connected devices.
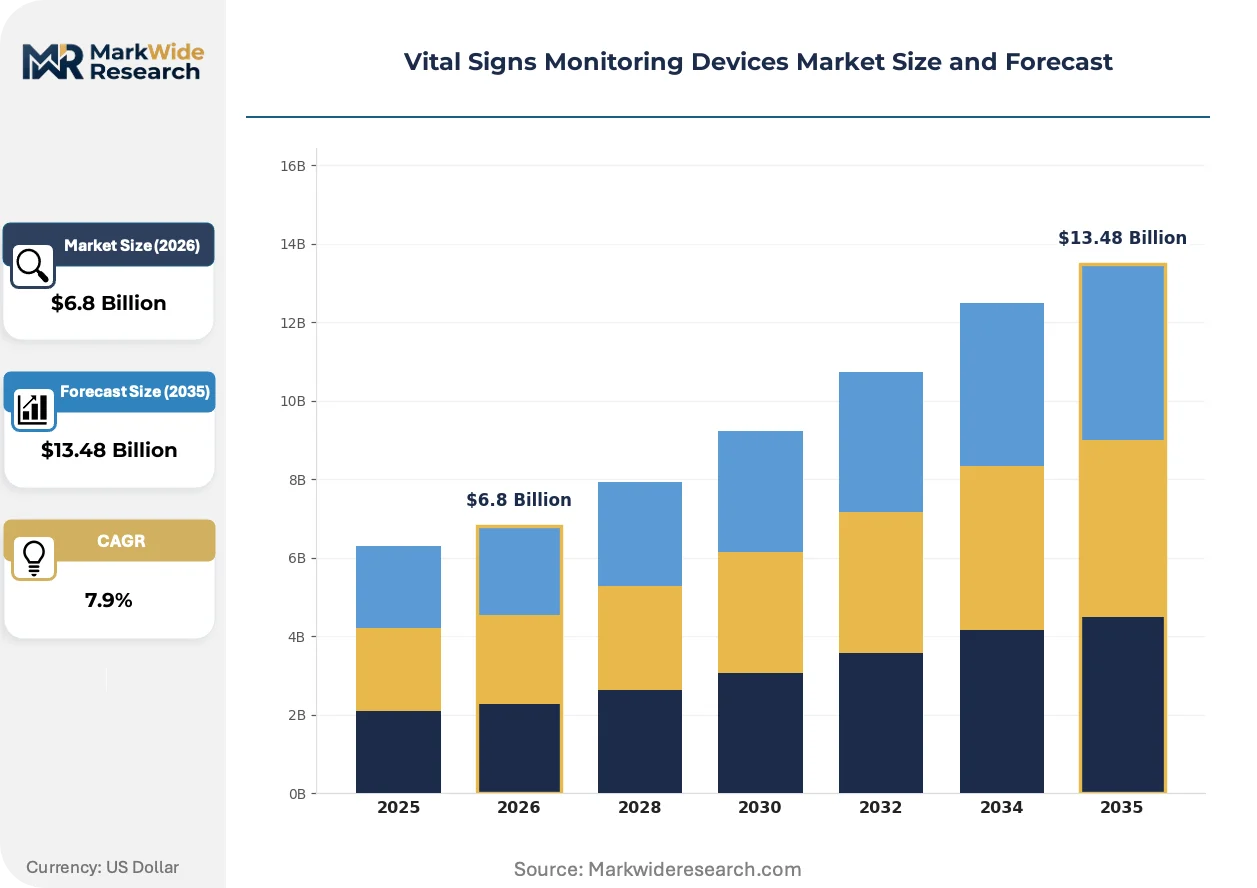
Market Dynamics
The central structural force shaping the market is the decentralization of care from hospitals to home settings. This shift, driven by remote patient monitoring technologies for chronic disease management, creates a fundamental tension between the need for clinical-grade accuracy and consumer-friendly device usability.
Growth Catalysts
- Chronic Disease Prevalence:The rising global incidence of conditions like hypertension and COPD, particularly in aging populations, necessitates continuous monitoring solutions that operate effectively outside of traditional clinical environments.
- Government Digital Health Initiatives:Investment in digital health infrastructure, such as that seen in China, and the promotion of telehealth services create substantial and sustained demand for connected monitoring devices.
- Wearable Sensor Miniaturization:Advances in semiconductor and sensor manufacturing allow for smaller, more power-efficient, and accurate components, expanding device applications from purely clinical use to the consumer wellness sector.
Market Restraints
- Data Security and Privacy Concerns:Transmitting sensitive patient data exposes devices to cybersecurity threats, increasing compliance burdens under regulations like HIPAA in the United States and GDPR in Europe.
- Stringent Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes rigorous clinical evidence and post-market surveillance requirements, increasing development costs and time-to-market for manufacturers.
- Reimbursement Framework Ambiguity:Inconsistent or absent reimbursement policies for remote patient monitoring services and devices in many national healthcare systems limit large-scale adoption by providers and patients.
Strategic Opportunities
- AI-Powered Predictive Analytics:Integrating artificial intelligence algorithms with continuous monitoring data can enable predictive alerts for patient deterioration, creating a new value proposition beyond simple physiological measurement.
- Expansion in Underserved Markets:Significant growth potential exists in Southeast Asian and Latin American countries, where healthcare infrastructure is developing rapidly and mobile connectivity is widespread.
- Integration with Electronic Health Records:Developing seamless interoperability between monitoring devices and hospital EHR systems offers a pathway to becoming an embedded partner in core clinical workflows, increasing customer stickiness.
Industry Challenges
- Interoperability with Legacy Systems:Integrating new wireless monitoring platforms with existing, often proprietary, hospital IT infrastructure presents significant technical and logistical challenges for healthcare providers seeking a unified data view.
- Cybersecurity Talent Scarcity:Device manufacturers face a shortage of specialized cybersecurity engineers required to design, test, and maintain secure connected medical devices against sophisticated and evolving threats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vital Signs Monitoring Devices Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Pressure Monitors, Pulse Oximeters, Thermometers, Respiratory Rate Monitors, Cardiac Monitors Technology: Wearable Sensors, Wireless Monitoring Systems, Portable Devices, Telemetry, Non-Invasive Monitors Application: Home Care, Emergency Response, Sports Science, Remote Patient Monitoring, Outpatient Diagnostics End User: Hospitals, Ambulatory Surgical Centers, Long-Term Care Facilities, Diagnostic Laboratories, Clinics |
| Companies Covered | Koninklijke Philips N.V., Medtronic, GE Healthcare, Masimo, Nihon Kohden Corporation, Mindray Medical International Limited, Omron Healthcare, Nonin Medical Inc., Contec Medical Systems Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vital Signs Monitoring Devices Market Strategic Shifts & Innovations
The convergence of consumer electronics design principles with medical-grade diagnostic requirements is creating new product categories and business models. This evolution prioritizes user experience and data integration alongside clinical accuracy, altering device development and market entry strategies.
Continuous glucose monitoring sensors, originally developed for diabetes management, provide real-time metabolic data through minimally invasive means. Adoption is now expanding beyond diabetic patients to include athletes and wellness-focused consumers seeking to optimize metabolic health. This trend is bifurcating the market into a regulated clinical segment focused on disease management and a consumer wellness segment focused on performance optimization.
Regulatory frameworks like the US FDA's Digital Health Software Precertification Program signal a shift towards streamlined pathways for software-based medical devices. This approach evaluates the developer's organizational excellence and quality management processes, not just the final product, potentially accelerating innovation cycles. Software as a Medical Device (SaMD) developers are most affected, prompting investment in robust quality systems to align with the new paradigm.
A transition from capital expenditure purchases to subscription-based models for monitoring services is gaining traction with healthcare providers. This disrupts the traditional model of one-time device sales by hospitals, with third-party remote patient monitoring (RPM) service companies emerging as a key channel. The shift is most prominent in the United States home care market, supported by established reimbursement codes for RPM services.
Vital Signs Monitoring Devices Market Segmentation
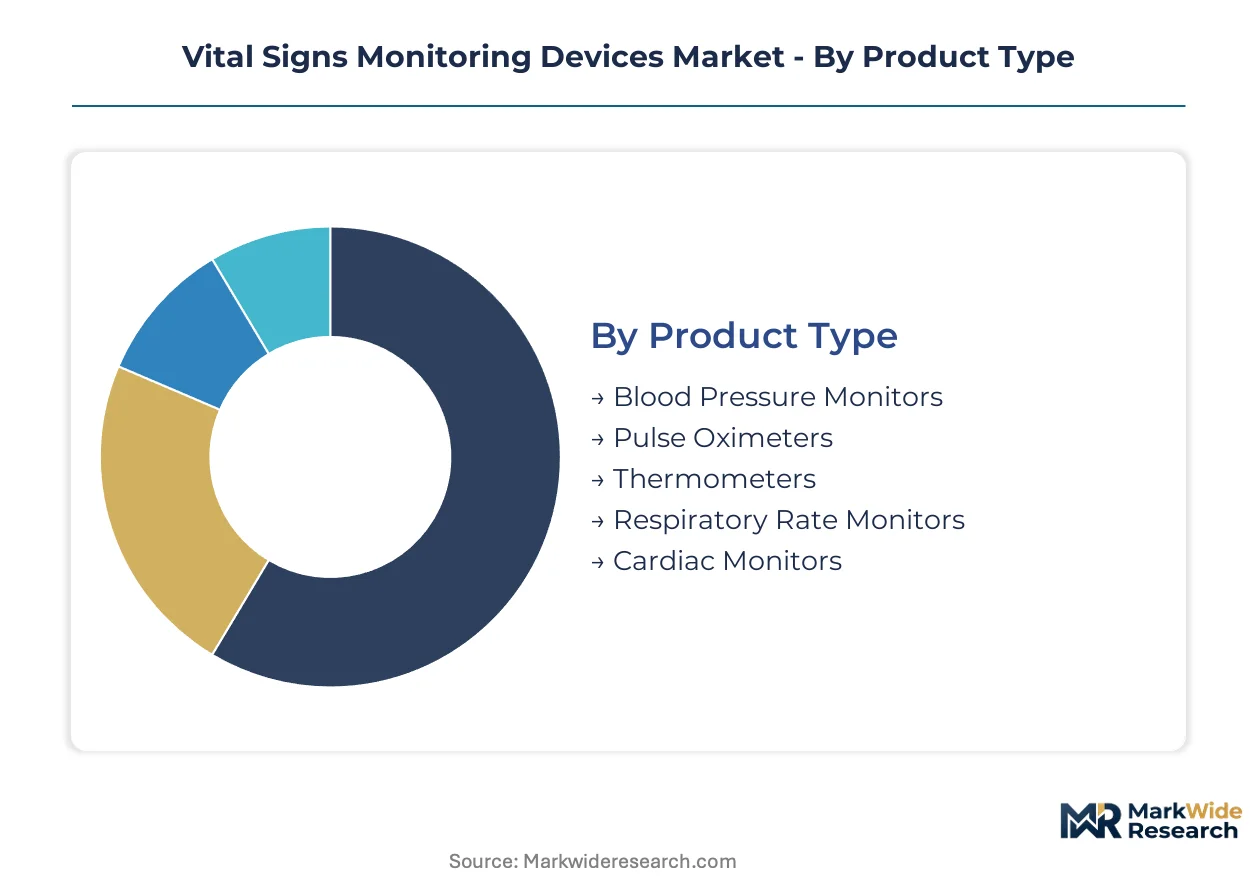
Segmentation provides a granular understanding of the vital signs monitoring devices market, revealing distinct customer needs and technological preferences. This analysis highlights how regulatory frameworks, application demands, and end-user requirements shape product development and market dynamics across various categories.
Product Type:
Regulatory bodies like the US FDA and Europe's MDR categorize vital signs monitoring devices based on their intended use and risk profile, influencing market entry and compliance burdens across different product types.
- Pulse Oximeters:These devices measure blood oxygen saturation (SpO2) and pulse rate using non-invasive photoplethysmography. Demand concentrates in hospitals and home care settings, driven by chronic respiratory conditions and remote patient monitoring initiatives.
- Blood Pressure Monitors:Devices measure systolic and diastolic blood pressure, utilizing oscillometric or auscultatory methods. Widespread adoption in primary care and home environments is propelled by the rising prevalence of hypertension.
- Thermometers:Devices accurately measure body temperature, ranging from basic oral units to advanced infrared forehead scanners.
- Respiratory Rate Monitors:These instruments quantify breaths per minute, often integrated into multi-parameter patient monitors for critical care.
- Cardiac Monitors:Devices track heart activity, including ECG, providing continuous data for arrhythmia detection and cardiac health assessment.
Blood Pressure Monitors handle the majority of throughput; Pulse Oximeters are the fastest mover on share.
Technology:
The technological advancements within vital signs monitoring devices directly shape their application across diverse healthcare environments, from clinical settings to personal wellness.
- Wearable Sensors:Miniaturized devices integrate directly onto the body, continuously collecting physiological data through optical or electrical means. Expansion in home care and sports science applications is driven by advances in semiconductor manufacturing and user convenience.
- Wireless Monitoring Systems:These platforms enable real-time data transmission from patient devices to central hubs or cloud services via Bluetooth or Wi-Fi. Demand in remote patient monitoring and long-term care facilities accelerates due to the decentralization of healthcare services.
- Portable Devices:Handheld or easily transportable units offer flexibility for on-site assessments in emergency response and outpatient clinics.
- Telemetry:Systems transmit vital signs data over distance, commonly used in hospital settings for continuous patient observation.
- Non-Invasive Monitors:Devices measure physiological parameters without penetrating the skin, ensuring patient comfort and reducing infection risks.
These technologies are enabling a significant shift towards patient-centric and decentralized care models.
Application:
Different applications for vital signs monitoring devices cater to distinct customer needs, ranging from individual patient management to large-scale public health initiatives.
- Home Care:Monitoring performed in a patient's residence, enabling continuous health tracking outside of clinical environments. Demand is concentrated in aging populations managing chronic diseases, supported by remote patient monitoring reimbursement codes in the US.
- Remote Patient Monitoring:Systems facilitate the collection of health data from patients in one location and electronic transmission to providers in another. This application sees significant growth in chronic disease management, reducing hospital readmissions and improving patient outcomes.
- Emergency Response:Devices provide immediate vital signs assessment for patients in pre-hospital and acute emergency settings.
- Outpatient Diagnostics:Clinical facilities use these monitors for routine check-ups, specialized tests, and follow-up care outside inpatient settings.
- Sports Science:Athletes and fitness enthusiasts use these devices for performance optimization and physiological recovery monitoring.
The evolution of these applications underscores the market's trajectory towards proactive and preventive healthcare delivery.
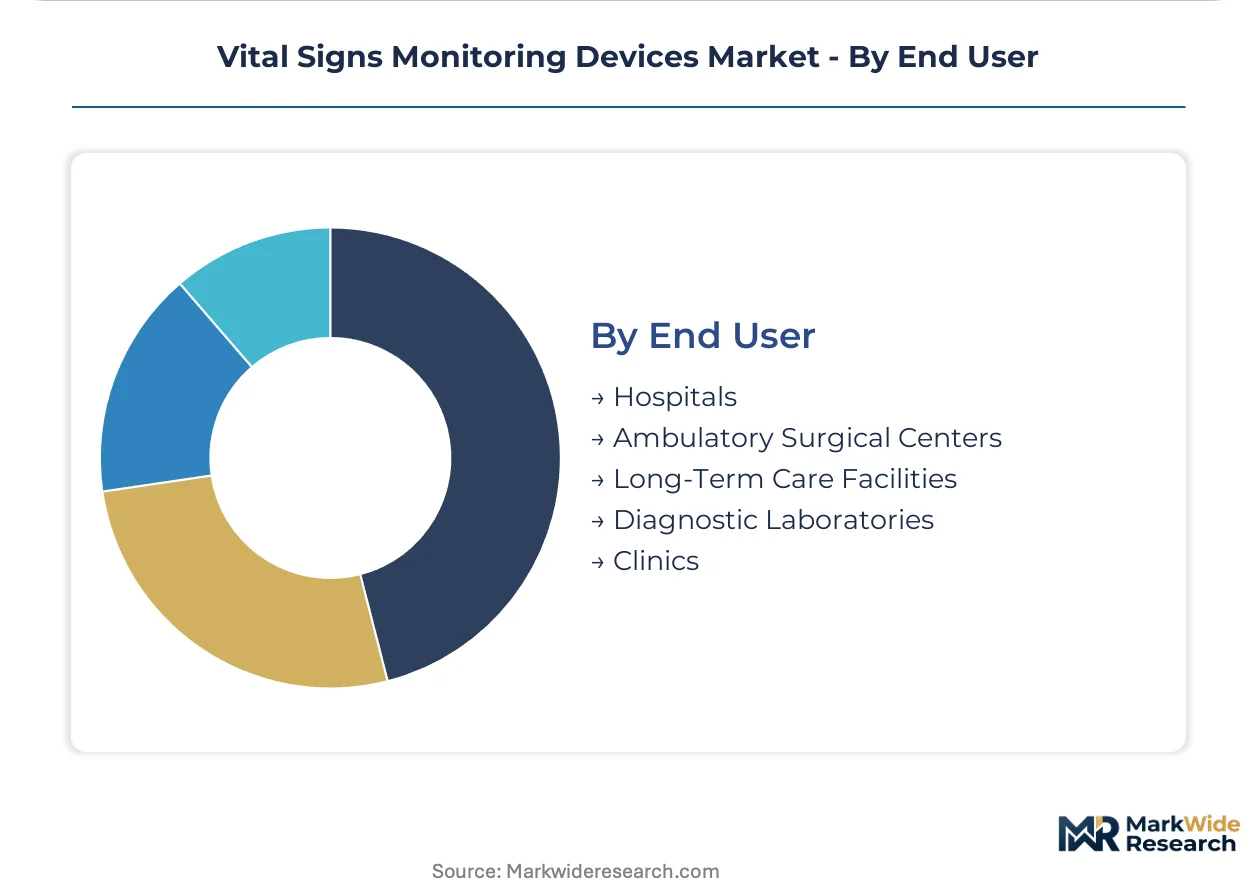
End User:
The varying scale of patient volume and care complexity across different end-user segments directly impacts the demand for specific vital signs monitoring device configurations.
- Hospitals:Large healthcare institutions require comprehensive multi-parameter monitors for acute care, operating rooms, and intensive care units. Procurement focuses on integrated solutions and large-volume contracts, often leveraging existing network relationships for acquisition.
- Clinics:Outpatient facilities, including physician offices and specialized centers, utilize devices for routine examinations and minor procedures. Demand concentrates on user-friendly, portable devices that support efficient patient throughput and diagnostic accuracy.
- Long-Term Care Facilities:These centers require continuous monitoring solutions for elderly residents and patients with chronic conditions.
- Ambulatory Surgical Centers:Facilities performing same-day surgical procedures need reliable vital signs monitors for pre-operative, intra-operative, and post-operative care.
- Diagnostic Laboratories:These specialized labs use vital signs data as part of broader diagnostic panels, often for research or complex case analysis.
Each end-user segment presents unique procurement challenges and opportunities for device manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitals and clinics globally represent the primary buyer archetypes for vital signs monitoring devices. However, the decentralization of care is shifting procurement towards home care and remote patient monitoring services. This transition necessitates devices balancing clinical accuracy with user-friendly designs.
United States
Demand for vital signs monitoring devices in the United States stems from chronic disease management and established remote patient monitoring reimbursement codes. The US FDA's regulatory framework and HIPAA privacy rules significantly influence device design and market entry. Biotech hubs like Boston and San Francisco drive innovation in wearable sensors and connected health solutions.
China
China's demand for vital signs monitors is concentrated in its rapidly expanding digital health infrastructure and government-backed telehealth initiatives. The National Medical Products Administration (NMPA) sets mandatory standards for device approval and market access. Major manufacturing centers like Shenzhen are pivotal for producing cost-effective, high-volume monitoring equipment.
Germany
German healthcare providers seek advanced vital signs monitoring solutions for an aging population and high-quality acute care settings. The European Union's Medical Device Regulation (MDR) imposes stringent clinical evidence and post-market surveillance requirements. Medical technology clusters in Bavaria and Baden-Württemberg foster innovation in integrated monitoring systems.
India
India's vital signs monitoring market expands due to increasing healthcare access and a rising prevalence of non-communicable diseases. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, ensuring product quality and safety for local distribution. Technology centers in Bengaluru and Hyderabad are developing localized, affordable monitoring solutions for diverse patient needs.
Japan
Japan's demand for vital signs monitoring devices reflects its super-aging society and strong emphasis on preventive health and home care. The Pharmaceuticals and Medical Devices Agency (PMDA) governs device approvals, maintaining high standards for medical technology. Research and development efforts in Tokyo and Osaka focus on miniaturized, high-precision wearable sensors.
Vital Signs Monitoring Devices Market Key Industry Players
Player mix skews toward established medical device conglomerates with significant market presence and specialized technology firms. The market structure exhibits a tiered consolidation, with large players dominating core hospital segments and nimbler innovators capturing emerging decentralized care opportunities. Strategic archetypes include diversified healthcare technology providers, niche monitoring specialists, and regional manufacturers focusing on cost-effectiveness and local market needs. Dominant competitive moves involve significant R&D investment in next-generation devices and strategic partnerships for integrated solutions, alongside M&A activities to expand technology portfolios.
Among established medical device manufacturers, Medtronic occupies a position as a diversified global healthcare technology company, reflecting extensive R&D capabilities. Masimo, an Irvine, California-based corporation, exemplifies a specialist archetype, deeply focused on advanced non-invasive monitoring technologies. Mindray Medical International Limited, a China-based Co. Ltd., represents a significant international player, providing a broad portfolio of medical devices across various global markets. These entities anchor different segments, from high-end clinical solutions to broader accessible monitoring platforms.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Medtronic |
| GE Healthcare |
| Masimo |
| Nihon Kohden Corporation |
| Mindray Medical International Limited |
| Omron Healthcare |
| Nonin Medical Inc. |
| Contec Medical Systems Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Large-volume contracts for integrated monitoring solutions lock in both supply access and price visibility for major healthcare providers. This contract stability allows manufacturers to plan production and manage component sourcing effectively.
Pricing Analysis
Cost-plus pricing, often indexed to semiconductor and specialized sensor costs, influences vital signs monitoring device prices. A hybrid model combining transactional sales for individual units with subscription-based services for remote monitoring platforms dominates the market. Regulatory certification levels and integrated solution bundling are primary price differentiation drivers. Pricing pressure is intensifying due to stringent regulatory compliance costs, particularly under the European Union's MDR. Home care consumers exhibit higher price sensitivity compared to large hospital systems.
Supply Chain Analysis
Specialized sensor manufacturing capacity in regions like China and the United States represents a critical chokepoint for vital signs monitoring devices. The supply chain concentrates in China, the United States, and Germany for both component manufacturing and final assembly. Raw material dependencies include advanced sensors, semiconductors, and wireless communication modules. Single-source component vulnerability poses a structural risk. Distribution runs through third-party remote patient monitoring (RPM) service companies and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the decentralization of care from hospitals to diverse home settings, creating specialized niches.
For Market Incumbents: Shield core hospital segments by investing in integrated monitoring solutions and robust cybersecurity infrastructure. GE Healthcare leverages its extensive hospital network to secure large-volume contracts, reinforcing its position against nimbler innovators capturing decentralized care opportunities. Deepen channel control through hospital networks and prioritize R&D in next-generation wearable devices to maintain competitive advantage.
For New Entrants and Emerging Players: A streamlined certification pathway, such as the US FDA's Digital Health Software Precertification Program, offers a viable entry point. Target underserved markets in Southeast Asian and Latin American countries, where healthcare infrastructure is developing rapidly. Focus on the consumer wellness segment with user-friendly, AI-powered predictive analytics devices. Implement subscription-based service models to align with evolving provider procurement preferences.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized technology firms with strong intellectual property in advanced non-invasive monitoring or SaMD developers. The market's long-term viability centers on continuous monitoring for chronic disease management and preventive health. Identify acquisition targets that offer seamless integration capabilities with electronic health records. The expansion of reimbursement codes for remote patient monitoring services represents a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures large-volume contracts and embeds devices within established clinical workflows for GE Healthcare. |
| Software Companion Development | Enhances device functionality with AI-powered predictive analytics, creating new value propositions for Medtronic. |
| Reimbursement Strategy Optimization | Accelerates adoption of remote patient monitoring services by ensuring financial viability for providers. |
| CE Marking Pathway Investment | Facilitates market access and compliance across the European Union for Mindray Medical International Limited. |
| Miniaturized Sensor R&D | Drives expansion into home care and consumer wellness applications, broadening market reach for Masimo. |
Research Approach
Operator-level perspectives from clinicians, hospital procurement committees, biomedical engineers, and remote patient monitoring service providers anchored the qualitative base for this analysis. Primary interviews were triangulated with secondary data from US FDA filings, China NMPA guidelines, EU MDR documentation, and various healthcare industry reports. This approach ensured a comprehensive understanding, supported by both bottom-up and top-down data validation.
Sensitivity analysis framed the quantitative model, which projected market trends across the analysis window. The model integrated segmentation dimensions including product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected market dynamics, incorporating industry-specific inputs such as chronic disease prevalence rates and digital health infrastructure investment.
Decision-makers should treat outputs as directional under current macroeconomic and regulatory assumptions; material deviation would warrant model refresh. Forecasts reflect these documented assumptions, but potential risk factors like unforeseen regulatory shifts or cybersecurity threats could impact market trajectory. Practitioners should keep alternative scenarios live as reimbursement policy changes and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Italy Cardiovascular Devices Market
Cardiovascular Devices
Ventricular Drainage Sets Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Neurovascular Stent Retrievers Market
Cardiovascular Devices
Peripheral Vascular Devices Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market