
 Healthcare Smart Card Reader Market | 2026-2036
Healthcare Smart Card Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Smart Card Reader Market Intelligence
Asset-light leasing models for clinical IT infrastructure is reconfiguring procurement patterns across mid-sized hospital networks. Thales Group leverages its aerospace-grade security heritage to anchor premium positioning in biometric-enabled readers. Identiv competes through specialized NFC and physical access convergence platforms for integrated health systems.
A healthcare smart card reader is an electronic device that interfaces with microprocessor-equipped cards through ISO 7816 contact pads or ISO 14443 radio frequency fields to authenticate identity, decrypt protected health information, or process payment credentials in clinical settings. Contactless technology leads segment momentum as hospitals prioritize hygiene protocols and throughput speed in emergency departments. Patient identification applications sustain the deepest margin pools due to mandatory interoperability mandates and longitudinal record-matching complexity. Cloud-based deployment architectures are accelerating fastest among multi-site pharmacy chains seeking centralized credential management.
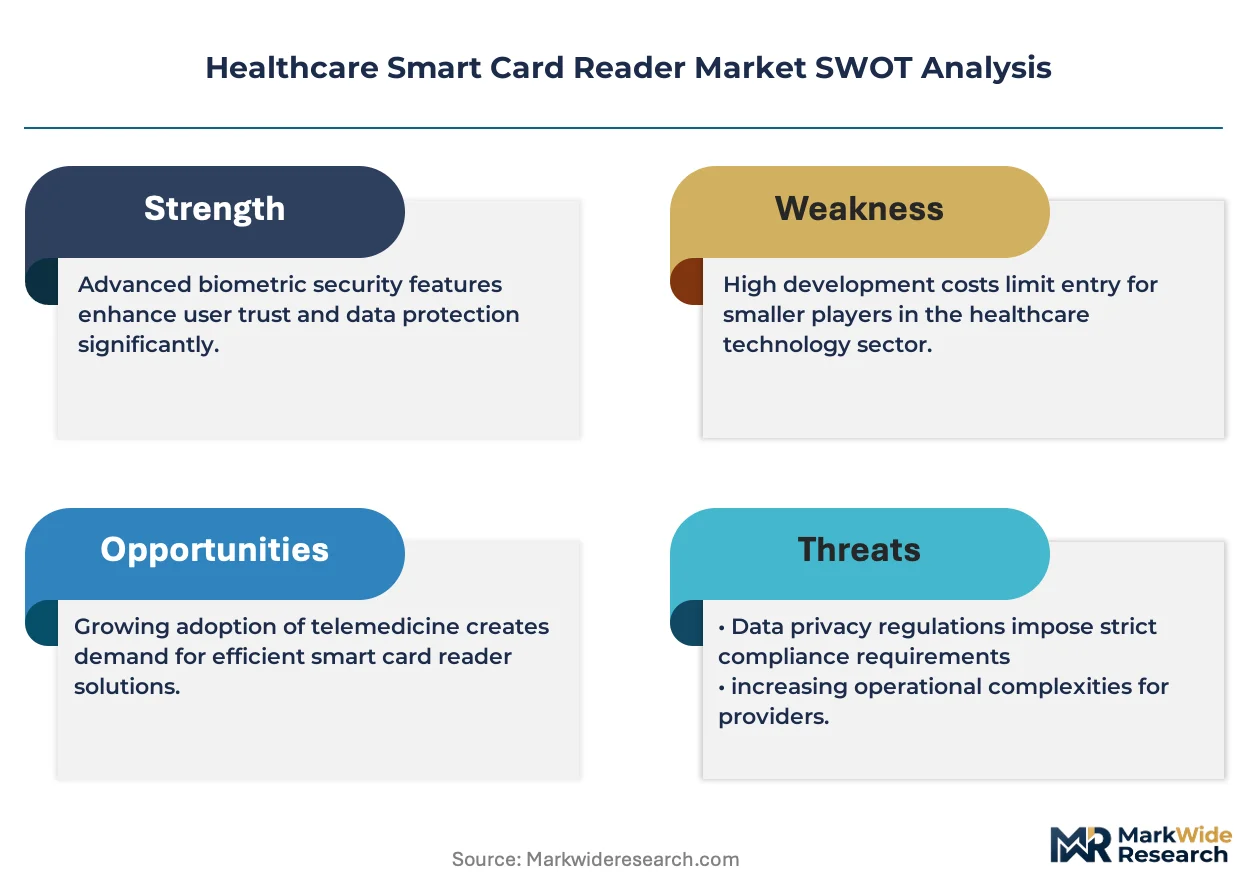
FDA 21 CFR Part 820 and HIPAA Security Rule requirements compel manufacturers to document design controls and audit trails for every firmware revision distributed to covered entities. The EU Medical Device Regulation and GDPR cross-apply where readers process biometric templates or cross-border patient data, forcing dual compliance investments. Stakeholders must monitor emerging state-level biometric privacy statutes that could fragment deployment standards and trigger retrofit obligations.
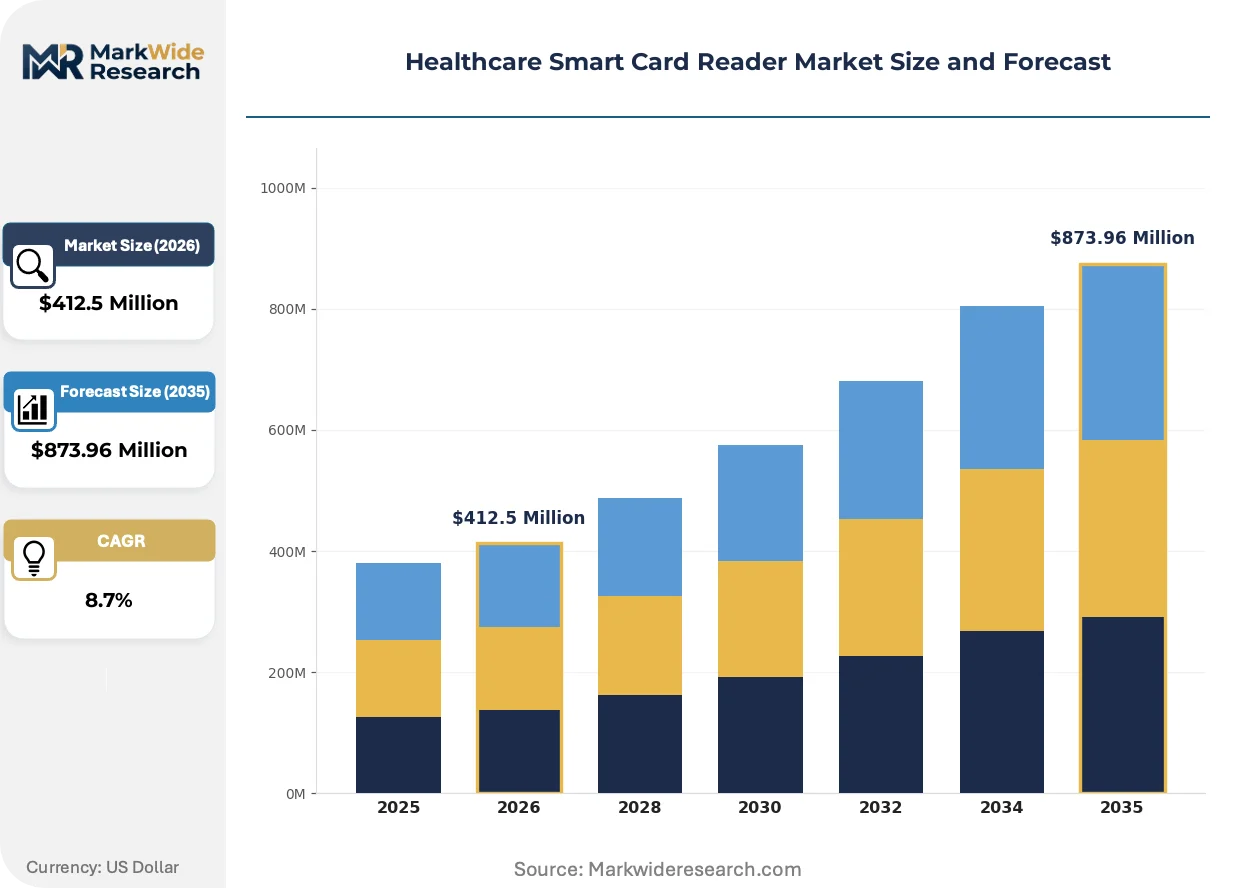
Market Dynamics
Contactless authentication protocols are compressing replacement cycles across acute care facilities, forcing hardware vendors to reconcile ISO 14443 interoperability with legacy EMV infrastructure already embedded in hospital payment ecosystems.
Growth Catalysts
- HIPAA Security Rule enforcement:Covered entities face escalating audit frequency for access control systems, compelling systematic upgrades to FIPS 140-2 validated readers at patient registration points.
- Emergency department throughput mandates:Hospital networks in the United States prioritize sub-second tap-and-go patient identification to reduce triage queue congestion during surge events.
- Biometric template standardization:INCITS 378 fingerprint format interoperability is unlocking multi-vendor procurement flexibility previously constrained by proprietary matching algorithms.
Market Restraints
- Semiconductor supply concentration:Discrete secure element fabrication concentrates among Taiwanese foundries, exposing reader manufacturers to 26-week lead time volatility for cryptographic coprocessors.
- EU MDR technical documentation burden:Class IIa device classification for biometric-enabled readers forces notified body involvement in every hardware revision, extending time-to-market by 8-14 months.
- Smartphone NFC substitution:Apple Wallet and Google Health integrations enable credential storage on consumer devices, threatening dedicated reader attach rates in ambulatory settings.
Strategic Opportunities
- India's Ayushman Bharat Digital Mission:The national health stack mandates ABHA-number-linked authentication at every care encounter, creating immediate demand for ISO 7816-compliant readers across 150,000+ public health facilities.
- Cloud-native credential lifecycle management:Multi-site pharmacy chains in Germany are piloting centralized provisioning that eliminates site-by-site card personalization infrastructure.
- FIDO2/WebAuthn convergence:Browser-based authentication standards are opening integration pathways between physical access readers and enterprise single sign-on systems.
Industry Challenges
- Firmware vulnerability management:FDA 21 CFR Part 820 design control requirements mandate documented traceability for every security patch distributed to deployed devices, straining DevSecOps bandwidth at mid-tier manufacturers.
- Biometric sensor calibration complexity:Multi-spectral fingerprint modules require field-level recalibration protocols that most biomedical engineering teams lack training to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Smart Card Reader Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Stripe, Contact Chip, Contactless, Biometrics End User: Hospitals, Clinics, Pharmacies, Laboratories Application: Patient Identification, Access Control, Payment Processing, Data Encryption Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Thales Group, Identiv, Advanced Card Systems, HID Global Corporation, IDEMIA, rf IDEAS, FEITIAN Technologies, CHERRY, Advantech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Smart Card Reader Market Strategic Shifts & Innovations
Authentication hardware is bifurcating between ultra-hygienic contactless dominance in clinical settings and ruggedized multi-interface durability for mobile emergency response units.
Multi-protocol reader chipsets is hybridizing contact EMV, contactless NFC, and Bluetooth Low Energy credential reception into single-module designs. Emergency medical services fleets in Texas and Florida are adopting these tri-mode devices to eliminate separate equipment for hospital access, vehicle ignition, and narcotics safe authentication. This convergence is compressing supplier margins by collapsing three discrete product categories into one replaceable component.
GDPR Article 9 processing restrictions on biometric health data are forcing EU manufacturers to implement on-device template matching that never transmits raw fingerprint images across networks. French hospital groups now require ANSM-certified readers with dedicated secure enclaves for template storage. German procurement offices are prioritizing vendors offering data residency guarantees backed by Bundesdatenschutzgesetz compliance documentation.
Leasing structures for clinical IT infrastructure are displacing capital purchase cycles across mid-sized hospital networks in the United States. Third-party financiers assume hardware refresh obligations while facilities pay per-authenticated-transaction fees. This model concentrates buyer power among regional health systems capable of negotiating enterprise-wide service agreements spanning 50+ sites.
Healthcare Smart Card Reader Market Segmentation
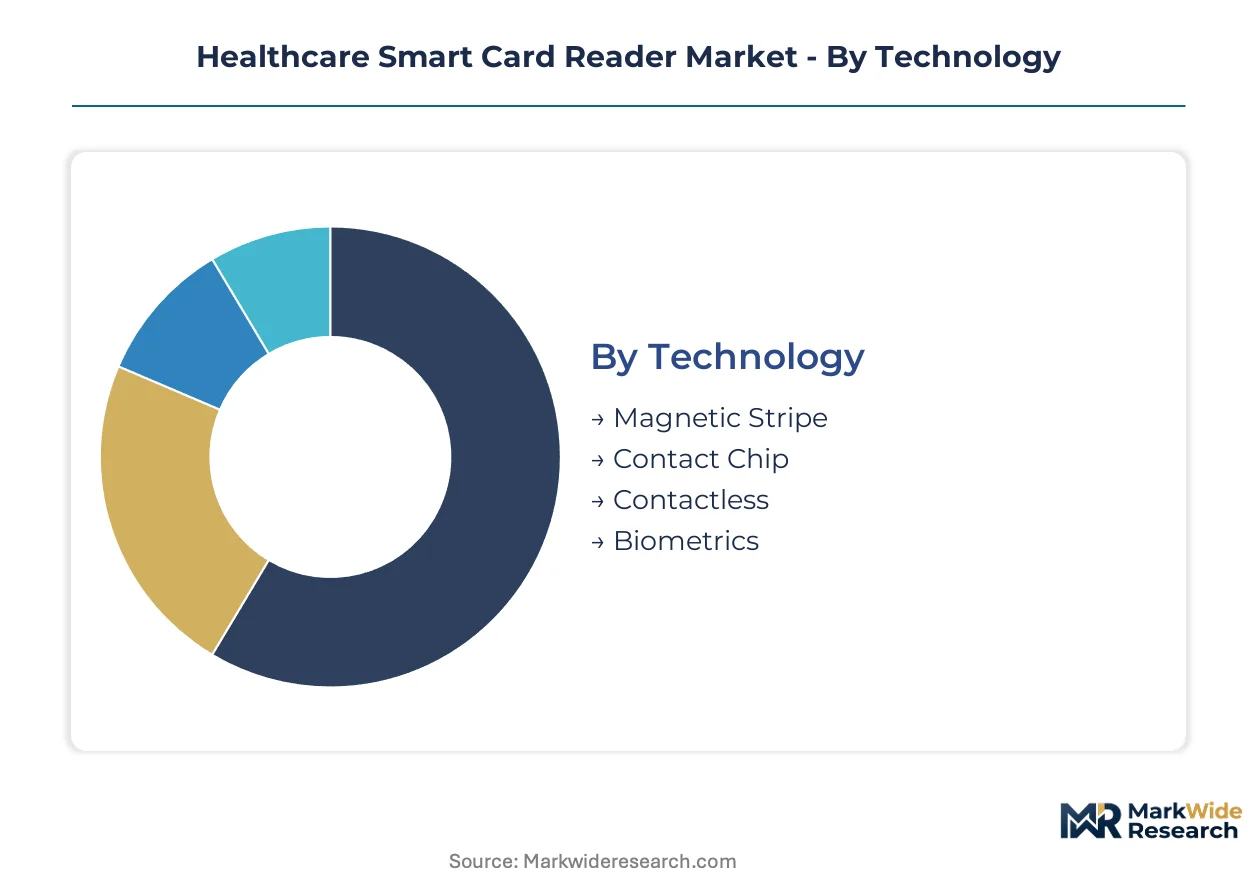
Technology choices in healthcare smart card readers determine regulatory compliance pathways and procurement budgets. Deployment architectures shape whether hospital networks retain infrastructure control or delegate credential management to cloud providers. Understanding these segment boundaries clarifies where vendor specialization creates defendable positions versus commodity competition.
Technology:
Cost tier stratification separates legacy infrastructure from premium biometric-enabled systems requiring specialized secure element integration.
- Contactless:ISO 14443-compliant radio frequency interfaces enable tap-and-go authentication without physical card insertion. Hospital emergency departments in the United States prioritize these readers to accelerate patient throughput during surge events while maintaining hygiene protocols.
- Contact Chip:ISO 7816 standard contact pads provide deterministic electrical connections for high-assurance cryptographic operations. German hospital networks retain substantial installed bases for EMV payment integration and legacy patient card compatibility.
- Biometrics:Multi-spectral fingerprint or palm vein sensors embed template matching within dedicated secure enclaves.
- Magnetic Stripe:Legacy swipe readers persist in ambulatory settings with minimal security requirements.
Contactless holds installed capacity. Biometrics is rotating up the share rankings.
End User:
Customer type concentration varies by procurement sophistication and regulatory exposure.
- Hospitals:Acute care facilities deploy multi-protocol readers at registration desks, pharmacy counters, and restricted clinical zones. United States health systems drive demand for FIPS 140-2 validated devices under intensified HIPAA Security Rule enforcement.
- Pharmacies:Retail and hospital-affiliated dispensers require compact countertop units with integrated payment authentication. German multi-site chains are piloting cloud-native credential lifecycle management to eliminate distributed card personalization infrastructure.
- Clinics:Outpatient facilities favor cost-optimized single-interface readers for basic patient identification.
- Laboratories:Diagnostic facilities prioritize audit trail capabilities for specimen chain-of-custody documentation.
Hospitals anchor procurement volume. Pharmacies are climbing the fastest as centralized authentication architectures displace site-level systems.
Application:
Functional use case determines margin structure and interoperability requirements.
- Patient Identification:Longitudinal record matching across encounters demands ISO-standard card interfaces and demographic verification algorithms. India's Ayushman Bharat Digital Mission mandates ABHA-number-linked authentication at every care touchpoint across public health facilities.
- Access Control:Physical security integration requires Wiegand or OSDP protocol compatibility with building management systems. French hospital groups now require ANSM-certified readers for biometric template storage under GDPR Article 9 processing restrictions.
- Payment Processing:EMV contact and contactless acceptance for patient financial responsibility.
- Data Encryption:On-device cryptographic operations for protected health information decryption.
Patient identification commands premium positioning. Access control is gaining share fastest as FIDO2 standards converge physical and logical security domains.
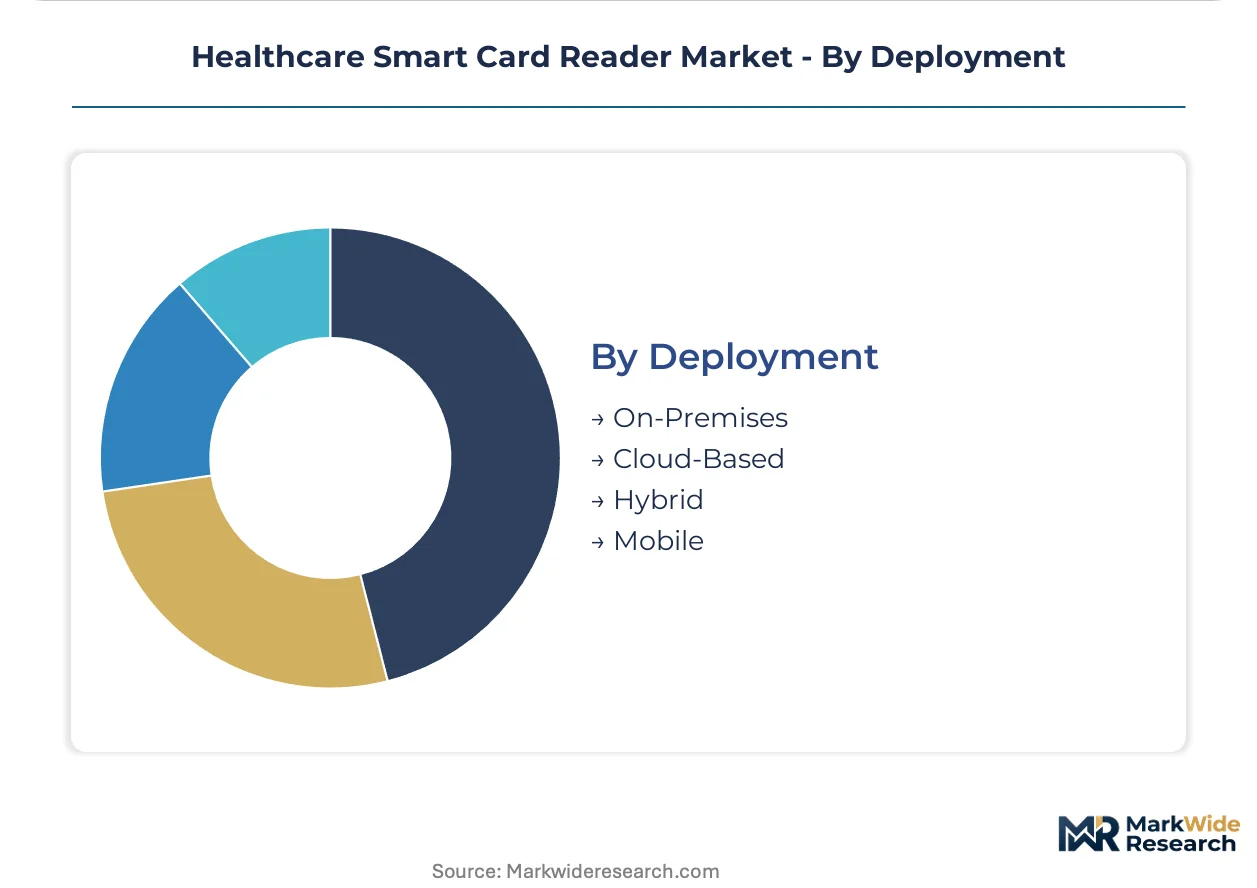
Deployment:
Architecture maturity separates capital-intensive on-premises installations from operational expenditure models.
- On-Premises:Local server infrastructure maintains complete data residency control with dedicated hardware security modules. German procurement offices prioritize vendors offering Bundesdatenschutzgesetz compliance documentation.
- Cloud-Based:Centralized credential provisioning and firmware management eliminate distributed IT overhead. United States mid-sized hospital networks are adopting per-transaction leasing structures that transfer hardware refresh obligations to third-party financiers.
- Hybrid:Edge authentication with cloud-synchronized policy enforcement balances latency and manageability.
- Mobile:Battery-powered Bluetooth Low Energy readers for emergency medical services and home health applications.
On-premises retains legacy dominance. Cloud-based is rotating up the share rankings as regional health systems consolidate multi-site service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in healthcare smart card readers tilt toward net imports in emerging health infrastructure markets while established manufacturing economies maintain trade surpluses in high-assurance biometric-enabled devices. Component sourcing concentrates among Taiwanese secure element foundries, creating supply chain exposure for assembly operations across multiple continents. Procurement patterns diverge sharply between contactless-dominant hospital networks in hygiene-sensitive markets and legacy contact-chip retention in EMV-integrated European systems.
United States
Hospital networks in Texas and Florida are deploying tri-mode readers for emergency medical services fleets to consolidate hospital access, vehicle ignition, and narcotics safe authentication into single devices. FDA 21 CFR Part 820 quality system regulation shapes device validation requirements for manufacturers serving covered entities under intensified HIPAA Security Rule enforcement. The Southeast health corridor from Atlanta to Miami is piloting per-transaction leasing structures that transfer hardware refresh obligations to third-party financiers.
Germany
Multi-site pharmacy chains are piloting cloud-native credential lifecycle management to eliminate distributed card personalization infrastructure across regional networks. Bundesdatenschutzgesetz compliance documentation is becoming a mandatory procurement filter for hospital procurement offices evaluating vendor shortlists. The Rhine-Ruhr metropolitan cluster anchors demand for ISO 7816-compliant contact readers retaining compatibility with legacy EMV payment infrastructure embedded in hospital ecosystems.
India
The Ayushman Bharat Digital Mission is mandating ABHA-number-linked authentication at every care encounter across public health facilities, creating immediate demand for ISO 7816-compliant readers at 150,000-plus sites. The national health stack is driving standardization requirements that favor interoperable contact-chip readers over proprietary biometric systems. Maharashtra's Mumbai-Pune industrial corridor is emerging as a distribution hub for reader deployment into tier-two and tier-three city hospital networks.
France
Hospital groups are requiring ANSM-certified readers with dedicated secure enclaves for biometric template storage under GDPR Article 9 processing restrictions on biometric health data. The Île-de-France region is concentrating procurement for multi-hospital systems seeking centralized credential management with data residency guarantees. Paris-based health technology integrators are specifying on-device template matching that never transmits raw fingerprint images across networks.
Japan
Metropolitan Tokyo hospital networks are prioritizing sub-second tap-and-go patient identification to reduce triage queue congestion during surge events while maintaining stringent hygiene protocols. PMDA medical device classification requirements are extending time-to-market for biometric-enabled readers requiring notified body involvement in hardware revisions. The Kansai Osaka-Kobe cluster is retaining substantial installed bases of contact-chip readers for payment integration compatibility with legacy patient card systems.
Healthcare Smart Card Reader Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers: aerospace-grade security heritage players, specialized NFC convergence specialists, and volume-driven Asian component fabricators. Strategic archetypes include premium biometric-integrated system houses, multi-protocol hybrid platform providers, and cloud-native credential lifecycle service operators. Dominant competitive moves span technology licensing partnerships for FIDO2/WebAuthn convergence and geographic expansion into India's Ayushman Bharat deployment pipeline.
Within the premium security tier, Thales Group and IDEMIA represent aerospace and government credential heritage translated into clinical settings, while Identiv exemplifies the NFC-specialist archetype competing through physical-logical access convergence. FEITIAN Technologies occupies a position among Asia-based fabricators serving cost-optimized procurement segments. HID Global Corporation anchors the multi-protocol platform category with hybrid contact-contactless-bluetooth module integration. These groupings illustrate how vendor selection criteria diverge between FIPS 140-2 validated deployments in United States health systems and Bundesdatenschutzgesetz-compliant configurations in German hospital networks.
| Leading Market Players |
|---|
| Thales Group |
| Identiv |
| Advanced Card Systems |
| HID Global Corporation |
| IDEMIA |
| rf IDEAS |
| FEITIAN Technologies |
| CHERRY |
| Advantech |
| Others |
Cost & Logistics Intelligence
The Kaohsiung-to-Long Beach transpacific corridor shapes landed cost dynamics for cryptographic coprocessors, concentrating pricing power among Taiwanese foundries while forcing German hospital procurement offices to absorb freight volatility into multi-year service agreements.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FIPS 140-2 certification tier and embedded secure element grade serving as primary differentiation drivers. Pricing pressure stems from smartphone NFC substitution threatening dedicated reader attach rates in ambulatory settings. Mid-sized hospital networks exhibit highest price sensitivity due to capital constraint, while aerospace-grade security heritage vendors command least sensitivity through mandatory compliance bundling.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment limit capacity expansion for secure element fabrication, concentrating supply among Taiwan, South Korea, and select US facilities. Raw material dependencies span silicon wafers, cryptographic coprocessors, and multi-spectral fingerprint sensor arrays. Single-source vulnerability in Taiwanese foundry capacity exposes assembly operations to lead time volatility. Distribution runs through authorized medical device distributors with FDA 21 CFR Part 820 traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FIDO2/WebAuthn integration expertise constrains vendor differentiation, creating acquisition premiums for engineering teams with cross-protocol authentication architecture experience.
For Market Incumbents: Insulate installed base relationships through backward integration into secure element supply chains and accelerated firmware vulnerability management protocols. Smartphone NFC substitution and cloud-native credential lifecycle operators threaten hardware attach rates. Certification investment in ANSM and Bundesdatenschutzgesetz compliance documentation anchors switching costs. For New Entrants and Emerging Players: India's Ayushman Bharat Digital Mission deployment pipeline represents the most penetrable entry point, with ISO 7816-compliant reader demand across 150,000-plus public health facilities creating immediate volume opportunity. Cloud-native credential lifecycle management for German multi-site pharmacy chains offers second white-space target. Hospital system partnership models with per-transaction leasing structures accelerate referenceability. For Investors and Strategic Acquirers: NFC-physical access convergence specialists with FIDO2 integration capabilities represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on authentication protocol standardization trajectories. The signal to watch is INCITS 378 fingerprint format interoperability adoption velocity across US health system procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| FIDO2/WebAuthn Certification | Opens integration pathways between physical access readers and enterprise single sign-on systems at US hospital networks. |
| Secure Element Backward Integration | Captures margin pool currently concentrated among Taiwanese foundries while reducing 26-week lead time exposure. |
| Cloud-Native Credential Lifecycle Platform | Eliminates distributed card personalization infrastructure for German multi-site pharmacy chains seeking centralized control. |
| ANSM Biometric Template Certification | Unlocks French hospital procurement under GDPR Article 9 processing restrictions with on-device matching requirements. |
| Ayushman Bharat Deployment Partnership | Secures volume anchor across 150,000-plus Indian public health facilities mandating ABHA-linked authentication. |
Research Approach
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at device manufacturers, then refined against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract repositories, and customs trade flow records. Bottom-up demand modeling across technology segments triangulated with top-down market sizing from component supply chain interviews.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across contactless, contact chip, and biometric technology tiers; deployment architecture spanning on-premises, cloud-based, and hybrid configurations; and end-user concentration among hospitals, pharmacies, and emergency medical services. CAGRs were derived from installed base replacement cycle analysis and penetration rate assumptions for emerging authentication protocols. Forecast inputs incorporated HIPAA Security Rule enforcement intensity and India's national health stack deployment velocity.
Stress conditions across semiconductor supply concentration, EU MDR classification timeline delays, and smartphone NFC substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and interoperability mandate adherence. Material shifts in export control regimes governing secure element fabrication equipment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Healthcare IT Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Femtech Market