
 Operating Room Software Market | 2026-2036
Operating Room Software Market Size, Share, and Industry Trends Forecast 2026-2036
Operating Room Software Market Insights
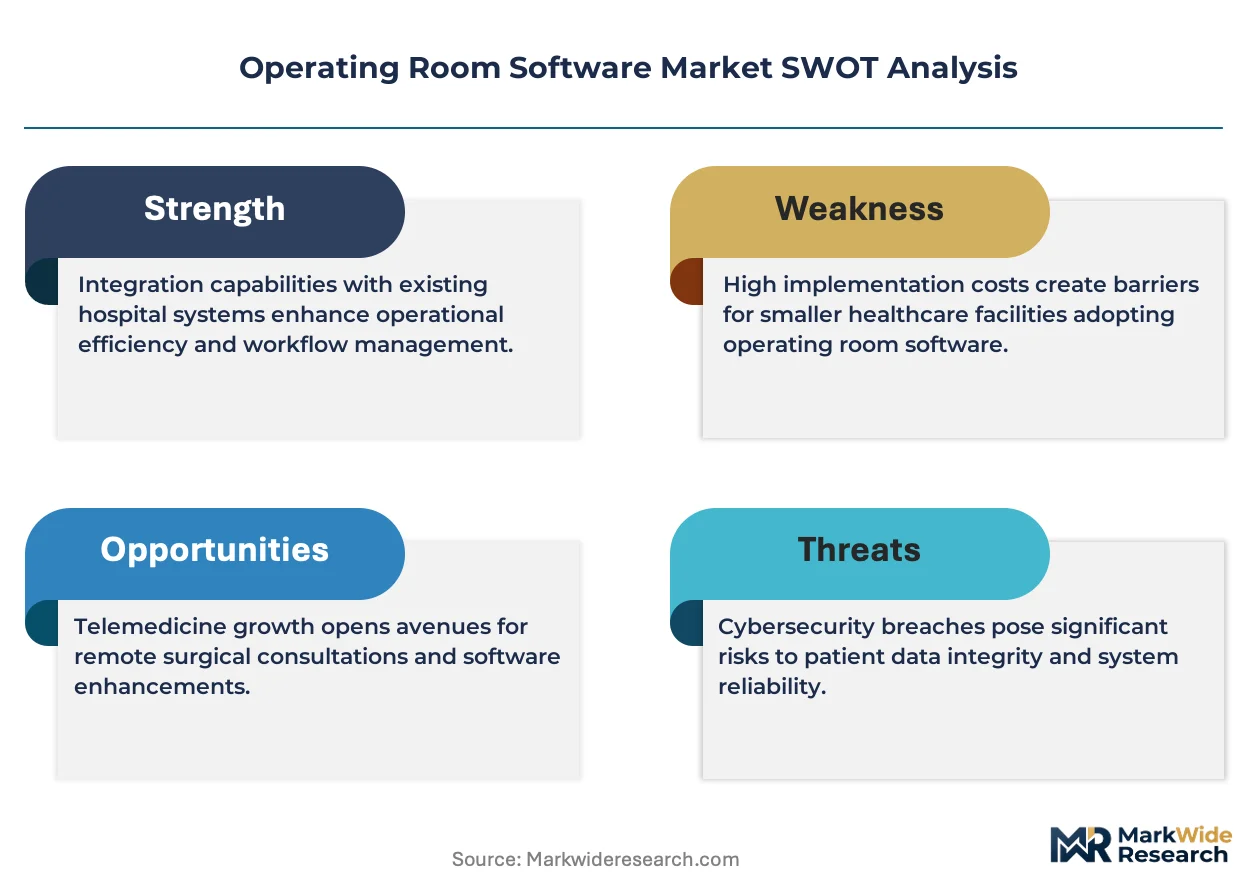
Subscription-based leasing and asset-light SaaS procurement is fragmenting competitive dynamics for smaller surgical facilities that previously could not afford enterprise licenses. Epic Systems Corporation leverages its dominance in hospital electronic health records to extend into perioperative workflows. GE Healthcare anchors its position through deep hardware-software integration across imaging and surgical navigation suites. Philips sustains R&D intensity in clinical informatics that connects pre-operative planning to intraoperative execution.
Operating room software encompasses digital platforms that coordinate surgical scheduling, resource allocation, instrument tracking, and real-time clinical documentation within perioperative environments. These systems typically integrate with anesthesia machines, patient monitors, and imaging modalities through HL7 FHIR or proprietary protocols to ensure continuity of care and regulatory traceability. Scheduling software and surgical dashboards capture the largest installed base, though cloud-based deployment models represent the fastest-expanding segment as health systems retire legacy client-server architectures. Inventory management systems command premium pricing where RFID-enabled instrument traceability supports compliance with FDA unique device identification mandates.
FDA software-as-a-medical-device guidance, HIPAA security rule provisions, and ONC interoperability certification requirements collectively shape product development roadmaps and customer procurement criteria for vendors seeking access to US health systems. The European Medical Device Regulation and GDPR data localization constraints add compliance layers for platforms serving multi-national hospital chains. Stakeholders must evaluate whether vendor consolidation around electronic health record incumbents will constrain best-of-breed innovation in surgical workflow optimization.
Market Dynamics
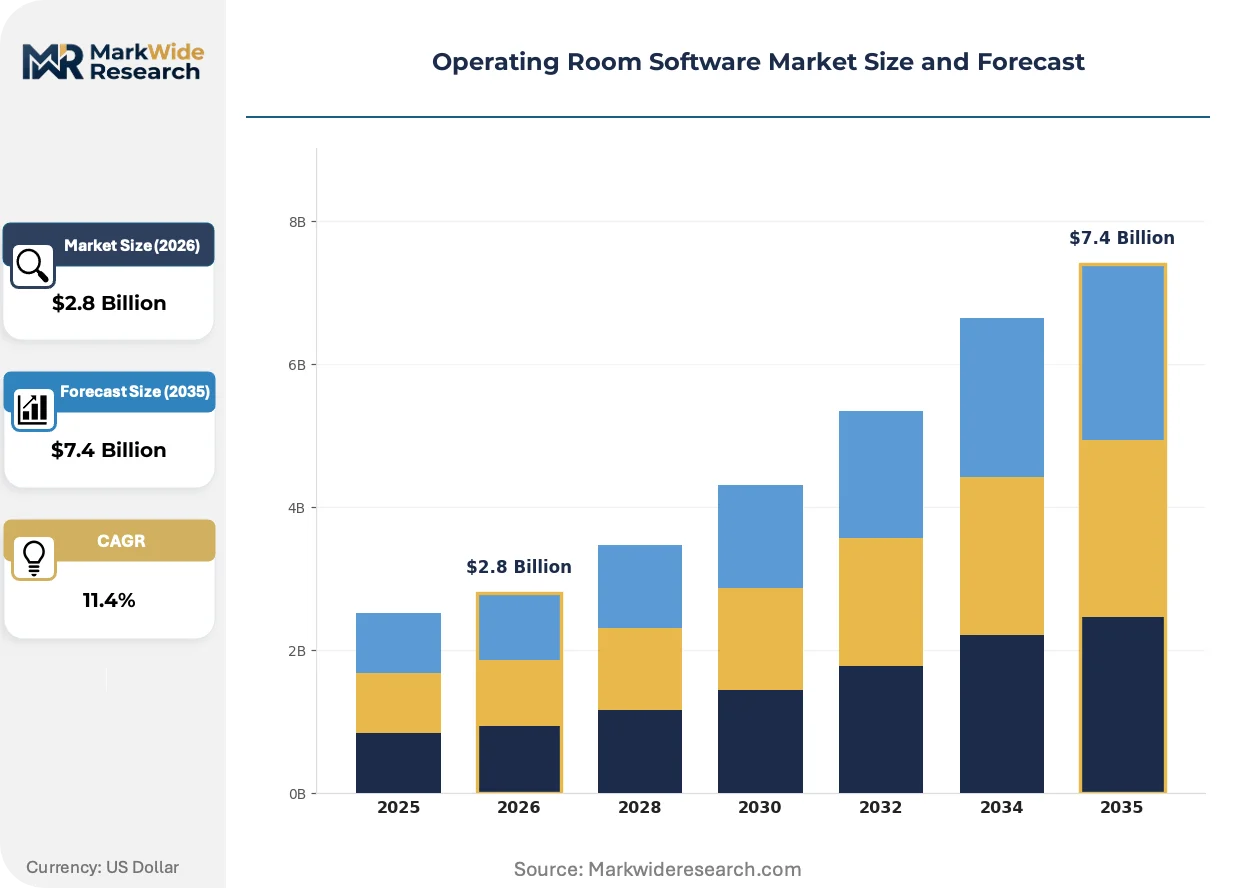
Cloud-native perioperative platforms are fragmenting competitive dynamics by collapsing upfront licensing barriers that historically locked smaller surgical facilities out of enterprise-grade workflow automation. The shift from perpetual licenses to consumption-based SaaS models is redistributing purchasing power toward ambulatory surgical centers and regional hospital networks.
Growth Catalysts
- FDA software-as-a-medical-device framework:The tightened validation requirements for surgical workflow tools are accelerating vendor consolidation around platforms with pre-cleared quality management systems, favoring established interoperability leaders.
- Ambulatory surgical centers:These facilities are expanding adoption of cloud-based perioperative platforms as subscription economics align with their capital-constrained operating models and episodic case volumes.
- HL7 FHIR protocols:Standardized data exchange specifications are reducing integration friction between OR software and anesthesia machines, patient monitors, and imaging modalities, compressing deployment timelines.
Market Restraints
- Specialized health informatics talent:Scarcity of professionals versed in both clinical workflows and FHIR implementation is inflating deployment costs and extending project timelines for mid-tier health systems.
- Legacy client-server architectures:Technical debt from decades-old on-premise installations creates switching friction that anchors installed bases to incumbent vendors despite superior cloud alternatives.
- GPR data localization:European Medical Device Regulation compliance layers constrain platform architecture flexibility for vendors serving multi-national hospital chains with centralized cloud infrastructure.
Strategic Opportunities
- RFID-enabled instrument traceability:Inventory management systems supporting FDA unique device identification mandates command premium pricing where compliance automation replaces manual reconciliation workflows.
- Pre-operative to intraoperative informatics convergence:Clinical platforms connecting surgical planning to real-time execution represent underpenetrated white space distinct from scheduling-dominated incumbents.
- Integrated delivery networks:United States health systems prioritizing interoperability investments are consolidating vendor relationships around platforms demonstrating cross-facility data continuity.
Industry Challenges
- FHIR certification complexity:ONC interoperability certification requirements demand sustained engineering investment that strains R&D budgets of specialized surgical workflow vendors competing against electronic health record incumbents.
- Multi-modal integration:Real-time synchronization across anesthesia machines, patient monitors, and imaging modalities requires proprietary protocol adaptation that fragments development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operating Room Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Inventory Management Systems, Documentation Tools, Surgical Dashboards End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Care Facilities Deployment: On-premises, Cloud-based, Hybrid, Mobile Applications Integration Level: Interoperable Systems, Standalone Solutions, API-integrated Platforms, Legacy Software |
| Companies Covered | Surgical Information Systems, Veradigm LLC, Picis Clinical Solutions, Inc., GE Healthcare, Oracle Corporation, Koeninklijke Philips N.V., Getinge AB, Epic Systems Corporation, Steris Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operating Room Software Market Trends and Innovations
Perioperative software architecture is pivoting from documentation-centric systems toward predictive coordination platforms that anticipate resource conflicts before they cascade into scheduling failures. This reorientation demands convergence of clinical informatics, IoT sensor networks, and machine learning inference at the edge.
Edge-deployed AI inference engines for surgical duration prediction are rendering obsolete rule-based scheduling algorithms that relied on historical averages and static block allocations. Academic medical centers in the United States are piloting these systems for orthopedic and cardiothoracic service lines. The compression of prediction error margins is enabling dynamic block reallocation that improves utilization rates without expanding physical OR footprint.
Europe's Medical Device Regulation is reclassifying perioperative decision support modules as Class IIa or IIb medical devices, triggering quality management system audits that smaller software vendors lack resources to navigate. The regulatory burden is concentrating innovation capacity among platforms with existing notified body relationships. Surgical dashboard vendors are responding by modularizing AI features into separately certifiable components that can be decoupled from core scheduling functionality.
Subscription leasing models are displacing perpetual license purchases across independent ambulatory surgical centers and regional hospital networks. Capital-constrained buyers favor operational expenditure treatment and embedded upgrade cycles over depreciation-heavy asset ownership. The United States exhibits the most pronounced shift, where private equity-backed surgery center rollups negotiate enterprise SaaS terms that bundle implementation services into per-case pricing.
Operating Room Software Market Segmentation
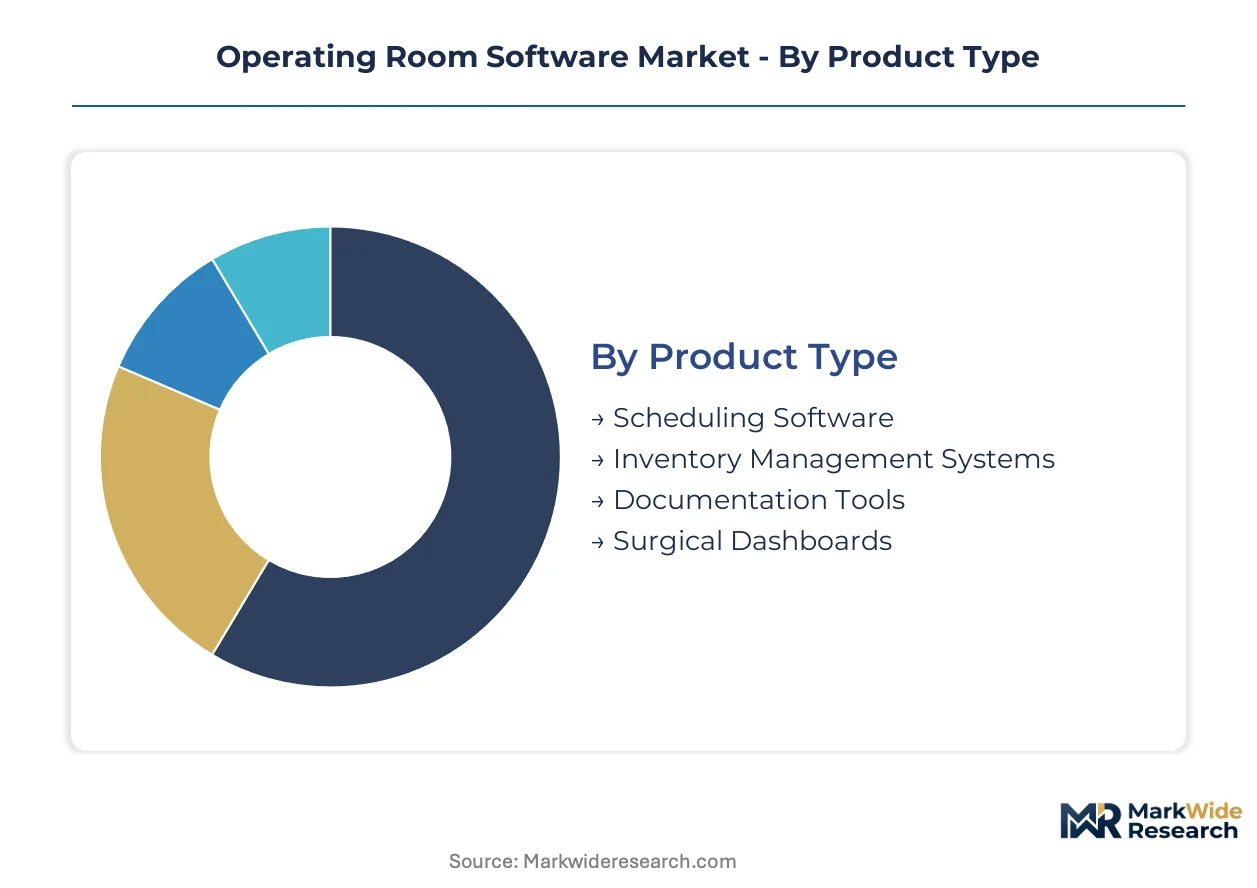
Perioperative software segmentation reveals divergent technology maturities across product categories, with legacy scheduling systems coexisting alongside emerging AI-native coordination platforms. Deployment models and integration architectures further stratify vendor competitiveness and customer switching economics.
Product Type:
Mature documentation-centric systems anchor installed bases while predictive coordination platforms emerge as the fastest-climbing revenue tier.
- Scheduling Software:Rule-based algorithms manage surgical block allocations, staff rotations, and equipment reservations through deterministic logic. United States integrated delivery networks concentrate procurement here as interoperability investments prioritize OR utilization metrics. Legacy vendors defend positions through embedded EHR relationships despite inferior predictive capabilities.
- Inventory Management Systems:RFID-enabled instrument tracking platforms automate FDA unique device identification compliance through real-time location services and sterilization cycle monitoring. Premium pricing concentrates among academic medical centers where surgical instrument loss rates exceed manual reconciliation thresholds. Cloud-native entrants displace on-premise legacy systems through subscription economics.
- Documentation Tools:Perioperative nursing notes and anesthesia records capture structured clinical data for regulatory traceability.
- Surgical Dashboards:Real-time visualization platforms aggregate patient monitors, imaging feeds, and workflow alerts.
Scheduling Software retains volume leadership; Inventory Management Systems holds the steepest expansion curve.
End User:
Capital intensity and case volume variability create four distinct procurement profiles across the care continuum.
- Hospitals:Enterprise health systems deploy comprehensive perioperative suites integrating scheduling, documentation, and analytics across multiple surgical service lines. United States hospitals prioritize ONC interoperability certification and FDA software-as-a-medical-device compliance in vendor selection. Epic Systems Corporation leverages EHR dominance to extend into OR workflows.
- Ambulatory Surgical Centers:Capital-constrained facilities favor cloud-based SaaS procurement with per-case pricing that aligns operational expenditure with episodic surgical volumes. Private equity-backed ASC rollups negotiate enterprise terms bundling implementation services. Subscription leasing collapses upfront barriers that historically excluded smaller facilities from workflow automation.
- Clinics:Office-based surgical suites require lightweight scheduling and limited documentation modules.
- Specialty Care Facilities:Orthopedic and ophthalmology centers demand procedure-specific instrument tracking and implant registry integration.
Hospitals dominate absolute revenue; Ambulatory Surgical Centers gains share fastest through SaaS conversion.
Deployment:
Architecture decisions determine total cost of ownership trajectories and regulatory compliance burdens across multi-national footprints.
- On-premises:Client-server installations persist where data residency requirements or legacy hardware dependencies anchor health systems to depreciated infrastructure. Technical debt from decades-old architectures creates switching friction that protects incumbent vendors despite superior cloud alternatives. United States rural hospitals exhibit highest retention rates.
- Cloud-based:Native SaaS platforms eliminate capital expenditure cycles and embed continuous upgrade delivery through containerized microservices. GDPR data localization constraints and European Medical Device Regulation quality management audits complicate centralized infrastructure for multi-national chains. Edge-deployed inference engines for surgical duration prediction pilot here.
- Hybrid:Split architectures retain sensitive patient data on-premise while offloading analytics workloads to public cloud.
- Mobile Applications:Surgeon-facing iOS and Android tools extend scheduling visibility and alert delivery beyond workstation tethering.
On-premises retains installed base dominance; Cloud-based climbs fastest as health systems retire legacy architectures.
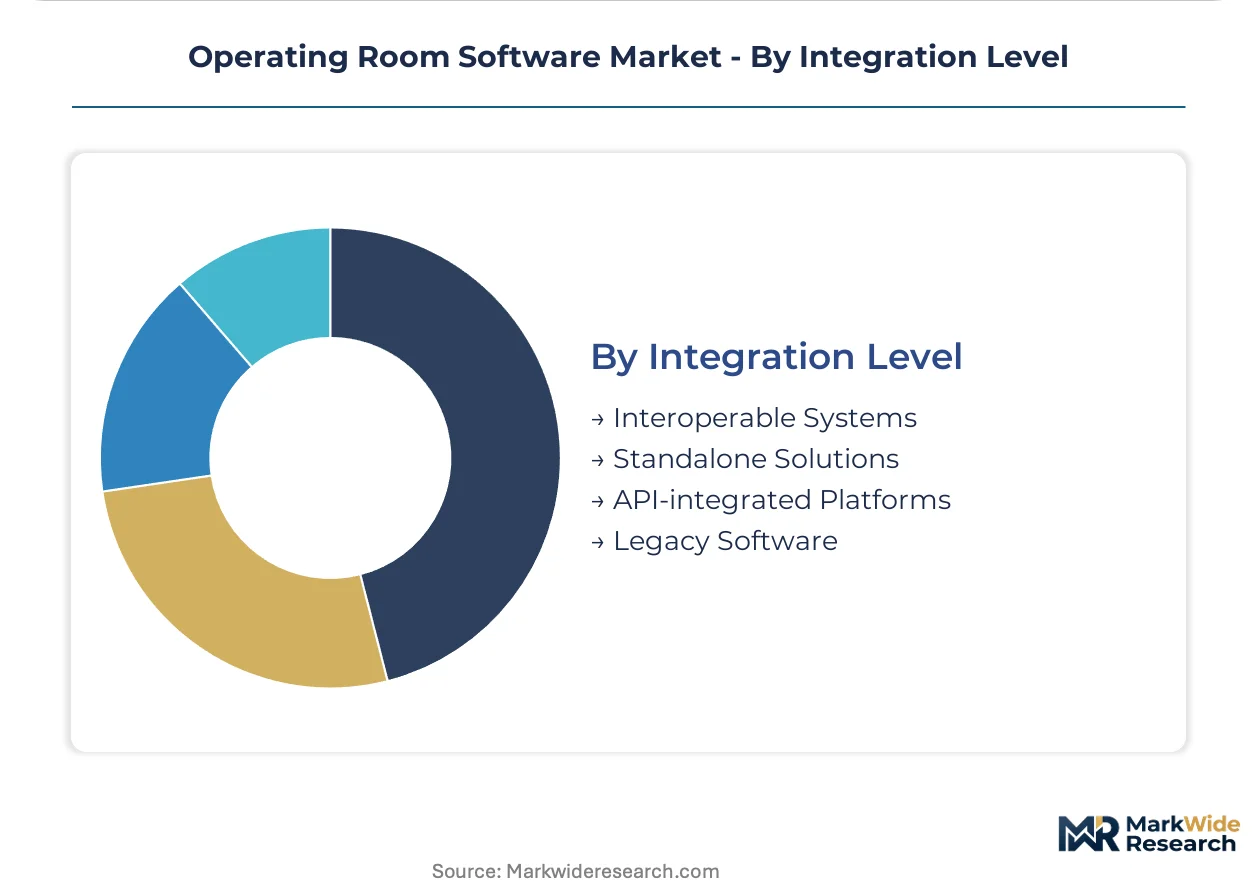
Integration Level:
Interoperability depth determines deployment complexity and long-term vendor switching costs for perioperative environments.
- Interoperable Systems:HL7 FHIR-native platforms exchange structured data with anesthesia machines, patient monitors, and imaging modalities through standardized APIs. FHIR certification complexity strains R&D budgets of specialized vendors competing against EHR incumbents. United States health systems prioritize these platforms for cross-facility data continuity.
- Standalone Solutions:Functionally isolated systems require manual data entry or batch file transfers to maintain care record continuity. Ambulatory surgical centers with limited IT staffing tolerate fragmentation where subscription economics outweigh integration benefits. Lowest upfront cost positions attract capital-constrained buyers.
- API-integrated Platforms:Middleware-dependent architectures connect to EHRs through vendor-specific interfaces rather than open standards.
- Legacy Software:Proprietary protocol systems from pre-FHIR eras persist through sunk cost rationalization and staff retraining avoidance.
Interoperable Systems leads procurement preference; API-integrated Platforms expands fastest as EHR incumbents open connectivity layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States health systems where interoperability investments command premium valuations, while European markets absorb compliance premiums from MDR and GDPR layering that compress vendor margins.
United States
Integrated delivery networks prioritize ONC interoperability certification and FDA software-as-a-medical-device compliance in procurement decisions. Epic Systems Corporation leverages its dominance in hospital electronic health records to extend into perioperative workflows. Academic medical centers in Boston and the Research Triangle pilot edge-deployed AI inference engines for surgical duration prediction.
Germany
University hospitals in Baden-Württemberg and Bavaria drive demand for RFID-enabled instrument traceability supporting EU MDR quality management audits. The country's notified body relationships concentrate innovation capacity among platforms with existing certification infrastructure. Stuttgart's medical technology cluster anchors hardware-software integration investments across surgical navigation suites.
United Kingdom
NHS trusts in London and the Midlands consolidate vendor relationships around platforms demonstrating cross-facility data continuity. GDPR data localization constraints complicate centralized cloud infrastructure for multi-national hospital chains. Manchester's health innovation district pilots predictive coordination platforms that anticipate resource conflicts before scheduling failures cascade.
Japan
Metropolitan Tokyo hospitals deploy comprehensive perioperative suites integrating scheduling, documentation, and analytics across multiple surgical service lines. PMDA software-as-a-medical-device guidance tightens validation requirements for surgical workflow tools. Osaka's medical device corridor sustains R&D intensity in clinical informatics connecting pre-operative planning to intraoperative execution.
India
Corporate hospital chains in Maharashtra and Karnataka expand adoption of cloud-based perioperative platforms as subscription economics align with capital-constrained operating models. CDSCO medical device regulations add compliance layers for platforms serving multi-national hospital chains. Hyderabad's health technology cluster attracts private equity-backed surgery center rollups negotiating enterprise SaaS terms.
Operating Room Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in narrow workflow automation niches. The vendor base stratifies between electronic health record incumbents with embedded OR modules and best-of-breed surgical workflow vendors competing on predictive capabilities. Three archetypes dominate: EHR-extended platforms, hardware-anchored suites, and cloud-native SaaS specialists. Competitive moves concentrate on strategic partnerships for FHIR certification acceleration and modular AI feature decoupling to navigate European MDR reclassification.
Among EHR-anchored platform providers, Epic Systems Corporation and Oracle Corporation occupy positions where hospital installed bases create switching friction. GE Healthcare and Koninklijke Philips N.V. exemplify the hardware-software integration archetype, leveraging imaging and surgical navigation equipment relationships to anchor perioperative suite deployments. These four entities represent the consolidation pressure facing specialized surgical workflow vendors competing against incumbents with pre-cleared quality management systems and existing notified body relationships.
| Leading Market Players |
|---|
| Surgical Information Systems |
| Veradigm LLC |
| Picis Clinical Solutions, Inc. |
| GE Healthcare |
| Oracle Corporation |
| Koeninklijke Philips N.V. |
| Getinge AB |
| Epic Systems Corporation |
| Steris Corporation |
| Others |
Pricing and Supply Chain Analysis
FDA software-as-a-medical-device validation chokepoints determine both pricing tier spreads and supply chain shape, compressing margins for vendors lacking pre-cleared quality management systems while concentrating procurement power among integrated delivery networks with compliance-ready vendor rosters.
Pricing Analysis
Integrated delivery networks anchor pricing structures around subscription-based SaaS tiers that bundle implementation services into per-case consumption models. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with full interoperability certification from modular point solutions and legacy on-premise installations. Cost compression in the economy tier is intensifying because ambulatory surgical centers negotiate enterprise terms through private equity-backed rollups. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with sterilization compliance mandates show lowest.
Supply Chain Analysis
Export-control restrictions on edge-deployed AI inference engines and FHIR-native middleware limit technology flows from United States developers to European and Asian health systems. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscaler regions in Virginia, Frankfurt, and Mumbai. Single-source vulnerability rests on concentrated hyperscaler dependencies for containerized microservices deployment. Distribution runs through direct enterprise sales teams serving hospital systems and channel partners reaching ambulatory surgical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States integrated delivery networks consolidating vendor relationships around interoperability-certified platforms, fragmenting procurement options for smaller surgical facilities into SaaS subscription tiers.
For Market Incumbents: Build regulatory certification moats through accelerated FDA software-as-a-medical-device pre-clearance investments that cloud-native entrants cannot replicate without 18-24 month quality management system audits. Deepen backward integration into edge AI inference hardware to control surgical duration prediction performance. Anchor channel control through exclusive GPO contracts with multi-hospital systems. For New Entrants and Emerging Players: Build out white-space presence in pre-operative to intraoperative informatics convergence, the least penetrated segment distinct from scheduling-dominated Epic Systems and Oracle Corporation strongholds. Target ambulatory surgical centers in India and Southeast Asia where subscription economics align with capital-constrained operating models. Pursue channel partnerships with medical device distributors possessing existing surgeon relationships. For Investors and Strategic Acquirers: European Medical Device Regulation Class IIa/IIb reclassification reshapes the acquisition landscape, concentrating viable targets among platforms with existing notified body relationships and modular AI architectures that can be decoupled for separate certification. Long-term viability favors vendors with cloud-native microservices stacks and FHIR-native interoperability. Monitor FDA enforcement patterns on software-as-a-medical-device validation timelines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Acceleration | ONC interoperability certification compresses deployment timelines for United States health systems. |
| Modular AI Feature Decoupling | Separately certifiable components navigate European MDR reclassification without core platform disruption. |
| Edge Inference Engine Deployment | Academic medical centers in Boston pilot surgical duration prediction outside cloud latency constraints. |
| ASC Rollup Enterprise Negotiation | Private equity-backed surgery center networks bundle implementation into per-case SaaS pricing. |
| Hardware-Software Integration Deepening | GE Healthcare and Philips anchor perioperative suite deployments through imaging equipment relationships. |
Research Methodology
Cross-validation between primary interviews with perioperative informatics officers, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) filings, ONC certification databases, hospital procurement records, and CMS Medicare cost reports anchors the qualitative findings. Bottom-up triangulation from ambulatory surgical center SaaS subscription disclosures and top-down reconciliation against integrated delivery network capital expenditure patterns validates market sizing.
Calibration against historical adoption curves for cloud-based healthcare IT platforms and anesthesia machine integration deployment timelines shapes the projection framework. Segmentation dimensions modeled include deployment architecture, end-user facility type, integration complexity tier, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to interoperability mandate compliance deadlines and SaaS conversion rates. Surgical duration prediction algorithm accuracy improvements and RFID instrument traceability mandate compliance costs serve as industry-specific forecast inputs.
Stress conditions across FDA enforcement intensity, European MDR audit backlogs, and hyperscaler infrastructure pricing volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability certification timelines and cloud migration acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Global Dermatology EMR Software Market