
 Global Pharmaceutical Quality Management Software Market | 2026-2036
Global Pharmaceutical Quality Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Quality Management Software Market Foresight
Mid-sized biopharma firms are rotating toward integrated quality suites as their primary procurement archetype, displacing the previous dominance of large enterprise buyers who once dictated vendor roadmaps. Veeva Vault Quality dominates cloud-native quality infrastructure for life sciences, leveraging its platform architecture to anchor multi-product deployments across R&D and commercial operations. MasterControl competes through deep manufacturing execution integrations, while Qualio specializes in serving emerging biotechs with streamlined, pre-validated SaaS configurations.
Pharmaceutical quality management software comprises configurable digital platforms that enforce GxP compliance through automated document control, audit trail generation, and risk-based CAPA workflows, with systems typically requiring FDA 21 CFR Part 11-compliant electronic signatures and data integrity safeguards. Cloud-based deployment now leads solution type adoption as biopharma firms prioritize remote accessibility and reduced validation overhead, while on-premise configurations retain footholds among generics manufacturers with legacy infrastructure investments. Document control and CAPA management represent the most mature application areas with established vendor competition, whereas supplier quality modules are attracting fastest-growing demand as pharmaceutical outsourcing to contract manufacturers intensifies.
FDA enforcement of data integrity guidance, EMA's MDR transition timelines, and China's NMPA digital submission mandates collectively reshape product requirements and procurement urgency across three major regulatory jurisdictions. ISO 13485 and ICH Q10 standards further compress vendor differentiation to validation-ready, audit-defensible system architectures. Stakeholders must monitor evolving regulator expectations around AI-assisted quality decision-making and determine whether current platform investments accommodate forthcoming algorithmic transparency requirements.
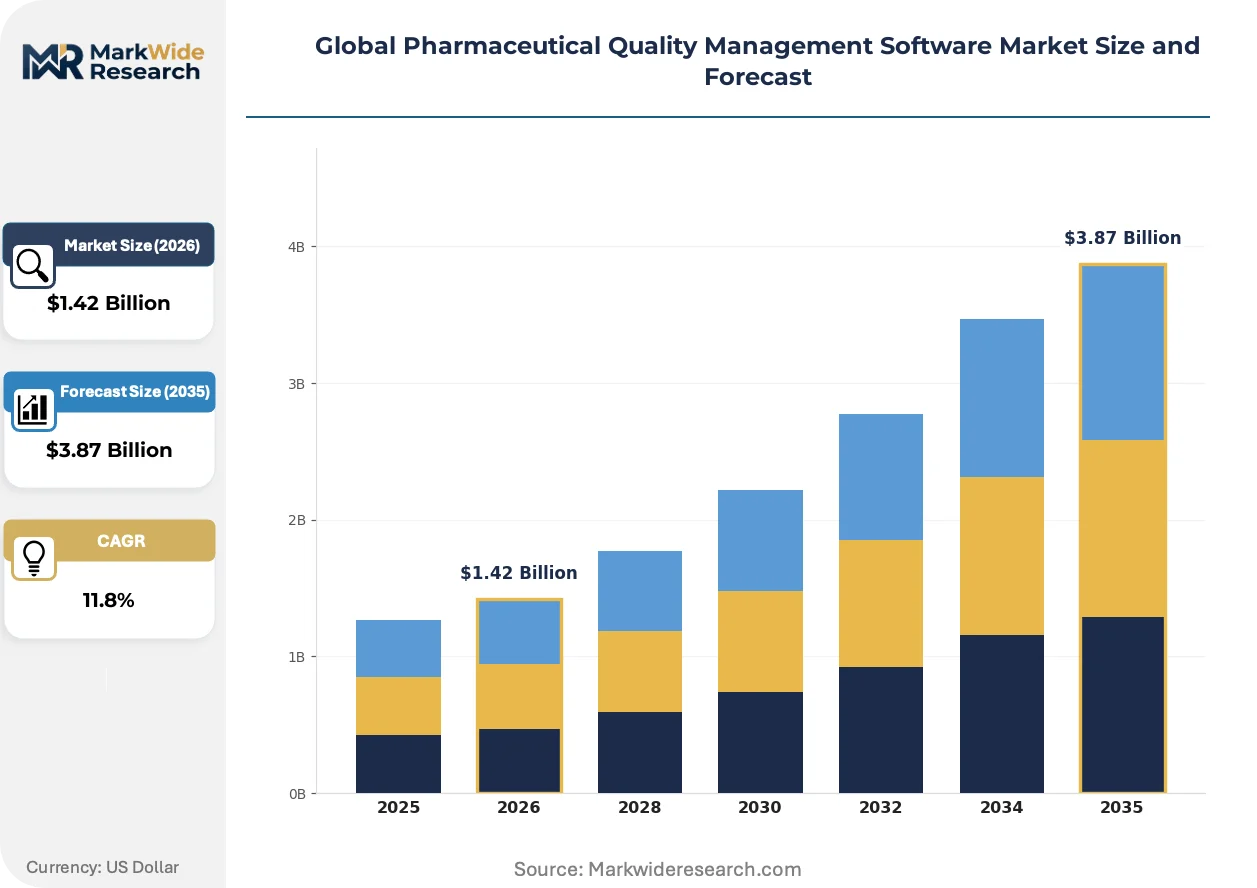
Market Dynamics
Cloud migration is compressing validation timelines while FDA 21 CFR Part 11 enforcement and EU MDR compliance deadlines force simultaneous system overhauls across quality, manufacturing, and clinical operations.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates compel replacement of paper-based quality systems with validated digital platforms across GxP environments.
- Contract Research Organizations:Multi-site clinical trial expansion drives centralized quality workflow standardization and remote audit capabilities.
- EU MDR transition:Stricter post-market surveillance requirements accelerate CAPA system upgrades and technical documentation digitization.
Market Restraints
- Validation cost structure:FDA-compliant software validation consumes 40-60% of total implementation spend, extending payback periods for mid-tier buyers.
- Legacy infrastructure lock-in:Generics manufacturers with sunk capital in on-premise ERP systems face high switching costs and data migration risk.
- Specialized talent scarcity:Qualified validation engineers and GxP auditors command premium compensation, constraining deployment velocity.
Strategic Opportunities
- India biopharma expansion:CDSCO digital submission mandates and PLI scheme incentives create first-mover advantage for cloud-native quality platform vendors.
- Supplier quality modules:Pharmaceutical outsourcing to contract manufacturers intensifies demand for integrated vendor qualification and audit management capabilities.
- AI-assisted decision-making:Regulator guidance on algorithmic transparency in quality risk assessment opens new product differentiation vectors.
Industry Challenges
- Data integrity remediation:FDA warning letter citations for ALCOA+ violations force costly retrospective validation of historical electronic records.
- Multi-system integration:Quality management platforms must synchronize with LIMS, MES, and ERP environments without creating audit trail fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Quality Management Software Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Document Control, Audit Management, Risk Management, Training Management, Change Control Deployment Mode: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Application Area: Compliance Tracking, CAPA Management, Supplier Quality, Product Release, Incident Management End User: Contract Research Organizations, Biopharma Firms, Generics Manufacturers, Medical Device Makers |
| Companies Covered | QT9 QMS, ComplianceQuest, MasterControl, AssurX, Propel Software, Veeva Vault Quality, Qualio, Dot Compliance, TrackWise Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Quality Management Software Market Shifts & Advancements
Platform architecture is consolidating around API-first designs that enable modular quality suite expansion, while regulatory pressure accelerates the shift from document-centric to data-centric compliance models.
Artificial intelligence is bifurcating quality decision workflows between predictive risk scoring and prescriptive CAPA recommendations. Large biopharma enterprises deploy machine learning for deviation pattern recognition across global manufacturing networks. This capability compression is forcing mid-market vendors to choose between partnership strategies and proprietary AI development investments.
EMA's MDR enforcement timelines are compressing technical documentation update cycles from annual to continuous review. Manufacturers must maintain real-time design history file accessibility for notified body inspections. Small-to-mid device companies face the steepest compliance cost escalation, driving consolidation toward integrated quality-regulatory platforms.
Subscription pricing models are displacing perpetual license structures across emerging biotech procurement. Venture-backed firms prioritize operating expense flexibility over capital asset ownership during clinical development phases. This preference shift is most pronounced in Boston and San Diego biotech clusters, where quality headcount constraints favor fully managed SaaS deployments.
Global Pharmaceutical Quality Management Software Market Segmentation
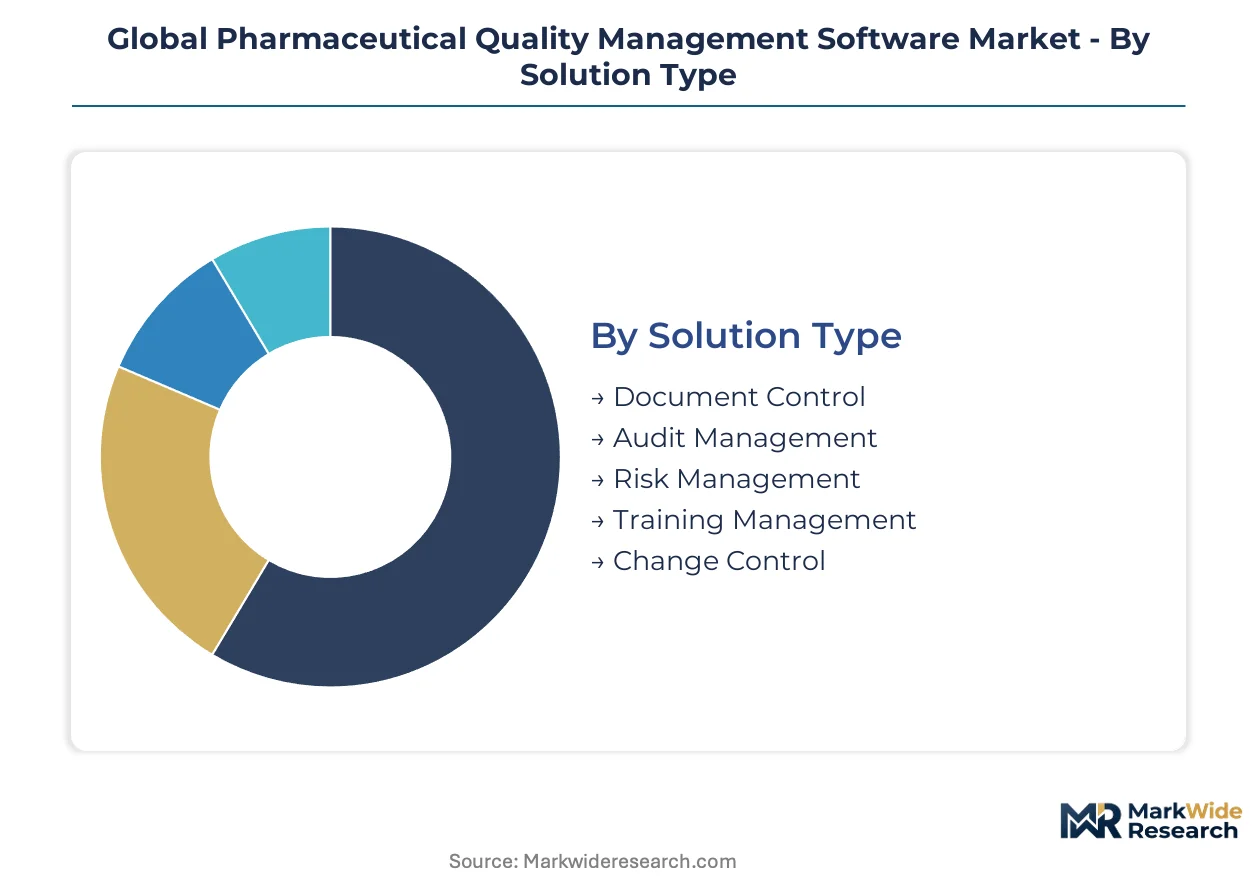
Regulatory complexity fragments procurement patterns across the pharmaceutical quality software landscape. Vendors must architect modular platforms that accommodate divergent compliance maturity levels and infrastructure constraints simultaneously.
Solution Type:
FDA 21 CFR Part 11 and EU MDR impose distinct functional requirements that reshape how quality modules are bundled and validated.
- Document Control:Core module governing version management, electronic signatures, and audit trails for SOPs, batch records, and regulatory submissions. Biopharma firms in the United States drive replacement demand as legacy paper systems face FDA enforcement pressure for ALCOA+ compliance.
- Audit Management:Schedules inspections, tracks findings, and automates response workflows across internal and external audit cycles. Contract Research Organizations expanding multi-site clinical operations in India and Germany concentrate procurement here to standardize remote audit capabilities.
- Risk Management:Enables FMEA and risk-based CAPA prioritization aligned with ICH Q10 guidelines.
- Training Management:Tracks personnel qualification, competency assessments, and curriculum compliance for GxP roles.
- Change Control:Governs deviation handling, corrective actions, and post-implementation verification protocols.
Document Control handles the majority of throughput; Audit Management is expanding most quickly on share.
Deployment Mode:
Cost tier stratification separates enterprise buyers from emerging biotechs with constrained validation budgets.
- Cloud-Based:Multi-tenant infrastructure with shared security and compliance certifications reducing customer validation burden. Biopharma clusters in Boston and Basel favor this model for rapid deployment without capital infrastructure commitments.
- SaaS:Fully managed subscription delivery with vendor-maintained validation documentation and continuous compliance updates. Venture-backed firms in San Diego and Cambridge concentrate here to preserve operating expense flexibility during clinical phases.
- On-Premise:Self-hosted installations retaining data sovereignty for manufacturers with legacy ERP integration requirements.
- Hybrid:Combines cloud accessibility for distributed teams with on-premise data residency for regulated records.
- Private Cloud:Dedicated tenant environments offering isolation without full infrastructure ownership.
Cloud-Based carries the largest installed base; SaaS is climbing the fastest on new procurement share.
Application Area:
Application maturity correlates directly with regulatory enforcement history and audit citation patterns.
- CAPA Management:Corrective and preventive action workflows with root cause analysis, effectiveness checks, and trend reporting. Generics manufacturers in India face CDSCO pressure to digitize CAPA systems following FDA warning letter patterns for deviation handling.
- Supplier Quality:Vendor qualification, audit scheduling, and performance scorecarding for contract manufacturing networks. Pharmaceutical outsourcing to Chinese and Korean CMOs intensifies demand for integrated supplier oversight capabilities.
- Compliance Tracking:Real-time monitoring of regulatory submission status and inspection readiness metrics.
- Product Release:Automated batch disposition against specification and documentation completeness checks.
- Incident Management:Adverse event capture, investigation workflows, and regulatory reporting for pharmacovigilance.
CAPA Management anchors the largest workflow volume; Supplier Quality is gaining share fastest as outsourcing accelerates.
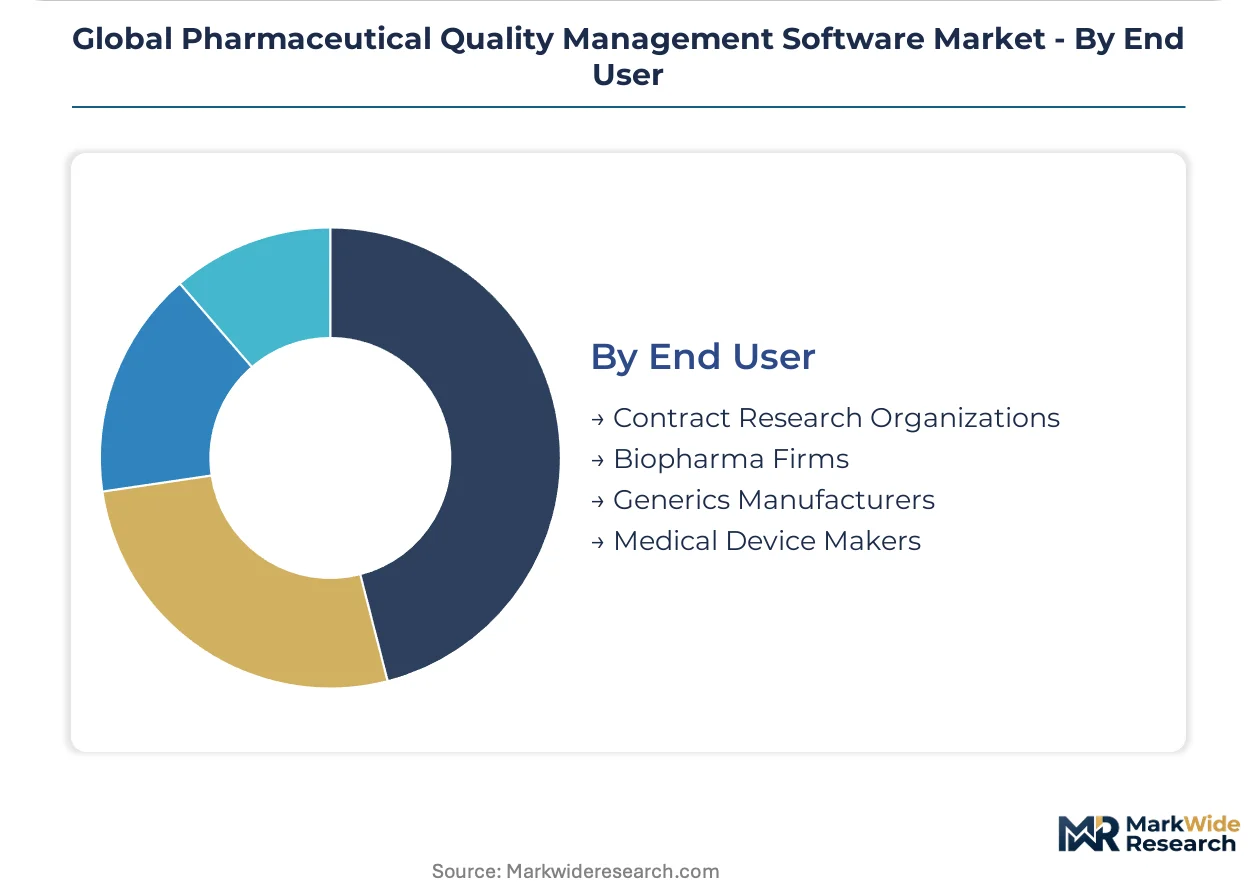
End User:
Customer type determines pricing tolerance, implementation timeline pressure, and integration complexity requirements.
- Biopharma Firms:Full-spectrum quality platforms spanning R&D through commercial manufacturing with enterprise-grade scalability. Large headquarters concentrations in the United States and Switzerland drive premium procurement for integrated quality-regulatory suites.
- Contract Research Organizations:Standardized multi-site deployments requiring remote accessibility and centralized oversight. IQVIA, Parexel, and Syneos Health operations across the United Kingdom, Singapore, and Poland concentrate demand for cloud-native standardization.
- Generics Manufacturers:Cost-constrained implementations prioritizing core document control and batch release capabilities.
- Medical Device Makers:ISO 13485-aligned systems with design history file management and post-market surveillance integration.
Biopharma Firms command the largest contract values; Contract Research Organizations are expanding procurement fastest on volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise biopharma firms in the United States drive the largest contract values, while mid-sized buyers in Germany and emerging biotech clusters in India concentrate procurement growth. Regulatory enforcement timelines across FDA, EMA, and CDSCO compress implementation windows simultaneously.
United States
FDA 21 CFR Part 11 enforcement and ALCOA+ data integrity mandates compel replacement of legacy paper systems across GxP environments. The 2024 FDA warning letter surge for electronic record violations accelerates validation-ready platform procurement. Boston and San Diego biotech clusters favor fully managed SaaS deployments to preserve operating expense flexibility during clinical phases.
Germany
EMA MDR transition deadlines and notified body inspection intensity drive technical documentation digitization for medical device manufacturers. The country's national pharmaceutical regulator enforces continuous design history file accessibility requirements. Stuttgart and Munich industrial corridors concentrate demand for integrated quality-regulatory platforms serving ISO 13485-aligned device makers.
Switzerland
Swissmedic inspection protocols and cross-border manufacturing oversight requirements elevate audit trail defensibility standards. Basel's biopharma headquarters cluster anchors premium procurement for multi-site quality standardization across R&D and commercial operations. Swiss firms prioritize cloud-native architectures that accommodate both EU MDR and FDA dual-compliance workflows.
India
CDSCO digital submission mandates and PLI scheme incentives create first-mover opportunity for cloud-native quality platform vendors. The national pharmaceutical regulator's adoption of FDA warning letter patterns for deviation handling pressures generics manufacturers toward CAPA digitization. Hyderabad and Ahmedabad manufacturing belts concentrate supplier quality module demand as contract manufacturing outsourcing intensifies.
United Kingdom
Post-Brexit MHRA recognition agreements and divergent UKCA marking requirements fragment validation documentation standards. London and Cambridge biotech clusters concentrate emerging firm procurement for streamlined SaaS configurations with reduced validation overhead. CRO operations across Oxford and Manchester drive centralized quality workflow standardization for multi-site clinical trials.
Global Pharmaceutical Quality Management Software Market Competitive Landscape
Player mix skews toward cloud-native specialists with pre-validated SaaS architectures, displacing previous dominance of legacy on-premise incumbents. Market structure exhibits tiered consolidation around three strategic archetypes: enterprise platform consolidators, mid-market vertical specialists, and emerging biotech-focused configurators. Dominant competitive moves include API-first modular expansion and partnership strategies for AI-assisted quality decision-making capabilities.
Within the cloud-native specialist tier, Veeva Vault Quality, MasterControl, and Qualio anchor distinct positioning vectors. Veeva Vault Quality exemplifies enterprise platform consolidation through multi-product deployments spanning R&D and commercial operations. MasterControl occupies a position emphasizing manufacturing execution integrations for validated production environments. Qualio represents the emerging biotech-focused archetype with streamlined, pre-validated SaaS configurations designed for venture-backed firms with constrained quality headcount. These three companies collectively illustrate how vendor differentiation compresses toward validation-ready, audit-defensible system architectures under intensifying regulator scrutiny.
| Leading Market Players |
|---|
| QT9 QMS |
| ComplianceQuest |
| MasterControl |
| AssurX |
| Propel Software |
| Veeva Vault Quality |
| Qualio |
| Dot Compliance |
| TrackWise Digital |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 validation requirements gate both vendor qualification and price differentiation simultaneously, compressing procurement timelines while stratifying cost tiers across deployment models. Cloud-native SaaS configurations command premium positioning through pre-validated architectures that reduce customer implementation burden, while on-premise alternatives compete on total cost of ownership for generics manufacturers with sunk infrastructure investments.
Pricing Analysis
Current-generation cloud-native SaaS platforms price at substantial premiums over prior-generation on-premise licenses, while next-generation AI-augmented quality suites are beginning to test value-based structures. Subscription pricing stratifies across premium, standard, and economy tiers anchored by validation depth and integration complexity. Cost compression in the standard tier intensifies as mid-market vendors compete for emerging biotech procurement. Venture-backed firms in Boston and San Diego exhibit highest price sensitivity, prioritizing operating expense flexibility over feature depth.
Supply Chain Analysis
Just-in-time deployment preferences dominate among biopharma firms seeking rapid validation cycles, though strategic stockpiling of compliance documentation persists among generics manufacturers facing CDSCO enforcement waves. Software development concentrates in the United States, Ireland, and India, with quality engineering talent pools anchoring vendor location decisions. Platform architectures rest on API-first modular designs, cloud infrastructure from hyperscalers, and pre-configured validation templates. Single-source vulnerability in specialized GxP auditor talent constrains deployment velocity. Distribution runs through direct enterprise sales for large biopharma, channel partners for mid-market penetration, and self-service onboarding for emerging biotechs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in pharmaceutical quality management hinge on API ecosystem interoperability, with vendor consolidation accelerating around architectures that synchronize quality, manufacturing, and clinical data layers without audit trail fragmentation.
For Market Incumbents: Compound defensive positioning through backward integration into validation services and captive AI development for predictive CAPA capabilities. Cloud-native specialists face margin pressure from hyperscaler partnerships that commoditize infrastructure layers. Certification investment in dual FDA-EMA compliance architectures preserves pricing power in Swiss and German headquarters markets. For New Entrants and Emerging Players: Differentiate on pre-validated SaaS configurations designed for venture-backed biotechs with zero quality headcount. Supplier quality modules for Indian and Korean contract manufacturing networks represent the most penetrable whitespace. Go-to-market execution should anchor on channel partnerships with CROs standardizing multi-site deployments. For Investors and Strategic Acquirers: EU MDR enforcement timelines reshape the acquisition landscape toward integrated quality-regulatory platforms with continuous technical documentation capabilities. Long-term viability favors vendors with audit-defensible system architectures and established FDA 21 CFR Part 11 compliance track records. Acquisition targets should demonstrate validation-ready deployments across three or more regulatory jurisdictions. The signal to watch is CDSCO digital submission mandate acceleration pressuring Indian generics manufacturers toward CAPA digitization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable seamless LIMS-MES-ERP synchronization without audit fragmentation. |
| Strategic Partnership | Hyperscaler alliances reduce infrastructure costs while accelerating FDA 21 CFR Part 11 certification cycles. |
| Acquisition of Specialist Firm | AI-assisted quality decision-making capabilities differentiate predictive risk scoring from prescriptive CAPA recommendations. |
| Geographic Expansion | India biopharma clusters offer first-mover advantage as CDSCO mandates drive CAPA digitization urgency. |
| Product Launch | Supplier quality modules capture fastest-growing demand as pharmaceutical outsourcing to contract manufacturers intensifies. |
Research Methodology
Initial hypotheses were tested against primary input from quality assurance directors, regulatory affairs leads, validation engineers, and CRO operations managers and refined through secondary validation. Primary fieldwork combined structured interviews with enterprise biopharma procurement teams and emerging biotech executives alongside channel partner discussions. Secondary sources encompassed FDA warning letter databases, EMA MDR submission trackers, CDSCO digital mandate circulars, and vendor validation documentation repositories. Bottom-up deployment estimates across customer segments were triangulated against top-down market sizing from software spend disclosures.
Variance decomposition across the projection horizon isolates growth contributions from regulatory enforcement intensity, cloud migration velocity, and AI capability adoption. Segmentation dimensions modeled include deployment mode, organization size, application area maturity, and regional regulatory cluster. CAGRs were derived from slope analysis of validated deployment timelines and procurement cycle compression patterns. Industry-specific forecast inputs incorporate FDA 21 CFR Part 11 enforcement wave timing and EU MDR notified body inspection capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement pressure or accelerated cloud infrastructure maturation would require recalibration. Forecasts reflect documented assumptions regarding validation timeline compression and mid-market vendor consolidation trajectories. Specific risk factors include ALCOA+ data integrity remediation costs, specialized talent scarcity, and multi-system integration complexity. Practitioners should keep alternative scenarios live as CDSCO digital submission mandates and AI transparency guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Hand Hygiene Monitoring System Market