
 Radiation Dose Optimisation Software Market | 2026-2036
Radiation Dose Optimisation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Dose Optimisation Software Market Outlook
The capital-intensity divergence between full-platform vendors and point-solution developers is reorganizing competitive dynamics across radiation dose management. GE Healthcare leverages embedded AI dose-tracking modules within its imaging hardware ecosystem to lock in hospital system contracts. Siemens Healthineers sustains R&D intensity across dual pipelines for diagnostic and interventional dose monitoring. Fujifilm Holdings Corporation specializes in retrofit analytics tools that integrate with heterogeneous imaging fleets in mid-tier diagnostic centers.
Radiation dose optimisation software encompasses algorithmic platforms that calculate, monitor, and reduce patient exposure during CT, fluoroscopy, and nuclear medicine procedures using Monte Carlo simulation engines and organ-dose mapping against reference levels. The software's primary commercial purpose is enabling compliance with diagnostic reference levels while preserving image quality for clinical confidence. Diagnostic software currently anchors the product portfolio as the most mature revenue stream, while cloud-based deployment configurations represent the fastest-expanding segment due to enterprise IT consolidation mandates. Analytics tools command premium pricing where machine-learning modules predict cumulative lifetime exposure across repeat-patient populations.
The FDA enforces diagnostic reference level reporting under the Mammography Quality Standards Act framework, while the EU Medical Device Regulation requires clinical evidence dossiers for software-as-medical-device classifications. The International Commission on Radiological Protection maintains exposure limits that national regulators transpose into licensure conditions for imaging facilities. Stakeholders must monitor whether emerging FDA guidance on adaptive AI in dose modulation triggers premarket submission requirements for self-learning algorithms.
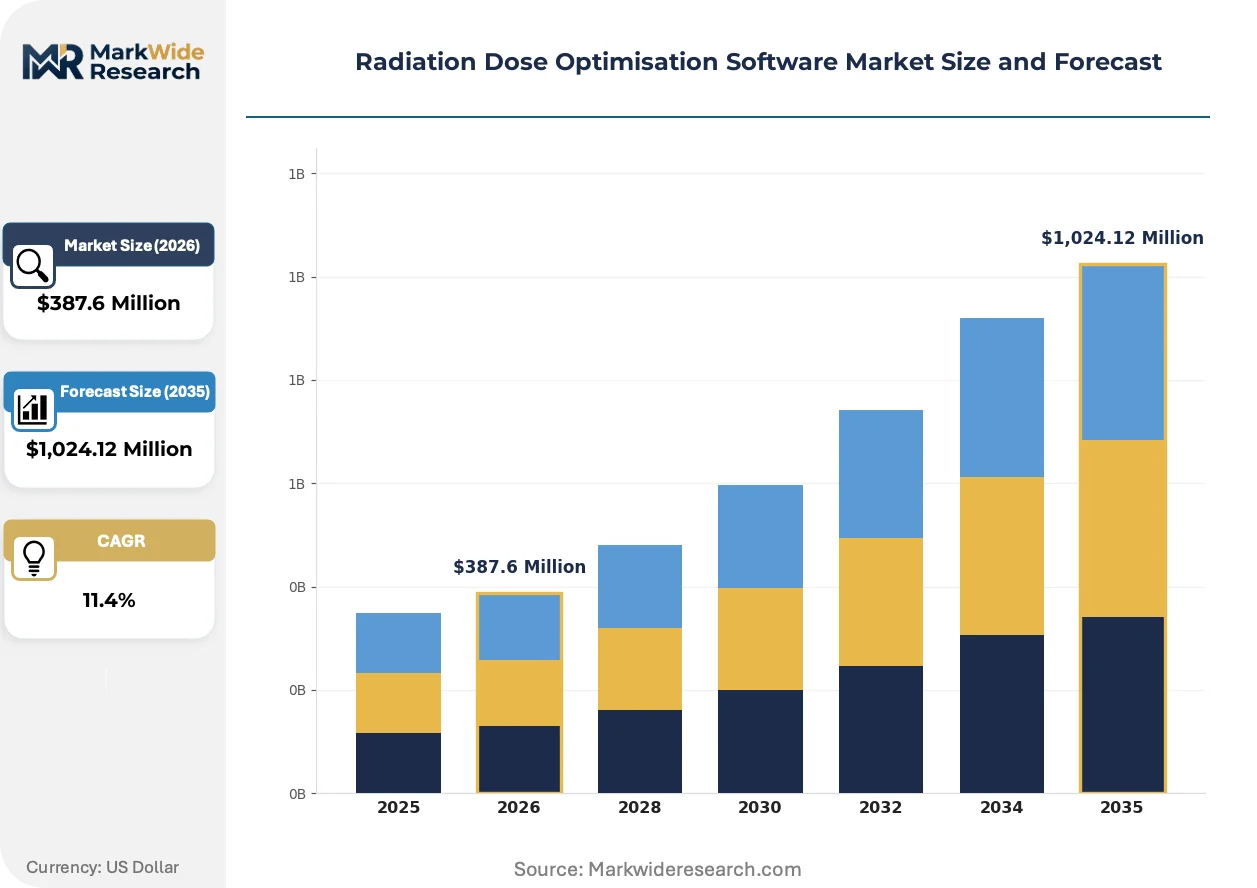
Market Dynamics
Diagnostic imaging volume expansion across tertiary care networks is compressing dose accountability timelines, forcing software vendors to embed real-time monitoring directly into radiology workflow engines rather than operate as standalone retrospective tools.
Growth Catalysts
- EU Medical Device Regulation:Clinical evidence dossier mandates for software-as-medical-device classifications are accelerating procurement of validated dose tracking platforms across European hospital systems.
- CT protocol standardization:Automated exposure modulation algorithms integrated into scanner consoles are generating demand for interoperable analytics that aggregate dose data across heterogeneous device fleets.
- Interventional cardiology expansion:Fluoroscopy-guided structural heart procedures are proliferating in Japan and Germany, creating installed bases requiring cumulative dose surveillance for repeat-patient populations.
Market Restraints
- Cloud infrastructure concentration:Enterprise IT consolidation mandates are tethering mid-tier diagnostic centers to hyperscaler platforms with limited interoperability for legacy PACS architectures.
- Monte Carlo licensing costs:Proprietary simulation engine royalties from physics software houses are inflating per-seat pricing for organ-dose mapping modules.
- FDA premarket pathway uncertainty:Ambiguity surrounding adaptive AI dose modulation algorithms is extending development timelines for self-learning exposure prediction tools.
Strategic Opportunities
- India diagnostic network buildout:Private imaging chains in tier-2 cities lack integrated dose tracking, creating whitespace for cloud-native retrofit analytics with minimal capital footprint.
- Nuclear medicine theranostics:Lutetium-177 and actinium-225 radioligand therapies are generating demand for patient-specific dosimetry software that calculates absorbed dose to tumor and organs at risk.
- ISO 27001 certification:Health data security frameworks are becoming procurement gatekeepers, favoring vendors with pre-certified information management systems.
Industry Challenges
- Medical physics workforce scarcity:Qualified professionals capable of validating organ-dose calculations against anthropomorphic phantom data are concentrated in academic medical centers.
- Legacy DICOM integration:Heterogeneous imaging fleets in multi-site health systems require custom middleware development to normalize dose structured reports across vendor-specific formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Dose Optimisation Software Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Software, Treatment Planning Systems, Workflow Management, Analytics Tools Application: Radiology, Oncology, Cardiology, Nuclear Medicine End User: Hospitals, Diagnostic Centers, Imaging Clinics, Research Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Bayer AG, Sectra AB, Fujifilm Holdings Corporation, Varian Medical Systems, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Dose Optimisation Software Market Strategic Shifts
Artificial intelligence is restructuring how exposure prediction models are trained, deployed, and regulated across radiology departments, compressing the gap between acquisition and actionable dose feedback.
Deep learning-based organ segmentation is displacing atlas-based methods for automated dose mapping in CT examinations. Academic medical centers in the United States are piloting these neural architectures for pediatric chest protocols. The technology is displacing manual contouring workflows that previously required 15-20 minutes per examination, collapsing quality assurance bottlenecks.
The FDA's emerging guidance on adaptive AI in dose modulation is requiring premarket submission pathways for algorithms that modify exposure parameters in real-time. Device manufacturers must now compile clinical evidence dossiers demonstrating non-inferiority in image quality metrics. Interventional fluoroscopy systems face the steepest compliance burden given the dynamic nature of procedure-specific exposure curves.
Subscription-based analytics procurement is replacing perpetual license models among mid-tier diagnostic networks. Chief information officers are prioritizing operational expenditure structures that bundle software maintenance, security patching, and regulatory update cycles. This shift is most visible in German outpatient imaging chains where quarterly compliance reporting obligations favor predictable cost structures over capital-intensive ownership.
Radiation Dose Optimisation Software Market Segmentation
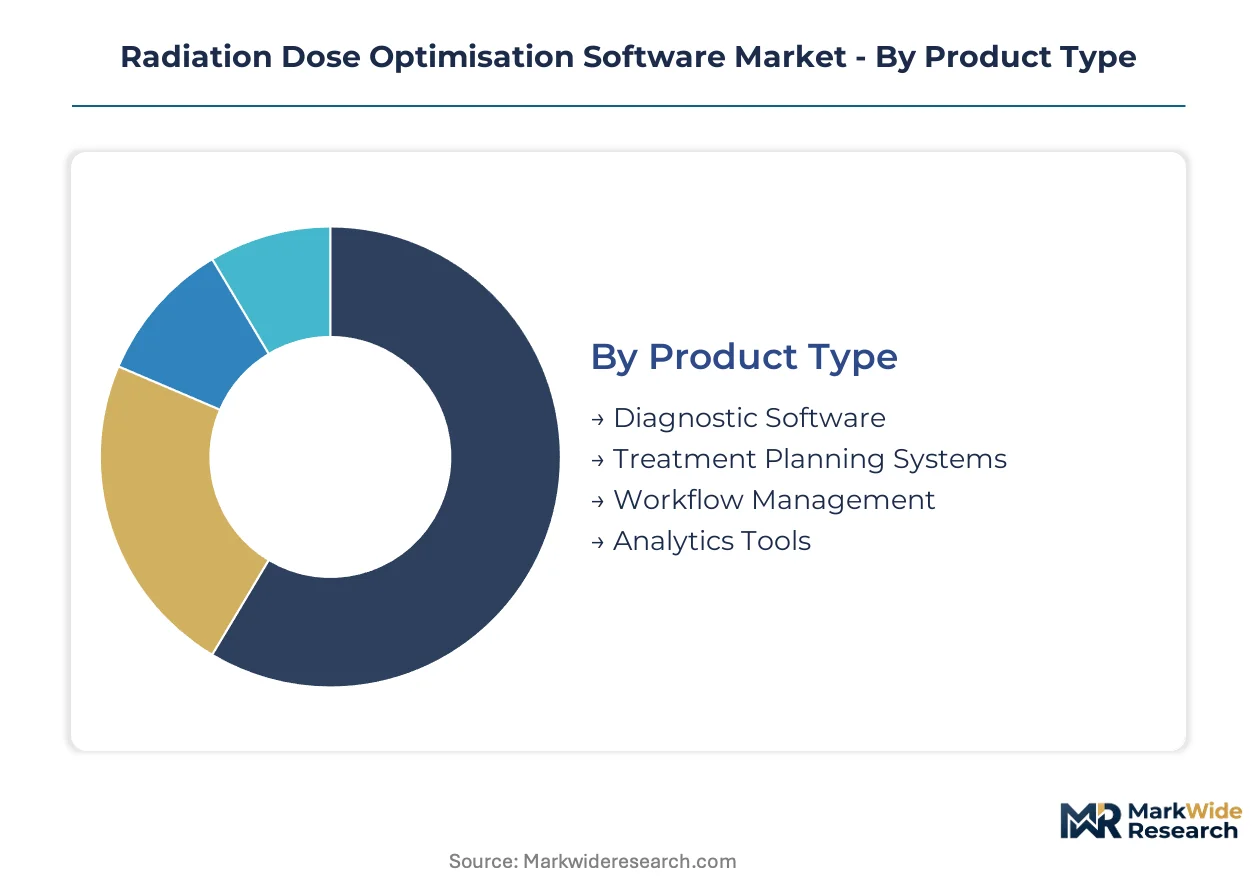
Radiation dose optimisation software segments slice across clinical workflow depth, infrastructure maturity, and regulatory exposure. Procurement patterns diverge sharply between capital-rich hospital systems and lean diagnostic networks, forcing vendors to architect tiered product strategies.
Product Type:
Geographic demand spreads unevenly: diagnostic software concentrates in domestic hospital systems with established compliance frameworks, while analytics tools track toward export-led growth in emerging diagnostic networks.
- Diagnostic Software:Monte Carlo simulation engines calculate patient-specific organ doses against reference levels in real-time. Demand clusters in United States academic medical centers where FDA diagnostic reference level mandates compress accountability timelines. The software embeds directly into CT and fluoroscopy consoles, locking in hardware ecosystem contracts.
- Analytics Tools:Machine-learning modules predict cumulative lifetime exposure across repeat-patient populations using longitudinal dose structured reports. German outpatient imaging chains favor these for quarterly compliance reporting under EU Medical Device Regulation dossier requirements. Cloud-native architectures reduce capital footprint for mid-tier networks.
- Treatment Planning Systems:Patient-specific dosimetry platforms for radiotherapy and theranostics.
- Workflow Management:Integration middleware normalizing dose data across heterogeneous imaging fleets.
Diagnostic software commands the established base. The steepest expansion runs through analytics tools.
Application:
Cost tiering separates high-complexity interventional applications from standardized diagnostic protocols, with reimbursement differentials driving procurement priority.
- Radiology:CT protocol standardization and automated exposure modulation dominate installed bases. Japanese tertiary networks deploy these for high-volume chest and abdominal examinations where cumulative population dose surveillance is mandatory. Integration with PACS workflow engines determines vendor selection.
- Cardiology:Fluoroscopy-guided structural heart procedures generate dynamic exposure curves requiring real-time monitoring. German and Japanese interventional suites lead procurement as transcatheter valve replacement volumes climb. Adaptive AI dose modulation faces FDA premarket pathway uncertainty, extending development timelines.
- Oncology:External beam planning and brachytherapy dose verification systems.
- Nuclear Medicine:Lutetium-177 and actinium-225 radioligand therapy dosimetry.
Radiology holds the dominant revenue share. Cardiology is climbing the fastest as structural heart procedure volumes accelerate.
End User:
Customer type stratification aligns with IT consolidation mandates: enterprise health systems demand embedded platforms while independent centers seek retrofit solutions.
- Hospitals:Tertiary care networks require enterprise-grade platforms with real-time monitoring embedded directly into radiology workflow engines. United States health systems prioritize FDA-validated dose tracking for Mammography Quality Standards Act compliance. Siemens Healthineers and GE Healthcare compete for multi-year system contracts.
- Diagnostic Centers:Mid-tier outpatient imaging chains in Germany favor subscription-based procurement bundling maintenance, security patching, and regulatory updates. Cloud deployment configurations reduce upfront capital requirements. ISO 27001 certification functions as a procurement gatekeeper.
- Imaging Clinics:Small-format facilities with limited physics support staff.
- Research Institutions:Academic medical centers piloting deep learning-based organ segmentation for pediatric protocols.
Hospitals anchor current revenue concentration. Diagnostic centers are expanding most quickly as outpatient imaging chains proliferate.
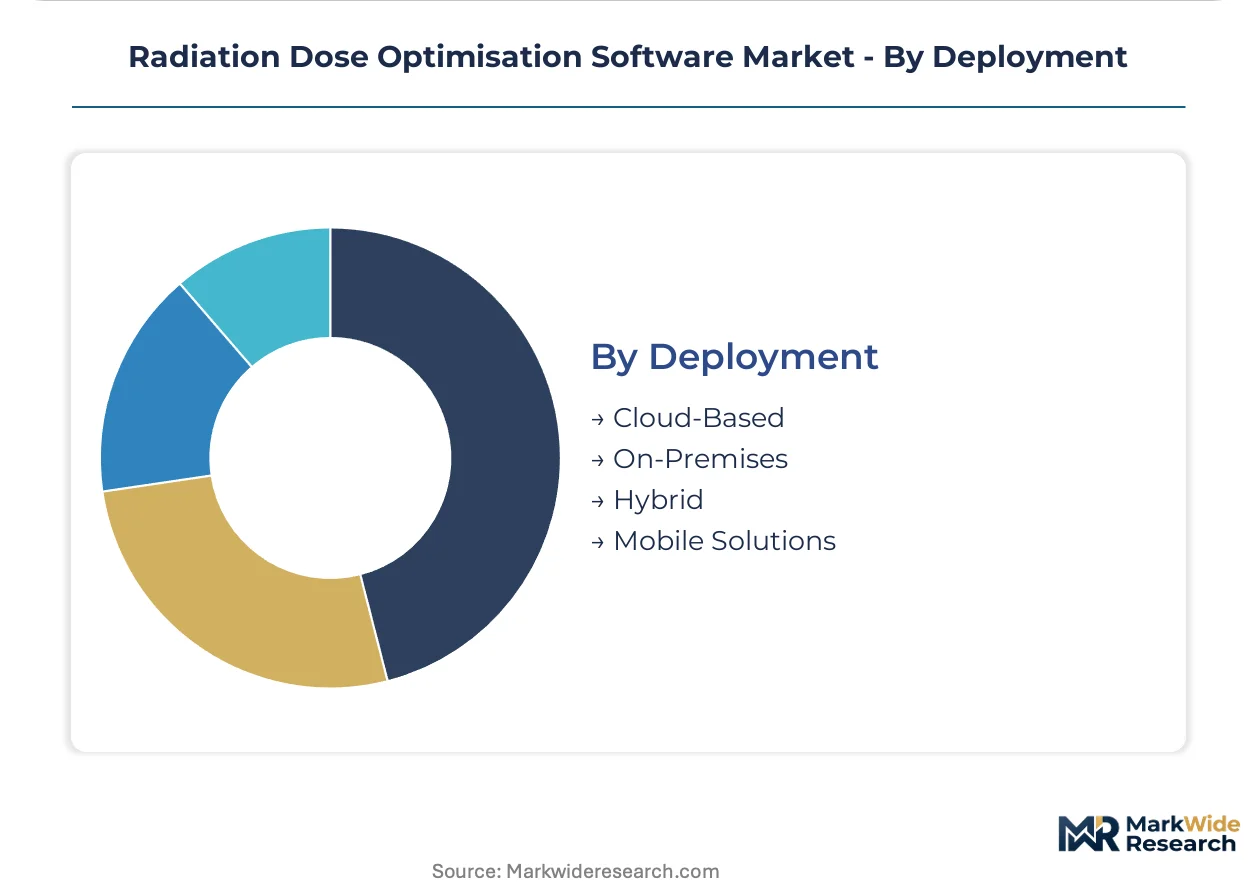
Deployment:
Volume concentration favors cloud architectures where enterprise IT consolidation mandates are restructuring procurement patterns across mid-tier networks.
- Cloud-Based:Enterprise IT consolidation mandates are tethering diagnostic centers to hyperscaler platforms with subscription-based operational expenditure structures. German outpatient chains lead adoption for predictable cost management under quarterly compliance reporting obligations. Limited interoperability with legacy PACS architectures constrains penetration in heterogeneous fleets.
- On-Premises:Tertiary hospital systems with dedicated IT infrastructure and stringent data sovereignty requirements retain perpetual license models. United States academic medical centers favor these for deep learning organ segmentation pilots where training data sensitivity demands local control. Higher total cost of ownership limits expansion.
- Hybrid:Mixed architectures bridging edge processing with cloud analytics.
- Mobile Solutions:Point-of-care dose verification for interventional suites.
On-premises deployments retain the installed base. Cloud-based configurations are gaining share fastest as operational expenditure models displace capital-intensive ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic centers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium analytics tools under strict regulatory mandates. Mid-tier networks in India and outpatient chains in the United States exhibit acute sensitivity, favoring subscription models that minimize capital exposure.
United States
Academic medical centers in Boston and the Research Triangle drive demand for deep learning-based organ segmentation pilots. FDA diagnostic reference level mandates under the Mammography Quality Standards Act compress procurement cycles for validated dose tracking. Tertiary networks in California and Texas embed real-time monitoring directly into radiology workflow engines.
Germany
Outpatient imaging chains across Bavaria and North Rhine-Westphalia favor subscription-based analytics bundling maintenance and regulatory updates. EU Medical Device Regulation dossier requirements for software-as-medical-device classifications accelerate procurement of validated platforms. Interventional suites in Munich and Hamburg lead fluoroscopy-guided structural heart procedure volumes.
Japan
Metropolitan hospital networks in Tokyo and Osaka deploy CT protocol standardization for high-volume chest and abdominal examinations. Cumulative population dose surveillance obligations under national radiological protection guidelines mandate enterprise-grade tracking. Interventional cardiology expansion in Nagoya and Fukuoka generates installed bases requiring repeat-patient dose surveillance.
India
Private imaging chains in tier-2 cities across Maharashtra and Karnataka lack integrated dose tracking infrastructure. Cloud-native retrofit analytics with minimal capital footprint address whitespace in diagnostic network buildout. Hyderabad and Chennai clusters pilot ISO 27001-certified platforms as procurement gatekeepers tighten.
Radiation Dose Optimisation Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the radiation dose management space. Full-platform vendors with embedded hardware ecosystems command premium positioning in tertiary hospital systems. Point-solution developers and retrofit analytics specialists compete on deployment flexibility for mid-tier diagnostic networks. Dominant competitive moves include strategic partnerships with imaging equipment manufacturers and portfolio diversification into cloud-native subscription models.
Among diversified healthcare technology conglomerates, GE Healthcare, Siemens Healthineers, and Fujifilm Holdings Corporation exemplify contrasting strategic positions. GE Healthcare anchors the embedded-platform archetype through hardware-integrated dose-tracking modules. Siemens Healthineers occupies a position spanning diagnostic and interventional monitoring pipelines. Fujifilm Holdings Corporation represents the retrofit-specialist tier, targeting heterogeneous imaging fleets in cost-constrained environments.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| Bayer AG |
| Sectra AB |
| Fujifilm Holdings Corporation |
| Varian Medical Systems |
| Agfa-Gevaert Group |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification functions as a procurement gatekeeper that simultaneously filters qualified suppliers and stratifies price premiums across deployment tiers. Buyers in German outpatient chains absorb higher subscription rates for certified platforms while tier-2 diagnostic centers in India face exclusion from enterprise contracts without compliance investment.
Pricing Analysis
After-sales revenue from bundled maintenance, security patching, and regulatory update cycles now drives lifetime value exceeding initial license fees. Three-tier pricing structure across premium, standard, and economy levels separates embedded-platform contracts from cloud-native retrofit solutions. Cost compression in mid-tier analytics stems from hyperscaler platform consolidation. Diagnostic centers in India exhibit acute price sensitivity, while German hospital systems demonstrate lowest elasticity under EU Medical Device Regulation mandates.
Supply Chain Analysis
Just-in-time software delivery dominates deployment architecture, though Monte Carlo simulation engine licensors maintain strategic stockpiles of physics calculation modules. Supply concentrates in the United States, Germany, and Japan for core algorithm development, with cloud infrastructure sourcing from Ireland and Singapore for data sovereignty compliance. Proprietary simulation royalties from physics software houses inflate component costs. Single-source vulnerability runs through Monte Carlo licensing concentration. Distribution runs through direct enterprise sales and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation dose optimisation software sits in early-cycle expansion as diagnostic imaging volumes climb worldwide and regulatory mandates tighten dose accountability timelines across installed CT and interventional radiology bases.
For Market Incumbents: Consolidate hardware ecosystem lock-in through embedded AI dose-tracking modules that tether multi-year hospital system contracts. Deepen vertical integration into Monte Carlo simulation engines to capture organ-dose mapping margins currently flowing to physics software licensors. Counter cloud-native retrofit specialists by accelerating FDA validation pathways for adaptive AI dose modulation algorithms. For New Entrants and Emerging Players: ISO 27001 fast-track certification opens procurement channels previously gated to established vendors. Private imaging chains in India's tier-2 cities present the most penetrable whitespace, lacking integrated dose tracking infrastructure amid diagnostic network buildout. Cloud-native deployment with minimal capital footprint and subscription-based operational expenditure structures offers the clearest go-to-market angle against perpetual-license incumbents. For Investors and Strategic Acquirers: FDA guidance on adaptive AI in dose modulation reshapes the acquisition landscape by extending development timelines for self-learning algorithms and elevating clinical evidence requirements. Long-term viability favors platform-agnostic analytics specialists with proven interoperability across heterogeneous imaging fleets. Watch for FDA premarket submission volume inflection as signal for regulatory barrier height and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Premarket validation for adaptive AI dose modulation algorithms compresses competitive timelines for real-time exposure prediction tools. |
| CE Marking Pathway | EU Medical Device Regulation dossier compliance accelerates procurement across German outpatient imaging chains under quarterly reporting mandates. |
| Hospital System Partnership | Multi-year enterprise contracts with United States tertiary networks embed dose tracking into radiology workflow engines. |
| Software Companion Development | Interoperable analytics modules integrate with legacy PACS architectures in mid-tier diagnostic centers. |
| Reimbursement Strategy | Diagnostic reference level compliance documentation supports payer accountability frameworks in Japan and Germany. |
Study Parameters
The analysis maps diagnostic software, analytics tools, treatment planning systems, and workflow management middleware, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and medical physicists. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EU MDR databases, hospital procurement records, and CMS Medicare data. Bottom-up sizing of installed imaging bases triangulates against top-down regulatory mandate penetration rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application specialty, end-user facility tier, and deployment architecture. CAGRs derive from regression analysis of historical imaging volume expansion correlated with regulatory compliance obligation intensity. Forecast inputs incorporate CT protocol standardization adoption curves and interventional cardiology procedure volume trajectories.
Decision-makers should treat outputs as directional under base assumptions of sustained diagnostic imaging volume growth and stable regulatory enforcement intensity; material deviation would warrant model refresh. Revision becomes warranted when FDA adaptive AI guidance triggers premarket submission thresholds or when cloud infrastructure interoperability constraints ease substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Patient Access Solutions Market