
 Europe Pharmaceutical Market | 2026-2036
Europe Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Market Intelligence
Continuous bioprocessing is reconfiguring how active pharmaceutical ingredients are manufactured across European facilities. Novo Nordisk leverages its Danish insulin fermentation expertise to anchor supply of GLP-1 therapies. Roche sustains leadership in oncology biologics through its Basel-based R&D and manufacturing infrastructure. Sanofi competes on vaccine scale, operating multi-product facilities in France and Belgium that supply both European and export markets.
Europe pharmaceutical encompasses chemically synthesized and biologically derived medicinal products formulated for disease prevention, diagnosis, or treatment, with specifications ranging from small-molecule purity thresholds to monoclonal antibody glycosylation profiles. The industry serves hospitals, retail pharmacies, and increasingly homecare settings where patients self-administer chronic therapies. Prescription drugs occupy the dominant value share, while biologics represents the fastest-expanding margin pool as biosimilar competition intensifies. Oncology commands the largest therapy area investment, with injectable delivery modes capturing premium pricing due to cold-chain complexity and sterility requirements.
EMA's centralized marketing authorization procedure shapes product access across all EU member states, while the EU AI Act introduces compliance obligations for algorithm-driven drug discovery platforms. The F-Gas Regulation constrains inhalation product propellant choices, forcing reformulation investments by respiratory specialists. Stakeholders must monitor how the EU Green Deal's pharmaceutical manufacturing emissions targets will reshape capital allocation toward continuous flow chemistry and solvent recovery systems.
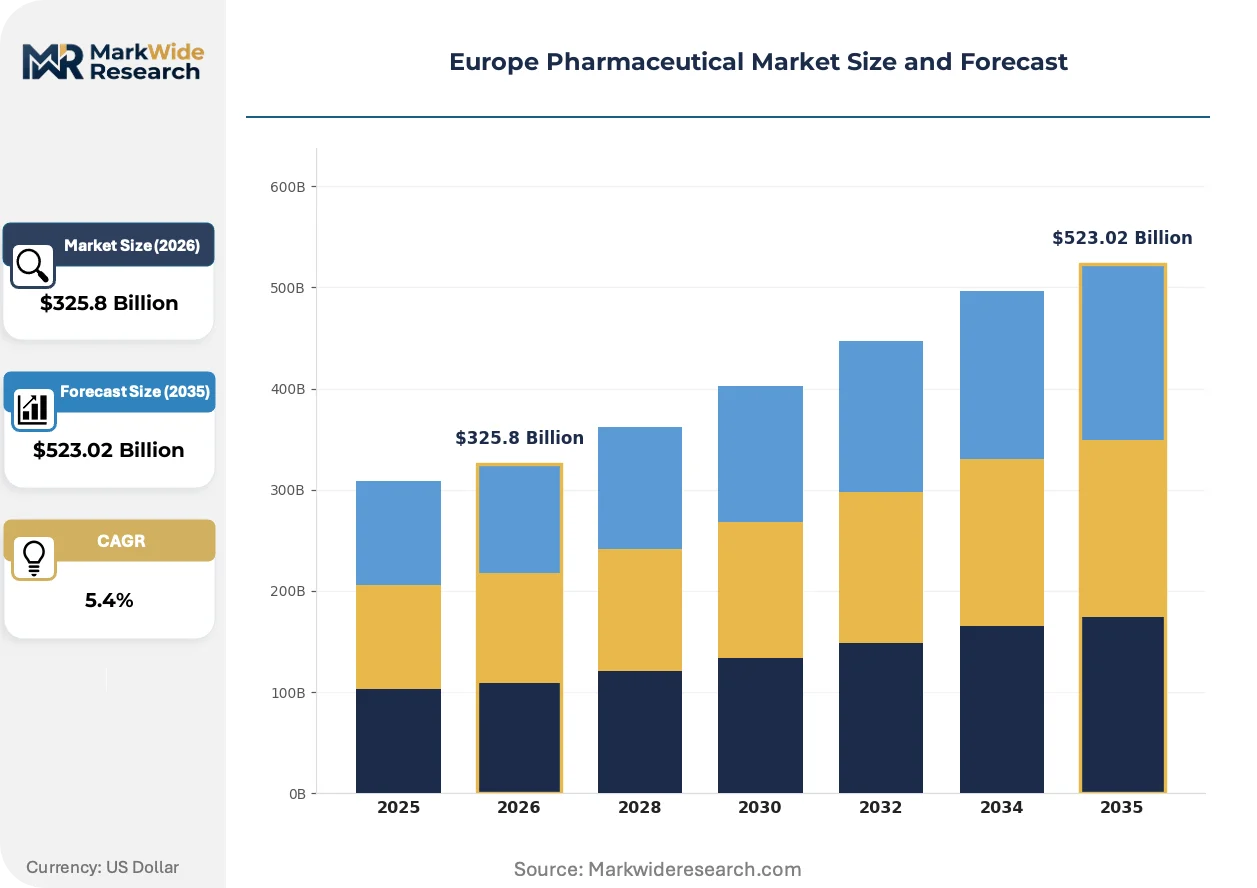
Market Dynamics
Continuous bioprocessing is compressing batch cycle times across European active pharmaceutical ingredient facilities while EMA's serialization mandates force wholesale infrastructure replacement ahead of Falsified Medicines Directive deadlines.
Growth Catalysts
- EMA Centralized Marketing Authorization:Single regulatory pathway accelerates cross-border product launches across all 27 EU member states, reducing time-to-revenue for novel biologics.
- GLP-1 therapy demand:Danish insulin fermentation clusters are expanding capacity to supply peptide-based diabetes and obesity treatments into hospital and retail pharmacy channels.
- EU Green Deal manufacturing targets:Emissions caps on pharmaceutical production are redirecting capital toward continuous flow chemistry and solvent recovery installations.
Market Restraints
- F-Gas Regulation constraints:Inhalation product propellant restrictions are forcing respiratory specialists into costly reformulation cycles with limited alternative chemistries.
- Cold-chain complexity:Injectable biologics require temperature-controlled distribution infrastructure that concentrates supply risk in specialized logistics providers.
- API import dependence:European finished dose manufacturers rely on Asian-sourced starting materials, creating vulnerability to customs delays and quality disputes.
Strategic Opportunities
- Homecare self-administration:Chronic therapy delivery is shifting from hospital infusion centers to patient-managed subcutaneous injections in Germany, France, and the UK.
- EU AI Act compliance services:Algorithm-driven drug discovery platforms need validation frameworks, creating advisory revenue for specialized consultancies.
- Biosimilar manufacturing scale:Patent expirations on reference biologics are opening contract manufacturing slots for monoclonal antibody copy products.
Industry Challenges
- Serialization system integration:Track-and-trace hardware must interface with legacy enterprise resource planning platforms across multi-site manufacturing networks.
- Glycosylation analytical talent:Characterization of monoclonal antibody carbohydrate structures requires scarce mass spectrometry specialists concentrated in Basel and Cambridge clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Market |
| Market Size in 2026 | $325.8 Billion |
| Market Size in 2035 | $523.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generics Delivery Mode: Injectables, Oral, Topical, Transdermal Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Diseases End User: Hospitals, Pharmacies, Research Institutions, Homecare |
| Companies Covered | Sanofi, Novo Nordisk, Roche, Takeda, Bayer, Novartis, GSK, Ipsen, AstraZeneca, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Market Strategic Shifts & Innovations
Digitization of quality control and manufacturing execution systems is compressing release timelines while regulatory pressure on environmental footprint accelerates process chemistry reinvention across European production sites.
Digital twin technology is virtualizing pharmaceutical manufacturing operations by creating real-time simulation replicas of bioreactor performance and downstream purification trains. Contract manufacturing organizations in the Rhine-Main cluster are deploying these systems to predict batch deviations before they occur. The technology is virtualizing traditional scale-up protocols that previously required physical pilot runs, cutting development timelines for sterile injectables.
The EU AI Act introduces conformity assessment obligations for machine learning models used in candidate molecule screening and clinical trial patient stratification. Pharmaceutical sponsors must now document algorithmic training data provenance and decision interpretability before EMA submission. Early-phase biotechnology developers in the Netherlands and Sweden are restructuring discovery workflows to embed audit trails from project inception.
Hospital procurement consortia are consolidating biologics purchasing power through tender aggregation platforms that reverse traditional supplier-negotiated contracts. Germany's university hospital networks and France's regional health agencies are channeling oncology antibody demand through centralized electronic auctions. This concentration is most advanced in the UK, where NHS England's specialized commissioning framework sets maximum acceptable prices for CAR-T and gene therapies before market access negotiations begin.
Europe Pharmaceutical Market Segmentation
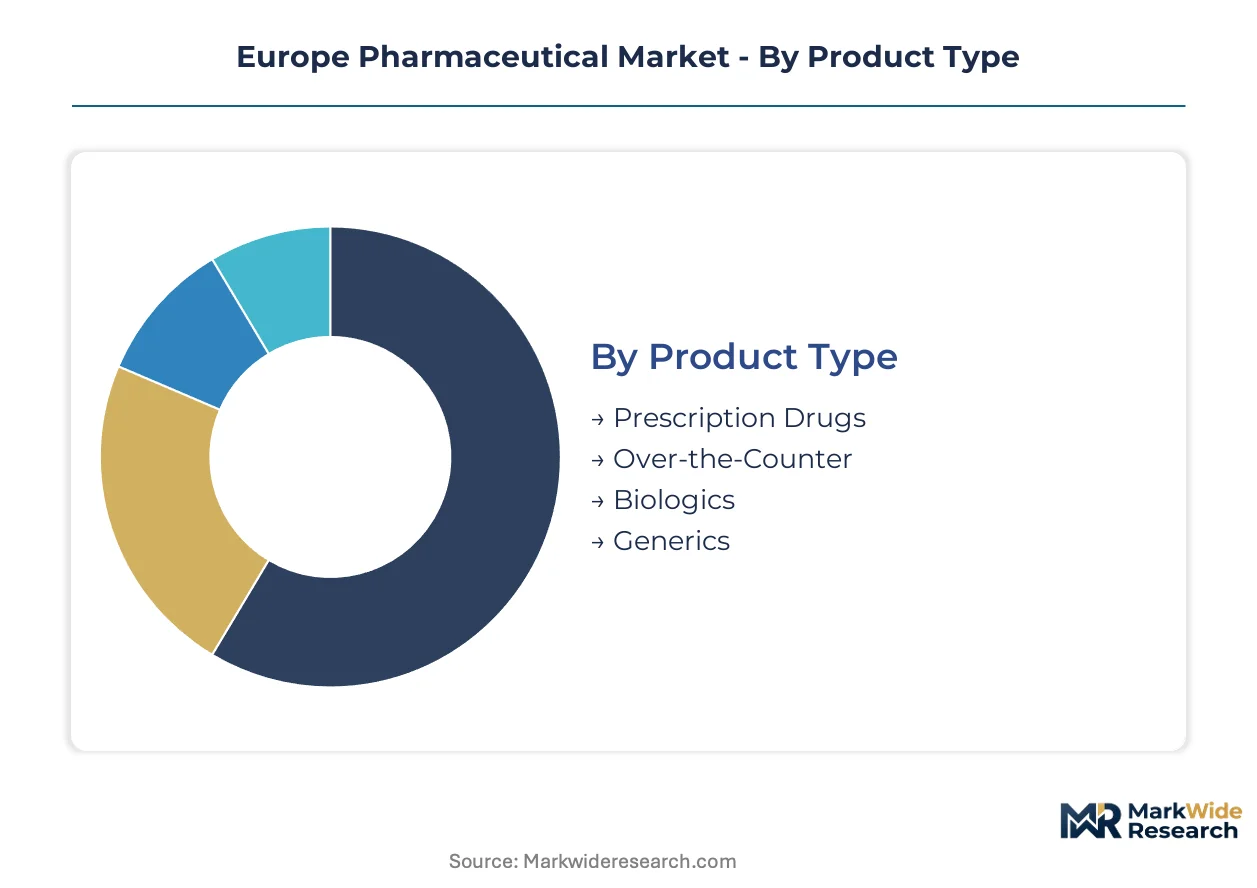
Segmentation across Europe pharmaceutical reveals how therapy complexity, regulatory pathways, and distribution infrastructure shape procurement economics. Understanding these dimensions exposes where margin pools concentrate and where logistics constraints create competitive moats.
Product Type:
Prescription protocols span acute intervention through chronic disease management, with reimbursement status determining patient access tiers across German sickness funds, French social security, and NHS England formularies.
- Prescription Drugs:Chemically synthesized small molecules dominate hospital formularies and retail pharmacy dispensing. German statutory health insurance funds channel the majority of cardiovascular and metabolic therapy procurement through centralized tendering, with reference pricing compressing margins on mature compounds.
- Biologics:Monoclonal antibodies and recombinant proteins command premium reimbursement through EMA centralized authorization pathways. Demand concentrates in oncology centers across the Rhine-Main cluster and Basel region, where cold-chain infrastructure supports temperature-sensitive monoclonal antibody distribution.
- Over-the-Counter:Self-medication products bypass prescription requirements, with pharmacy-only status in Germany contrasting supermarket availability in the UK. Analgesics and gastrointestinal remedies lead volume.
- Generics:Bioequivalent small molecules compete on price through tender aggregation platforms, with French regional health agencies and NHS England driving procurement consolidation.
The dominant share belongs to Prescription Drugs, while Biologics is closing the gap fastest.
Delivery Mode:
Route of administration determines manufacturing complexity, sterility requirements, and distribution infrastructure investment across European production sites.
- Injectables:Parenteral formulations demand aseptic fill-finish capacity and cold-chain logistics. Sterile vials and prefilled syringes supply hospital infusion centers and increasingly homecare settings in France and the UK.
- Oral:Tablets and capsules remain the default for chronic disease maintenance, with high-volume solid dose manufacturing concentrated in Ireland and Germany.
- Topical:Creams, ointments, and ophthalmic preparations serve dermatology and localized therapy needs through retail pharmacy channels.
- Transdermal:Patch-based delivery systems bypass first-pass metabolism for pain management and hormone replacement, requiring specialized adhesive formulation expertise.
Injectables capture the steepest expansion trajectory as biologics shift from hospital to home administration.
Therapy Area:
Disease burden demographics and pipeline investment intensity concentrate R&D and manufacturing capacity across distinct clinical domains.
- Oncology:Immuno-oncology antibodies and targeted small molecules attract the largest development investment. CAR-T manufacturing facilities in Germany and the Netherlands serve centralized NHS England and French regional procurement frameworks.
- Cardiovascular:Anticoagulants and lipid-lowering therapies sustain high prescription volumes through primary care networks, with generic substitution pressures intensifying.
- Neurology:Multiple sclerosis and Alzheimer's disease therapies require specialized distribution to hospital neurology departments and academic medical centers.
- Infectious Diseases:Antibiotic stewardship programs restrict broad-spectrum use, while vaccine production scales at multi-product facilities in France and Belgium.
Oncology leads absolute spending, though Neurology is expanding most quickly as gene therapies advance through EMA assessment.
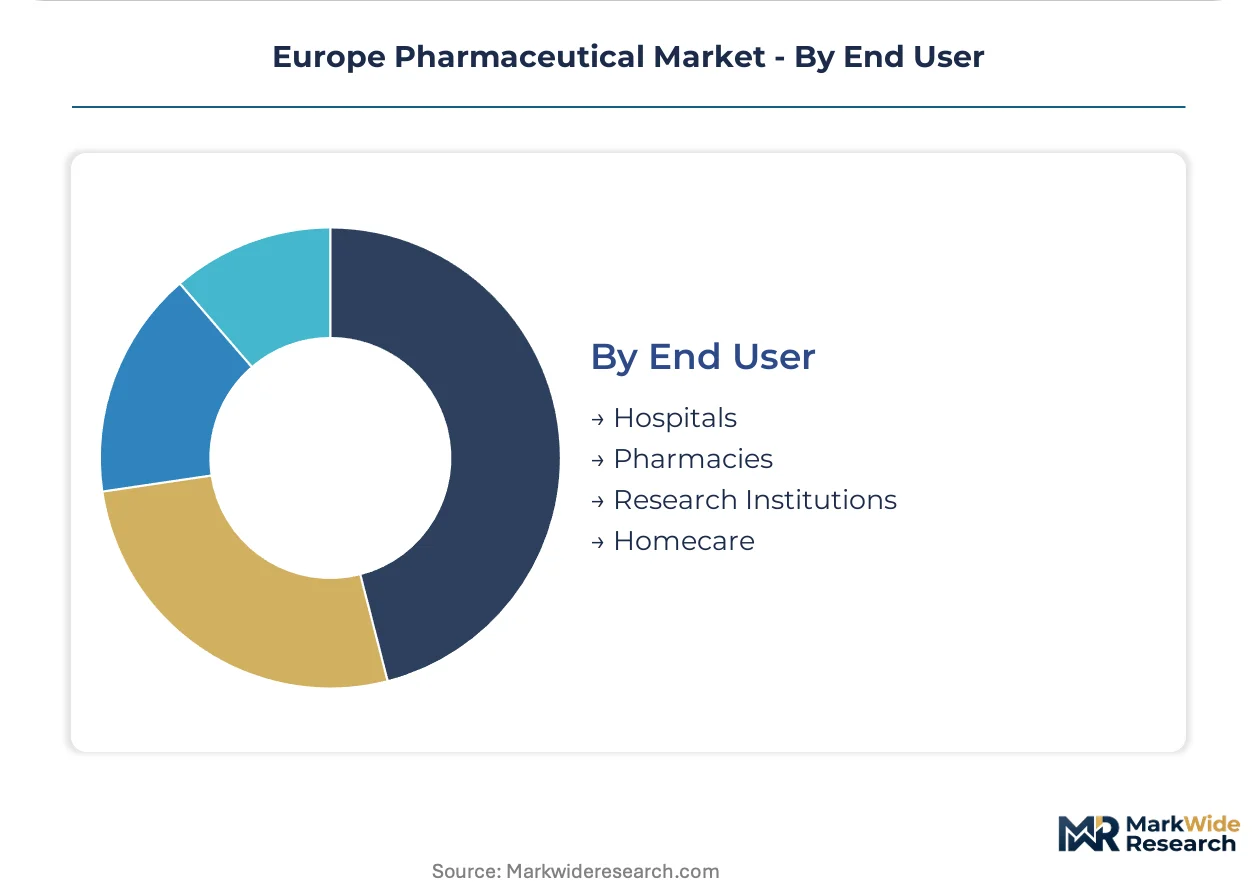
End User:
Patient care settings determine dosing complexity, reimbursement mechanisms, and supply chain service requirements across the value chain.
- Hospitals:Acute care institutions administer infused biologics and parenteral antibiotics through centralized pharmacy operations. German university hospital networks and French public hospitals aggregate purchasing through tender platforms.
- Homecare:Self-administered subcutaneous injections and oral chronic therapies shift patient management from clinical settings to domestic environments, requiring nurse training and patient support programs.
- Pharmacies:Community and hospital outpatient dispensaries handle prescription fulfillment and OTC recommendations, with e-pharmacy growth accelerating in Germany and the Netherlands.
- Research Institutions:Academic medical centers and contract research organizations drive early-phase clinical trial supply and investigator-initiated studies.
Hospitals retain the largest procurement volume, while Homecare is gaining share fastest as chronic therapy administration decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's pharmaceutical trade balance tilts toward finished dose exports while remaining structurally dependent on Asian-sourced active pharmaceutical ingredients. This import vulnerability shapes capital allocation decisions across the continent's manufacturing footprint.
Germany
The Rhine-Main cluster anchors sterile injectable capacity expansion as university hospital networks consolidate biologics procurement through tender aggregation platforms. The country's reference pricing system for statutory health insurance funds compresses margins on mature small-molecule compounds. Hesse-based contract manufacturing organizations are scaling continuous bioprocessing infrastructure to supply peptide-based diabetes therapies.
France
Regional health agencies channel oncology antibody demand through centralized electronic auctions, reversing traditional supplier-negotiated contracts. ANSM oversees marketing authorization compliance alongside EMA centralized procedures. The Paris-Saclay biocluster hosts CAR-T manufacturing facilities serving both domestic hospital networks and export markets through multi-product vaccine sites in the north.
United Kingdom
NHS England's specialized commissioning framework sets maximum acceptable prices for cell and gene therapies before market access negotiations begin. The MHRA operates post-Brexit regulatory pathways that diverge from EMA centralized procedures in accelerated approval timelines. London-Oxford-Cambridge corridor concentration supports early-phase biotechnology developers restructuring discovery workflows for EU AI Act compliance.
Switzerland
Basel-based R&D and manufacturing infrastructure sustains leadership in oncology biologics through specialized glycosylation analytical capabilities. Swissmedic maintains independent marketing authorization procedures that often parallel EMA assessments. The country's insulin fermentation expertise anchors supply chain security for GLP-1 receptor agonist therapies expanding into obesity indications.
Netherlands
Early-phase biotechnology developers in the Randstad region embed audit trails from project inception to meet algorithmic training data provenance requirements under the EU AI Act. The country's logistics infrastructure supports temperature-controlled distribution for monoclonal antibodies shifting from hospital infusion to homecare administration. Eindhoven's health technology cluster converges pharmaceutical manufacturing with digital twin deployment for predictive batch deviation detection.
Europe Pharmaceutical Market Key Industry Players
On the supply side, the industry is consolidating around integrated biologics manufacturers with captive fermentation capacity and specialized fill-finish infrastructure. Tiered competitive positioning separates scale-driven vaccine producers from precision oncology specialists and emerging biosimilar challengers. Three archetypes dominate: vertically integrated Big Pharma with multi-therapy portfolios, mid-cap biotechs with single-asset concentration, and contract manufacturing organizations capturing overflow capacity. Competitive intensity centers on M&A activity targeting gene therapy platforms and sterile injectable capacity expansion in the Rhine-Main corridor.
Among European-headquartered innovators, Roche and Novartis exemplify the integrated research-to-commercialization archetype through Basel-based infrastructure. Novo Nordisk occupies a distinctive position anchoring Danish insulin fermentation clusters that now supply expanded GLP-1 peptide capacity. Sanofi represents the multi-product manufacturing scale archetype through its vaccine and general medicine footprint across France and Belgium.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk |
| Roche |
| Takeda |
| Bayer |
| Novartis |
| GSK |
| Ipsen |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
The Rhine-Main pharmaceutical cluster concentrates sterile injectable capacity expansion, compressing regional manufacturing costs while amplifying pricing leverage for contract manufacturing organizations serving German university hospital networks and French regional health agencies. EMA centralized authorization pathways reinforce this dynamic by consolidating cross-border procurement power among large buyers.
Pricing Analysis
Hospital procurement consortia anchor contract-based long-term offtake structures across European biologics markets. Price differentiation stratifies across EMA-approved originator products, biosimilar alternatives, and unbranded generic small molecules, with tender aggregation platforms intensifying cost compression in mature therapy areas. Reference pricing systems in Germany and NHS England maximum acceptable price frameworks squeeze margins on cardiovascular and metabolic compounds. Small-molecule generics exhibit highest price sensitivity, while CAR-T and gene therapies retain lowest sensitivity due to manufacturing complexity and limited supplier pools.
Supply Chain Analysis
Starting material inputs for European finished dose manufacturers draw predominantly from India and China, creating structural dependence on Asian-sourced active pharmaceutical ingredients and key starting materials. Fermentation-derived peptides, monoclonal antibody cell lines, and synthetic small-molecule intermediates constitute critical feedstock categories. Single-source vulnerability concentrates in specialized glycosylation analytical reagents and cold-chain logistics infrastructure. Distribution runs through temperature-controlled networks anchored by Rhine-Main and Basel regional hubs, with hospital pharmacy consolidation shifting volume toward direct manufacturer arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe pharmaceutical market sits at a platform-economics inflection where tender aggregation platforms and algorithmic procurement systems are displacing traditional supplier-negotiated contracting, with NHS England's specialized commissioning framework and German hospital network consolidation exemplifying this interoperability shift.
For Market Incumbents: Insulate market position by deepening backward integration into peptide fermentation capacity at Danish and Basel-based manufacturing sites, capturing margin from GLP-1 therapy expansion. Secure EMA centralized authorization pathways ahead of EU AI Act compliance deadlines to lock out algorithm-driven discovery competitors. Prioritize serialization system integration investments to maintain wholesale channel access under Falsified Medicines Directive mandates. For New Entrants and Emerging Players: Establish a beachhead in biosimilar manufacturing slots opening through reference biologic patent expirations, particularly in monoclonal antibody copy products. Target contract manufacturing overflow demand in the Rhine-Main corridor where sterile injectable capacity constraints create procurement bottlenecks. Lead with EU AI Act validation services for early-phase biotechnology developers restructuring discovery workflows in the Netherlands and Sweden. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap biotechs with single-asset concentration facing EMA regulatory complexity and capital intensity thresholds. Long-term viability centers on manufacturing scale rather than discovery-stage platforms, with five-to-ten year windows favoring integrated biologics producers. Watch for inflection signals in hospital procurement consortia tender aggregation platform adoption rates across German and French networks.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Scale-Up | Rhine-Main CMOs deploying digital twin technology compress batch cycle times for sterile injectables. |
| EU AI Act Compliance Pathway | Algorithmic training data provenance requirements reshape Netherlands and Sweden discovery workflows. |
| Cold-Chain Infrastructure Partnership | Temperature-controlled distribution networks support monoclonal antibody shift to homecare administration. |
| Biosimilar Manufacturing Slot Acquisition | Patent expirations on reference biologics open contract manufacturing capacity for copy products. |
| Serialization System Integration | Track-and-trace hardware interfacing with legacy ERP platforms secures wholesale channel access under FMD. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary research phases, encompassing drug development executives at Basel and Rhine-Main headquartered firms, regulatory affairs leads navigating EMA centralized procedures, hospital procurement managers at German university networks and French regional health agencies, and formulary directors within NHS England specialized commissioning frameworks. Secondary validation drew from EMA submission databases, ClinicalTrials.gov protocol registrations, hospital procurement tender platforms, and EU regulatory filings. Bottom-up patient population modeling and top-down pharmaceutical spending reconciliation provided analytical triangulation.
Calibration anchored quantitative outputs to historical volume trajectories across the projection horizon, with segmentation modeling spanning therapy area, delivery mode, product type, and regional regulatory cluster dimensions. CAGRs were derived from treatment line penetration curves, dosage form substitution elasticities, and administration route shift patterns. Forecast inputs incorporated GLP-1 therapy demand expansion, biosimilar competitive entry timelines, and cold-chain infrastructure capacity buildout rates.
Sensitivities concentrate around EMA regulatory timeline delays, EU Green Deal manufacturing emissions target acceleration, and Asian API supply disruption scenarios. Cross-checking against EMA centralized authorization approval databases and hospital procurement tender aggregation platform award data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Veterinary Pain Management Drugs Market