
 Healthcare IT Provider Market | 2026-2036
Healthcare IT Provider Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare IT Provider Market Foresight
A shortage of health informaticists with dual clinical-technical training is collapsing implementation timelines across enterprise deployments. Epic Systems Corporation leverages its proprietary interoperability architecture to sustain dominance in large academic medical centers. Oracle Health anchors cloud migration momentum through aggressive infrastructure consolidation. Siemens Healthinerrs competes on imaging-to-informatics integration across radiology and cardiology workflows.
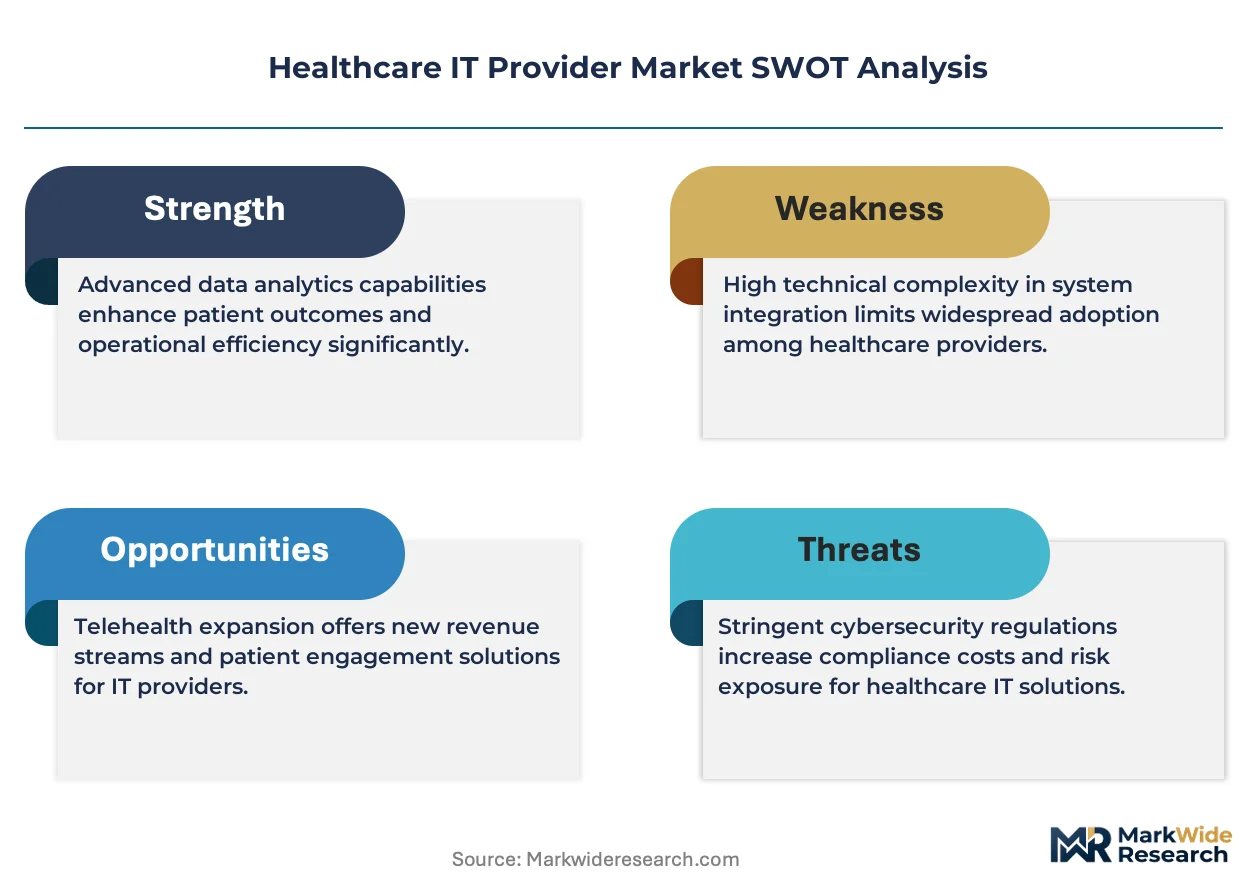
Healthcare IT providers deliver software platforms, data infrastructure, and digital services that manage clinical workflows, financial operations, and patient engagement across care settings. Electronic health records form the core data layer, typically built on HL7 FHIR interoperability specifications, while telehealth solutions extend synchronous and asynchronous care delivery beyond facility walls. Cloud-based deployment is capturing the fastest expansion as hospitals exit capital-intensive on-premise data centers, though hybrid architectures retain share among organizations with legacy system dependencies. Artificial intelligence within the technology stack is attracting disproportionate R&D investment, particularly for clinical decision support and operational forecasting applications.
FDA oversight of software-as-a-medical-device, HIPAA privacy and security mandates, and ONC interoperability certification requirements collectively determine product design priorities and market access conditions for vendors serving US providers. The EU AI Act and MDR framework impose parallel conformity obligations for European deployments, while Japan's PMDA and METI coordinate digital therapeutics and health data governance standards. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of platform architecture and go-to-market sequencing.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around platforms that satisfy ONC interoperability certification and HIPAA security mandates simultaneously, compressing qualification timelines from eighteen months to under nine months for cloud-native entrants.
Growth Catalysts
- ONC 21st Century Cures Act enforcement:Information blocking penalties are compelling health systems to replace legacy EHR modules with FHIR-compliant alternatives, opening replacement cycles across inpatient and ambulatory settings.
- Cloud migration mandates:Hospital CFOs are exiting capital-intensive data center obligations, favoring subscription-based infrastructure that shifts IT expenditure from balance-sheet assets to operating expenses.
- Artificial intelligence integration:Clinical decision support algorithms are attracting disproportionate R&D investment as radiology departments demand automated lesion detection and cardiology units pursue predictive arrhythmia forecasting.
Market Restraints
- Health informaticist shortage:Dual clinical-technical training programs graduate fewer than four thousand specialists annually in the United States, collapsing implementation timelines for enterprise deployments.
- Legacy system dependency:Hybrid architectures retain share among organizations with mainframe-based revenue cycle management, delaying full cloud transitions and fragmenting vendor consolidation.
- FDA software-as-medical-device oversight:Algorithm-based diagnostic tools face extended premarket review pathways, compressing commercialization windows for AI-native entrants against established EHR incumbents.
Strategic Opportunities
- Imaging-to-informatics convergence:Radiology and cardiology workflow integration represents underpenetrated white space for vendors capable of unifying PACS, VNA, and clinical data repositories.
- Telehealth infrastructure permanence:Post-acute care settings and rural health clinics are cementing synchronous virtual visit capabilities as core service lines rather than pandemic contingencies.
- EU AI Act conformity:Early alignment with risk-classification frameworks for clinical decision support systems creates first-mover positioning for European hospital procurement cycles.
Industry Challenges
- Interoperability implementation complexity:HL7 FHIR specification adoption requires mapping thousands of legacy data fields, consuming implementation resources and extending professional services engagements.
- Cybersecurity certification burden:HIPAA security rule audits and state-level breach notification laws demand dedicated compliance infrastructure, diverting engineering talent from product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare IT Provider Market |
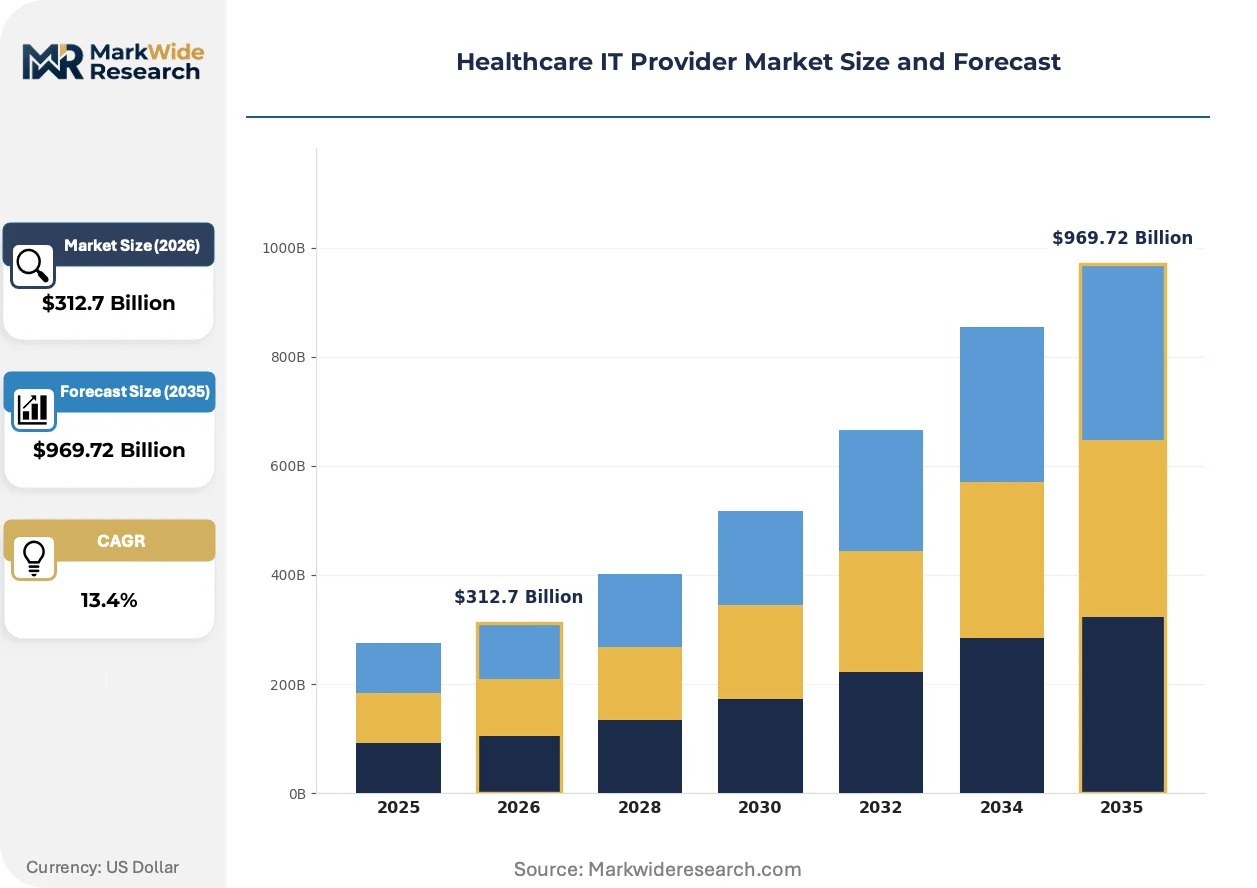
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $969.72 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Telehealth Solutions, Practice Management Software, Medical Billing Software End User: Hospitals, Ambulatory Care Centers, Diagnostics Laboratories, Home Healthcare Providers Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Applications Technology: Interoperability Standards, Artificial Intelligence, Data Analytics, Blockchain |
| Companies Covered | Epic Systems Corporation, Oracle Health, Allscripts Healthcare Solutions, GE Healthcare, Siemens Healthineers, Philips Healthcare, McKesson Corporation, IBM Corporation, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare IT Provider Market Shifts & Advancements
Healthcare IT architecture is fragmenting from monolithic enterprise suites toward composable platforms that allow health systems to swap individual modules without full-stack replacement, accelerating competitive pressure on integrated incumbents.
Microservices-based EHR architecture is decomposing the traditional all-in-one electronic health record into discrete, API-connected components for scheduling, documentation, billing, and clinical decision support. Academic medical centers with substantial internal development capacity are adopting these modular stacks fastest, assembling best-of-breed solutions rather than accepting vendor-defined workflows. This decomposition is compressing switching costs and enabling point-solution vendors to penetrate accounts previously sealed by Epic Systems Corporation and Oracle Health.
The EU AI Act risk-classification framework is imposing conformity assessment obligations on clinical decision support algorithms deployed in European hospitals. Medium-risk diagnostic tools now require notified body review and post-market surveillance systems, extending time-to-revenue for AI-native entrants. German university hospitals and French cancer centers are responding by demanding vendor-provided conformity documentation prior to pilot contracts, filtering supplier pools before procurement initiation.
Hospital supply chain and IT procurement functions are merging under single chief transformation officers, collapsing traditional silos between clinical technology and operational software. Integrated delivery networks in the United States are consolidating vendor negotiations across EHR, ERP, and supply chain platforms, favoring suppliers with cross-functional platform breadth. This concentration is most visible among Catholic health systems and regional Blue Cross-affiliated networks pursuing enterprise-wide standardization.
Healthcare IT Provider Market Segmentation
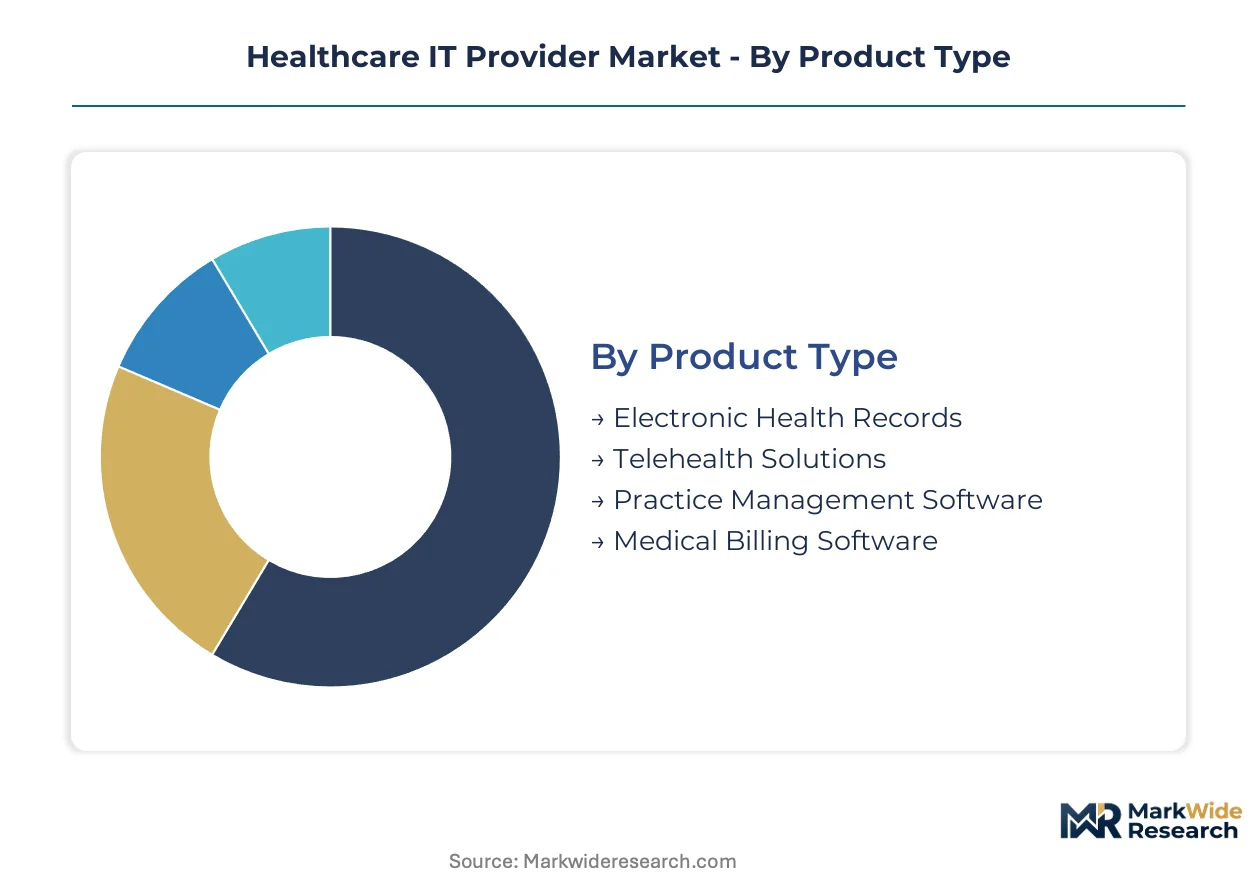
Healthcare IT procurement committees evaluate platforms through four distinct lenses: clinical workflow functionality, end-user operational scale, infrastructure deployment model, and underlying technical architecture. Segmentation clarity determines vendor qualification timelines and contract value distribution across hospital systems.
Product Type:
Substitution pressure intensifies where legacy modules face FHIR-mandated replacement, compressing incumbent advantage in documentation and revenue cycle categories.
- Electronic Health Records:Core clinical data repositories built on HL7 FHIR specifications manage patient histories, medication lists, and care plans across inpatient and ambulatory settings. Large academic medical centers in the United States concentrate procurement around Epic Systems and Oracle Health architectures as ONC certification deadlines accelerate replacement cycles.
- Telehealth Solutions:Synchronous and asynchronous virtual care platforms extend clinical encounters beyond facility walls through video consultation, remote monitoring, and digital triage workflows. Rural health clinics and post-acute care settings in Germany and Japan are cementing these capabilities as permanent service lines rather than contingency infrastructure.
- Practice Management Software:Scheduling, registration, and referral coordination modules for physician group operations.
- Medical Billing Software:Claims processing and revenue cycle automation for institutional and professional fee capture.
Electronic Health Records anchors the volume base while Telehealth Solutions gains share at the steepest rate.
End User:
Cost tier stratification separates enterprise-scale deployments with dedicated informatics teams from resource-constrained settings dependent on vendor-managed services.
- Hospitals:Integrated delivery networks with substantial internal IT capacity pursue composable EHR architectures that decompose monolithic suites into API-connected scheduling, documentation, and clinical decision support modules. United States hospital systems are consolidating vendor negotiations across EHR, ERP, and supply chain platforms under single chief transformation officers.
- Ambulatory Care Centers:Outpatient clinics and physician practices requiring streamlined workflows without enterprise-grade infrastructure overhead. German university hospitals and French cancer centers are demanding vendor-provided EU AI Act conformity documentation prior to pilot contracts, filtering supplier pools for medium-risk diagnostic tools.
- Diagnostics Laboratories:High-volume test processing facilities integrating laboratory information systems with clinical data repositories.
- Home Healthcare Providers:Post-acute and long-term care agencies deploying remote patient monitoring and mobile documentation tools.
Hospitals dominate current contract value while Ambulatory Care Centers expand most quickly as cloud-native point solutions penetrate previously sealed accounts.
Deployment:
Volume concentration tracks CFO-driven exits from capital-intensive data center obligations toward subscription-based operating expenditure models.
- Cloud-Based:Fully managed infrastructure delivered through SaaS subscription models eliminates on-premise hardware maintenance and disaster recovery capital requirements. Hospital CFOs across the United States, Germany, and Japan favor this shift from balance-sheet assets to operating expenses.
- Hybrid Solutions:Mixed architectures retaining sensitive workloads on-premise while migrating non-critical systems to cloud environments. Organizations with mainframe-based revenue cycle management dependencies deploy this model to preserve legacy integrations while capturing partial cloud benefits.
- On-Premise:Self-managed data center installations with full hardware ownership and operational control.
- Mobile Applications:Smartphone and tablet-native interfaces for point-of-care documentation and patient engagement.
Cloud-Based deployment captures the steepest expansion trajectory as hybrid architectures retain transitional share among legacy-dependent organizations.
Technology:
Margin differentiation separates commodity interoperability infrastructure from premium AI and analytics layers attracting disproportionate R&D investment.
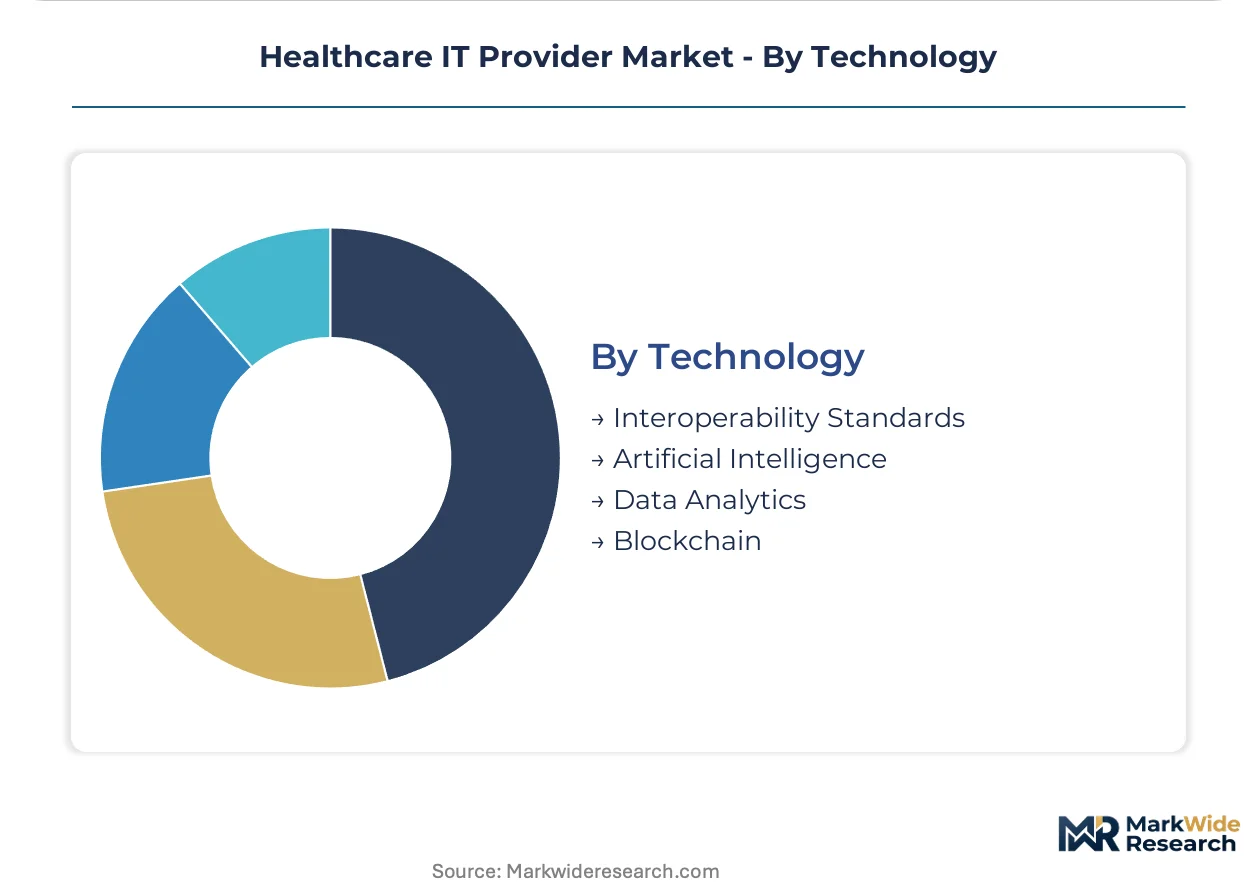
- Artificial Intelligence:Clinical decision support algorithms for automated lesion detection in radiology departments and predictive arrhythmia forecasting in cardiology units. FDA software-as-medical-device oversight extends premarket review pathways for these diagnostic tools.
- Data Analytics:Operational forecasting and population health management platforms processing claims, clinical, and social determinants data. Japanese METI and PMDA coordination on digital therapeutics standards shapes procurement requirements for analytics-enabled care delivery.
- Interoperability Standards:HL7 FHIR specification implementation for health information exchange across disparate systems.
- Blockchain:Distributed ledger applications for credential verification and supply chain integrity in pharmaceutical tracking.
Interoperability Standards underpins current platform architecture while Artificial Intelligence climbs the fastest as radiology and cardiology departments automate diagnostic workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of software-as-a-medical-device anchors the United States as the dominant geography, while ONC interoperability mandates and HIPAA security rules reshape procurement patterns across hospital systems. German university hospitals and Japanese metropolitan health networks are accelerating cloud migration timelines in response to parallel regulatory frameworks.
United States
Large academic medical centers concentrate procurement around integrated EHR architectures as ONC 21st Century Cures Act enforcement accelerates replacement cycles. FDA premarket review pathways for AI diagnostic tools compress commercialization windows for algorithm-native entrants. The Boston-Cambridge cluster and Greater New York metro area host the densest concentration of health informaticist talent, though annual graduation rates fall short of enterprise deployment demand.
Germany
University hospitals in Bavaria and Baden-Württemberg demand vendor-provided EU AI Act conformity documentation prior to pilot contracts for medium-risk clinical decision support systems. The country's national pharmaceutical regulator coordinates with EMA frameworks on digital therapeutics standards. Berlin-Brandenburg health networks are consolidating vendor negotiations across EHR and operational platforms under single chief transformation officers.
Japan
Metropolitan hospital systems in Tokyo and Osaka are cementing telehealth capabilities as permanent service lines rather than contingency infrastructure. METI and PMDA coordination shapes procurement requirements for analytics-enabled care delivery and health data governance standards. The Kansai region exhibits particular concentration in imaging-to-informatics integration for radiology and cardiology workflows.
United Kingdom
NHS trusts in London and the Southeast are adopting microservices-based EHR architectures that decompose monolithic suites into API-connected components. GDPR and NHS Digital interoperability mandates filter supplier pools before procurement initiation. The Midlands and North England health networks pursue hybrid cloud deployments to preserve legacy revenue cycle integrations while capturing partial cloud benefits.
India
Private hospital chains in Maharashtra and Karnataka are deploying cloud-native point solutions for ambulatory care expansion. CDSCO oversight of software-as-medical-device creates parallel conformity pathways for diagnostic algorithms. The Delhi-NCR cluster concentrates health informaticist training programs, though dual clinical-technical graduates remain scarce relative to enterprise implementation timelines.
Healthcare IT Provider Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Healthcare IT Provider Market. Integrated enterprise suite vendors sustain dominance in large academic medical centers through proprietary interoperability architectures, while cloud-native point solution vendors penetrate previously sealed accounts via modular API-connected components. Three archetypes define competitive positioning: monolithic platform incumbents, composable cloud-native challengers, and imaging-to-informatics specialists. M&A activity concentrates around infrastructure consolidation and AI capability acquisition, while strategic partnerships target FHIR-compliant interoperability certification.
Within the integrated platform tier, Epic Systems Corporation and Oracle Health occupy positions sustained by ONC certification dominance and aggressive cloud migration momentum. Siemens Healthineers exemplifies the imaging-to-informatics convergence archetype, competing on radiology and cardiology workflow unification across European and Asia-Pacific hospital networks. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| Allscripts Healthcare Solutions |
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| McKesson Corporation |
| IBM Corporation |
| Accenture |
| Others |
Supply & Pricing Matrix
ONC 21st Century Cures Act certification requirements gate both vendor qualification and price differentiation simultaneously, compressing procurement timelines for cloud-native entrants while sustaining premium positioning for established FHIR-compliant platforms. Hospital CFOs exploit this bifurcation to extract subscription concessions from challengers even as they pay maintenance premiums for incumbent interoperability architectures.
Pricing Analysis
United States hospital systems command 15-25% subscription discounts against German and Japanese equivalents due to scale concentration and competitive vendor density. Pricing stratifies across premium, standard, and economy tiers anchored by ONC certification level, implementation complexity, and after-sales professional services bundling. Cost compression in the standard tier intensifies as cloud-native point solutions penetrate ambulatory care centers with API-first architectures. Safety-net hospitals and rural health clinics exhibit highest price sensitivity, while academic medical centers prioritize interoperability depth over unit cost.
Supply Chain Analysis
The United States, Germany, and Japan anchor healthcare IT platform development, with India supplying engineering talent and cloud infrastructure services. Software development draws from health informaticist labor pools, hyperscaler compute capacity, and HL7 FHIR specification libraries. Single-source vulnerability concentrates in cloud infrastructure dependencies, where three hyperscalers dominate hospital data center migration. Distribution runs through direct enterprise sales teams serving integrated delivery networks, supplemented by value-added resellers penetrating mid-tier ambulatory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare IT architecture is fragmenting from monolithic suites toward composable platforms, with FHIR-mandated replacement cycles creating a high-growth disruption window for modular vendors. ONC interoperability enforcement compresses incumbent advantage while opening white-space for API-native challengers.
For Market Incumbents: Shield core academic medical center accounts by accelerating proprietary FHIR gateway development, locking in data exchange protocols that raise switching costs for decomposing EHR architectures. Deepen vertical integration into imaging-to-informatics workflows to defend margin position against Siemens Healthineers and GE Healthcare specialization. Prioritize certification investment in EU AI Act conformity documentation to preempt German university hospital procurement filtering.
For New Entrants and Emerging Players: Lead with cardiology and radiology workflow modules as the most penetrable white-space, where imaging-to-informatics convergence remains underconsolidated and PACS-VNA integration demands outstrip incumbent delivery capacity. Target rural health clinics and post-acute care settings in Japan and Germany, where telehealth infrastructure permanence creates greenfield subscription opportunities absent legacy mainframe dependencies. Anchor go-to-market through channel partnerships with hyperscaler marketplaces, bypassing eighteen-month direct sales cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models, compressing working capital requirements and accelerating cash conversion for SaaS-architecture vendors. Prioritize acquisition targets with demonstrated EU AI Act conformity documentation and established pilot contracts at German university hospitals or French cancer centers. Monitor FDA software-as-medical-device premarket review pathway velocity as the critical signal for AI-native diagnostic tool commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Compliant Interoperability Certification | ONC certification gates hospital procurement qualification and compresses vendor evaluation timelines to under nine months. |
| EU AI Act Conformity Alignment | Early risk-classification documentation creates first-mover positioning for European hospital procurement cycles. |
| Imaging-to-Informatics Integration | Radiology and cardiology workflow unification captures white-space in PACS-VNA-clinical data repository convergence. |
| Cloud Migration Partnership | Hyperscaler alliances accelerate CFO-mandated exits from capital-intensive data center obligations. |
| Health Informaticist Talent Acquisition | Dual clinical-technical training programs collapse implementation timelines for enterprise deployments. |
Research Methodology
The analysis maps electronic health record platforms, telehealth solutions, and imaging-to-informatics systems, each validated through hospital CIOs, health informaticists, GPO contracts managers, and biomedical engineers. Primary interviews with procurement committee members at integrated delivery networks in the United States, university hospitals in Germany, and metropolitan health systems in Japan combined with secondary validation against CMS Medicare data, hospital procurement databases, GPO contract repositories, and FDA 510(k) filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators ensures cross-verification of volume and value outputs.
Consistency checks validated projections against external benchmarks including hyperscaler healthcare vertical revenue disclosures, EHR vendor SEC filings, and national health IT adoption surveys. The forecast framework segments by deployment model, end-user scale tier, technology architecture, and regional regulatory cluster across the analysis window. CAGRs derive from logistic adoption curve fitting for cloud migration penetration and replacement cycle velocity for FHIR-mandated legacy system displacement. AI clinical decision support algorithm commercialization timelines and health informaticist graduation rates feed directly into implementation capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained ONC enforcement, stable cloud infrastructure pricing, and continued hyperscaler healthcare market investment would require recalibration. Forecasts reflect assumptions regarding regulatory continuity, labor supply elasticity, and hospital capital expenditure prioritization. Recalibration cycles align with material shifts in interoperability mandate enforcement, FDA software-as-medical-device pathway revisions, and EU AI Act implementation guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
North American Dental Software Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Global Pharmacy Management System Market