
 Healthcare AIDC Market | 2026-2036
Healthcare AIDC Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare AIDC Market Intelligence
The replacement of traditional 1D linear barcodes with 2D matrix codes and RFID tags is pivoting product design and data capacity in medical devices. Zebra Technologies Corporation leverages its extensive portfolio of scanners and mobile computers to support this transition. Datalogic S.p.A. specializes in high-performance imaging technology for complex healthcare environments. Honeywell International Inc. competes with integrated solutions spanning data capture and workflow automation for hospitals.
Healthcare Automatic Identification and Data Capture refers to technologies that automate the identification of patients, medications, and assets. These systems use radio-frequency identification (RFID) or high-density 2D barcodes to capture data with minimal human error. While barcode scanners maintain a large installed base, RFID readers are a high-growth product category. Hospitals remain the dominant end-user, with medication tracking applications driving new investment over basic inventory management.
The regulatory environment is defined by patient safety and data integrity mandates, including the FDA's Unique Device Identification (UDI) system and the EU's Medical Device Regulation (MDR). Compliance with standards like HIPAA in the United States also shapes system design to protect patient health information. Stakeholders must now decide on investment pathways that ensure interoperability between disparate AIDC technologies and existing electronic health record systems.
Market Dynamics
The imperative for patient safety and supply chain integrity, enforced by stringent regulatory mandates, is the central force shaping the healthcare AIDC market. This pressure compels healthcare providers and device manufacturers to invest in advanced traceability technologies beyond basic inventory control.
Growth Catalysts
- Regulatory Mandates:Compliance with frameworks like the FDA's Unique Device Identification (UDI) rule and the EU's Medical Device Regulation (MDR) necessitates the adoption of AIDC technologies for complete product lifecycle traceability.
- Patient Safety Initiatives:Hospitals are implementing barcode and RFID systems for medication administration and specimen tracking to reduce human error, a primary driver of new system investment.
- Technology Maturation:The decreasing cost and increasing performance of RFID tags and 2D imaging scanners make them more accessible for widespread deployment across clinical and logistical applications.
Market Restraints
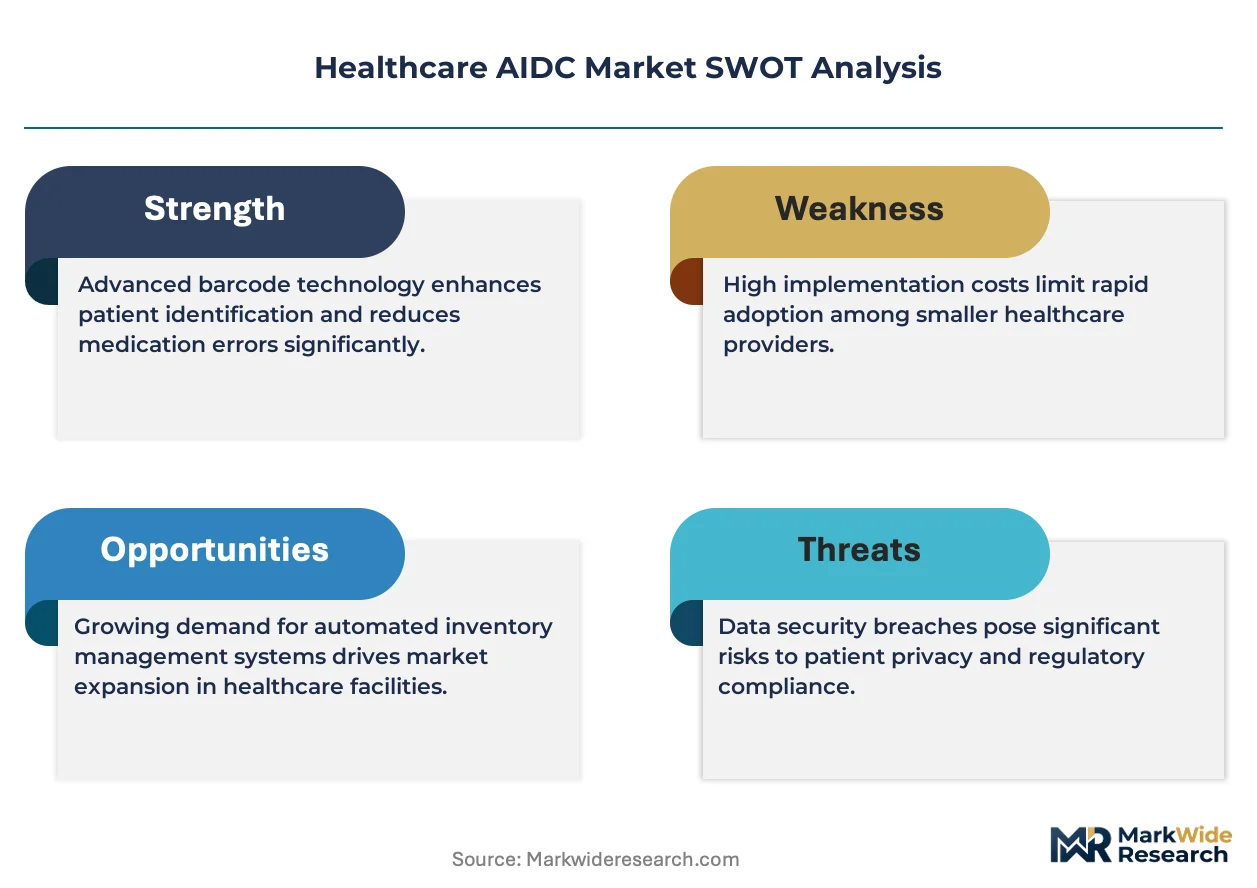
- High Implementation Costs:The significant upfront capital expenditure required for RFID infrastructure, including readers, tags, and middleware software, can be a barrier for smaller healthcare facilities.
- Interoperability Hurdles:A lack of universal standards across AIDC platforms creates difficulties in integrating new systems with existing Electronic Health Record (EHR) and hospital management software.
- System Complexity:The technical complexity of deploying and maintaining large-scale AIDC networks, particularly with RFID, can strain the IT resources of many healthcare organizations.
Strategic Opportunities
- Emerging Market Penetration:Healthcare systems in countries like Brazil and India represent significant growth areas as they begin to modernize infrastructure and adopt digital health technologies.
- Expanded Applications:There is a substantial opportunity to apply AIDC for managing high-value medical assets, tracking patient workflows, and ensuring the integrity of sterile surgical instrument kits.
- AI and Data Analytics:Integrating AIDC data with artificial intelligence platforms can unlock predictive insights for hospital operations, such as forecasting supply needs or optimizing patient flow.
Industry Challenges
- Data Security and Privacy:Ensuring the security of sensitive patient data captured by AIDC systems to maintain compliance with regulations like HIPAA is a constant operational challenge.
- Legacy System Integration:The difficulty and expense of integrating modern AIDC technologies with disparate, aging hospital IT infrastructures frequently delays or complicates project rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare AIDC Market |
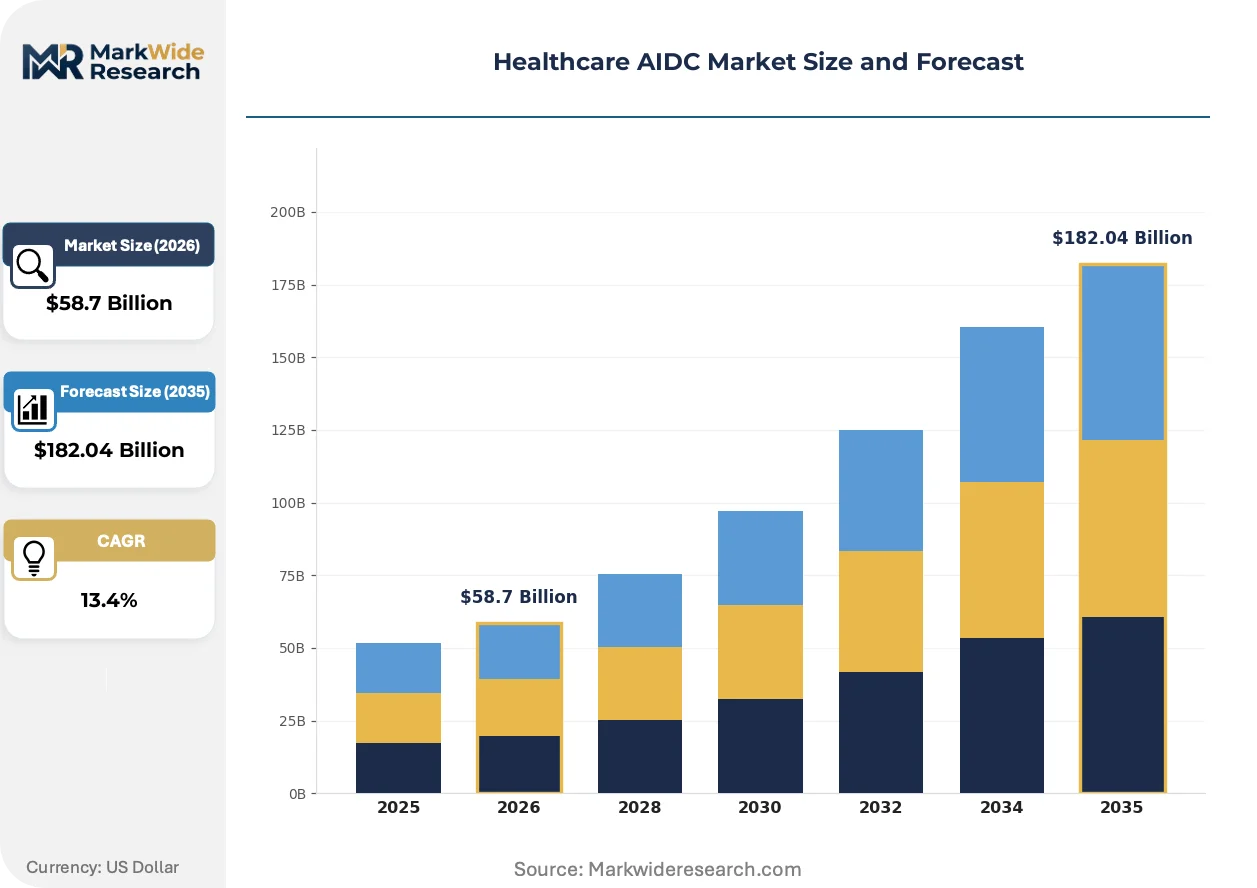
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $182.04 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barcode Scanners, RFID Readers, Biometric Scanners, Mobile Computers, Card Printers Application: Patient Identification, Medication Tracking, Inventory Management, Asset Tracking, Lab Sample Management End User: Hospitals, Diagnostic Laboratories, Pharmacies, Ambulatory Care Centers, Blood Banks Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Zebra Technologies Corporation, Honeywell International Inc., Datalogic S.p.A., Avery Dennison Corporation, SATO Holdings Corporation, Cognex Corporation, Impinj, Inc., NEC Corporation, SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare AIDC Market Strategic Shifts & Innovations
The market is shifting from a focus on simple data capture to the intelligent application of that data for workflow automation and clinical decision support. This evolution prioritizes system interoperability and the integration of AIDC with broader digital health ecosystems.
Technology Evolution
High-density 2D matrix codes and radio-frequency identification tags provide enhanced data storage capacity. Medical device manufacturers and hospital pharmacies are rapidly adopting these technologies to meet new traceability requirements. The ability to embed lot numbers, expiration dates, and serial numbers directly onto small items is overtaking the limited data capacity of traditional linear barcodes.
Regulatory Shift
The European Union's Medical Device Regulation (MDR) imposes strict requirements for device tracking throughout the supply chain. This regulation forces manufacturers to assign a Unique Device Identifier to products sold in the EU and maintain accessible data. Medical device firms are most affected, redesigning packaging and product labels to incorporate compliant 2D barcodes or RFID tags.
Demand-Side Shift
Hospital procurement is evolving from purchasing standalone hardware components to seeking fully integrated AIDC solutions. This change favors suppliers that can offer a bundled package of scanners, software, and implementation services over single-product vendors. The trend is most pronounced in large, multi-site hospital networks within the United States and Germany seeking standardized, enterprise-wide systems.
Healthcare AIDC Market Segmentation

The Healthcare AIDC market segmentation provides granular insights into the diverse technologies, applications, and end-user adoption patterns driving industry evolution. Understanding these distinct segments helps stakeholders identify specific investment pathways and tailor solutions to address varied operational needs. This detailed breakdown highlights areas of concentrated demand and emerging growth opportunities.
Product Type:
The market for AIDC product types is currently undergoing a significant replacement cycle, with older 1D barcode systems being upgraded to more advanced solutions. This shift influences procurement decisions across healthcare facilities.
- RFID Readers:These devices utilize radio waves to wirelessly identify and track objects, offering superior data capacity and read ranges compared to barcodes. Demand is concentrating in hospitals for high-value asset tracking and medication management, driven by improved inventory accuracy.
- Barcode Scanners:These optical scanners decode linear or 2D barcodes, remaining a fundamental component of AIDC systems due to their cost-effectiveness and widespread adoption. Their demand remains strong in patient identification and basic inventory tasks, supported by a large installed base.
- Biometric Scanners:These devices capture unique biological traits for secure patient identification and access control, enhancing data integrity and reducing fraud risks.
- Mobile Computers:Handheld devices integrating scanning capabilities with data processing, enabling point-of-care data capture and streamlined clinical workflows.
- Card Printers:Specialized equipment for producing identification cards, often used for patient registration, staff badges, and access control within healthcare settings.
Volume placements concentrate in Barcode Scanners; the faster expansion belongs to RFID Readers.
Application:
The diverse applications of Healthcare AIDC systems reflect specific operational challenges and regulatory compliance requirements within clinical and administrative environments. Each application targets distinct efficiency and safety improvements.
- Medication Tracking:Systems designed to monitor pharmaceuticals from receipt to administration, ensuring correct dosage, patient, and time. Hospitals are heavily investing in these solutions to minimize medication errors and improve patient safety outcomes.
- Patient Identification:Technologies used to accurately identify patients at various points of care, linking individuals to their medical records and preventing mix-ups. Demand is concentrated in emergency rooms and surgical units, driven by critical safety protocols.
- Inventory Management:AIDC tools employed to monitor stock levels, expiration dates, and movement of medical supplies and equipment within healthcare facilities.
- Asset Tracking:Solutions for locating and managing high-value medical devices and equipment across hospital departments, improving utilization and reducing loss.
- Lab Sample Management:Systems used to identify and track biological samples through laboratory processes, ensuring accuracy and reducing the risk of mislabeling.
Medication Tracking and Patient Identification applications collectively drive significant investment, reflecting core patient safety and operational efficiency imperatives.
End User:
The end-user segmentation highlights the varied needs and operational scales of different healthcare providers adopting AIDC technologies. Each customer type prioritizes distinct benefits from these systems.
- Hospitals:Large, complex facilities requiring comprehensive AIDC solutions for patient identification, medication tracking, and extensive asset management across multiple departments. Their demand is concentrated in large urban centers in the United States and Germany, driven by regulatory mandates and operational scale.
- Pharmacies:Retail and hospital pharmacies utilize AIDC for inventory control, prescription verification, and drug dispensing accuracy. Investment is concentrating on automated systems to enhance efficiency and reduce human error in medication handling.
- Diagnostic Laboratories:Facilities that process patient samples, using AIDC for sample identification, tracking, and workflow automation to ensure diagnostic accuracy.
- Ambulatory Care Centers:Outpatient clinics and urgent care facilities implementing AIDC for streamlined patient check-in and basic inventory management.
- Blood Banks:Specialized centers employing AIDC for precise tracking of blood products, ensuring donor-recipient compatibility and regulatory compliance.
Hospitals remain the primary end-user segment, although specialized facilities like Blood Banks are demonstrating expanding adoption for critical traceability requirements.
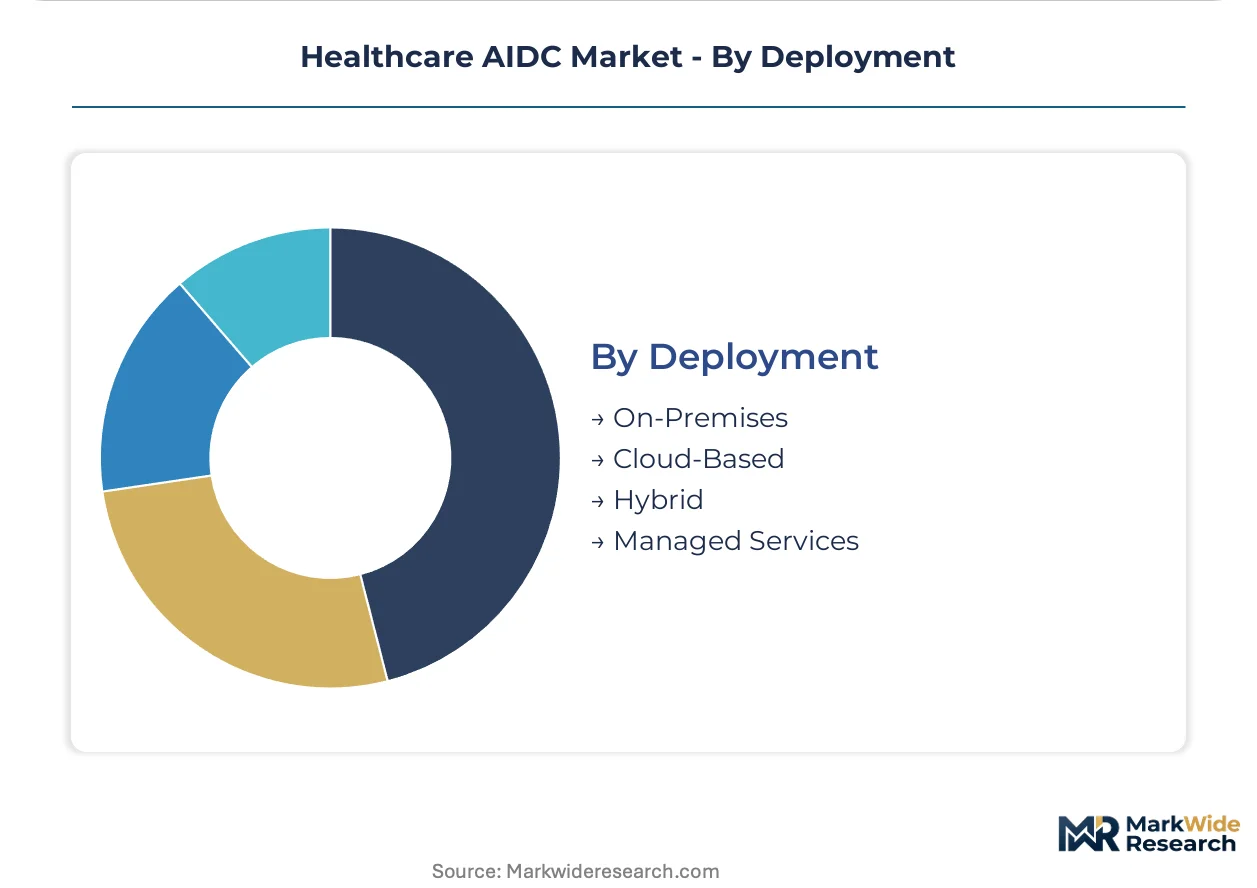
Deployment:
The deployment models for AIDC solutions are evolving, reflecting shifts in IT infrastructure preferences and data management strategies across the healthcare sector. Maturity levels influence adoption patterns.
- Cloud-Based:Solutions hosted on remote servers, offering scalability, reduced upfront IT costs, and remote accessibility for data. Demand is concentrating among newer facilities and those seeking agile IT infrastructure, driven by operational flexibility.
- On-Premises:Systems installed and managed directly within the healthcare organization's own data centers, providing maximum control over data security and customization. This model remains prevalent in large hospital networks with established IT departments.
- Hybrid:A combination of on-premises and cloud-based components, allowing organizations to leverage benefits from both deployment strategies for specific applications.
- Managed Services:External providers manage and maintain the AIDC infrastructure and software, allowing healthcare facilities to focus on core operations.
While On-Premises deployments maintain a substantial footprint, the shift towards Cloud-Based and Hybrid models is gaining momentum due to scalability and cost-efficiency benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Innovation zones and dedicated healthcare technology clusters across developed economies drive significant investment in advanced AIDC solutions. These specialized areas foster collaboration between technology providers, medical device manufacturers, and large hospital networks, accelerating product development and deployment. Such concentrated efforts ensure rapid adoption of new identification and data capture technologies.
United States
Hospitals in the United States prioritize patient identification and medication tracking to enhance safety and operational efficiency. The FDA's Unique Device Identification (UDI) rule mandates comprehensive traceability for medical devices, influencing procurement decisions. Major healthcare innovation hubs like Boston and Silicon Valley see robust activity in AIDC research and deployment, integrating new systems into complex clinical workflows.
Germany
German healthcare systems focus on supply chain integrity and regulatory compliance, particularly with the EU's Medical Device Regulation (MDR). This regulation compels manufacturers and providers to implement sophisticated tracking solutions. Cities like Munich and Berlin, with strong medical technology sectors, are centers for developing and integrating high-performance AIDC systems within hospital networks.
India
India's healthcare sector is modernizing, creating demand for cost-effective AIDC solutions for inventory management and patient record digitization. Government initiatives, such as the Ayushman Bharat Digital Mission, encourage the adoption of digital health technologies. Major metropolitan areas like Bengaluru and Hyderabad are witnessing increased investment in AIDC infrastructure as new hospitals and clinics emerge.
Brazil
Brazilian healthcare providers seek AIDC technologies to improve operational efficiency and address patient safety concerns in a growing market. The country's national health surveillance agency, ANVISA, influences standards for medical device traceability. São Paulo and Rio de Janeiro, as key economic centers, lead the adoption of these systems within large private hospital groups and public health facilities.
Japan
Japanese healthcare emphasizes precision and reliability, driving demand for advanced AIDC in pharmaceutical tracking and asset management. The Ministry of Health, Labour and Welfare (MHLW) supports initiatives for digital transformation in healthcare. Tokyo and Osaka, with their concentration of advanced manufacturing and medical facilities, are key areas for the implementation of 2D barcodes and RFID technologies.
Healthcare AIDC Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the healthcare AIDC market. The market exhibits a tiered structure, with established technology providers offering integrated solutions alongside niche players focusing on specific applications. Companies frequently engage in strategic partnerships and portfolio diversification to address the varied needs of healthcare end-users.
Global technology conglomerates, such as Zebra Technologies Corporation and Honeywell International Inc., exemplify the integrated solution provider archetype, offering a broad range of scanners, mobile computers, and software. Datalogic S.p.A. represents specialists in high-performance imaging technology, occupying a significant position in complex healthcare environments. These companies anchor the market with their extensive product portfolios and established distribution channels, catering to large hospital networks and medical device manufacturers seeking comprehensive AIDC deployments.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Honeywell International Inc. |
| Datalogic S.p.A. |
| Avery Dennison Corporation |
| SATO Holdings Corporation |
| Cognex Corporation |
| Impinj, Inc. |
| NEC Corporation |
| SICK AG |
| Others |
Cost & Logistics Intelligence
Vertical integration by major technology providers anchors both the supply position and pricing power within the Healthcare AIDC market. This strategy allows companies to control component costs and offer bundled solutions to large hospital networks.
Pricing Analysis
Volume placements of barcode scanners typically operate on lower margins compared to the higher-margin, integrated RFID solutions. The dominant pricing structure combines per-unit transactional costs for hardware with subscription-based models for associated software and services. Price differentiation stems from customization levels for complex deployments and the depth of after-sales service provided by vendors. Pricing softness affects basic barcode scanner units due to widespread availability, while large hospital networks show less price sensitivity for comprehensive, integrated AIDC systems.
Supply Chain Analysis
Direct sales channels handle large hospital network demand for integrated AIDC solutions, while value-added resellers support smaller facilities. Geographic supply of core components centers on China for basic hardware manufacturing and Germany for high-performance imaging technologies. The industry draws from global semiconductor chip production and specialized optical lens suppliers. A structural risk involves single-source vulnerabilities for advanced RFID chipsets, impacting lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare AIDC market navigates a crucial technology-transition phase, with 2D matrix codes and RFID tags rapidly displacing traditional 1D linear barcodes. This shift redefines data capture capabilities and traceability standards across the healthcare ecosystem.
For Market Incumbents:Cement market leadership by accelerating R&D into next-generation RFID and integrated AI-driven analytics platforms. This proactive investment counters the threat from emerging cloud-native solution providers and future-proofs existing portfolios. Expanding channel control through strategic partnerships with large hospital system integrators reinforces their distribution advantage. Investing in advanced certification pathways for new solutions also maintains a competitive edge.
For New Entrants and Emerging Players:Price-point gaps between premium enterprise solutions and basic economy offerings present opportunities for new entrants. Target underpenetrated ambulatory care centers and smaller clinics in modernizing infrastructure in countries like India and Brazil. Focus on offering cost-effective, SaaS-based AIDC solutions for basic inventory management and patient identification. A go-to-market angle emphasizing rapid deployment and minimal upfront capital expenditure will resonate with these budget-conscious buyers.
For Investors and Strategic Acquirers:Exit pathways concentrate in strategic acquisitions by larger technology conglomerates seeking to expand their healthcare AIDC portfolios. The market demonstrates strong long-term viability over the next 5-10 years, driven by continuous regulatory mandates and technological advancements. Identify niche software developers specializing in seamless AIDC-EHR system integration or innovative RFID tag manufacturers as prime acquisition targets. Investors should monitor consolidation activity among mid-tier solution providers as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies disparate AIDC data streams with existing Electronic Health Record systems for comprehensive patient insights. |
| RFID Technology Enhancement | Improves accuracy and read range for critical asset and medication tracking in complex hospital environments. |
| Regulatory Compliance Services | Supports medical device manufacturers in meeting stringent FDA UDI and EU MDR traceability requirements. |
| AI-Driven Analytics Development | Transforms raw AIDC data into predictive insights for optimizing hospital operations and supply chain efficiency. |
| Emerging Market Entry | Captures new growth opportunities by addressing modernizing infrastructure needs in countries like India and Brazil. |
Research Approach
FDA filings, EU MDR guidelines, and hospital procurement databases formed the secondary backbone of this study. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and Group Purchasing Organization (GPO) contracts managers provided crucial qualitative insights. This approach combined bottom-up data aggregation with top-down market validation. Triangulation across these diverse sources ensured comprehensive market understanding.
Historical trendline analysis and market sizing models underpinned the quantitative projections across the analysis window. The study modeled segmentation dimensions including product type, application, end-user, deployment model, and regional regulatory cluster. Compound Annual Growth Rates were derived from an assessment of historical data and projected growth drivers. Forecast inputs included healthcare IT spending trends and medical device production volumes.
Inputs from public financial reports and regulatory body publications were available; gaps in proprietary vendor sales data introduce uncertainty bands. Forecasts reflect assumptions regarding market evolution and technology adoption. Practitioners should monitor significant shifts in regulatory mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Global RFID in Healthcare Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market