
 Patient Self-Service Kiosks Market | 2026-2036
Patient Self-Service Kiosks Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Self-Service Kiosks Market Analytics
The hardware-software capability gap between integrated platform vendors and component assemblers is unwinding competitive hierarchies in patient self-service kiosks. NCR Corp leverages its ATM manufacturing scale to dominate payment-integrated healthcare terminals across North American hospital networks. International Business Machines Corporation anchors its position through Watson Health AI layers that sustain premium pricing for cognitive check-in workflows. Clearwave Corporation specializes in cloud-native software stacks that compete effectively against legacy on-premise installations.
Patient self-service kiosks are interactive, freestanding terminals that combine touchscreen interfaces, thermal printers, card readers, and biometric sensors to automate registration, payment, and wayfinding functions in healthcare facilities. These systems typically integrate HL7 FHIR protocols to exchange demographic and insurance data with hospital information systems, reducing average check-in duration from twelve minutes to under three minutes. Check-in kiosks occupy the largest installed base among product types, though biometric authentication terminals are recording the fastest expansion as fingerprint and iris recognition displace password-based patient verification. Touchscreen technology leads unit shipments, while NFC-enabled contactless payment modules are capturing disproportionate margin pools as hospitals accelerate cashless transaction mandates.
The FDA regulates kiosk-mounted biometric devices as Class II medical devices under 510(k) clearance pathways, while HIPAA mandates encryption standards for all patient data captured at terminal endpoints. The ONC's Cures Act Final Rule enforces API-based interoperability, forcing kiosk vendors to rebuild proprietary data architectures around standardized health information exchange protocols. Stakeholders must monitor how state-level Medicaid expansion timelines alter capital allocation priorities for rural clinic kiosk deployments versus urban hospital upgrades.
Market Dynamics
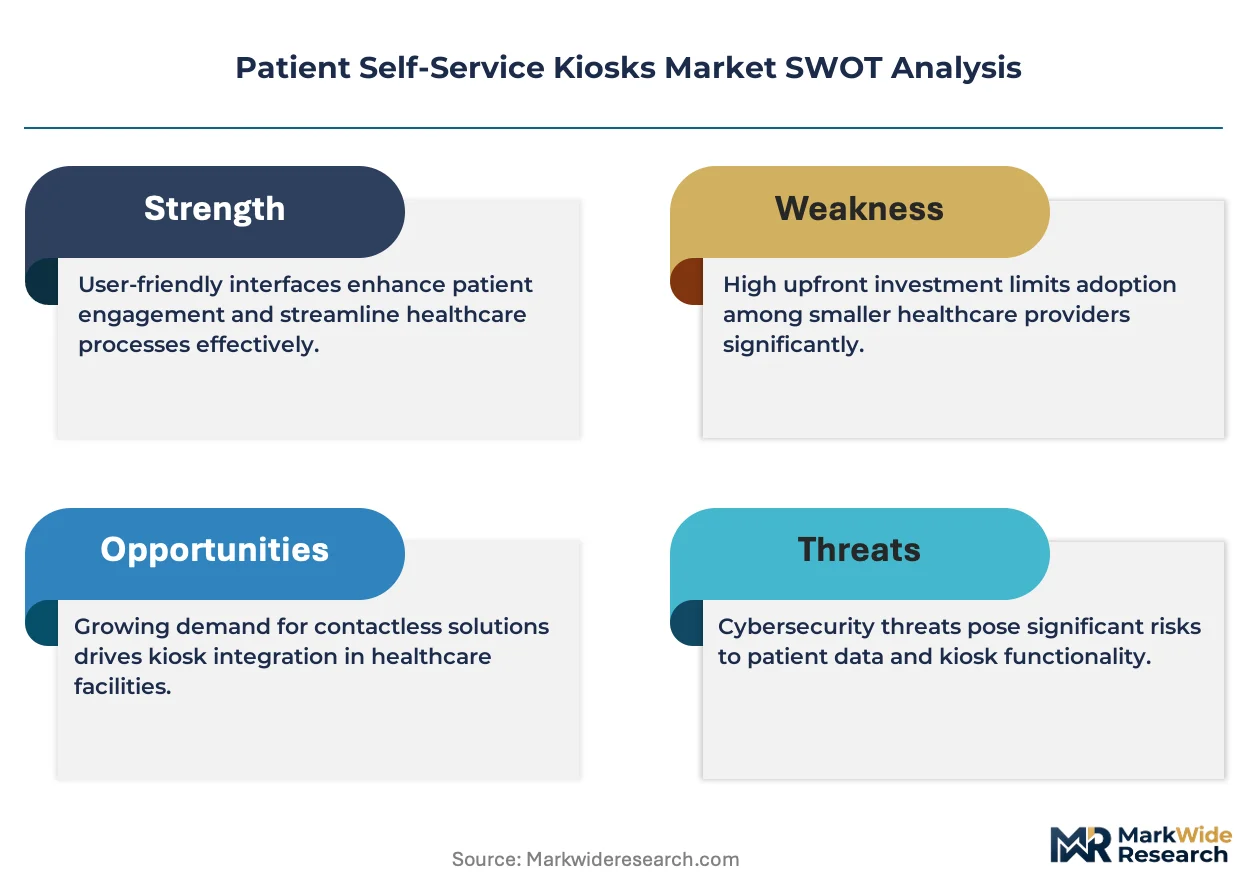
The 21st Century Cures Act's interoperability mandates are forcing kiosk vendors to dismantle proprietary data architectures and rebuild around HL7 FHIR protocols, compressing margins for legacy on-premise installers while accelerating cloud-native platform adoption.
Growth Catalysts
- Interoperability Mandates:The ONC's Cures Act Final Rule enforces API-based data exchange between kiosks and electronic health record systems, eliminating integration friction that previously stalled hospital procurement cycles.
- Biometric Authentication:Fingerprint and iris recognition modules are displacing password-based patient verification, reducing check-in fraud and insurance eligibility disputes at high-volume outpatient networks.
- Southeastern Health System Consolidation:Large Florida and Georgia health systems are consolidating outpatient networks, creating concentrated demand for standardized kiosk fleets across multi-site deployments.
Market Restraints
- Semiconductor Supply Concentration:Touchscreen controllers and NFC payment modules depend on concentrated Asian foundry capacity, exposing kiosk manufacturers to input volatility and extended lead times.
- FDA 510(k) Pathway Friction:Biometric sensors mounted on kiosks require Class II medical device clearance, adding twelve-to-eighteen month certification timelines that delay product launches and freeze R&D roadmaps.
- Mobile App Substitution:Smartphone-based check-in applications are capturing low-acuity patient visits, threatening kiosk utilization rates at urgent care and primary care clinics.
Strategic Opportunities
- Rural Clinic Underpenetration:Federally Qualified Health Centers in Mississippi and Alabama remain kiosk-sparse, presenting first-mover opportunities as Medicaid expansion timelines clarify capital allocation priorities.
- AI-Driven Wayfinding Convergence:Natural language processing layers combined with computer vision are enabling voice-activated navigation for visually impaired patients, opening accessibility-compliant procurement channels.
- Contactless Payment Mandates:Hospital cashless transaction policies are accelerating NFC module upgrades, creating aftermarket retrofit demand across installed bases of older touchscreen terminals.
Industry Challenges
- Legacy HIS Integration Complexity:Health information systems running on outdated architectures require custom middleware development, stretching implementation timelines and inflating professional services costs.
- Cybersecurity Talent Scarcity:HIPAA-compliant endpoint encryption and biometric data protection demand specialized security engineering skills that command premium compensation and elongate hiring cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Self-Service Kiosks Market |
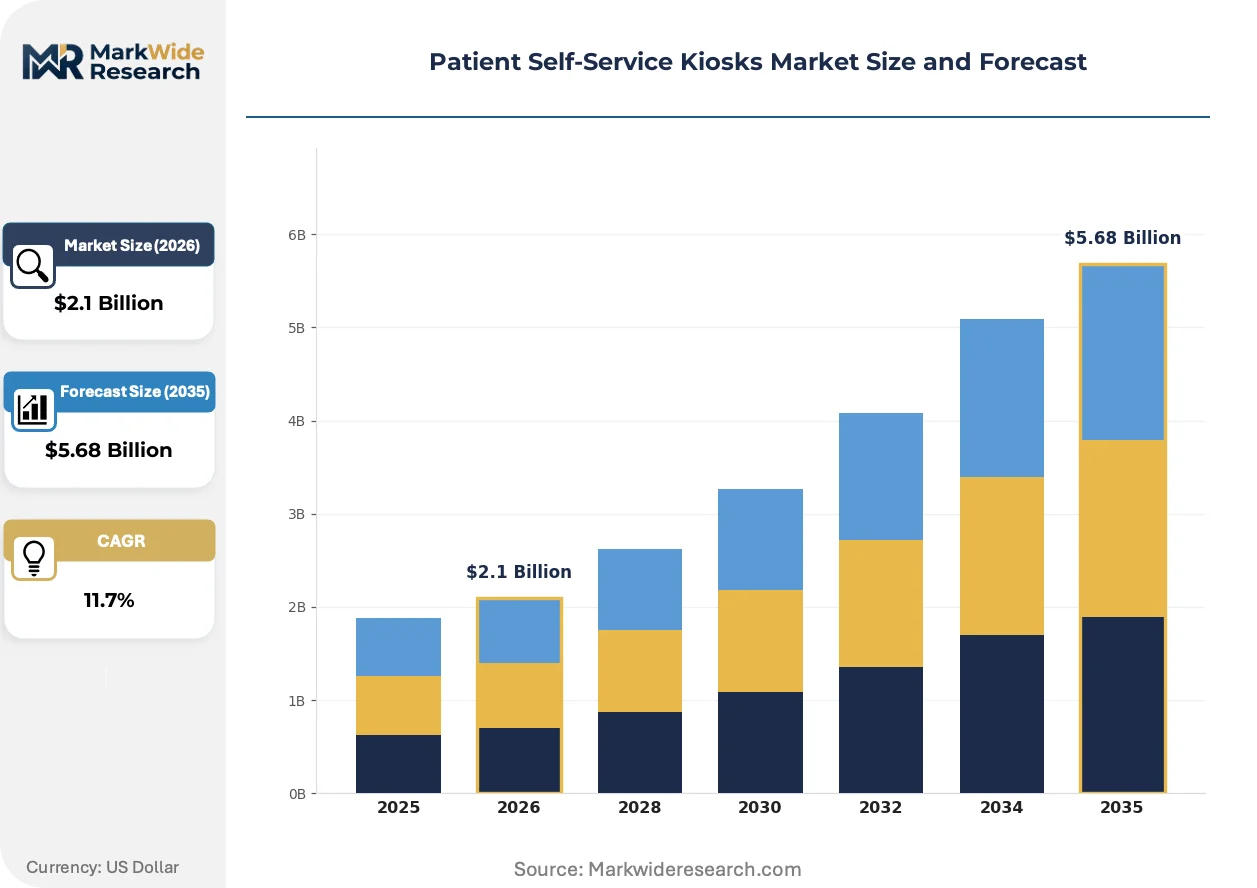
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.68 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Check-In Kiosks, Payment Kiosks, Information Kiosks, Wayfinding Kiosks Technology: Touchscreen, QR Code Scanners, NFC, Biometric Authentication End User: Hospitals, Clinics, Urgent Care Centers, Specialty Practices Distribution Channel: Direct Sales, Online Retail, Value-Added Resellers, Distributors |
| Companies Covered | NCR Corp, International Business Machines Corporation, Clearwave Corporation, KIOSK Information Systems Inc., Diebold Nixdorf, Slabb Kiosks, Meridian Kiosks LLC, EMBROSS Group Pty Ltd, Olea Kiosks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Self-Service Kiosks Market Evolving Landscape
Touchscreen-based patient self-service kiosks are fragmenting into specialized component ecosystems, with software layers decoupling from hardware enclosures and enabling modular upgrade paths that extend equipment lifecycles.
Biometric authentication hardware is decomposing the traditional password-and-barcode patient verification stack. Large southeastern hospital networks are deploying fingerprint and iris recognition terminals at check-in pods, replacing magnetic stripe readers and paper-based insurance card scanning. This decomposition is compressing average verification duration from multiple manual steps to sub-second automated matching, while forcing legacy kiosk vendors to source third-party biometric modules or cede authentication revenue to specialized suppliers.
The FDA's 510(k) clearance pathway for kiosk-mounted biometric devices is tightening quality system requirements for hardware manufacturers. Vendors must now submit clinical validation data demonstrating equivalent safety profiles to predicate devices, elevating documentation burdens and favoring established medical device suppliers over consumer electronics entrants. Cardiology and oncology outpatient units, where patient identity errors carry elevated clinical risk, are prioritizing FDA-cleared terminals over uncertified alternatives despite fifteen-to-twenty percent cost premiums.
Hospital procurement teams are unbundling hardware acquisition from software licensing and maintenance contracts, fragmenting vendor relationships that previously consolidated under single-source agreements. Health system IT departments are negotiating directly with cloud-native software platforms while sourcing enclosures and payment modules through separate channels, compressing margins for integrated platform vendors. This unbundling is most pronounced in Florida and Georgia, where multi-hospital networks are standardizing software stacks across disparate hardware vintages to reduce training and support complexity.
Patient Self-Service Kiosks Market Segmentation
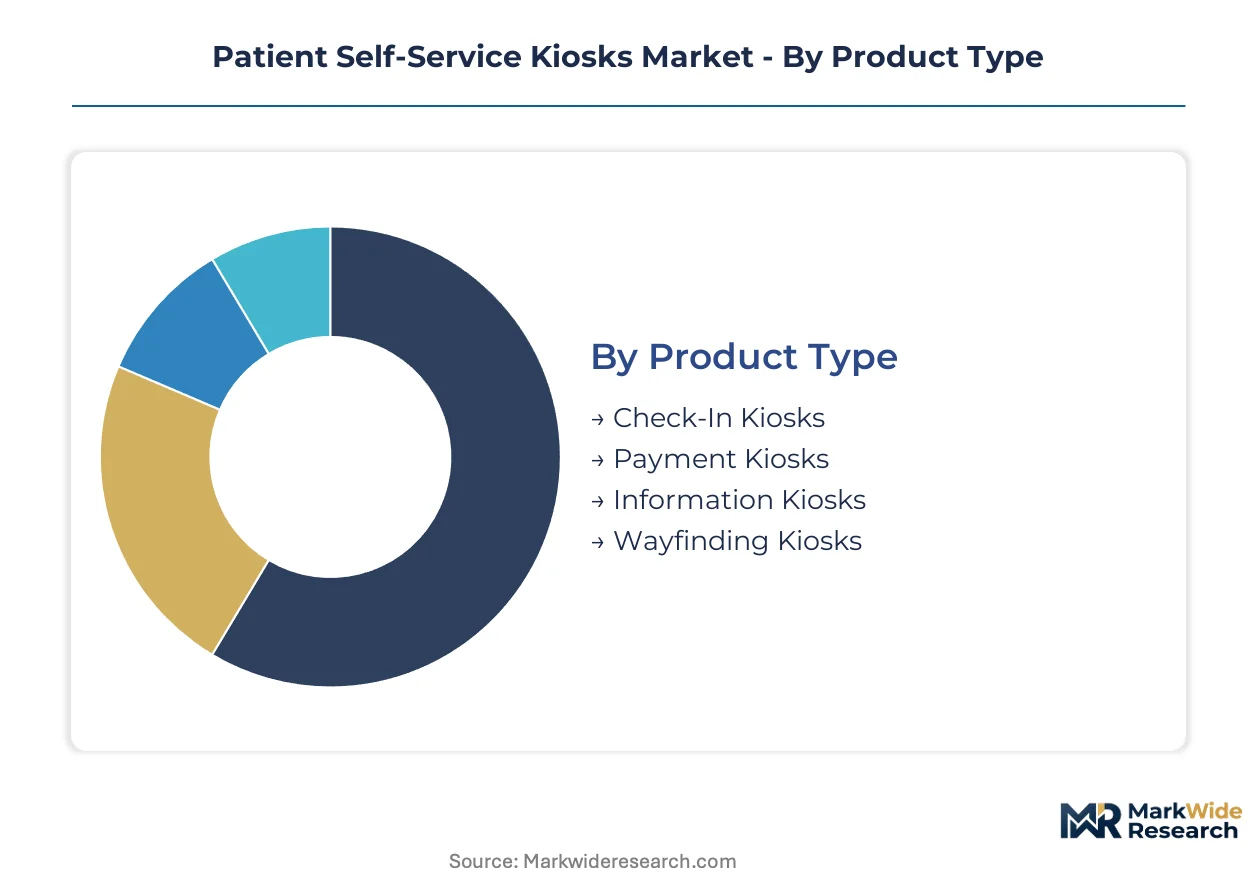
Patient self-service kiosks fragment across four intersecting dimensions that determine procurement priorities and margin structures. Product type and technology choices dominate hospital capital allocation, while end-user scale and distribution channel access shape vendor competitive positioning.
Product Type:
FDA clearance requirements and HIPAA encryption mandates create divergent compliance burdens across kiosk categories, elevating total cost of ownership for biometric-intensive configurations.
- Check-In Kiosks:These terminals integrate touchscreen interfaces, thermal printers, and card readers to automate patient registration and insurance verification. Southeastern hospital networks in Florida and Georgia deploy standardized fleets across consolidated outpatient networks, driven by front-desk labor reduction targets.
- Payment Kiosks:Units combine NFC contactless modules with encrypted card readers to process copayments and outstanding balances. Large health systems mandate cashless transaction policies, accelerating retrofit demand across legacy touchscreen installations.
- Information Kiosks:Directory and educational terminals with lower integration requirements serve lobbies and waiting areas.
- Wayfinding Kiosks:Interactive navigation systems with computer vision layers guide patients through complex medical campuses.
Established volume favors Check-In Kiosks; emerging adoption favors Wayfinding Kiosks.
Technology:
Component sourcing concentration in Asian foundries concentrates supply risk for NFC and biometric modules, while touchscreen controllers benefit from diversified manufacturing.
- Biometric Authentication:Fingerprint and iris recognition hardware requires FDA 510(k) clearance as Class II medical devices, adding twelve-to-eighteen month certification timelines. Cardiology and oncology outpatient units prioritize these terminals despite cost premiums, as patient identity errors carry elevated clinical risk.
- NFC:Contactless payment modules capture disproportionate margin pools as hospitals accelerate cashless mandates, though semiconductor supply volatility extends lead times.
- Touchscreen:Capacitive and resistive interfaces lead unit shipments across all product categories.
- QR Code Scanners:Lower-cost optical modules support mobile app handoff workflows at urgent care and primary care clinics.
Touchscreen deployments dominate current installations; biometric authentication is climbing the fastest.
End User:
Capital intensity and patient volume throughput create tiered procurement patterns, with federal funding timelines altering rural clinic deployment schedules.
- Hospitals:Multi-hospital networks standardize software stacks across disparate hardware vintages to reduce training complexity, unbundling hardware acquisition from cloud-native platform licensing.
- Clinics:Federally Qualified Health Centers in Mississippi and Alabama remain kiosk-sparse, presenting first-mover opportunities as Medicaid expansion clarifies capital priorities.
- Urgent Care Centers:High patient turnover drives demand for rapid check-in automation, though smartphone app substitution threatens utilization rates.
- Specialty Practices:Cardiology and oncology units prioritize FDA-cleared biometric terminals for identity verification accuracy.
Hospital procurement commands the largest deal sizes; clinic deployments are expanding most quickly.
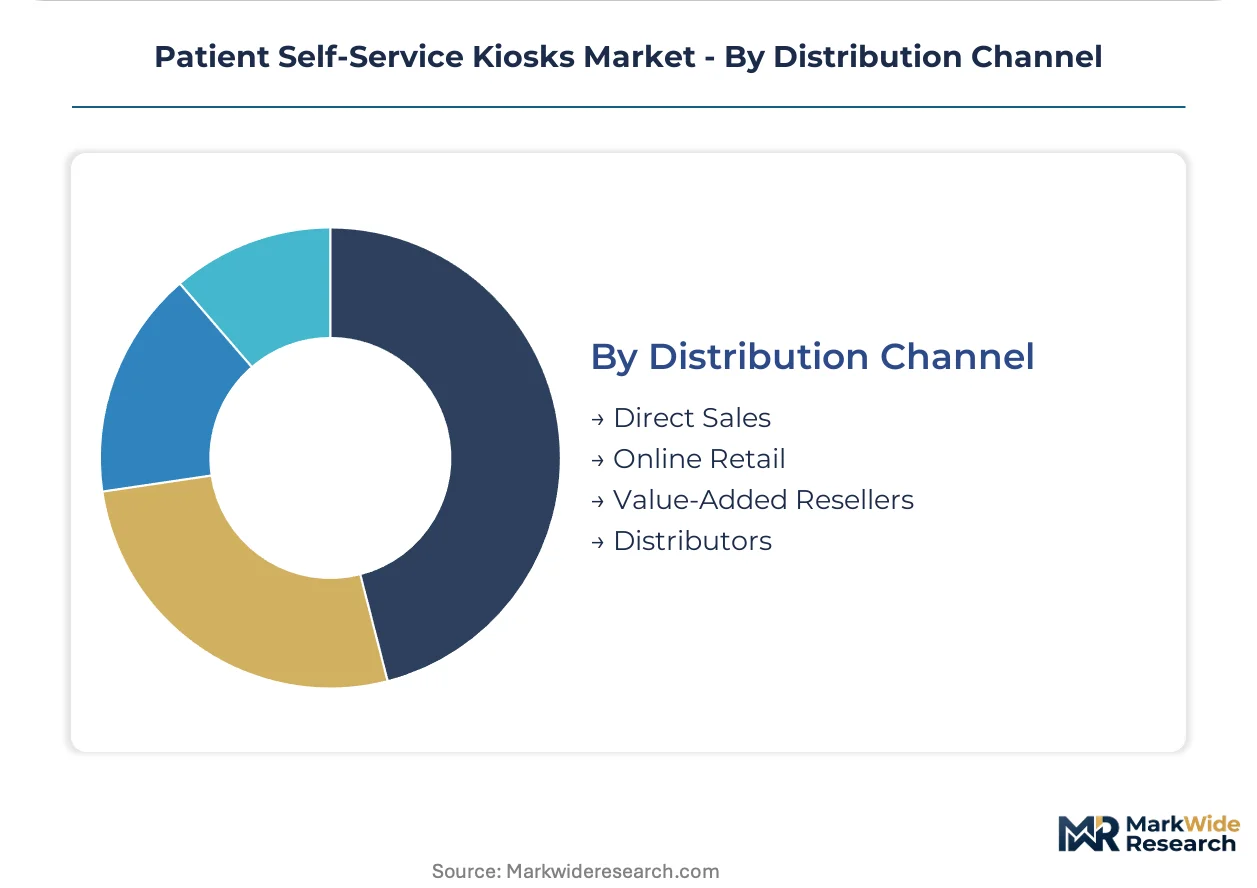
Distribution Channel:
Health system IT departments increasingly negotiate software directly with cloud-native platforms, fragmenting vendor relationships that previously consolidated under single-source agreements.
- Direct Sales:Enterprise agreements with large southeastern health systems dominate high-volume transactions, compressing margins for integrated platform vendors.
- Value-Added Resellers:Regional specialists provide implementation and support services for legacy HIS integration complexity.
- Distributors:Hardware-focused channels source enclosures and payment modules separately from software licensing.
- Online Retail:Lower-touch procurement serves small clinic and specialty practice segments with standardized configurations.
Direct sales anchor hospital network revenue; value-added resellers are gaining share fastest among mid-tier deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the southeastern United States, where Florida and Georgia health systems command volume discounts on standardized kiosk fleets, while rural markets in Mississippi and Alabama absorb premium deployment costs due to sparse vendor competition and legacy infrastructure gaps.
United States
Hospital networks in Florida and Georgia are consolidating outpatient facilities and deploying standardized kiosk fleets across multi-site deployments. The 21st Century Cures Act's interoperability mandates are accelerating HL7 FHIR protocol adoption, forcing vendors to rebuild proprietary architectures. Atlanta and Miami anchor the largest concentration of check-in terminal installations.
Canada
Provincial health authorities in Ontario and British Columbia are piloting biometric authentication terminals for patient identity verification. Health Canada's medical device regulations govern kiosk-mounted sensors under Class II pathways. Toronto's hospital clusters are prioritizing cloud-native software stacks over legacy on-premise installations.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are integrating wayfinding kiosks with existing campus navigation systems. The EU Medical Device Regulation (MDR) imposes conformity assessment requirements on biometric hardware. Munich's medical technology corridor is attracting kiosk vendors seeking CE-marked product validation.
United Kingdom
NHS trusts in London and the Midlands are deploying payment-integrated terminals to reduce cash handling in outpatient departments. GDPR mandates strict encryption standards for patient data captured at terminal endpoints. The NHS Digital transformation program is standardizing API-based interoperability requirements.
Australia
Public hospital networks in New South Wales and Victoria are expanding self-service check-in to reduce front-desk congestion. The Therapeutic Goods Administration (TGA) regulates biometric devices as medical devices. Sydney's health precincts are testing voice-activated wayfinding for accessibility compliance.
Patient Self-Service Kiosks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in patient self-service kiosks, with integrated platform vendors commanding premium pricing for cognitive workflows while component assemblers compete on hardware margins. The vendor base fragments across four tiers: ATM-scale manufacturers with payment integration expertise, cloud-native software specialists, legacy on-premise installers, and regional hardware fabricators. Strategic differentiation centers on FDA 510(k) clearance capabilities for biometric modules and HL7 FHIR protocol certification. Dominant competitive moves include unbundling hardware from software licensing and geographic expansion through value-added reseller networks.
Within the integrated platform tier, NCR Corp and International Business Machines Corporation occupy positions that exemplify divergent scale advantages, with the former leveraging ATM manufacturing infrastructure and the latter anchoring cognitive check-in workflows through AI layers. Clearwave Corporation represents the cloud-native specialist archetype, competing against legacy installations through modular software architectures. These three companies illustrate how competitive positioning fragments between hardware-scale incumbents, cognitive workflow premium vendors, and agile software-first entrants.
| Leading Market Players |
|---|
| NCR Corp |
| International Business Machines Corporation |
| Clearwave Corporation |
| KIOSK Information Systems Inc. |
| Diebold Nixdorf |
| Slabb Kiosks |
| Meridian Kiosks LLC |
| EMBROSS Group Pty Ltd |
| Olea Kiosks Inc. |
| Others |
Value Network & Pricing Analysis
Cloud-native software stacks displacing legacy on-premise installations simultaneously shift procurement geography toward vendor-agnostic hardware sourcing and compress margin capture for integrated platform vendors across North American hospital networks.
Pricing Analysis
Configured-to-order pricing for FDA 510(k) cleared biometric terminals commands fifteen-to-twenty percent premiums over standard touchscreen configurations, with certification grade and volume scale as primary differentiation drivers. Cost compression in entry-level payment kiosks is intensifying because unbundled software licensing fragments vendor relationships. Federally Qualified Health Centers exhibit highest price sensitivity, while cardiology and oncology outpatient units absorb premiums for identity-verification accuracy.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes touchscreen controller and NFC payment module shipments to geopolitical disruption, with semiconductor fabrication concentrated in Taiwan, South Korea, and mainland China. Kiosk assembly draws from Asian foundry capacity for biometric sensors, thermal printers, and encryption chipsets. Single-source vulnerability in advanced node semiconductor production elevates supply risk. Distribution runs through value-added reseller networks for mid-tier health system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA 510(k) clearance timelines and HIPAA compliance requirements create twelve-to-eighteen month barriers that protect incumbent positions from rapid competitive displacement.
For Market Incumbents: Shield installed base revenue by deepening backward integration into biometric sensor supply and accelerating HL7 FHIR certification investments ahead of interoperability mandate deadlines. Mobile app substitution threatens urgent care utilization rates; channel control through exclusive value-added reseller agreements in the southeastern United States reinforces defensive positioning.
For New Entrants and Emerging Players: FDA 510(k) clearance fast-tracks for Class II biometric devices open procurement channels at cardiology and oncology outpatient units where patient identity errors carry elevated clinical risk. Rural Federally Qualified Health Centers in Mississippi and Alabama remain kiosk-sparse, presenting first-mover opportunities. Cloud-native software licensing decoupled from hardware enclosures enables rapid deployment without legacy HIS integration complexity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud-native software specialists possessing modular architectures and recurring revenue streams. Long-term viability across the five-to-ten year window favors platforms with established FDA clearance capabilities and health system GPO contract access. Watch Medicaid expansion timeline clarity in southeastern states as the inflection signal for rural clinic capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Class II medical device certification unlocks cardiology and oncology procurement channels. |
| HL7 FHIR Protocol Integration | API-based interoperability satisfies ONC Cures Act mandates and accelerates hospital sales cycles. |
| Cloud-Native Platform Development | Modular software architectures enable unbundled licensing and extend equipment lifecycles. |
| Biometric Authentication Module Sourcing | Fingerprint and iris recognition hardware reduces check-in fraud and insurance eligibility disputes. |
| Value-Added Reseller Network Expansion | Regional specialists address legacy HIS integration complexity for mid-tier health system deployments. |
Research Methodology
Operator-level perspectives from hospital IT directors, biomedical engineers, GPO contracts managers, and kiosk vendor sales executives anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) clearance databases, hospital procurement records, and CMS Medicare reimbursement data. SEC filings of publicly traded hardware manufacturers and cloud-native software specialists provided financial triangulation. Bottom-up unit shipment estimates and top-down health system capital expenditure analysis converged on market sizing.
Sensitivity analysis tested biometric adoption curves and Medicaid expansion scenarios across the projection horizon. Segmentation dimensions modeled include product type, authentication technology, end-user scale, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to hospital network consolidation patterns and interoperability mandate compliance timelines. Cashless transaction policy acceleration and semiconductor supply volatility served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained interoperability enforcement and stable health system capital allocation; material deviation in FDA clearance timelines or semiconductor supply disruption would warrant model refresh. Practitioners should keep alternative scenarios live as state-level Medicaid expansion decisions and mobile app substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Global Electronic Trial Master File (ETMF) Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Clinical Healthcare IT Market