
 Global Patient Flow Management Solutions Market | 2026-2036
Global Patient Flow Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Flow Management Solutions Market Foresight
Nursing informatics specialists is redrawing competitive boundaries across the patient flow management landscape. Cerner Corporation leverages its entrenched EHR footprint to bundle flow optimization modules into existing hospital contracts. Epic Systems Corporation anchors its position through deep integration between scheduling, bed management, and clinical documentation workflows. TeleTracking Technologies specializes in real-time capacity command centers that dominate large academic medical center deployments.
Patient flow management solutions coordinate the movement, placement, and status tracking of individuals through acute care settings using RFID triangulation, predictive bed-turn algorithms, and interoperability protocols such as HL7 FHIR. These systems reduce emergency department boarding hours and optimize surgical block utilization. Cloud-based deployment now leads new procurement decisions as health systems prioritize elastic infrastructure over capital-intensive server farms. Real-time location systems represent the fastest-growing solution category, driven by hardware miniaturization and Bluetooth Low Energy mesh networks that slash installation costs compared to legacy infrared systems.
FDA digital health software guidance, HIPAA security rule enforcement, and ONC interoperability certification collectively determine which vendors qualify for federal reimbursement programs and health system shortlists. The EU AI Act and GDPR cross-border data restrictions add compliance layers for platforms processing patient movement patterns across European hospital networks. Stakeholders must monitor how CMS inpatient prospective payment system reforms reshape the business case for throughput automation versus labor expansion.
Market Dynamics
Cloud migration is compressing deployment timelines from eighteen months to under ninety days for patient flow management platforms, forcing vendors to rearchitect legacy codebases around containerized microservices and API-first interoperability.
Growth Catalysts
- HIPAA Security Rule enforcement:Federal audits of hospital data handling practices are accelerating procurement of encrypted patient tracking systems with audit-ready access logs.
- Bluetooth Low Energy mesh networks:Hardware costs for real-time location infrastructure have dropped below legacy infrared pricing, enabling mid-size community hospitals to deploy enterprise-grade capacity command centers.
- Emergency department boarding crisis:CMS penalties for prolonged length-of-stay metrics are compelling health systems to automate bed-turn predictions and discharge planning workflows.
Market Restraints
- IT talent scarcity:Health systems face twelve-to-eighteen month hiring cycles for HL7 FHIR integration specialists, delaying platform rollouts and inflating implementation costs.
- Legacy EHR lock-in:Proprietary data formats from entrenched electronic health record vendors create switching costs that deter multi-hospital networks from consolidating flow management vendors.
- Cyber insurance exclusions:Underwriters are carving out coverage for cloud-based clinical systems, exposing hospitals to uncovered liability from ransomware disruptions to patient tracking infrastructure.
Strategic Opportunities
- Post-acute integration:Skilled nursing facilities and home health agencies present unserved demand for patient transition tracking that extends flow visibility beyond hospital walls.
- EU AI Act compliance services:European hospital networks require algorithmic audit trails for predictive bed management tools, creating a services layer around explainable AI documentation.
- Edge computing convergence:On-premise inference chips from NVIDIA and Qualcomm are enabling sub-second location updates without cloud dependency, opening rural and military hospital segments previously blocked by bandwidth constraints.
Industry Challenges
- Interoperability certification backlog:ONC's delayed testing schedules for HL7 FHIR R4 interfaces are pushing vendor release dates and freezing hospital procurement committees.
- Clinical workflow redesign:Nursing unions resist automated patient assignment algorithms that override seniority-based bed allocation protocols, requiring change management investments that erode ROI projections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Flow Management Solutions Market |
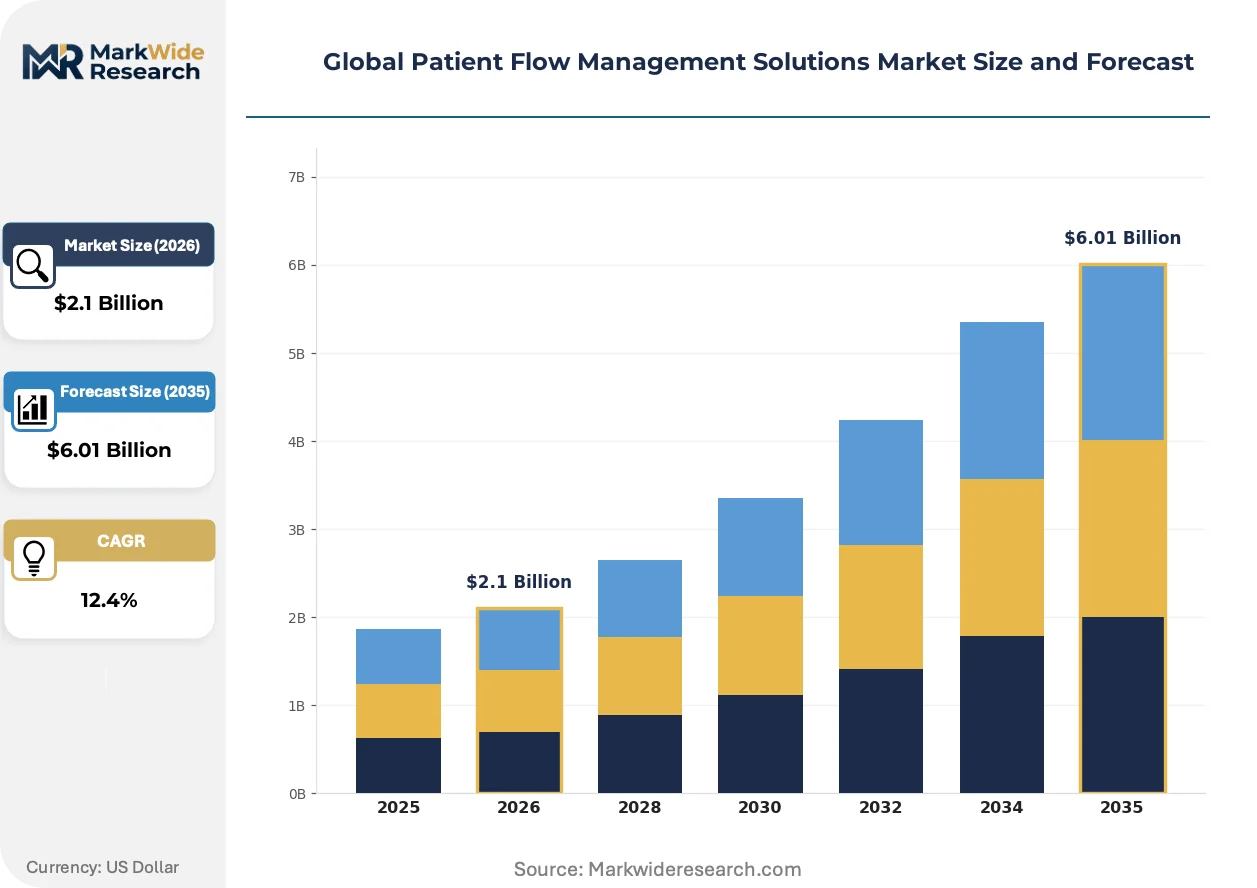
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.01 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Real-Time Location Systems, Bed Management, Queue Management, Appointment Scheduling, Resource Allocation, Staff Coordination Deployment Mode: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Application Use Case: Emergency Department, Outpatient Clinics, Surgical Scheduling, Patient Transport, Admission & Discharge, Diagnostic Services End User: Hospitals, Ambulatory Surgery Centers, Long-Term Care Facilities, Diagnostic Laboratories, Rehabilitation Centers |
| Companies Covered | McKesson Corporation, Epic Systems Corporation, Cerner Corporation, TeleTracking Technologies, CenTrak, Care Logistics, Central Logic, Allscripts Healthcare Solutions, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Flow Management Solutions Market Shifts & Advancements
Artificial intelligence is rewriting how hospitals anticipate demand surges, with machine learning models now ingesting weather patterns, viral surveillance data, and elective surgery schedules to predict census spikes forty-eight hours in advance.
Real-time location systems are fragmenting the hardware vendor landscape as semiconductor miniaturization allows RFID and BLE beacon manufacturers to bypass traditional infrared infrastructure specialists. Community hospitals in Texas and Florida are piloting sub-$50,000 location networks that previously required $400,000 capital commitments. This price compression is enabling independent rural facilities to match academic medical center visibility into patient movement patterns without IT department expansion.
The EU AI Act's risk classification framework for clinical decision support is forcing European vendors to reengineer predictive discharge algorithms with mandatory human-in-the-loop checkpoints. Germany's university hospitals are delaying deployments of fully automated bed assignment tools until Q3 2025 to accommodate documentation requirements. French health authorities through ANSM are requiring algorithmic impact assessments that add four-to-six months to product launch timelines.
Subscription pricing is displacing perpetual licenses as the dominant procurement model for patient flow platforms, with health systems prioritizing operational expenditure treatment over capital budget competition with imaging equipment. Large integrated delivery networks in California and New York are consolidating vendor relationships to secure enterprise-wide rate cards that bundle software, hardware, and implementation services. This concentration is squeezing regional resellers and forcing them toward specialized consulting roles in workflow optimization rather than license distribution.
Global Patient Flow Management Solutions Market Segmentation
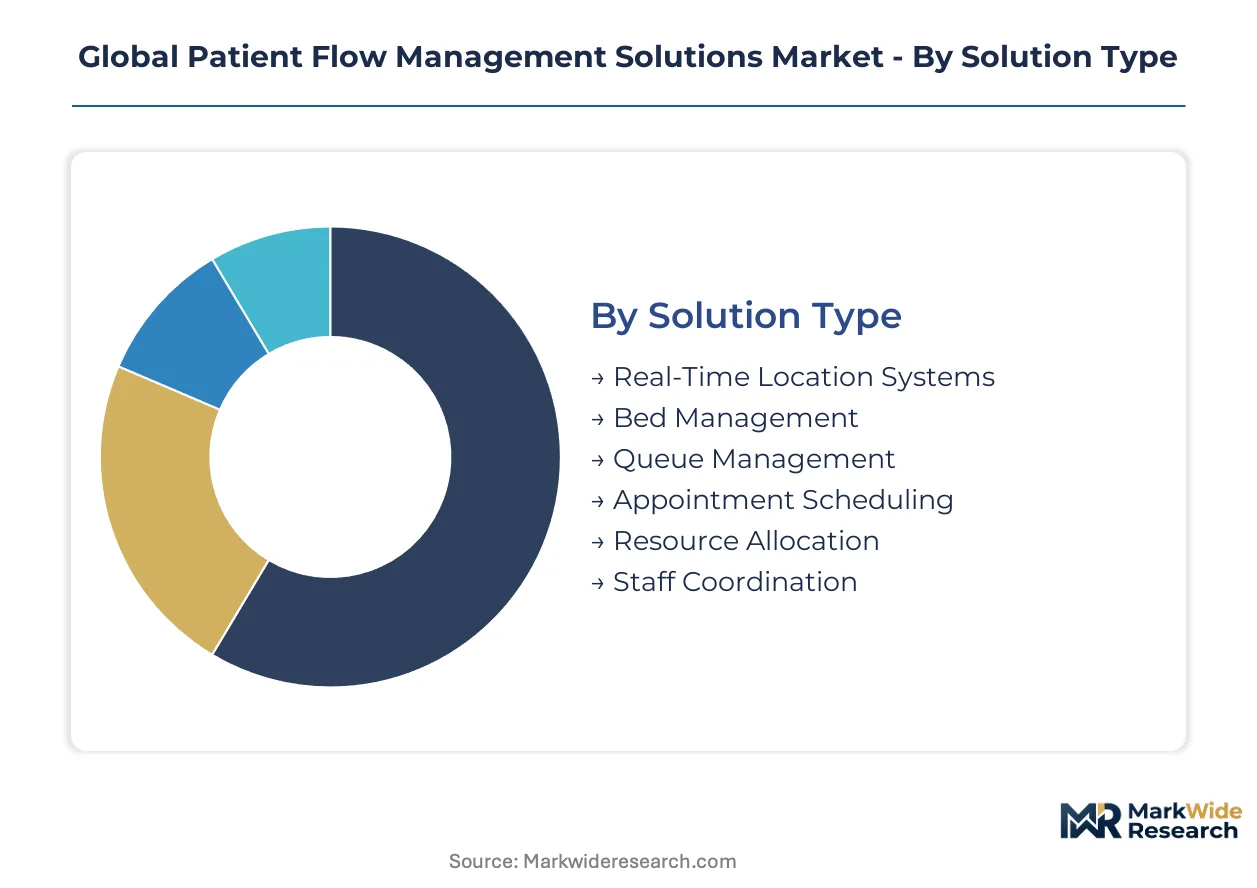
Patient flow management solutions fragment across multiple technical and operational dimensions. Solution architecture, infrastructure deployment, clinical application, and facility type each create distinct procurement patterns and vendor specialization zones.
Solution Type:
North American academic medical centers drive premium demand for integrated platforms, while Asian hospital networks prioritize modular point solutions for phased rollouts.
- Real-Time Location Systems:Bluetooth Low Energy mesh networks and RFID triangulation hardware track patient, staff, and asset positioning with sub-meter accuracy. Demand concentrates in Texas and Florida community hospitals where sub-$50,000 deployments now match academic medical center visibility. The steepest expansion runs through diagnostic services integration.
- Bed Management:Predictive bed-turn algorithms and automated capacity dashboards reduce emergency department boarding hours. German university hospitals are delaying fully automated tools until Q3 2025 to accommodate EU AI Act documentation requirements. Bed management commands the established base.
- Queue Management:Digital triage and wait-time optimization platforms streamline outpatient throughput.
- Appointment Scheduling:Intelligent slot allocation tools integrate surgical block calendars with resource availability.
- Resource Allocation:Dynamic matching of clinical staff, equipment, and physical space to real-time demand signals.
- Staff Coordination:Communication layers connecting nursing assignments with patient acuity and location data.
Real-time location systems command the established base. The steepest expansion runs through bed management predictive analytics.
Deployment Mode:
Cost tier stratification separates capital-intensive legacy infrastructure from operational expenditure cloud models favored by mid-size networks.
- Cloud-Based:Containerized microservices and API-first architectures compress deployment timelines from eighteen months to under ninety days. Health systems in California and New York prioritize elastic infrastructure over server farm capital commitments.
- On-Premise:Air-gapped installations serving military and rural hospitals with bandwidth constraints.
- Hybrid:Split architectures keeping sensitive patient data local while leveraging cloud analytics.
- Web-Based:Browser-accessible dashboards requiring minimal endpoint configuration.
- Mobile Application:Native iOS and Android tools for bedside clinicians and transport staff.
Cloud-based deployment commands the established base. The steepest expansion runs through hybrid configurations bridging compliance and scalability.
Use Case:
Application maturity varies sharply: emergency department solutions carry decade-long track records while diagnostic services integration remains nascent.
- Emergency Department:Boarding reduction and throughput optimization tools face CMS penalty pressure for prolonged length-of-stay metrics. Japan's aging population strains ED capacity, accelerating automated triage procurement in Tokyo and Osaka metropolitan hospitals.
- Outpatient Clinics:Appointment sequencing and room turnover optimization for high-volume specialty practices.
- Surgical Scheduling:Block time utilization and pre-admission workflow coordination.
- Patient Transport:Logistics platforms coordinating movement between units, imaging, and procedural areas.
- Admission & Discharge:Predictive discharge planning and bed request automation.
- Diagnostic Services:Imaging and laboratory queue optimization with equipment load balancing.
Emergency department solutions command the established base. The steepest expansion runs through diagnostic services workflow integration.
End User:
Customer type determines contract scale and integration complexity: integrated delivery networks consolidate vendors while independent facilities seek modular entry points.
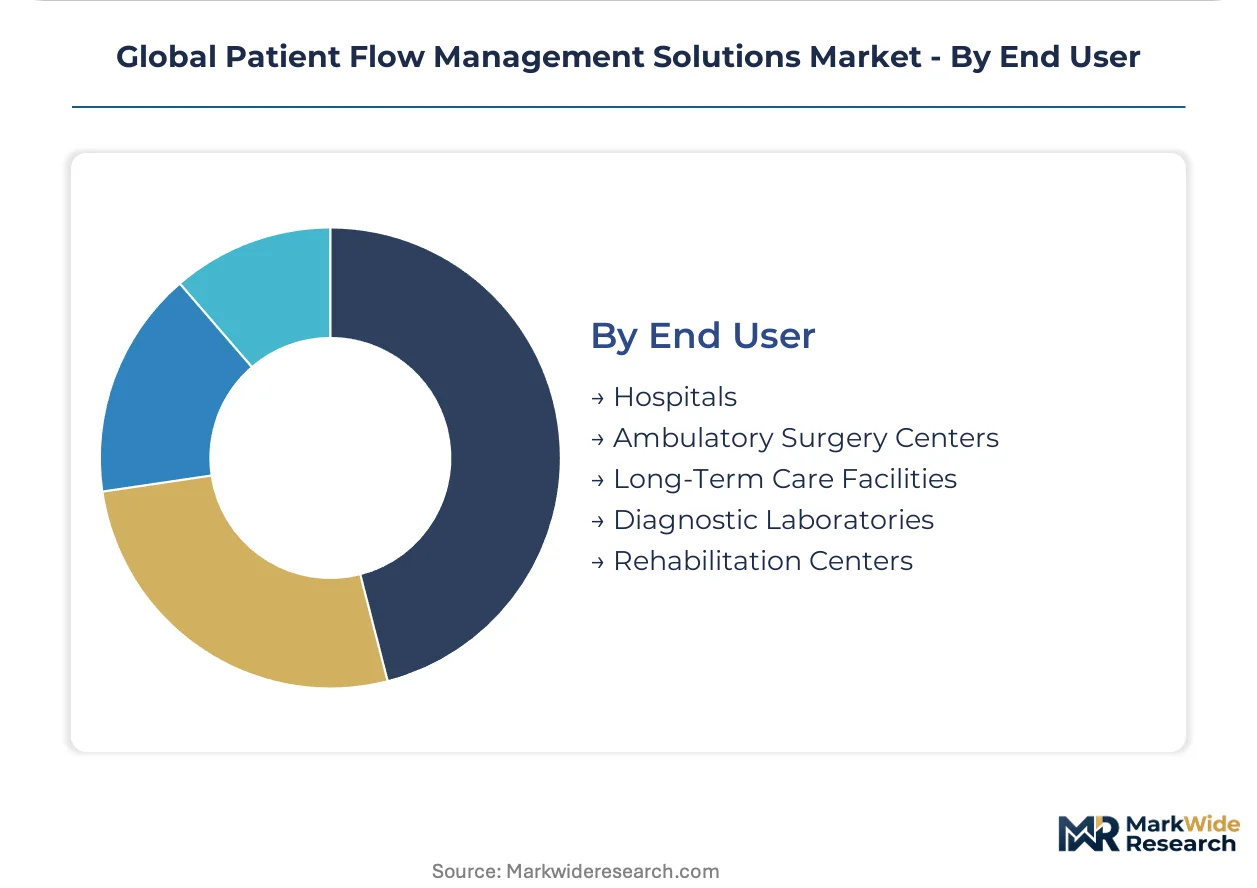
- Hospitals:Enterprise-wide capacity command centers requiring HL7 FHIR interoperability and HIPAA-compliant audit trails. FDA digital health software guidance shapes vendor qualification for federal reimbursement programs.
- Ambulatory Surgery Centers:Streamlined scheduling and rapid turnover tools for high-volume procedural facilities.
- Long-Term Care Facilities:Transition tracking extending flow visibility beyond acute care walls.
- Diagnostic Laboratories:Specimen tracking and equipment utilization optimization.
- Rehabilitation Centers:Therapy scheduling and patient progress coordination platforms.
Hospitals command the established base. The steepest expansion runs through long-term care facility integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deployment patterns diverge sharply by geography. United States health systems favor cloud-native capacity command centers with predictive analytics, while German hospitals prioritize on-premise architectures with mandatory human-in-the-loop checkpoints under EU AI Act risk classifications.
United States
Academic medical centers in Texas and Florida drive demand for sub-$50,000 Bluetooth Low Energy location networks that previously required $400,000 capital commitments. HIPAA Security Rule enforcement accelerates procurement of encrypted patient tracking systems with audit-ready access logs. Hospital networks in California and New York consolidate vendor relationships to secure enterprise-wide rate cards bundling software, hardware, and implementation services.
Germany
University hospitals delay fully automated bed assignment tools until Q3 2025 to accommodate EU AI Act documentation requirements for algorithmic audit trails. ANSM and federal health authorities mandate impact assessments that add four-to-six months to product launch timelines. The Baden-Württemberg and Bavaria clusters concentrate pilot deployments of explainable AI documentation services around predictive discharge algorithms.
Japan
Aging populations in Tokyo and Osaka metropolitan areas strain emergency department capacity, accelerating automated triage procurement. METI digital health infrastructure programs subsidize interoperability investments for mid-size community hospitals. The Kanto region anchors demand for real-time location systems processing patient movement patterns across hospital networks.
United Kingdom
NHS trusts prioritize queue management and outpatient throughput optimization to reduce elective surgery backlogs. GDPR cross-border data restrictions shape vendor qualification for platforms processing patient transitions across integrated care systems. The London-Southeast corridor concentrates deployments of digital triage platforms streamlining specialty practice workflows.
India
Private hospital chains in Maharashtra and Karnataka pilot modular point solutions for phased rollouts rather than integrated enterprise platforms. CDSCO digital health software guidance and hospital accreditation requirements drive demand for HL7 FHIR-compliant tracking systems. The Delhi-NCR cluster attracts vendor implementation partnerships targeting mid-tier facility automation.
Global Patient Flow Management Solutions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with EHR incumbents leveraging entrenched footprints to bundle flow optimization modules while pure-play vendors dominate real-time capacity command centers at academic medical centers. The market structure rewards deep workflow integration over standalone functionality. Three archetypes prevail: electronic health record platform extenders, real-time location infrastructure specialists, and capacity command center pure-plays. Competitive intensity concentrates on strategic partnerships with health system IT departments and API-first interoperability certifications that unlock federal reimbursement program eligibility.
Within the EHR-platform-extender tier, Epic Systems Corporation and Cerner Corporation occupy positions that anchor workflow integration between scheduling, bed management, and clinical documentation. TeleTracking Technologies exemplifies the capacity command center pure-play archetype, with deployments concentrated at large academic medical centers requiring sub-meter location accuracy. These three entities represent the dominant competitive anchors against which mid-tier specialists and regional resellers position workflow optimization consulting services.
| Leading Market Players |
|---|
| McKesson Corporation |
| Epic Systems Corporation |
| Cerner Corporation |
| TeleTracking Technologies |
| CenTrak |
| Care Logistics |
| Central Logic |
| Allscripts Healthcare Solutions |
| Oracle |
| Others |
Supply & Pricing Matrix
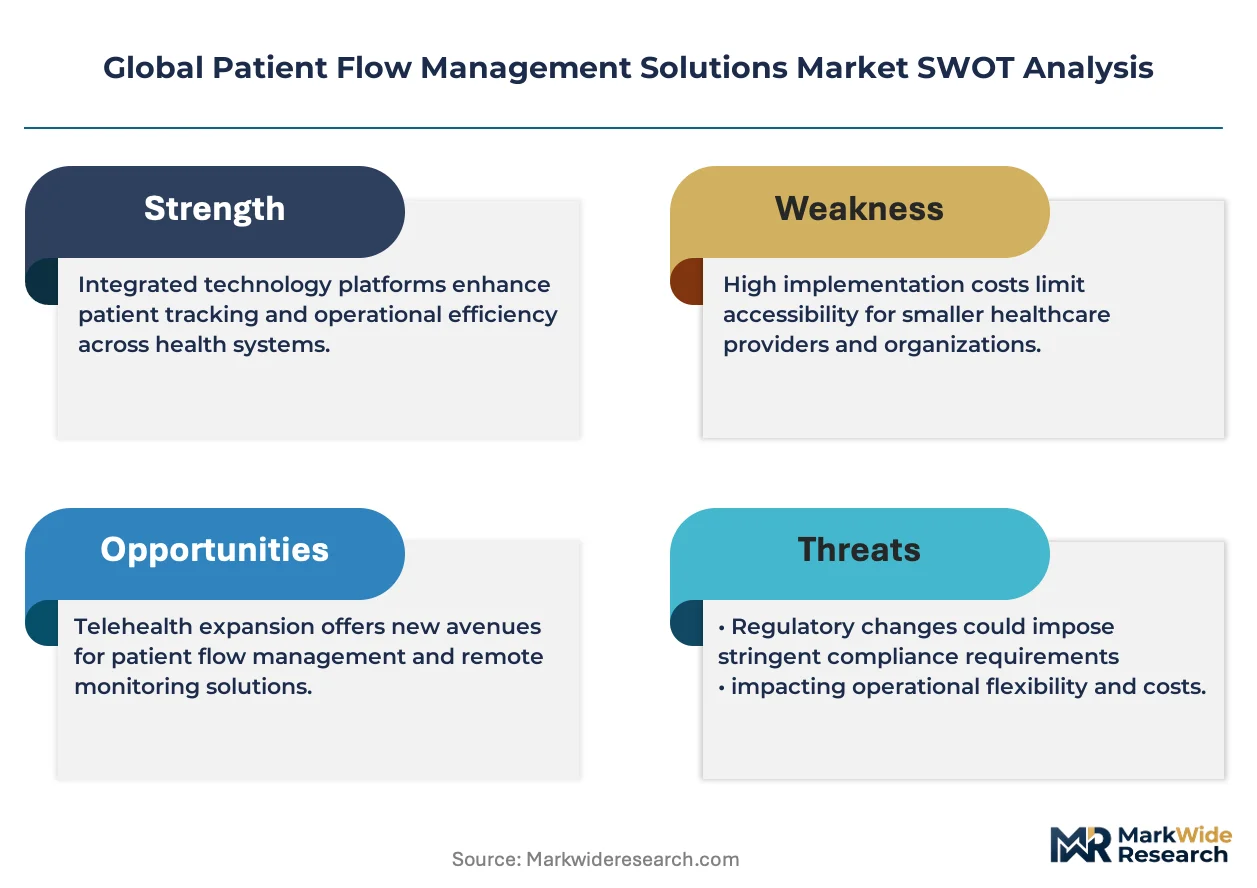
FDA digital health software guidance and HIPAA Security Rule enforcement gate both vendor qualification and price differentiation in patient flow management platforms. Health systems disqualify uncertified suppliers while paying premiums for audit-ready systems with encrypted tracking infrastructure.
Pricing Analysis
Long-term enterprise subscription contracts dominate procurement, displacing perpetual licenses as health systems prioritize operational expenditure treatment. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with predictive analytics bundles from community hospitals with basic bed management modules. Cost compression in the standard tier intensifies because Bluetooth Low Energy hardware miniaturization slashes deployment costs. Community hospitals exhibit highest price sensitivity, while integrated delivery networks in California and New York leverage volume consolidation for enterprise rate cards.
Supply Chain Analysis
Inventory cycles for RFID tags and BLE beacon hardware have compressed from twelve weeks to under four weeks as semiconductor foundries in Taiwan and South Korea expand capacity. Component sourcing draws from NVIDIA edge inference chips, Qualcomm Bluetooth modules, and Nordic Semiconductor mesh network controllers. Single-source vulnerability concentrates in Taiwan's foundry ecosystem, exposing vendors to geopolitical disruption of sub-meter location accuracy hardware. Distribution runs through health system IT procurement committees and GPO contracts rather than traditional software channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient flow management sits in early-cycle expansion as cloud migration compresses deployment timelines from eighteen months to under ninety days. Bluetooth Low Energy mesh networks unlock mid-size hospital segments previously blocked by capital constraints.
For Market Incumbents: Consolidate API-first interoperability certifications to lock federal reimbursement program eligibility before ONC testing backlogs clear. Deepen vertical integration into edge computing hardware through partnerships with NVIDIA and Qualcomm, neutralizing specialist RTLS vendors. Bundle workflow optimization consulting services to offset margin pressure from subscription pricing displacement.
For New Entrants and Emerging Players: ONC HL7 FHIR R4 fast-track certification opens procurement shortlists at mid-size community hospitals in Texas and Florida. Target long-term care facility integration as the most penetrable segment, extending flow visibility beyond acute care walls where EHR incumbents lack presence. Pursue EU AI Act compliance documentation services as a consulting wedge around German university hospital deployments.
For Investors and Strategic Acquirers: CMS inpatient prospective payment system reforms reshape the acquisition landscape by elevating throughput automation ROI against labor expansion. Five-to-ten year viability favors capacity command center pure-plays with real-time location infrastructure over EHR-extender commoditization. Watch CMS penalty enforcement intensity as the signal for hospital automation procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner leverage entrenched EHR footprints to bundle flow optimization modules into existing hospital contracts. |
| Regulatory Certification Pathway | ONC HL7 FHIR R4 interoperability certification unlocks federal reimbursement program eligibility and health system shortlists. |
| Strategic Partnership | TeleTracking Technologies anchors large academic medical center deployments through real-time capacity command center specialization. |
| Acquisition of Specialist Firm | Regional resellers pivot toward workflow optimization consulting as vendor consolidation squeezes license distribution margins. |
| Geographic Expansion | Community hospitals in Texas and Florida pilot sub-$50,000 BLE location networks enabling rural facility automation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital CIOs, nursing informatics specialists, GPO contracts managers, and biomedical engineers; and secondary validation through FDA 510(k) filings, CMS Medicare cost reports, hospital procurement databases, and ONC interoperability certification records. Bottom-up triangulation across deployment volume estimates and top-down reconciliation against health system IT expenditure patterns anchored market sizing.
Across the analysis window, forecasts model solution type, deployment mode, clinical use case, and facility tier segmentation. CAGRs derive from elasticity-adjusted adoption curves and hardware cost compression trajectories. Inputs include Bluetooth Low Energy pricing trends, cloud infrastructure capex disclosures from hyperscalers, and EU AI Act implementation timelines affecting algorithmic deployment.
Decision-makers should treat outputs as directional under assumptions of continued HIPAA enforcement intensity and stable semiconductor supply; material deviation in regulatory penalty structures or foundry capacity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Epharmacy Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Neurosurgery Software Market