
 Middle East and Africa Critical Care Equipment (CCE) Market | 2026-2036
Middle East and Africa Critical Care Equipment (CCE) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Critical Care Equipment (CCE) Market Foresight
ISO 13485 certification is rotating as the primary gating mechanism for market access across the Middle East and Africa, filtering out distributors lacking quality management documentation. Hamilton Medical AG leverages its Swiss manufacturing pedigree to sustain premium positioning in Gulf Cooperation Council tenders. Mindray Medical International Limited anchors volume supply through competitive pricing for public hospital systems in North Africa. Drägerwerk AG & Co. KGaA differentiates via integrated perioperative workflow systems that extend beyond standalone device sales.
Critical Care Equipment encompasses life-support apparatus engineered to sustain organ function during acute physiological failure, with ventilators typically delivering precision gas mixtures at pressure ranges of 5-40 cm H₂O and infusion pumps administering medications within 0.1-999 mL/hour tolerances. These systems serve the primary commercial purpose of reducing mortality in emergency and perioperative settings where patient hemodynamics destabilize unpredictably. Ventilators command the largest installed base across the region, though digital monitoring systems incorporating wireless telemetry represent the fastest-expanding margin pool as hospitals pursue centralized patient data architectures. Intensive care applications absorb the majority of capital expenditure, while home care emerges as a structurally underpenetrated channel where automated infusion technology could unlock new reimbursement pathways.
Saudi Food and Drug Authority registration protocols, UAE Ministry of Health and Prevention import licensing, and South African Health Products Regulatory Authority conformity assessments collectively elevate compliance costs for non-domestic manufacturers while creating protected demand windows for pre-qualified suppliers. These frameworks shape procurement by mandating Arabic-language labeling, local technical service presence, and post-market surveillance infrastructure that smaller distributors struggle to fund. Stakeholders must weigh the capital requirements of multi-jurisdiction regulatory maintenance against the concentration risk of over-dependence on single-country tender pipelines.
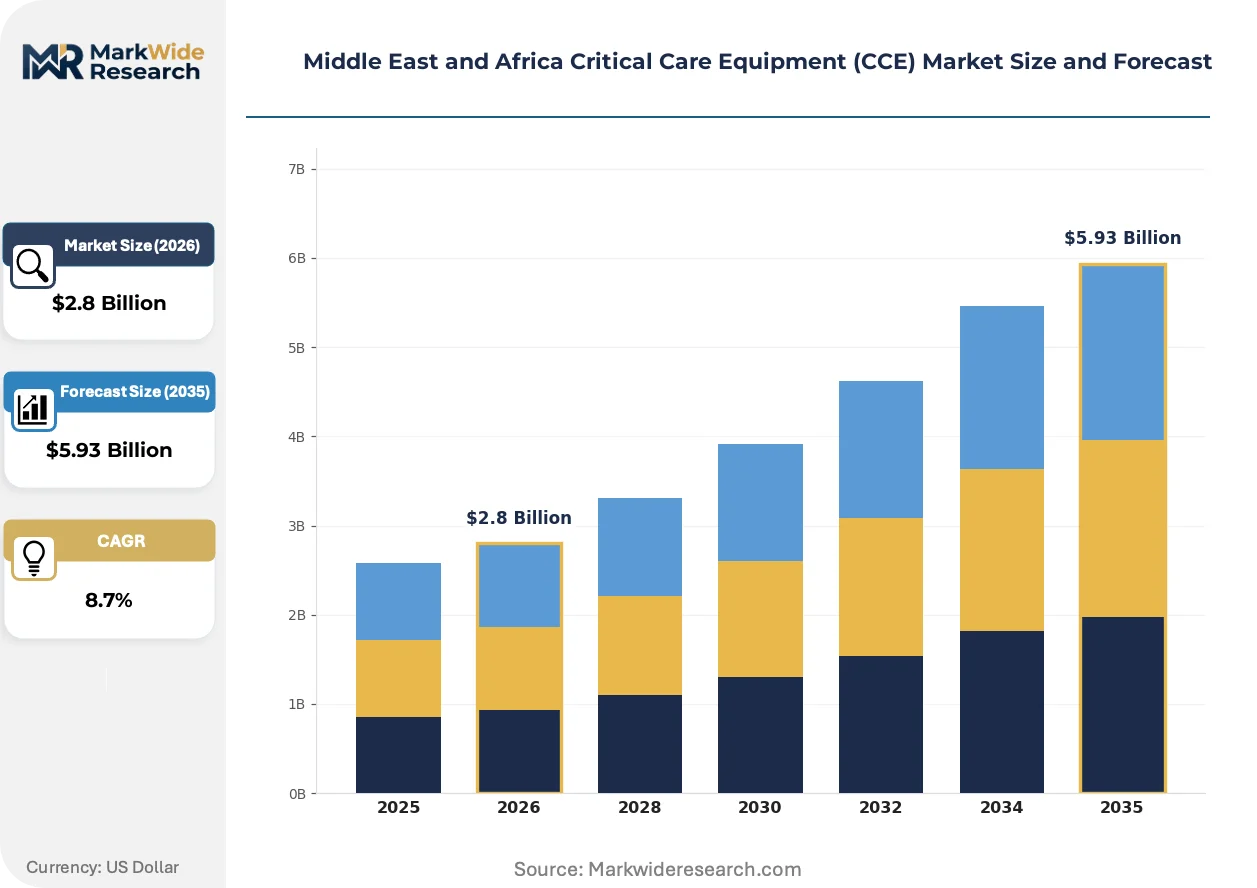
Market Dynamics
SFDA registration protocols are compressing market access timelines while simultaneously elevating capital requirements for non-domestic manufacturers, creating a bifurcation between pre-qualified suppliers and distributors lacking ISO 13485 documentation.
Growth Catalysts
- Egypt's public sector modernization:Cairo's Ministry of Health and Population is replacing legacy anesthesia workstations across 47 central hospitals, generating concentrated tender volume for ventilator and patient monitoring systems.
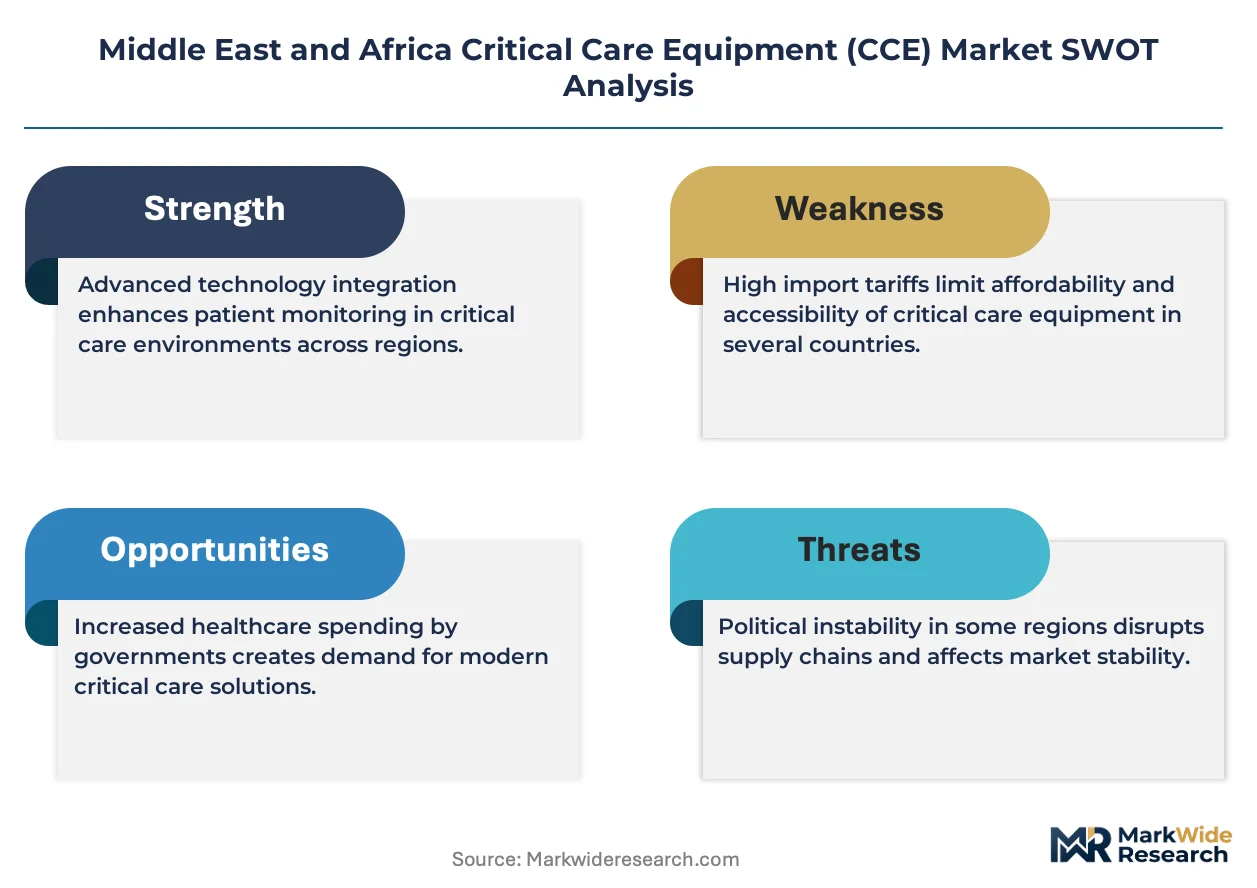
- MDR-equivalent alignment:Gulf Cooperation Council harmonization with European Medical Device Regulation technical standards is accelerating CE-marked product acceptance in Saudi Arabia and the UAE, reducing duplicate certification burdens.
- Wireless telemetry integration:Tertiary hospitals in Johannesburg and Cape Town are deploying centralized patient data architectures that pull real-time hemodynamic feeds from bedside monitors to nursing stations.
Market Restraints
- Import duty volatility:Egyptian customs authorities impose fluctuating tariff schedules on electromedical equipment, creating margin unpredictability for distributors serving Alexandria and Delta region hospitals.
- Single-source component dependency:Precision pressure sensors for ventilator manufacturing concentrate among German and Swiss suppliers, exposing regional assemblers to euro-denominated input cost swings.
- Biomedical engineering scarcity:Nigeria and Kenya produce fewer than 200 certified clinical engineers annually, constraining deployment velocity for multi-parameter monitoring systems requiring localized calibration protocols.
Strategic Opportunities
- Morocco's underpenetrated home care channel:Casablanca's private insurance networks are piloting reimbursement codes for automated infusion pumps in post-acute settings, potentially unlocking outpatient revenue streams.
- AI-enabled predictive alarms:Machine learning integration with multiparameter monitors is reducing false-positive alert fatigue in Saudi Arabian ICU environments, differentiating premium system vendors.
- Ethiopia's diagnostic infrastructure buildout:Addis Ababa's Health Transformation Initiative is creating demand for portable ventilators and transport monitors across 250 newly constructed primary hospitals.
Industry Challenges
- SFDA post-market surveillance compliance:Saudi Arabia mandates Arabic-language adverse event reporting within 72 hours, requiring distributors to maintain dedicated regulatory affairs staff that smaller operators cannot fund.
- Legacy system interoperability:South African private hospital networks operate heterogeneous device fleets from multiple vintages, complicating centralized data aggregation and nurse training standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Critical Care Equipment (CCE) Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Infusion Pumps, Monitors, Defibrillators Application: Emergency Care, Surgical Procedures, Intensive Care, Anesthesia End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Mechanical Ventilation, Digital Monitoring, Wireless Systems, Automated Infusion |
| Companies Covered | Getinge AB, Baxter International Inc., Philips Healthcare, Hamilton Medical AG, Fresenius Kabi AG, GE Healthcare, Medtronic plc, Mindray Medical International Limited, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Critical Care Equipment (CCE) Market Shifts & Advancements
Digital integration and portable form factors are compressing traditional equipment categories while regulatory harmonization accelerates product lifecycle velocity across Gulf and North African markets.
Mems-based pressure transducers are replacing conventional pneumatic sensors in next-generation ventilators, enabling closed-loop control algorithms that adjust tidal volume within breath cycles. Saudi Arabian military hospitals and UAE federal medical centers are piloting these systems for field-deployable critical care. The technology is miniaturizing ventilator footprints from cart-based units to backpack-portable configurations, expanding use cases beyond fixed ICU installations.
SFDA's 2023 medical device guidance document mandates local technical service presence and spare parts warehousing for Class III life-support equipment, effective across all Saudi Arabian import channels. This regulatory friction is advantaging distributors with existing Jeddah and Riyadh logistics infrastructure while disqualifying remote-service models. Ventilator and anesthesia workstation categories face the steepest compliance cost escalation, prompting consolidation among import agents.
Hospital procurement committees in Dubai and Abu Dhabi are unbundling after-sales service contracts from capital equipment purchases, creating standalone multi-vendor maintenance agreements. This behavioral shift is compressing OEM service margins while elevating third-party biomedical engineering firms specializing in cross-brand repair capabilities. The pattern is most visible among UAE Ministry of Health and Prevention facilities transitioning to total cost of ownership evaluation frameworks.
Middle East and Africa Critical Care Equipment (CCE) Market Segmentation
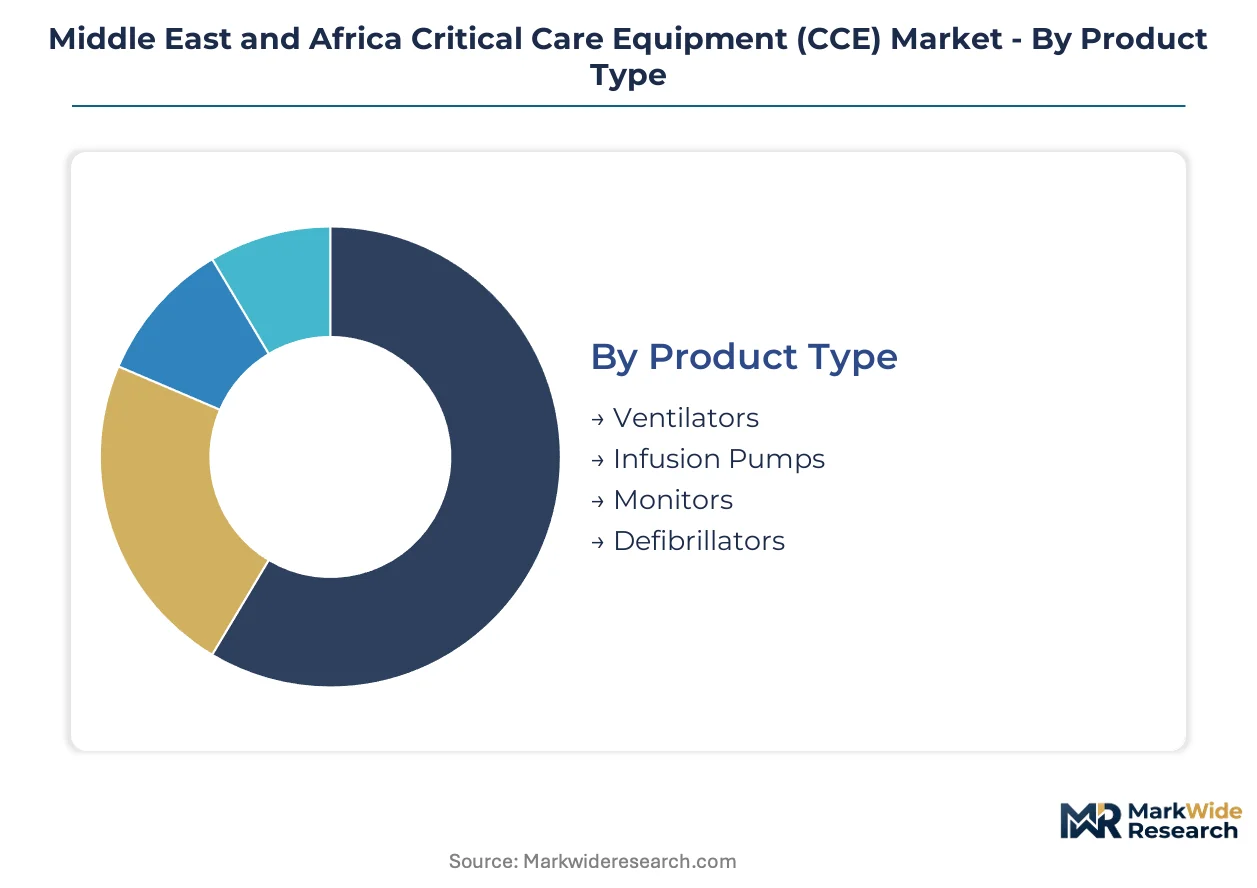
Critical care equipment procurement patterns diverge sharply across Middle East and Africa markets, with Gulf Cooperation Council hospitals prioritizing premium integrated systems while North African public sectors optimize for unit economics. Understanding these segment-specific demand drivers enables suppliers to align certification investments and service infrastructure with actual purchasing authority.
Product Type:
Ventilator demand concentrates in Saudi Arabian and Emirati tertiary hospitals requiring advanced modes, while infusion pump procurement spreads across Egypt's public hospital modernization and South African private networks.
- Ventilators:These systems deliver precision gas mixtures across pressure ranges of 5-40 cm H₂O with closed-loop control algorithms now standard in Gulf military hospitals. Demand clusters in Saudi Arabian ICU expansions and UAE federal medical centers piloting field-deployable configurations.
- Infusion Pumps:Devices administering medications within 0.1-999 mL/hour tolerances serve perioperative and post-acute applications. Cairo's Ministry of Health and Population tender activity for 47 central hospitals is driving concentrated volume for syringe and volumetric pump categories.
- Monitors:Multi-parameter systems with wireless telemetry capability anchor Johannesburg and Cape Town hospital digitization initiatives.
- Defibrillators:Biphasic waveform devices with automated external operation modes penetrate emergency departments across Nigerian and Kenyan referral hospitals.
Ventilators hold the largest share; momentum sits with monitors gaining share fastest through centralized patient data architectures.
Application:
Intensive care applications absorb the majority of capital expenditure across the region, though reimbursement pilot programs are opening post-acute channels previously closed to equipment suppliers.
- Intensive Care:Hemodynamic instability management in tertiary hospital settings requires continuous organ support with predictive alarm integration. Saudi Arabian SFDA registration protocols for Class III life-support equipment create protected demand windows for pre-qualified ventilator and anesthesia workstation suppliers.
- Emergency Care:Resuscitation and stabilization protocols in trauma bays demand rapid-deployment equipment with minimal calibration requirements. Ethiopian Health Transformation Initiative construction of 250 primary hospitals is generating transportable ventilator and monitor demand in Addis Ababa and regional capitals.
- Surgical Procedures:Perioperative anesthesia workstations face replacement cycles in Egypt's central hospital network.
- Anesthesia:Integrated gas delivery systems with patient monitoring convergence serve operating theater renovations across Gulf Cooperation Council countries.
Intensive care dominates installed base value; emergency care shows steepest expansion trajectory through primary hospital infrastructure buildout.
End User:
Hospital procurement committees command decision authority, though home care channel development in Maghreb private insurance markets is creating alternative access routes bypassing centralized tender processes.
- Hospitals:Tertiary and secondary acute care facilities operate centralized procurement through ministry-level tenders or private network standardization. Dubai and Abu Dhabi facilities are unbundling after-sales service contracts from capital purchases, elevating third-party biomedical engineering firms with cross-brand repair capabilities.
- Home Care:Post-acute settings including sub-acute facilities and residential care are piloting automated infusion reimbursement codes. Casablanca's private insurance networks are testing coverage frameworks that could unlock outpatient revenue streams for portable pump technology.
- Clinics:Ambulatory surgical centers and specialty practices require compact monitoring configurations with simplified operation protocols.
- Rehabilitation Centers:Long-term ventilator weaning and respiratory therapy facilities need durable equipment with extended service intervals.
Hospitals retain dominant procurement volume; home care is climbing the fastest as reimbursement pilots expand addressable patient populations.
Technology:
Digital integration architectures are compressing traditional equipment categories, with wireless telemetry and automated control systems displacing standalone mechanical platforms in premium hospital segments.
- Digital Monitoring:Centralized patient data architectures pull real-time hemodynamic feeds from bedside devices to nursing stations, reducing response latency. Johannesburg and Cape Town tertiary deployments are establishing reference implementations for sub-Saharan African hospital digitization.
- Automated Infusion:Closed-loop medication delivery with dose error reduction software integrates pharmacy information systems at the point of care. Morocco's reimbursement pilot programs for post-acute settings are creating initial demand penetration for smart pump technology outside hospital walls.
- Mechanical Ventilation:Pneumatic and electronic ventilator platforms with invasive and non-invasive capability serve the core installed base.
- Wireless Systems:Telemetry-enabled transport monitors and wearable sensors extend monitoring continuity beyond fixed ICU installations.
Digital monitoring captures the largest technology investment; automated infusion is gaining share fastest through safety protocol standardization and reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SFDA registration protocols and the UAE's MOHAP import licensing frameworks are elevating compliance thresholds across Gulf Cooperation Council markets, channeling procurement toward pre-qualified suppliers with established local technical service infrastructure.
Saudi Arabia
Tertiary hospital ICU expansions in Riyadh and Jeddah are driving concentrated demand for advanced ventilator and anesthesia workstation categories. The SFDA's 2023 medical device guidance mandates Arabic-language labeling and 72-hour adverse event reporting, filtering out distributors lacking dedicated regulatory affairs staff. Eastern Province military hospitals are piloting field-deployable critical care configurations with MEMS-based pressure transducer technology.
United Arab Emirates
Dubai and Abu Dhabi procurement committees are unbundling after-sales service contracts from capital equipment purchases, elevating third-party biomedical engineering firms with cross-brand repair capabilities. MOHAP facilities are transitioning to total cost of ownership evaluation frameworks that compress OEM service margins. Federal medical centers in Al Ain are deploying centralized patient data architectures pulling real-time hemodynamic feeds to nursing stations.
South Africa
Private hospital networks in Johannesburg and Cape Town are standardizing wireless telemetry-enabled monitoring systems across heterogeneous device fleets from multiple vintages. The South African Health Products Regulatory Authority's conformity assessments for Class III life-support equipment create protected demand windows for ISO 13485-certified suppliers. Western Cape tertiary facilities are establishing reference implementations for sub-Saharan African hospital digitization initiatives.
Egypt
Cairo's Ministry of Health and Population is replacing legacy anesthesia workstations across 47 central hospitals, generating tender volume for syringe and volumetric pump categories. Fluctuating customs tariff schedules on electromedical equipment create margin unpredictability for distributors serving Alexandria and Delta region hospitals. Giza's central hospital cluster is absorbing the majority of public sector modernization capital expenditure for perioperative systems.
Morocco
Casablanca's private insurance networks are piloting reimbursement codes for automated infusion pumps in post-acute settings, potentially unlocking outpatient revenue streams previously closed to equipment suppliers. The underpenetrated home care channel is climbing fastest as coverage frameworks test portable pump technology outside hospital walls. Rabat's regulatory alignment with European Medical Device Regulation technical standards is accelerating CE-marked product acceptance and reducing duplicate certification burdens.
Middle East and Africa Critical Care Equipment (CCE) Market Competitive Landscape
Player mix skews toward European and North American multinationals with established Gulf logistics infrastructure, creating tiered access where SFDA pre-qualification separates incumbent suppliers from aspirant entrants. Market structure concentrates around premium integrated system vendors and volume-optimized equipment specialists, with limited mid-tier presence. Two strategic archetypes dominate: Swiss-German precision manufacturers leveraging manufacturing pedigree for tender positioning, and Asia-Pacific scale players anchoring public hospital procurement through competitive unit economics. Consolidation is accelerating through distributor acquisitions and local technical service buildouts.
Within the premium-tier vector, Hamilton Medical AG and Drägerwerk AG & Co. KGaA exemplify European precision manufacturing archetypes that occupy protected positions in military and federal hospital tenders. Mindray Medical International Limited represents the volume-optimized specialist model, anchoring North African public sector procurement through price-competitive positioning. Getinge AB sits within the integrated perioperative workflow tier, where service unbundling trends are compressing traditional equipment-margin structures. These three company types collectively illustrate how regulatory pre-qualification and local infrastructure requirements are reshaping competitive access across Middle East and Africa markets.
| Leading Market Players |
|---|
| Getinge AB |
| Baxter International Inc. |
| Philips Healthcare |
| Hamilton Medical AG |
| Fresenius Kabi AG |
| GE Healthcare |
| Medtronic plc |
| Mindray Medical International Limited |
| Drägerwerk AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Ninety-day inventory buffers for precision pressure sensors expose regional assemblers to euro-denominated input volatility while concentrating pricing power with German and Swiss component suppliers who serve pre-qualified ventilator manufacturers.
Pricing Analysis
Certification level creates the primary spread across ventilator and anesthesia workstation categories, with ISO 13485 and CE-marked products commanding substantial premiums over uncertified alternatives in Saudi Arabian SFDA-regulated tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales bundling and local technical service presence, with Dubai and Abu Dhabi procurement committees unbundling maintenance contracts to compress OEM margins. Cost compression in mid-tier segments intensifies because Mindray Medical International Limited anchors volume supply through competitive unit economics for North African public hospital systems. Public sector tender participants in Egypt and Ethiopia exhibit highest price sensitivity, while Gulf Cooperation Council military and federal medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor precision pressure sensor and pneumatic component manufacturing for ventilator assembly, with MEMS-based transducer production concentrating among specialized semiconductor foundries in these jurisdictions. Regional equipment assemblers in Saudi Arabia and the UAE draw from euro-denominated input streams for critical sensing elements, Swiss-manufactured control valves, and German-sourced gas delivery modules. Single-source dependency for precision pressure sensors exposes regional supply chains to currency fluctuation and geopolitical logistics disruption. Distribution runs through Jeddah and Riyadh logistics hubs for Saudi Arabian market access, with Dubai serving as re-export gateway for sub-Saharan African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centralized patient data architectures across Johannesburg and Cape Town tertiary hospitals signal a platform-economics inflection, where interoperability standards and wireless telemetry integration reshape competitive positioning beyond standalone device specifications.
For Market Incumbents: Compound defensive positioning through backward integration into MEMS-based pressure transducer supply chains and captive technical service infrastructure in Riyadh and Jeddah. Emerging Asia-Pacific scale players threaten premium-tier positioning through price-competitive tenders in Egypt and Ethiopia. Certification maintenance and Arabic-language adverse event reporting capabilities serve as the priority defensive lever against distributor consolidation. For New Entrants and Emerging Players: SFDA registration fast-tracks for Class III life-support equipment create immediate access pathways for CE-marked manufacturers already compliant with European Medical Device Regulation technical standards. Morocco's underpenetrated home care channel and Ethiopia's diagnostic infrastructure buildout represent the most penetrable white-space targets. Reimbursement pilot partnerships with Casablanca private insurance networks offer a specific go-to-market angle bypassing centralized hospital tender processes. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SFDA pre-qualification and local technical service mandates create protected demand windows with substantial switching costs. Acquisition targets should profile as ISO 13485-certified distributors with established Jeddah or Riyadh logistics infrastructure and existing hospital system relationships. The signal to watch is SFDA guidance document revisions expanding local spare parts warehousing requirements to additional equipment categories.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway | Arabic-language labeling and 72-hour adverse event reporting mandates filter out undercapitalized distributors. |
| Hospital System Partnership | Dubai and Abu Dhabi procurement committees unbundling service contracts elevate third-party biomedical engineering firms. |
| Software Companion Development | AI-enabled predictive alarm integration with multiparameter monitors differentiates premium system vendors in Saudi Arabian ICUs. |
| CE Marking Alignment | Gulf Cooperation Council harmonization with European Medical Device Regulation standards reduces duplicate certification burdens. |
| Reimbursement Strategy | Casablanca private insurance pilots for automated infusion pumps in post-acute settings unlock outpatient revenue streams. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings, with secondary validation drawing from SFDA medical device guidance documents, hospital procurement databases, and CE marking certification records. Bottom-up and top-down triangulation reconciles distributor shipment data with ministry-level tender announcements across Saudi Arabia, UAE, Egypt, and South Africa.
Sensitivity analysis across ventilator, infusion pump, monitor, and anesthesia workstation categories tests forecast robustness over the projection horizon, with segmentation dimensions spanning product type, application intensity, end-user channel, and technology integration level. CAGRs derive from installed base replacement cycles, ICU expansion pipelines, and reimbursement expansion trajectories, with wireless telemetry adoption curves and home care channel development serving as critical forecast inputs.
Underlying assumptions cover SFDA regulatory stability, euro-Saudi riyal exchange rate bands, and Egyptian customs tariff predictability, with deviation risk concentrated in import duty volatility and biomedical engineering scarcity constraining deployment velocity. Recalibration cycles align with material shifts in Gulf Cooperation Council harmonization timelines and Moroccan reimbursement pilot expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Equipment
Acute Care Hospital Bed and Stretcher Market
Clinical Equipment
Patient Simulator Market
Clinical Equipment
Hong Kong Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Portable Clinical Analyzer Market
Clinical Equipment
Global Phototherapy Equipment Market
Clinical Equipment
Acute Care Needleless Connectors Market
Clinical Equipment
Critical Care Equipment Market
Clinical Equipment
Patient Handling Equipment Market
Clinical Equipment
Hydrotherapy Equipment Market
Clinical Equipment
Patient Positioning Equipment Market
Clinical Equipment
China Intensive Care Unit (ICU) Beds and Surfaces Market
Clinical Equipment
Total Lab Automation Market
Clinical Equipment
Biofeedback Equipment Market
Clinical Equipment
Clinical Trial Equipment and Ancillary Solutions Market