
 IP-Based Nurse Call System Market | 2026-2036
IP-Based Nurse Call System Market Size, Share, and Industry Trends Forecast 2026-2036
IP-Based Nurse Call System Market Insights
UL 1069 certification-grade hardware is rotating into standard procurement specifications across North American health systems. Hillrom Holdings Inc. leverages its bedside device integration portfolio to anchor enterprise contracts. Rauland-Borg Corporation specializes in custom workflow software layers that differentiate its offerings in long-term care. Ascom Holding AG dominates European VoIP nurse call deployments through its alarm management middleware.
An IP-based nurse call system transmits patient-initiated alerts over Internet Protocol networks using Ethernet or Wi-Fi infrastructure, typically supporting audio communication, location tracking, and integration with electronic health records through HL7 or FHIR interfaces. The primary purpose is reducing response latency while creating auditable data trails for clinical workflow optimization. Wireless Solutions and Cloud-Based technology are capturing the fastest expansion as hospitals seek to bypass copper wiring limitations in aging infrastructure. Alarm Management Solutions command premium positioning by filtering false alerts and routing prioritized signals to specific caregiver roles. Digital Systems remain the volume backbone for new hospital construction, while Hybrid Systems serve the substantial retrofit segment where legacy analog endpoints must coexist with IP backbones.
FDA guidance on medical device interoperability, HIPAA security standards for networked patient data, and Joint Commission alarm safety goals collectively mandate encrypted, traceable communication architectures that only IP platforms deliver at scale. UL 1069 and IEC 60601-1-8 compliance requirements further narrow vendor qualification, advantaging manufacturers with established testing regimes. Stakeholders must evaluate whether their current infrastructure can absorb software-defined nurse call upgrades or whether greenfield cloud deployments offer lower total cost of ownership over a fifteen-year equipment lifecycle.
Market Dynamics
Cloud-connected nurse call platforms are decomposing the traditional capital equipment sales model, forcing vendors to restructure around recurring software revenue streams and API-driven integration ecosystems.
Growth Catalysts
- FDA Interoperability Guidance:The FDA's medical device interoperability framework mandates encrypted data exchange standards that only IP-native architectures satisfy, accelerating hospital upgrade cycles.
- Acute Care Hospital Consolidation:Multi-facility health systems in the United States are standardizing on single-vendor enterprise contracts to reduce operational complexity across distributed campuses.
- Wi-Fi 6 Infrastructure:Dense wireless coverage in aging hospital buildings eliminates copper rewiring costs, enabling rapid deployment of wireless nurse call endpoints without construction disruption.
Market Restraints
- Copper Legacy Embeddedness:Decades-old analog wiring in long-term care facilities creates path dependency, forcing hybrid system investments that delay full IP migration.
- UL 1069 Certification Bottleneck:Extended testing timelines for safety-critical hardware limit vendor throughput and compress margins for smaller manufacturers lacking established testing regimes.
- HIPAA Security Rule Compliance:Networked patient data transmission requires specialized cybersecurity infrastructure that raises total cost of ownership for budget-constrained rural hospitals.
Strategic Opportunities
- Long-Term Care Underpenetration:Skilled nursing facilities in the United States remain predominantly analog, representing a conversion-ready installed base for wireless retrofit solutions.
- Alarm Management Middleware:Convergence of nurse call systems with real-time location services and clinical communication platforms creates new subscription revenue pools.
- Joint Commission Alarm Safety Goals:Mandates for alert prioritization and fatigue reduction drive demand for intelligent filtering software layered atop existing hardware investments.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hospitals face acute shortages of IT-clinical hybrid staff capable of configuring HL7/FHIR integrations between nurse call platforms and electronic health records.
- Multi-Vendor Integration Complexity:Enterprise deployments require orchestration of bedside devices, middleware, and EHR systems from competing suppliers, extending implementation timelines.
- Cybersecurity Patch Management:Network-connected endpoints demand continuous vulnerability monitoring and firmware updates that strain hospital IT operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP-Based Nurse Call System Market |
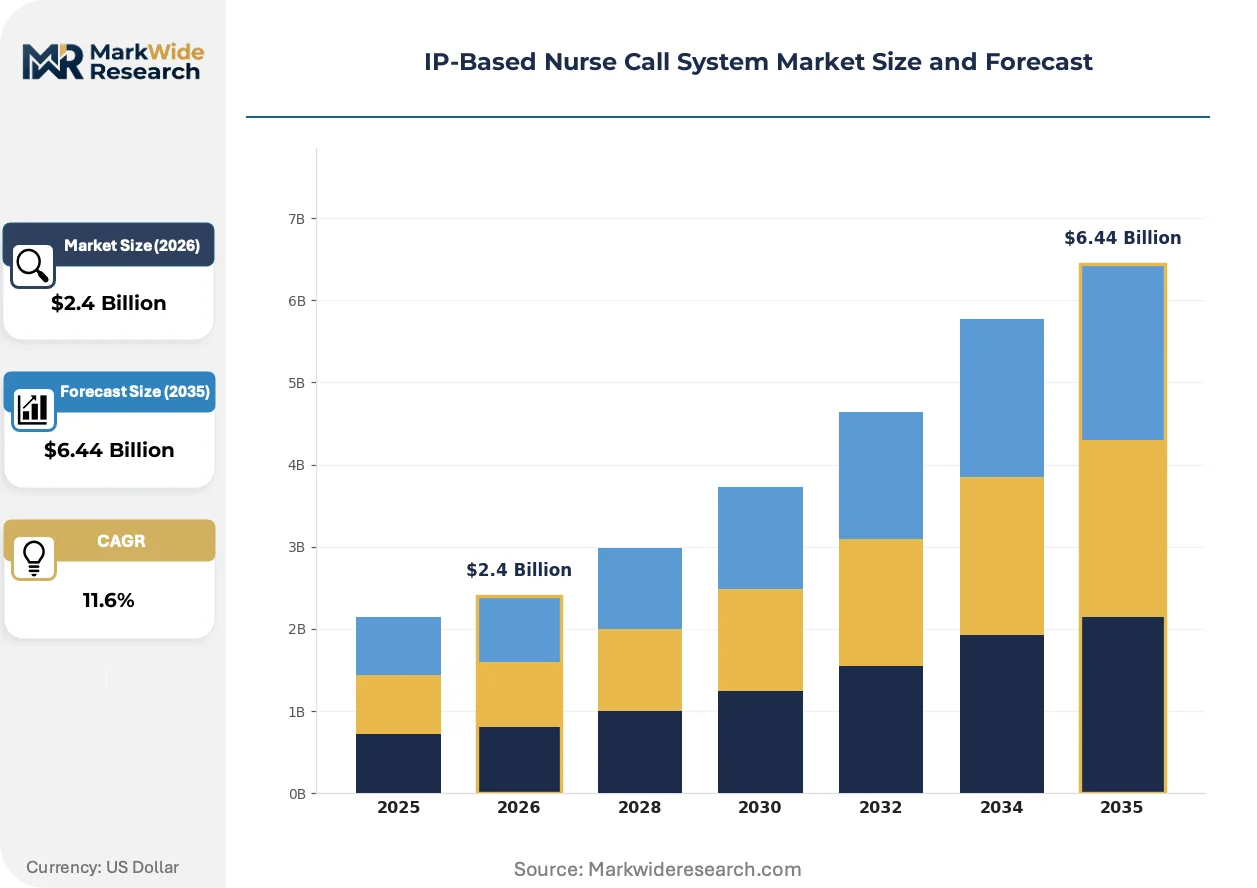
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Systems, Digital Systems, Wireless Solutions, Hybrid Systems End User: Hospitals, Long-Term Care Facilities, Ambulatory Surgical Centers, Home Healthcare Providers Technology: VoIP, LAN-Based, Cloud-Based, Alarm Management Solutions Installation Type: New Installations, Upgrades, Retrofitting, Integrated Systems |
| Companies Covered | Ascom Holding AG, Hillrom Holdings Inc., STANLEY Healthcare, Rauland-Borg Corporation, Baxter International, Jeron Electronic Systems, West-Com Nurse Call Systems, Critical Alert Systems, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP-Based Nurse Call System Market Trends and Innovations
Software-defined functionality is overtaking purpose-built hardware as the primary value driver, compressing equipment refresh cycles and redistributing margin toward persistent licensing models.
Native cloud architecture is decomposing the monolithic nurse call system into modular microservices. Acute care hospitals in the United States are adopting these platforms fastest, drawn by zero-touch deployment and automatic security updates. This decomposition enables third-party developers to build workflow applications atop open APIs, fragmenting what was once a captive vendor ecosystem.
The FDA's medical device interoperability guidance is mandating standardized data formats and encrypted transmission protocols. Device manufacturers must now engineer for plug-and-play connectivity with competing systems rather than proprietary lock-in. Acute care hospitals face the steepest compliance burden, accelerating procurement of pre-certified platforms from established testing regimes.
Health system procurement departments are consolidating vendor relationships into enterprise framework agreements that bundle nurse call with patient monitoring and clinical communication. Independent distributors and regional systems integrators are losing access as direct manufacturer contracts capture multi-year service revenue. This concentration is most visible in the United States, where mega-mergers have created purchasing entities spanning dozens of facilities.
IP-Based Nurse Call System Market Segmentation
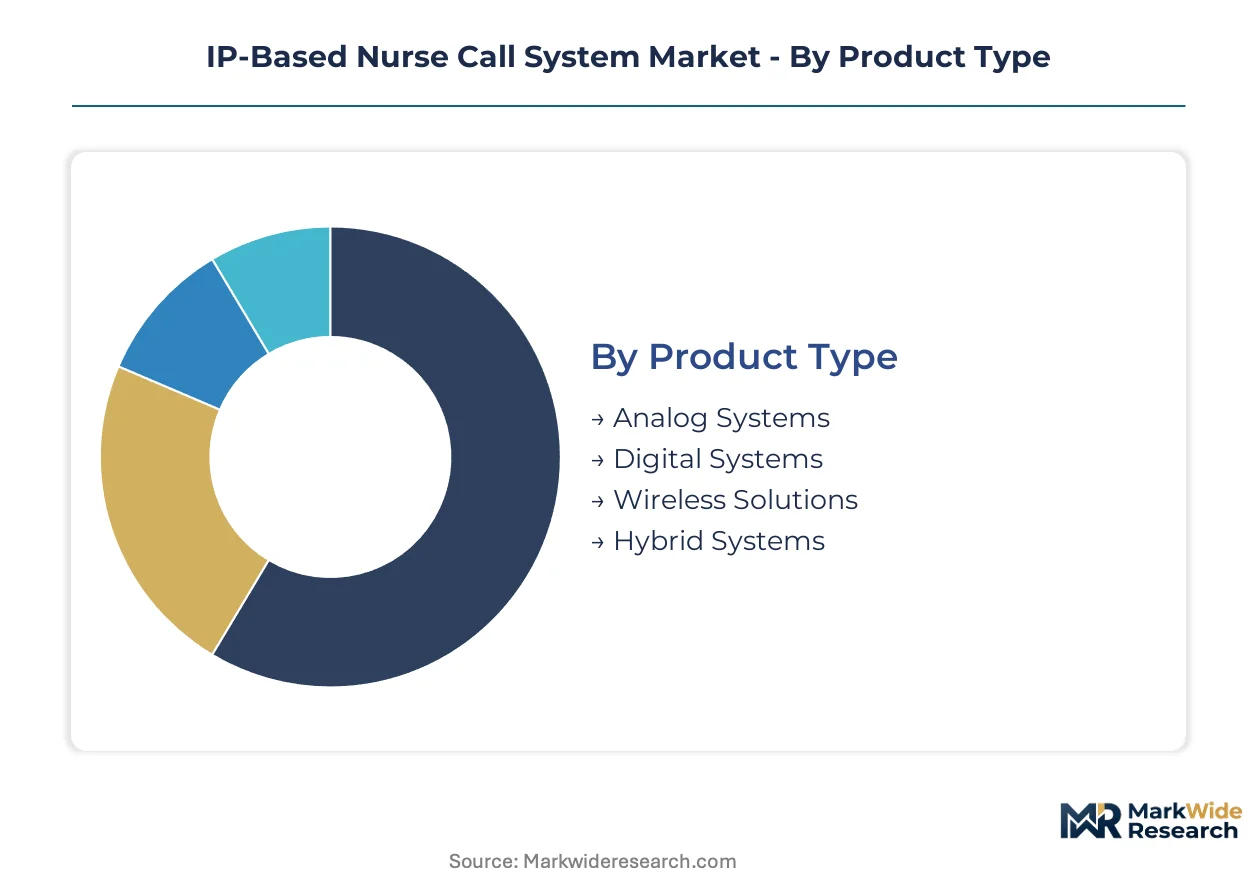
IP-based nurse call systems fragment across four critical dimensions that determine procurement priorities and vendor competitive positioning. Product architecture choices dictate infrastructure investment requirements, while end-user concentration shapes regional demand patterns and technology adoption timelines.
Product Type:
Wireless Solutions face the most intense substitution pressure from emerging cloud-native platforms, while legacy analog infrastructure resists displacement due to embedded copper wiring and certification dependencies.
- Digital Systems:Purpose-built IP-native hardware with dedicated Ethernet backbones and embedded audio processing. Demand concentrates in new hospital construction across the United States, where Joint Commission alarm safety goals mandate auditable response workflows. UL 1069 certification requirements limit vendor qualification to established testing regimes.
- Wireless Solutions:Wi-Fi 6-enabled endpoints transmitting over existing hospital wireless infrastructure without dedicated cabling. Acute care hospitals in the United States deploy these most aggressively to bypass copper rewiring costs in aging facilities. Wi-Fi 6 infrastructure upgrades enable rapid deployment without construction disruption.
- Analog Systems:Legacy copper-wired architectures with electromechanical signaling.
- Hybrid Systems:Mixed infrastructure preserving analog endpoints while migrating to IP backbones.
Digital Systems retain volume leadership; Wireless Solutions hold the steepest expansion curve.
End User:
Procurement scale varies dramatically across care settings, with multi-facility health systems extracting enterprise pricing leverage unavailable to standalone operators.
- Hospitals:Acute care facilities with 200+ beds requiring enterprise-scale alarm management, EHR integration through HL7/FHIR interfaces, and real-time location services. United States health system consolidation is driving single-vendor framework agreements spanning dozens of facilities. FDA interoperability guidance mandates encrypted, traceable architectures.
- Long-Term Care Facilities:Skilled nursing and assisted living operators with 50-150 beds per site, predominantly analog-installed. These facilities represent substantial retrofit opportunity as wireless solutions eliminate copper rewiring barriers. Staffing shortages intensify demand for automated alert routing.
- Ambulatory Surgical Centers:Same-day surgical facilities with lower acuity monitoring requirements.
- Home Healthcare Providers:Distributed care models with mobile caregiver coordination needs.
Hospitals dominate revenue concentration; Long-Term Care Facilities present the largest untapped conversion base.
Technology:
Margin distribution shifts toward software layers as hardware commoditization accelerates across all architecture types.
- Cloud-Based:Native cloud architecture decomposing monolithic systems into modular microservices with automatic security updates and zero-touch deployment. Acute care hospitals in the United States adopt these fastest, drawn by API-driven integration ecosystems and third-party developer access.
- Alarm Management Solutions:Middleware filtering false alerts and routing prioritized signals to specific caregiver roles. These command premium positioning by reducing alarm fatigue and enabling outcome-based workflow optimization. Joint Commission mandates for alert prioritization drive procurement.
- VoIP:Voice-over-IP communication with integrated location tracking.
- LAN-Based:Traditional Ethernet-dependent architectures requiring on-premise server infrastructure.
Alarm Management Solutions capture the highest margin per unit; Cloud-Based platforms are climbing the fastest.
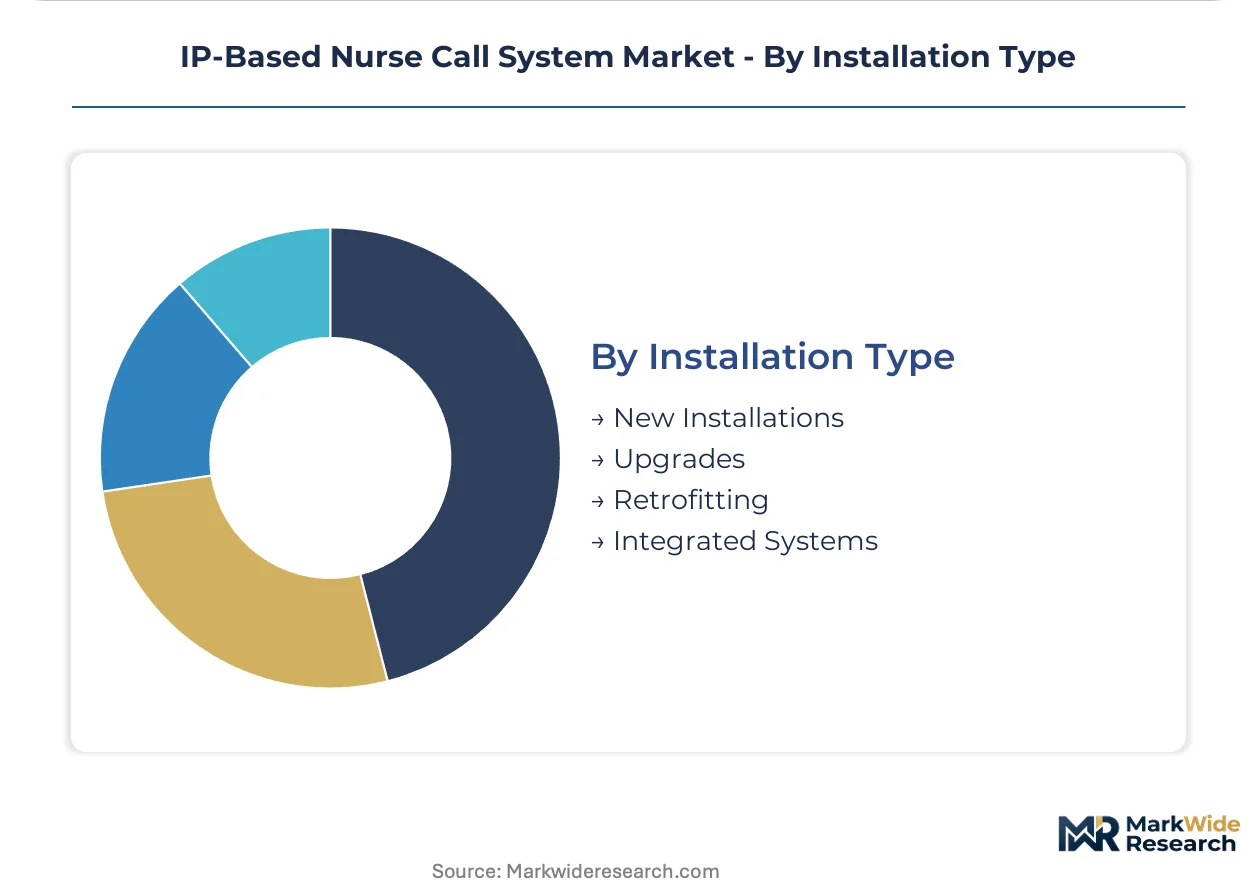
Installation Type:
Project complexity and timeline risk vary substantially based on existing infrastructure condition and integration scope.
- New Installations:Greenfield deployments in construction-phase facilities enabling full IP-native specification without legacy constraints. These projects bundle nurse call with patient monitoring and clinical communication under enterprise framework agreements. United States hospital construction permits indicate concentrated regional activity.
- Retrofitting:Wireless overlay solutions preserving existing infrastructure while adding IP functionality. Aging hospital buildings across the United States drive demand here, as copper rewiring costs often exceed equipment spend. Wi-Fi 6 density requirements determine project feasibility.
- Upgrades:Software and firmware enhancements to existing IP installations.
- Integrated Systems:Multi-vendor orchestration combining nurse call with EHR, RTLS, and clinical communication platforms.
New Installations anchor capital equipment revenue; Retrofitting represents the most scalable volume opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor certification regimes concentrate manufacturing and testing capacity in jurisdictions with established medical device regulatory frameworks. Health system procurement patterns track directly to reimbursement density and hospital construction activity.
United States
Acute care hospital consolidation drives enterprise-scale deployments across multi-facility networks. FDA medical device interoperability guidance and HIPAA security rule updates mandate encrypted IP architectures. The Southeast corridor from Florida through Georgia anchors retrofit demand as aging facilities bypass copper rewiring through Wi-Fi 6 overlays.
Germany
University hospital networks standardize on alarm management middleware with HL7/FHIR integration requirements. EU Medical Device Regulation (MDR) and IEC 60601-1-8 compliance narrow vendor qualification to established testing regimes. The Baden-Württemberg cluster around Stuttgart concentrates engineering-intensive system integration capabilities.
United Kingdom
NHS Long Term Plan digitization targets accelerate procurement of cloud-connected platforms with automatic security updates. NHS Digital interoperability standards and UKCA marking requirements post-Brexit reshape supplier access. Greater Manchester's health system consolidation exemplifies framework agreement concentration across integrated care systems.
Japan
Super-aging society demographics intensify demand for automated alert routing in long-term care conversion projects. PMDA medical device quality management system requirements and JIS standards govern market entry. The Kansai region around Osaka anchors manufacturing partnerships for wireless endpoint production.
Australia
Digital Health Agency interoperability frameworks drive public hospital procurement toward API-native architectures. TGA medical device conformity assessment procedures and cybersecurity guidance for connected devices raise compliance barriers. New South Wales and Victoria concentrate health system procurement through state-level purchasing authorities.
IP-Based Nurse Call System Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized nurse call system manufacturers. The vendor base stratifies across three tiers: enterprise-scale platform providers with bedside device portfolios, regional specialists in custom workflow software, and wireless infrastructure pure-plays. Dominant competitive moves include strategic partnerships with EHR vendors and geographic expansion through health system framework agreements.
Within the diversified medical technology tier, Hillrom Holdings Inc., Baxter International, and Honeywell International exemplify scale-driven positioning through integrated device portfolios. Ascom Holding AG and Rauland-Borg Corporation occupy specialist positions in alarm management middleware and custom workflow layers respectively. STANLEY Healthcare represents the security-technology crossover archetype, while Jeron Electronic Systems, West-Com Nurse Call Systems, and Critical Alert Systems sit within the mid-market installation and service tier.
| Leading Market Players |
|---|
| Ascom Holding AG |
| Hillrom Holdings Inc. |
| STANLEY Healthcare |
| Rauland-Borg Corporation |
| Baxter International |
| Jeron Electronic Systems |
| West-Com Nurse Call Systems |
| Critical Alert Systems |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
UL 1069 certification gates both vendor qualification and price stratification simultaneously, compressing margins for manufacturers lacking established testing regimes while enabling premium positioning for incumbent testing laboratories. Health system procurement departments exploit this bottleneck through enterprise framework agreements that bundle hardware with persistent software licensing.
Pricing Analysis
FDA medical device interoperability guidance dictates the pricing tier structure across the IP-based nurse call system landscape. Three-tier pricing structure across premium, standard, and economy levels separates UL 1069-certified alarm management middleware from uncertified LAN-based alternatives from unbranded Asian imports. Cost compression in the standard tier is intensifying because cloud-native platforms are displacing purpose-built hardware with subscription models. Rural hospitals exhibit acute price sensitivity, while consolidated United States health systems prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Taiwanese semiconductor foundry capacity serves as the critical chokepoint for wireless endpoint production, constraining Wi-Fi 6 chip availability and extending lead times for dense hospital deployments. Manufacturing concentrates in China, Mexico, and Germany, with final assembly drawing from Malaysian electronics clusters and Czech automation component suppliers. Single-source vulnerability pervades the custom audio processing chip segment, where two vendors control hospital-grade noise cancellation IP. Distribution runs through health system group purchasing organizations and specialized medical device distributors with UL testing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-connected nurse call platforms transform hardware vendors into recurring-revenue software enterprises, with alarm management middleware subscriptions expanding faster than endpoint sales. This service-attach dynamic redefines competitive positioning around API ecosystems rather than device specifications.
For Market Incumbents: Compound enterprise contract value by embedding real-time location services and clinical communication platforms into existing bedside device portfolios. Defend against cloud-native entrants through backward integration into cybersecurity patch management services. Prioritize UL 1069 testing laboratory partnerships to compress certification timelines for new product introductions. For New Entrants and Emerging Players: Differentiate on wireless retrofit solutions targeting long-term care facilities with copper legacy constraints, where incumbent hardware vendors lack flexible deployment architectures. Penetrate the skilled nursing segment through zero-touch Wi-Fi 6 overlay systems that eliminate construction disruption. Pursue direct-to-facility sales models bypassing group purchasing organization gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform development, enabling asset-light scaling without manufacturing footprint expansion. Target alarm management middleware specialists with established HL7/FHIR integration libraries and recurring revenue bases exceeding sixty percent of total sales. Monitor FDA enforcement patterns around medical device interoperability compliance as the primary inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise framework agreements with multi-facility United States health systems lock out competing vendors across dozens of sites. |
| Software Companion Development | API-native alarm management applications attract third-party developers and fragment proprietary vendor ecosystems. |
| FDA Submission Pathway | Pre-certified interoperability architectures accelerate procurement cycles for acute care hospital consolidation projects. |
| CE Marking Pathway | EU Medical Device Regulation compliance opens university hospital networks in Germany and integrated care systems in the United Kingdom. |
| Reimbursement Strategy | Joint Commission alarm safety goal compliance documentation supports hospital quality metric reporting and value-based purchasing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineering directors, and group purchasing organization contract managers; and secondary validation against FDA 510(k) filings, hospital procurement databases, and UL certification registries. Bottom-up endpoint shipment estimates triangulated against top-down health system capital expenditure disclosures.
Across the projection horizon, the analytical framework modeled demand by product architecture, care setting acuity tier, installation type, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and software attach rate penetration curves. Forecast inputs incorporated Wi-Fi 6 infrastructure deployment timelines and health system merger integration schedules.
The analysis sits within stated boundaries; outcomes outside sustained hospital construction activity and stable cybersecurity liability frameworks would require recalibration. Practitioners should keep alternative scenarios live as FDA interoperability enforcement intensity and cloud platform security incident frequency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Pharma Management Software Market