
 Global Dental Software Market | 2026-2036
Global Dental Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Software Market Analysis
Subscription-based imaging analytics is repositioning how dental software vendors capture recurring revenue from chairside diagnostics. Henry Schein leverages its distribution network to bundle software with consumable supply contracts. Carestream Dental anchors its competitive stance through proprietary imaging hardware-to-software integration. Patterson Companies competes by embedding practice management tools within its equipment financing ecosystem.
Dental software encompasses practice management systems, imaging platforms, patient engagement tools, and revenue cycle applications that run on local servers, private clouds, or multi-tenant SaaS architectures, typically integrating with DICOM-compliant imaging hardware and HL7-interfaced electronic health records to automate scheduling, clinical documentation, billing, and regulatory reporting for oral healthcare providers. Practice management and imaging software dominate current revenue pools due to their status as foundational infrastructure in established markets, while patient communication modules represent the fastest-expanding segment as dental groups prioritize automated recall and treatment acceptance workflows. Cloud-based and SaaS deployments are displacing on-premises installations among mid-market dental service organizations seeking centralized IT governance across dozens of locations.
FDA software-as-medical-device oversight, HIPAA security rule enforcement, and EU MDR classification of certain diagnostic algorithms are elevating compliance costs while simultaneously creating competitive moats for vendors with validated quality management systems. ISO 13485 certification and IEC 62304 software lifecycle standards increasingly function as table stakes for market access in regulated jurisdictions. Stakeholders must weigh the capital efficiency of SaaS delivery against the data sovereignty requirements that still favor hybrid architectures in privacy-sensitive European and Asia-Pacific deployments.
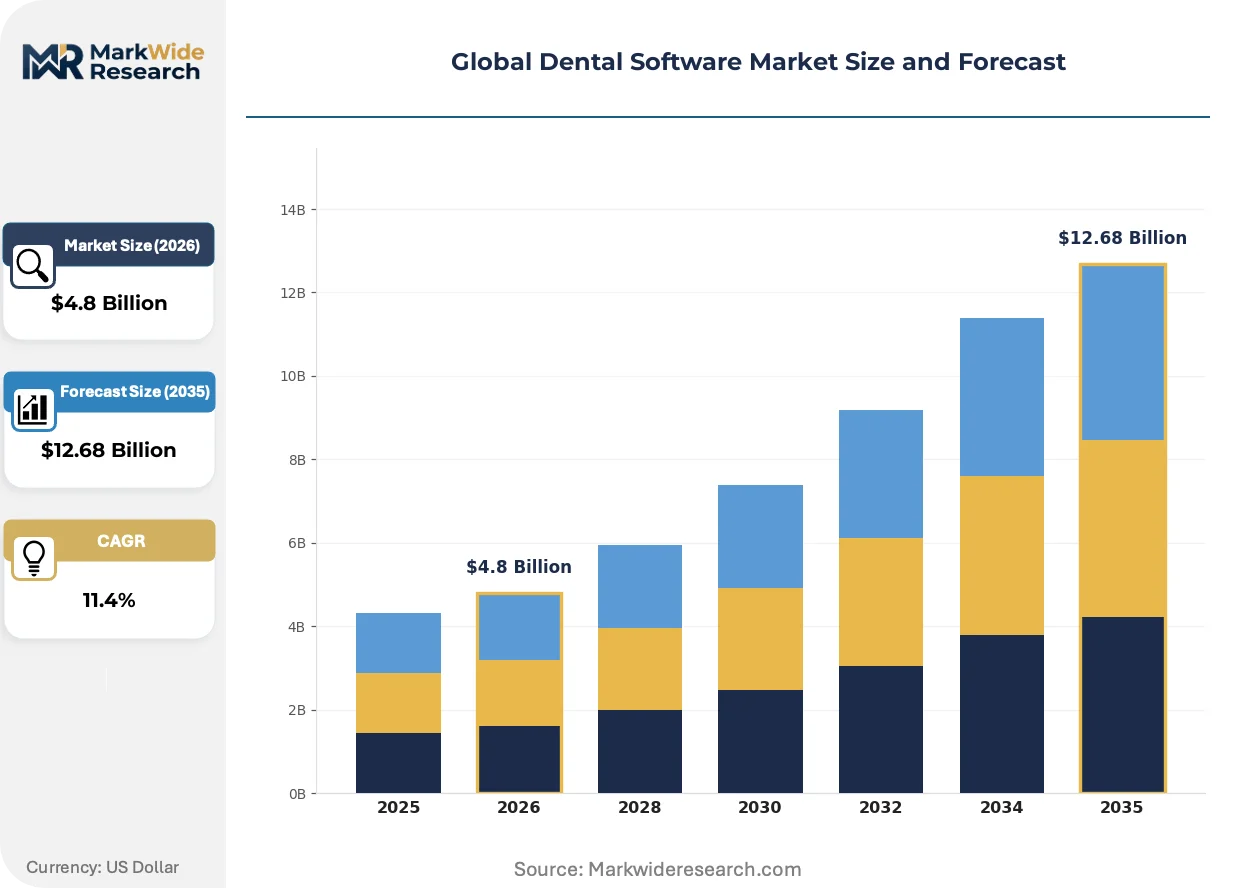
Market Dynamics
Cloud-native SaaS architectures are consolidating practice management across multi-location dental service organizations, compressing IT governance costs while elevating cybersecurity and compliance requirements as competitive differentiators.
Growth Catalysts
- HIPAA Security Rule enforcement:US dental groups are replacing legacy on-premises systems with validated cloud platforms to satisfy audit-ready documentation mandates and avoid penalty exposure.
- Dental clinic consolidation:Multi-location dental service organizations in Germany and Japan are standardizing on centralized SaaS practice management to reduce per-location IT overhead.
- DICOM-compliant imaging integration:Chairside CAD/CAM workflows require seamless hardware-to-software data pipelines, pulling investment into unified digital dentistry stacks.
Market Restraints
- EU MDR diagnostic algorithm classification:European Union Medical Device Regulation reclassifies certain AI-powered radiology tools as Class IIa devices, extending validation timelines and compliance costs.
- Hybrid architecture persistence:Data sovereignty requirements in Switzerland and Australia sustain on-premises or private cloud deployments despite SaaS operational advantages.
- ISO 13485 certification bottleneck:Limited notified body capacity for quality management system audits creates queuing delays for software vendors seeking European market access.
Strategic Opportunities
- India's underserved dental clinic base:Low software penetration among independent practitioners in tier-2 and tier-3 cities creates whitespace for localized, mobile-first practice management platforms.
- Automated patient recall systems:Treatment acceptance workflows and AI-driven scheduling optimization represent underexploited modules with high attach rates to core practice management subscriptions.
- FDA software-as-medical-device guidance:Clearer predicate pathways for diagnostic algorithms reduce regulatory uncertainty, accelerating investment in validated imaging analytics for US market entry.
Industry Challenges
- HL7 interface engineering scarcity:Shortage of developers with healthcare interoperability expertise delays electronic health record integration projects and extends implementation timelines.
- Legacy server migration complexity:Decades of patient data trapped in proprietary on-premises formats complicate cloud transitions and risk data integrity during extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Practice Management, Patient Communication, Imaging Software, Billing Software Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Dentists, Dental Clinics, Hospitals, Dental Laboratory Technology: Artificial Intelligence, Machine Learning, Big Data, Blockchain |
| Companies Covered | Henry Schein, Carestream Dental, Curve Dental, Patterson Companies, DentiMax, Planet DDS, NextGen Healthcare, Open Dental, Veradigm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Software Market Emerging Trajectories
Artificial intelligence is penetrating diagnostic workflows at the chairside, regulatory frameworks are hardening around software safety, and procurement patterns are favoring bundled platform contracts over point solutions.
Machine learning-powered radiographic analysis is expanding into routine preventive examinations. Mid-market dental groups in the United States are deploying these tools at the fastest adoption rates. The technology is compressing specialist referral cycles by flagging pathology for immediate chairside discussion rather than delayed specialist consultation.
EU MDR classification of diagnostic algorithms as medical devices is elevating software lifecycle documentation requirements. Vendors must now maintain design history files and post-market surveillance systems comparable to hardware manufacturers. European dental software suppliers are responding by restructuring quality management systems around IEC 62304 standards and segregating regulated from non-regulated product modules.
Subscription bundling is consolidating previously separate purchasing decisions. Dental service organizations now negotiate enterprise agreements covering practice management, imaging, patient communication, and revenue cycle tools through single procurement processes. This pattern is most visible in Germany, where clinic chains leverage scale to demand platform-wide service level agreements and unified data governance frameworks.
Global Dental Software Market Segmentation
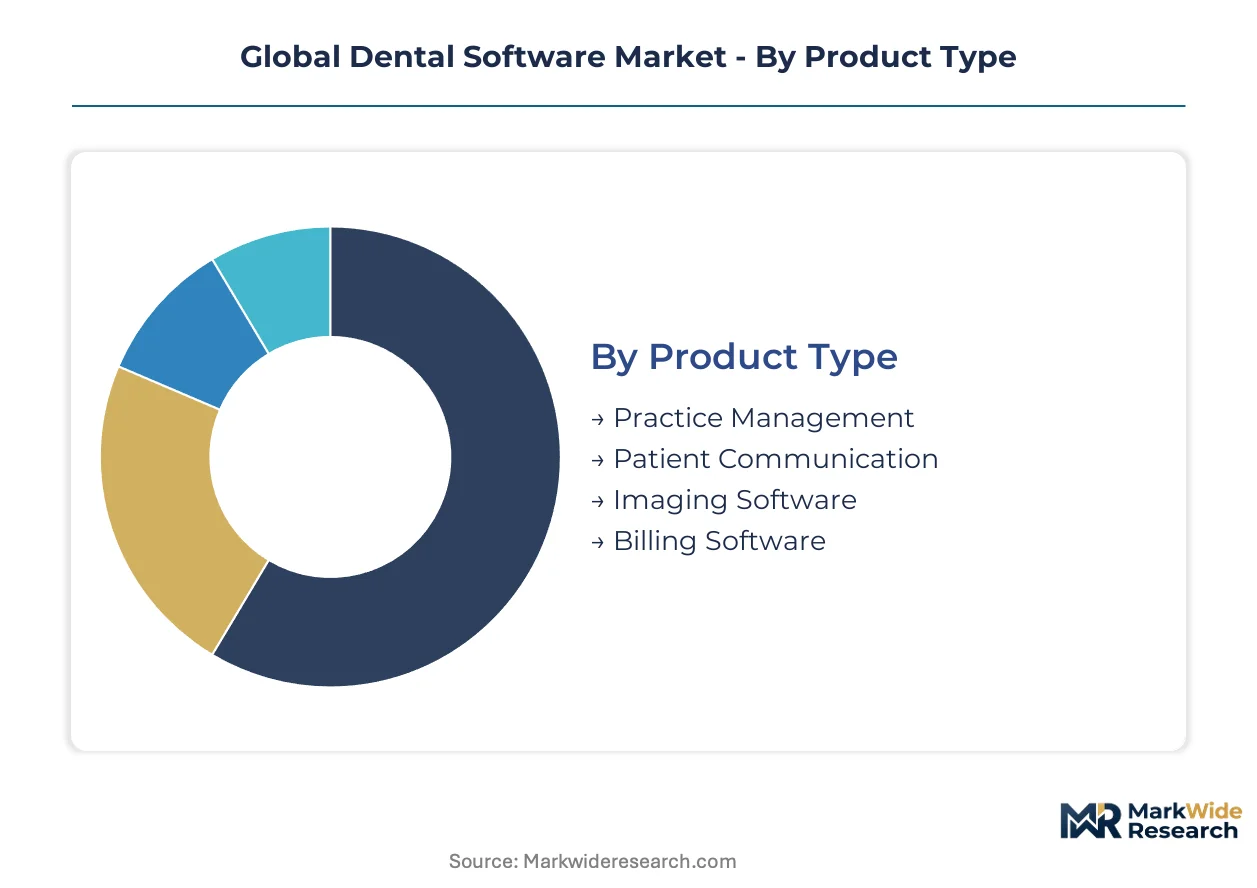
Dental software procurement patterns diverge sharply by practice scale and IT maturity. Segmentation reveals how cloud-native platforms capture multi-location dental service organizations while legacy systems persist among independent practitioners with constrained capital budgets.
Product Type:
Purchase decisions in this category track practice operational priorities and regulatory exposure levels.
- Practice Management:Core scheduling, clinical documentation, and regulatory reporting modules anchor enterprise procurement in Germany and the United States. HIPAA audit mandates and EU MDR documentation requirements drive replacement cycles among dental service organizations seeking centralized governance.
- Imaging Software:DICOM-compliant visualization and CAD/CAM integration platforms command premium positioning through hardware-software bundling. Chairside diagnostic workflows in Japan and US metropolitan markets pull investment toward unified digital dentistry stacks with seamless sensor-to-screen pipelines.
- Patient Communication:Automated recall and treatment acceptance modules attach to core subscriptions with high conversion rates.
- Billing Software:Revenue cycle tools integrate with electronic health records through HL7 interfaces to accelerate claims processing.
Practice Management leads volumes today; Patient Communication is gaining share fastest.
Deployment:
Architecture selection reflects data sovereignty requirements against operational efficiency trade-offs.
- Cloud-Based:Multi-tenant SaaS platforms compress IT governance costs across distributed clinic networks. German and Japanese dental service organizations standardize on these architectures to eliminate per-location server maintenance.
- SaaS:Subscription delivery models align vendor incentives with customer uptime requirements through service level agreements. US dental groups under HIPAA Security Rule enforcement favor validated cloud platforms with audit-ready documentation.
- Hybrid:Mixed architectures satisfy Swiss and Australian data residency mandates while capturing SaaS operational advantages.
- On-Premises:Local server installations persist where legacy data formats complicate extraction and migration.
Cloud-Based deployments dominate new procurement; Hybrid architectures expand where privacy regulations tighten.
End User:
Buyer sophistication and procurement scale determine platform complexity and integration depth.
- Dental Clinics:Multi-location dental service organizations in Germany and Japan negotiate enterprise agreements covering practice management, imaging, and patient communication through unified procurement processes.
- Dentists:Independent practitioners in India's tier-2 and tier-3 cities present whitespace for mobile-first platforms with localized interfaces and minimal hardware requirements.
- Hospitals:Oral health departments within larger health systems demand HL7-interfaced solutions compatible with enterprise electronic health record environments.
- Dental Laboratory:CAD/CAM workflow integration and case management tools support digital prosthesis fabrication and quality tracking.
Dental Clinics drive enterprise revenue concentration; Dentists represent the deepest volume pool globally.
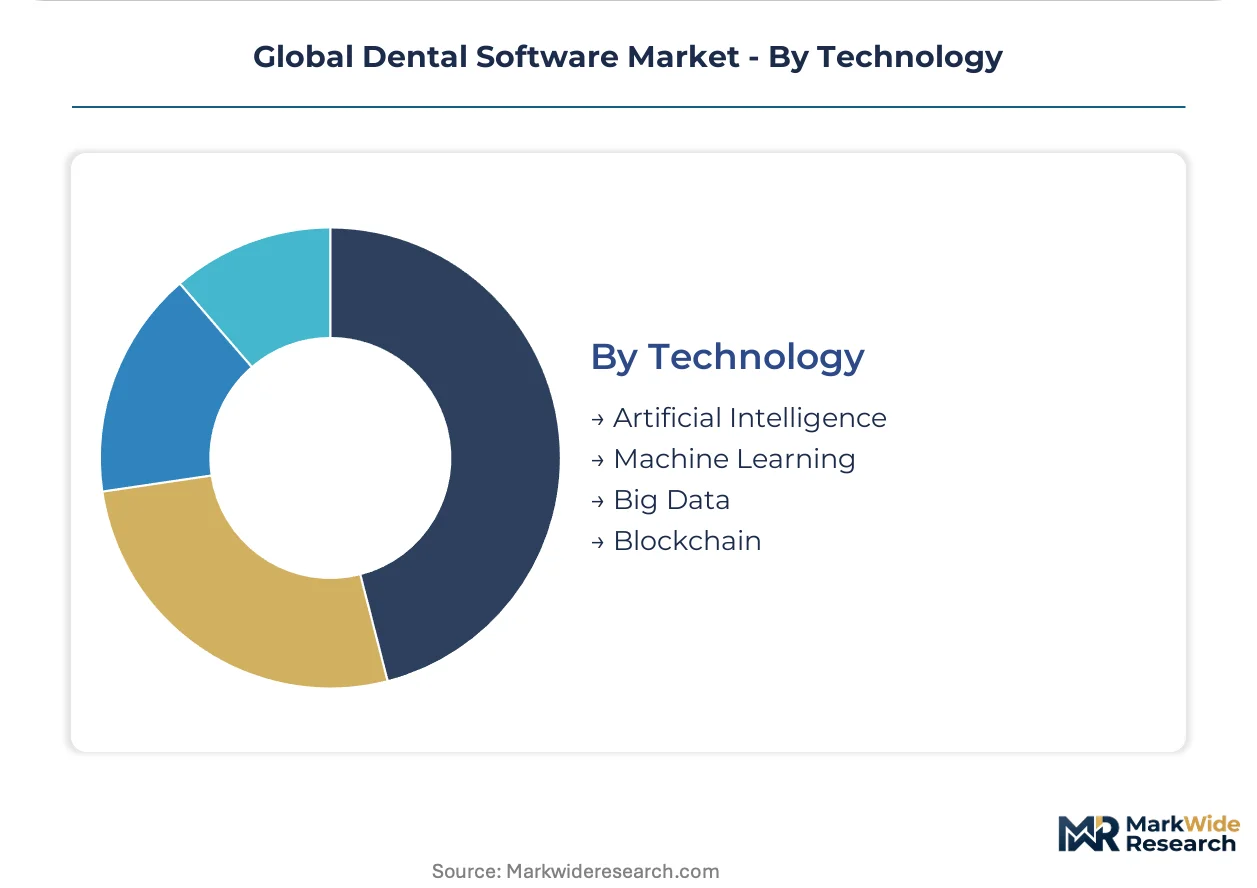
Technology:
Regulatory classification and validation burden separate experimental applications from production deployment.
- Artificial Intelligence:Machine learning-powered radiographic analysis tools receive FDA software-as-medical-device oversight and EU MDR Class IIa classification, extending validation timelines while creating competitive moats for vendors with certified quality management systems.
- Machine Learning:Predictive scheduling and treatment acceptance algorithms optimize chairside efficiency without triggering medical device regulatory thresholds.
- Big Data:Population-level analytics support dental service organization benchmarking and outcome measurement across clinic networks.
- Blockchain:Distributed ledger applications for credential verification and supply chain traceability remain exploratory with limited production deployment.
Machine Learning delivers immediate operational returns; Artificial Intelligence faces regulatory gating before scale deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dental clinic consolidation outpaces Japan's hardware-centric upgrade cycles, while the United States drives cloud migration through enforcement pressure rather than technology pull alone.
United States
HIPAA Security Rule audits and FDA software-as-medical-device guidance accelerate replacement of legacy on-premises systems with validated cloud platforms. Multi-location dental service organizations in Texas and Florida negotiate enterprise SaaS contracts to satisfy audit-ready documentation mandates. The Boston-to-Washington corridor hosts concentrated imaging analytics development clusters serving metropolitan dental groups.
Germany
Dental clinic chains in Bavaria and North Rhine-Westphalia standardize on centralized practice management to eliminate per-location server maintenance overhead. EU MDR classification of diagnostic algorithms as Class IIa devices extends validation timelines for vendors seeking European market access. The Munich-Stuttgart axis anchors hardware-software integration development for chairside CAD/CAM workflows.
Japan
Digital imaging upgrades in Tokyo and Osaka metropolitan markets pull investment toward unified sensor-to-screen pipelines. METI industrial policy supports dental technology adoption through SME digitalization subsidies. The Nagoya medical device cluster concentrates imaging hardware manufacturing with tight software integration requirements.
India
Low software penetration among independent practitioners in tier-2 and tier-3 cities creates whitespace for mobile-first platforms with localized interfaces. BIS standards compliance and CDSCO medical device regulations shape vendor entry strategies for diagnostic algorithm modules. The Bengaluru-Hyderabad corridor hosts emerging dental technology development centers targeting domestic price points.
Australia
Data sovereignty requirements sustain hybrid cloud architectures despite SaaS operational advantages in Sydney and Melbourne dental markets. TGA medical device oversight and privacy regulations influence procurement decisions for diagnostic software. The Perth medical technology cluster experiments with private cloud deployments serving regional dental networks.
Global Dental Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated platform vendors commanding enterprise dental service organizations while fragmented point-solution providers serve independent practitioners. The market structure tiers around three strategic archetypes: distribution-anchored bundlers, hardware-integrated platform vendors, and pure-play SaaS specialists. Dominant competitive moves include strategic partnerships between imaging hardware manufacturers and software developers, plus geographic expansion through localized compliance adaptation.
Among distribution-anchored bundlers, Henry Schein and Patterson Companies occupy positions leveraging supply chain relationships to embed software within equipment financing ecosystems. Carestream Dental exemplifies the hardware-integrated archetype through proprietary imaging-to-software pipelines. Curve Dental and Planet DDS represent pure-play SaaS specialists targeting mid-market dental groups with cloud-native architectures.
| Leading Market Players |
|---|
| Henry Schein |
| Carestream Dental |
| Curve Dental |
| Patterson Companies |
| DentiMax |
| Planet DDS |
| NextGen Healthcare |
| Open Dental |
| Veradigm |
| Others |
Supply Flow & Price Mechanics
Multi-location dental service organization procurement consolidation in Germany and the United States is compressing vendor margins while elevating ISO 13485 certification requirements as non-negotiable table stakes, forcing supply restructuring toward validated quality management systems and audit-ready documentation pipelines.
Pricing Analysis
Capacity additions in India's tier-2 and tier-3 software development corridors are reshaping price floors for mobile-first practice management platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by HIPAA validation tier and HL7 integration depth. Pricing pressure stems from SaaS subscription commoditization among mid-market dental groups. Independent practitioners in India exhibit highest price sensitivity; enterprise dental service organizations in Germany demonstrate lowest.
Supply Chain Analysis
Healthcare interoperability engineer shortages in Bengaluru and Hyderabad constrain HL7 interface development velocity. Software lifecycle documentation feeds from ISO 13485-certified quality management systems, DICOM-compliant imaging hardware partnerships, and IEC 62304-validated development pipelines. Single-source vulnerability concentrates in FDA-registered predicate pathway consultants. Distribution runs through Henry Schein and Patterson Companies supply chain networks with embedded financing ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental software procurement is maturing toward validated, audit-ready platforms as HIPAA Security Rule enforcement and EU MDR classification elevate quality specifications above feature differentiation.
For Market Incumbents: Cement market position through proprietary imaging hardware-to-software integration and captive ISO 13485 certification capacity. Acquire HL7 interface engineering talent pools to defend against interoperability bottlenecks. Deepen backward integration into DICOM-compliant sensor manufacturing to lock in chairside workflow control. For New Entrants and Emerging Players: Capture whitespace in India's tier-2 and tier-3 independent practitioner markets through localized, mobile-first architectures with minimal hardware requirements. Deploy BIS-compliant diagnostic algorithm modules ahead of CDSCO medical device enforcement expansion. Pursue dental school partnership channels for early clinician habit formation. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play SaaS specialists possessing validated cloud platforms and multi-tenant architecture scale. Five-to-ten year viability favors vendors with segregated regulated and non-regulated product modules. Monitor FDA software-as-medical-device predicate pathway clarity as inflection signal for diagnostic algorithm investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified practice management-imaging-patient communication stacks satisfy German dental service organization enterprise procurement demands. |
| Regulatory Certification Investment | ISO 13485 and IEC 62304 validation creates competitive moats against unqualified entrants in EU MDR jurisdictions. |
| Geographic Expansion | Localized compliance adaptation for BIS and CDSCO requirements unlocks India's underserved independent practitioner base. |
| Strategic Partnership | Imaging hardware manufacturer alliances secure proprietary sensor-to-screen pipeline control for CAD/CAM workflows. |
| Acquisition of Specialist Firm | HL7 interface engineering boutiques address interoperability scarcity delaying electronic health record integration timelines. |
Methodological Framework
Bottom-up dental clinic deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core. Primary interviews with practice management officers, dental service organization IT directors, HL7 integration specialists, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, HIPAA audit documentation, EU MDR notified body records, and DICOM standards committee proceedings. Triangulation across stakeholder inputs and regulatory databases ensures segmentation integrity.
Input-output matrices map cloud deployment rates, imaging hardware upgrade cycles, and patient communication module attach rates against dental clinic consolidation velocity across the analysis window. Segmentation dimensions include deployment architecture, practice scale tier, integration complexity, and regional regulatory cluster. CAGRs derive from weighted average of bottom-up capacity expansion and top-down spending pattern trajectories, with dental service organization SaaS standardization and AI diagnostic algorithm regulatory clearance timelines as key forecast inputs.
FDA software-as-medical-device guidance revision, EU MDR notified body capacity constraints, and HIPAA Security Rule enforcement intensity are the dominant revision risks. Forecasts reflect assumptions on regulatory stability and dental clinic consolidation continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Femtech Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market