
 Cancer Patient Registry Software Market | 2026-2036
Cancer Patient Registry Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Patient Registry Software Market Outlook
A shortage of certified cancer registrars is collapsing the ability of health systems to maintain manual data workflows. Elekta leverages its embedded presence in radiation oncology departments to cross-sell registry modules. Oracle Corporation sustains enterprise-scale deployments through its Cerner health record integration. IBM competes via Watson Health analytics layers that process unstructured pathology reports.
Cancer patient registry software comprises specialized health IT applications that capture, classify, and transmit tumor-specific data using standardized coding systems such as ICD-O-3 and AJCC staging protocols; these platforms enable longitudinal patient tracking, quality reporting, and population health surveillance for oncology providers and research networks. Cloud-based deployment leads the product type category as hospital IT departments prioritize remote accessibility and reduced infrastructure overhead, while on-premises installations retain traction among research institutions with stringent data sovereignty requirements. The end-user dimension shows pharmaceutical companies representing the fastest-expanding segment as sponsors integrate real-world evidence pipelines directly from registry feeds.
The FDA enforces 21st Century Cures Act interoperability mandates that require certified health IT to support standardized application programming interfaces, directly shaping vendor development roadmaps and procurement criteria. State cancer registries operate under CDC-funded National Program of Cancer Registries guidelines that dictate minimum data element collection, creating baseline demand for compliant software configurations. HIPAA security rules impose encryption and access control standards that elevate functionality requirements across all deployment models. Stakeholders must weigh interoperability investment against the fragmentation of state-level registry reporting protocols.
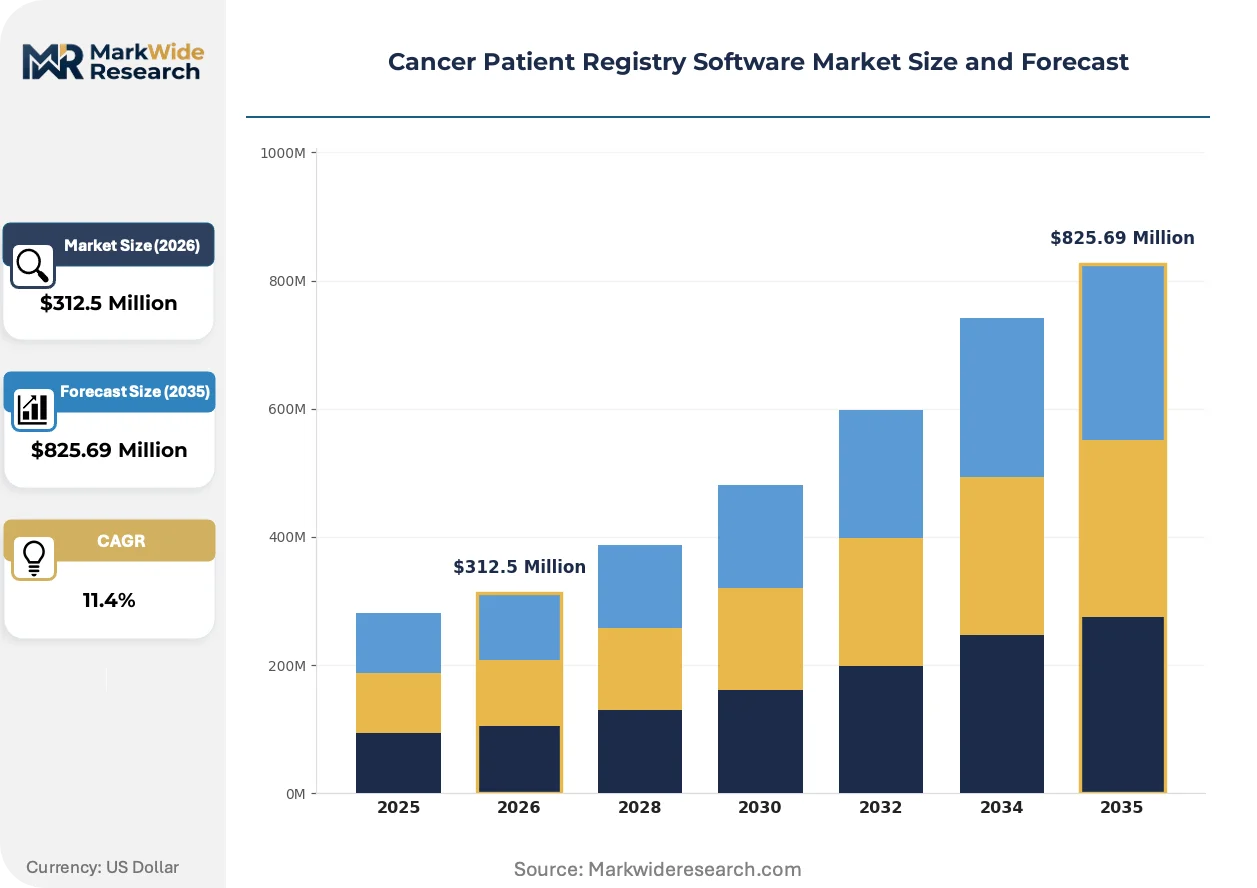
Market Dynamics
The FDA's 21st Century Cures Act interoperability mandates are compressing vendor development timelines and forcing hospital networks to consolidate fragmented registry systems into unified data architectures.
Growth Catalysts
- Interoperability Mandates:The FDA requires certified health IT to support standardized application programming interfaces, compelling oncology departments to upgrade legacy registry platforms.
- Real-World Evidence Pipelines:Pharmaceutical sponsors now integrate registry feeds directly into clinical development workflows, expanding software procurement beyond traditional hospital buyers.
- Cloud Migration:Hospital IT departments prioritize remote accessibility and reduced infrastructure overhead, accelerating displacement of on-premises installations.
Market Restraints
- Data Sovereignty Requirements:Research institutions in Germany and Switzerland maintain on-premises installations due to national privacy frameworks, fragmenting deployment standardization.
- Certified Registrar Shortage:The collapsing supply of credentialed cancer registrars limits health systems' ability to extract value from software investments regardless of platform sophistication.
- State-Level Protocol Fragmentation:CDC-funded National Program of Cancer Registries guidelines vary by jurisdiction, forcing vendors to maintain multiple compliant configurations.
Strategic Opportunities
- Pharmaceutical Integration:Sponsors building real-world evidence capabilities create demand for registry modules that feed directly into regulatory submission pipelines.
- AI-Augmented Coding:Natural language processing tools that extract structured data from unstructured pathology reports reduce manual abstraction burden.
- Population Health Surveillance:Public health agencies in India and Brazil are digitizing tumor registries, opening public-sector procurement channels.
Industry Challenges
- Legacy System Integration:Oncology departments running decade-old electronic health record instances face data mapping complexity when connecting modern registry platforms.
- HIPAA Security Compliance:Encryption and access control standards elevate functionality requirements, extending implementation timelines and testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Patient Registry Software Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Open Source End User: Hospitals, Research Institutions, Oncology Clinics, Pharmaceutical Companies Application: Clinical Trials, Patient Monitoring, Data Management, Reporting Functionality: Data Collection, Analytics, Interoperability, Security |
| Companies Covered | Elekta, Oracle Corporation, IBM, McKesson Corporation, Conduent, Health Catalyst, ONCO, C/NET Solutions, Q-Centrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Patient Registry Software Market Strategic Shifts
Natural language processing and FHIR-based data exchange are compressing the gap between clinical documentation and structured registry reporting, reshaping how tumor data flows from point of care to surveillance networks.
Natural language processing engines that parse unstructured pathology reports are fragmenting the traditional manual abstraction workflow. Community oncology practices with limited registrar staffing adopt these tools to maintain case completeness. The technology is fragmenting labor concentration in academic medical centers and redistributing data capture capability across smaller treatment sites.
The EU AI Act's risk classification framework for clinical decision support tools is forcing registry software vendors to reengineer algorithmic features. Systems that flag staging discrepancies or suggest coding corrections now face conformity assessment requirements. European hospital procurement committees are prioritizing vendors with documented CE marking pathways for AI-enhanced modules.
Subscription pricing for cloud-based registry platforms is displacing perpetual license models in North American hospital networks. Finance departments favor operational expenditure treatment and predictable annual costs over capital-intensive on-premises deployments. This shift is most visible in United States hospital systems undergoing IT modernization following Cerner and Epic consolidation waves.
Cancer Patient Registry Software Market Segmentation
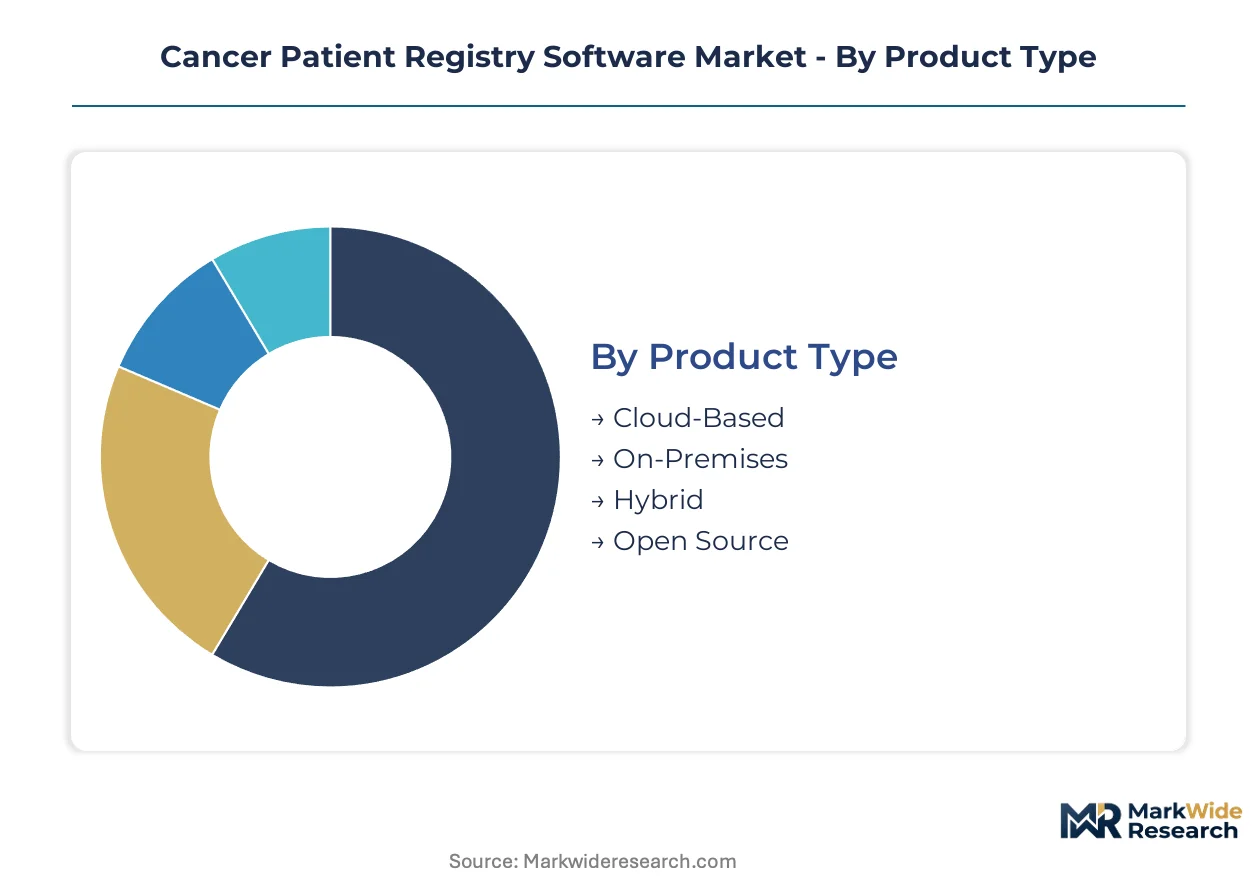
Cancer patient registry software segments reflect divergent IT infrastructure philosophies and regulatory compliance requirements across healthcare delivery models. Understanding these divisions reveals where procurement budgets concentrate and which deployment architectures capture sustained investment.
Product Type:
Margin pools concentrate in recurring revenue models that reduce hospital capital expenditure burdens while ensuring vendor lock-in through data gravity.
- Cloud-Based:Multi-tenant architectures with automated scaling and remote accessibility dominate new hospital procurements. United States health systems undergoing EHR consolidation waves prioritize these platforms to eliminate server maintenance overhead and enable real-time data sharing across distributed oncology networks.
- On-Premises:Single-tenant installations with direct hardware control persist in German and Swiss research institutions bound by national data sovereignty frameworks. These deployments command premium professional services fees but face shrinking addressable market as cloud security certifications mature.
- Hybrid:Split architectures keeping sensitive patient data local while pushing analytics workloads to cloud environments.
- Open Source:Community-developed platforms with customizable codebases attracting academic consortia with dedicated development resources.
The dominant share belongs to Cloud-Based deployments, while Hybrid configurations are closing the gap fastest as privacy-preserving federated learning techniques mature.
End User:
Procurement authority and budget cycles vary sharply across these institutional types, shaping sales motion design and implementation complexity.
- Hospitals:Integrated delivery networks with centralized IT governance mandate enterprise-wide registry standardization. Epic and Cerner EHR dominance in United States hospital systems creates demand for modules that embed directly within existing clinical workflows rather than standalone portals.
- Pharmaceutical Companies:Sponsors building real-world evidence capabilities for regulatory submissions now procure registry software as core infrastructure. These buyers prioritize API-first architectures that stream structured oncology data directly into clinical development pipelines without manual abstraction bottlenecks.
- Research Institutions:Academic medical centers with grant-funded tumor banks require granular data provenance tracking.
- Oncology Clinics:Community practices with limited IT staffing favor turnkey cloud subscriptions with minimal configuration demands.
Hospitals retain the largest installed base, though Pharmaceutical Companies are expanding most quickly as FDA real-world evidence guidance solidifies.
Application:
Functional use case determines integration depth with adjacent health IT systems and regulatory submission pathways.
- Patient Monitoring:Longitudinal tracking modules capturing recurrence patterns and survival outcomes across treatment episodes. United States cancer centers leverage these capabilities for Commission on Cancer accreditation maintenance and quality benchmarking against national datasets.
- Clinical Trials:Case report form generation and adverse event reporting aligned with FDA 21 CFR Part 11 requirements. Pharmaceutical sponsors demand these features for seamless transition from registry-derived hypothesis generation to interventional study execution.
- Data Management:Centralized repositories with audit trails for multi-site research collaborations.
- Reporting:Automated generation of state registry submissions and physician quality dashboards.
Patient Monitoring commands the deepest workflow integration, while Clinical Trials applications are gaining share fastest as sponsor-site data sharing protocols standardize.
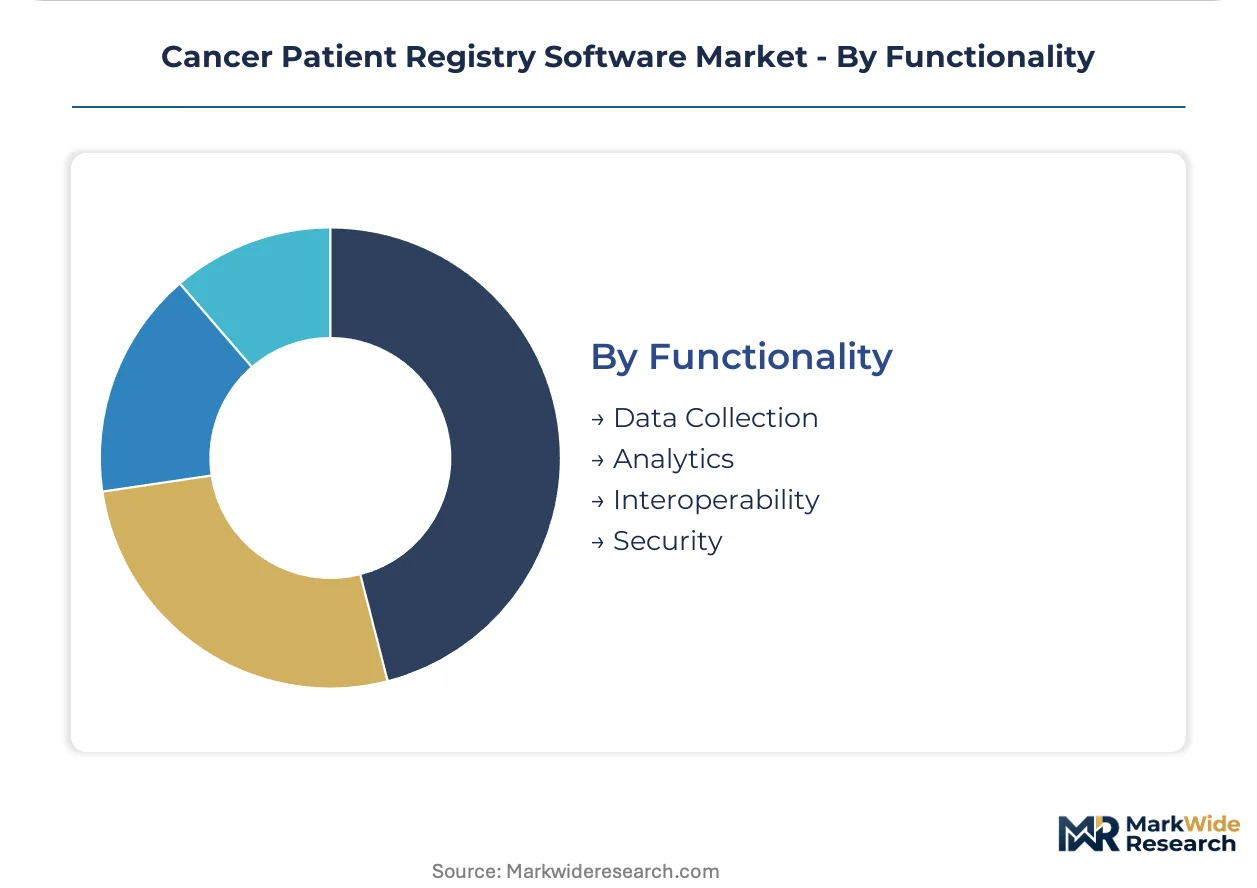
Functionality:
Technical capability layers differentiate commodity registry tools from platforms commanding sustained pricing power.
- Interoperability:FHIR-based data exchange and standardized API support mandated by 21st Century Cures Act certification requirements. Hospital procurement committees in the United States now disqualify vendors lacking documented interoperability test results from national certification bodies.
- Analytics:Population-level surveillance dashboards and predictive risk stratification algorithms. Research networks deploy these tools to identify disparities in cancer outcomes across demographic and geographic dimensions for publication and policy advocacy.
- Data Collection:Structured abstraction interfaces with ICD-O-3 and AJCC staging embedded.
- Security:Encryption at rest and in transit with role-based access controls satisfying HIPAA technical safeguards.
Interoperability features represent the primary procurement gate, while Analytics capabilities are climbing the fastest as AI-augmented coding tools demonstrate abstraction efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems deploy cancer patient registry software primarily for Commission on Cancer accreditation and quality benchmarking, while European research institutions emphasize data sovereignty compliance and German pharmaceutical sponsors prioritize real-world evidence pipelines for regulatory submissions.
United States
Hospital networks in the United States drive procurement volume through EHR consolidation mandates and FDA 21st Century Cures Act interoperability requirements. The National Program of Cancer Registries funds state-level data collection infrastructure, creating baseline demand for compliant software configurations. Academic medical centers in Boston and Houston anchor deployment density, with MD Anderson and Dana-Farber operating integrated registry-to-research pipelines.
Germany
German research institutions maintain on-premises installations bound by national data sovereignty frameworks and stringent privacy regulations. The Federal Institute for Drugs and Medical Devices enforces MDR compliance for clinical decision support modules, elevating vendor certification requirements. Heidelberg and Munich host dense clusters of university hospitals digitizing tumor banks with granular data provenance tracking.
Switzerland
Swiss cancer centers prioritize single-tenant deployments with direct hardware control under federal data protection law. Swissmedic oversees software used in clinical trials, creating dual regulatory pathways for registry platforms serving both care delivery and research functions. The Basel and Zurich metropolitan areas concentrate procurement authority among grant-funded academic consortia.
India
Indian public health agencies are digitizing population-level tumor registries under national cancer control program expansion. The Central Drugs Standard Control Organization regulates software used in clinical settings, while state governments fund district-level data collection infrastructure. Mumbai and Bangalore emerge as deployment centers where private hospital chains integrate cloud-based platforms for remote accessibility.
Brazil
Brazilian oncology networks adopt registry software to support national cancer institute surveillance mandates and hospital accreditation programs. ANVISA regulates health IT systems used in clinical care, creating compliance requirements for both domestic and international vendors. São Paulo and Rio de Janeiro concentrate private hospital investment in integrated data infrastructure for quality reporting.
Cancer Patient Registry Software Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with enterprise health IT vendors leveraging EHR embeddedness against pure-play registry developers. The competitive terrain divides between radiation oncology platform extenders, cloud-native abstraction specialists, and analytics-layer integrators. Dominant competitive moves include cross-selling registry modules through existing departmental relationships and API-first architectures that bypass manual data abstraction bottlenecks.
Within the integrated health IT tier, Oracle Corporation and Elekta occupy positions that exemplify divergent embedding strategies—one through enterprise EHR consolidation, the other through radiation therapy workflow dominance. IBM anchors the analytics-layer archetype, representing vendors that process unstructured clinical documentation through natural language pipelines. These three companies collectively illustrate how competitive positioning in this market depends on upstream control over data capture workflows rather than standalone software functionality.
| Leading Market Players |
|---|
| Elekta |
| Oracle Corporation |
| IBM |
| McKesson Corporation |
| Conduent |
| Health Catalyst |
| ONCO |
| C/NET Solutions |
| Q-Centrix |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure scale economies concentrate procurement leverage among three hyperscaler providers, compressing hosting cost floors while elevating vendor margin pressure as subscription pricing becomes the dominant commercial model across United States hospital networks.
Pricing Analysis
Contract structures favor multi-year SaaS subscriptions with annual escalators tied to case volume tiers, replacing perpetual license models that dominated prior procurement cycles. Price differentiation rests on FHIR certification grade and embedded EHR integration depth, with Epic-native modules commanding premium positioning over standalone portals. Cost compression in the mid-market segment intensifies as regional oncology clinics consolidate purchasing through GPO contracts. Pharmaceutical sponsors exhibit lowest price sensitivity, prioritizing API throughput and regulatory audit trail completeness over per-seat licensing economics.
Supply Chain Analysis
Inbound logistics costs for specialized server hardware from Taiwan and South Korea fluctuate with container availability across Pacific trade lanes, though cloud-native deployment models increasingly eliminate physical infrastructure dependencies. Software development talent concentrates in India, the United States, and Germany, with natural language processing engineering expertise anchoring vendor R&D location decisions. Single-source vulnerability persists for FHIR certification testing bodies, creating bottleneck risk for vendors seeking 21st Century Cures Act compliance. Distribution runs through direct enterprise sales teams for hospital networks, with channel partners serving community oncology practices requiring localized implementation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as FHIR-based interoperability transforms registry software from departmental tool to health system infrastructure layer, with API-first architectures capturing disproportionate value from pharmaceutical real-world evidence pipelines.
For Market Incumbents: Shield installed base erosion by embedding registry modules deeper within radiation oncology and EHR workflows, creating data gravity that raises switching costs. Prioritize backward integration into NLP training data pipelines to reduce dependency on third-party abstraction tools. Counter cloud-native entrants through professional services bundling that addresses certified registrar staffing shortages.
For New Entrants and Emerging Players: Anchor in pharmaceutical sponsor segments where procurement committees lack incumbent relationships and prioritize API-first architectures over workflow integration depth. Target Indian and Brazilian public health digitization initiatives as white-space opportunities with lower competitive density. Pursue federated learning partnerships with academic medical centers as a go-to-market angle that bypasses direct hospital sales cycle complexity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with demonstrated CE marking pathways for AI-augmented coding modules, as the EU AI Act risk classification framework elevates compliance barriers. Long-term viability rests on control over data capture workflows rather than standalone software functionality. Monitor FDA real-world evidence guidance evolution as the primary inflection signal for pharmaceutical procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding registry modules within Epic and Cerner workflows captures hospital procurement decisions. |
| Strategic Partnership | Federated learning alliances with academic medical centers enable privacy-preserving multi-site research. |
| Acquisition of Specialist Firm | Natural language processing boutiques accelerate AI-augmented pathology abstraction capabilities. |
| Geographic Expansion | Indian and Brazilian public health digitization opens procurement channels outside saturated North American markets. |
| Product Launch | CE-marked AI coding modules satisfy EU AI Act conformity assessment requirements for European hospital buyers. |
Study Parameters
Cross-validation between primary interviews with cancer registrars, hospital IT procurement officers, and pharmaceutical real-world evidence executives anchors the qualitative findings against secondary validation from FDA 21st Century Cures Act certification databases, CMS Medicare claims files, and state cancer registry submission protocols. Bottom-up modeling of vendor-reported deployment metrics triangulates with top-down expenditure analysis across United States hospital networks and European research institutions.
Sensitivity analysis around cloud migration velocity and certified registrar supply constraints shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user institution type, application workflow depth, and regional regulatory cluster. CAGRs derive from logistic adoption curve fitting against historical EHR consolidation patterns, with AI-augmented coding penetration and pharmaceutical sponsor procurement acceleration as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA interoperability enforcement and stable cloud infrastructure pricing; material deviation in either would warrant model refresh. Specific risks include state-level registry protocol fragmentation delays and EU AI Act implementation timeline uncertainty. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Femtech Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market