
 Pharmaceutical Blister Packaging Market | 2026-2036
Pharmaceutical Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Blister Packaging Market Intelligence
Demand from contract manufacturing organizations (CMOs) is rotating market share away from direct procurement by large pharmaceutical firms. Amcor plc leverages its extensive manufacturing footprint to serve these multinational clients. Klöckner Pentaplast specializes in high-barrier films like Aclar for sensitive drug formulations. Meanwhile, Constantia Flexibles competes on flexible solutions tailored for both unit-dose and multi-dose applications.
Pharmaceutical blister packaging is a pre-formed plastic packaging solution used for solid oral dosage forms, comprising a thermoformed or cold-formed cavity and a lidding material. Its primary purpose is to provide product integrity, tamper evidence, and protection from environmental factors like moisture and oxygen. Thermoforming blisters made from PVC and PVDC dominate in volume for tablet and capsule packaging due to cost-effectiveness. However, cold form blisters using aluminum foil offer superior barrier properties, commanding higher margins for moisture-sensitive medications.
Product design and material selection are governed by stringent health and safety standards set by regulators including the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). Regulations like China's NMPA requirements for drug packaging integrity and traceability directly shape market access and material qualifications. Future competitive advantage will hinge on developing sustainable, mono-material packaging solutions that meet these rigorous compliance mandates.
Market Dynamics
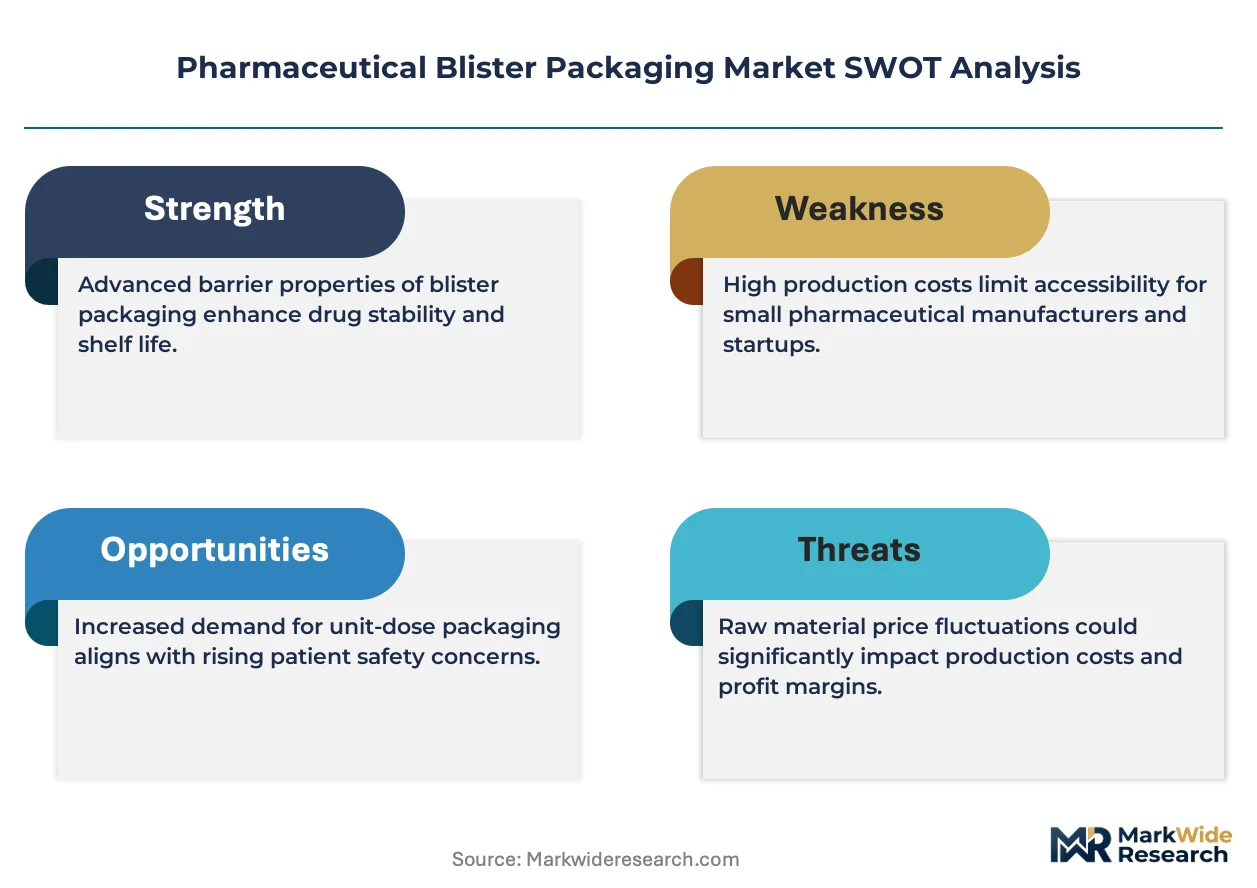
The central force shaping the market is the escalating tension between stringent regulatory mandates for product protection, such as those from the FDA and EMA, and the concurrent industry-wide pressure to adopt sustainable, recyclable mono-materials. This dynamic is concentrating investment in new film technologies.
Growth Catalysts
- Nutraceutical Expansion:The growing consumer use of vitamins, minerals, and supplements is creating a large, less-regulated application category for blister packaging, driving volume demand for standard PVC and PVDC formats.
- Regulatory Mandates:Requirements for child-resistant and senior-friendly features, enforced by bodies like the US Consumer Product Safety Commission, compel product redesigns that favor unit-dose blister formats over bottles.
- Generic Drug Production:India's expanding role as a global supplier of generic medicines, supported by policies like the PLI scheme, fuels significant domestic demand for cost-effective thermoformed blister solutions.
Market Restraints
- Material Cost Volatility:Price fluctuations in aluminum, the primary raw material for high-barrier cold form foils, create margin pressure and forecasting challenges for manufacturers of packaging for moisture-sensitive drugs.
- Regulatory Qualification Hurdles:The extensive time and cost required to validate new packaging materials under strict pharmaceutical stability testing protocols from the FDA and EMA slows the adoption of innovative or sustainable polymers.
- Substitution from Smart Packaging:The emergence of smart bottles with integrated adherence monitoring poses a long-term substitution threat, particularly for high-value chronic care medications where compliance is a key concern.
Strategic Opportunities
- Sustainable Mono-Materials:Developing high-barrier, mono-material PET or PP films that are compatible with existing recycling streams offers a significant competitive advantage in response to sustainability pressures from the EU Green Deal.
- Digitalization for Traceability:Integrating QR codes or NFC tags onto blister packs to meet traceability requirements, such as the EU's Falsified Medicines Directive, opens new revenue streams in data management and patient engagement.
- OTC Market Penetration:Expanding the use of unit-dose blister packs for over-the-counter medications in emerging markets can help combat counterfeiting and improve dosing accuracy, creating a new growth vector.
Industry Challenges
- Capital-Intensive Re-tooling:Transitioning production lines from traditional PVC/PVDC to new mono-material films requires significant capital expenditure on machinery and process validation, creating a barrier for smaller converters.
- Complex Compliance Validation:Navigating the fragmented and evolving landscape of global packaging regulations, including specific material contact standards from the NMPA, PMDA, and FDA, consumes substantial internal resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Blister Packaging Market |
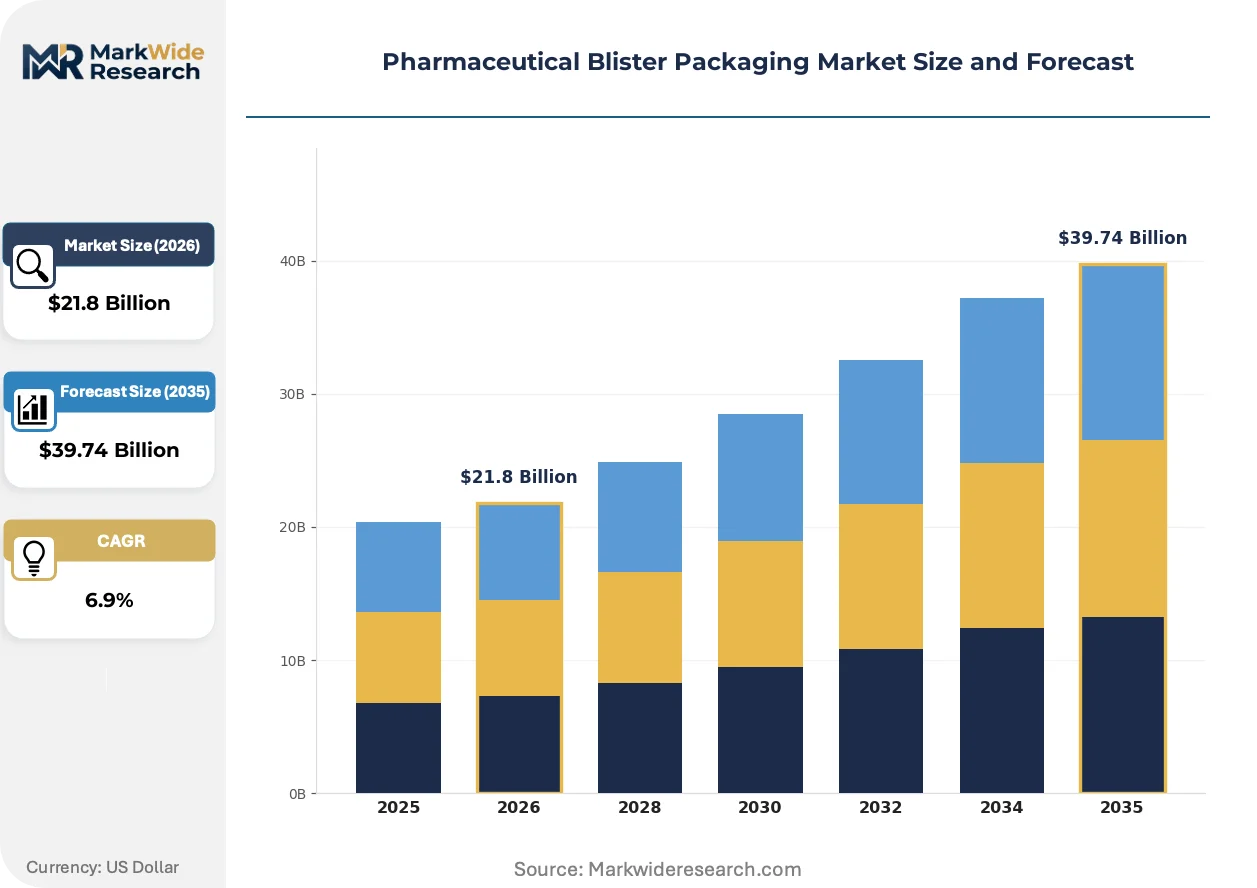
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Form Blister, Heat Form Blister, Thermoforming Blister, Cold Seal Blister, Push-Through Blister Material: PVC, PVDC, Aluminum Foil, Paperboard, Aclar, Polyethylene Terephthalate Application: Tablet Packaging, Capsule Packaging, Sachet Packaging, Medical Device Packaging, Nutraceutical Packaging Packaging Type: Unit Dose, Multi-Dose, Child-Resistant, senior-Friendly, Tamper-Evident |
| Companies Covered | Smurfit Westrock, Huhtamäki Oyj, Amcor plc, WINPAK LTD., CCL Healthcare, Constantia Flexibles, Klöckner Pentaplast, Nelipak, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Blister Packaging Market Strategic Shifts & Innovations
Sustainability goals are reshaping material science priorities. The industry is navigating the complex trade-off between achieving full recyclability and maintaining the non-negotiable barrier properties required for drug stability and patient safety.
Mono-material PET and PP films provide a recyclable alternative to traditional multi-layer PVC/PVDC structures for thermoforming. Pharmaceutical firms with public sustainability commitments are piloting these materials for less-sensitive solid oral dose products. This shift is decomposing the market's historical segmentation between low-barrier thermoform and high-barrier cold form, creating a new mid-tier focused on recyclability.
China's NMPA has implemented stricter requirements for drug packaging integrity and full supply chain traceability. This policy compels manufacturers to invest in higher-quality barrier films and advanced lidding technologies to guarantee product safety. The cold form foil segment is most impacted, as suppliers must now demonstrate compliance with these rigorous Chinese standards for market access.
A significant shift in purchasing behavior involves the rotation of procurement volume toward contract manufacturing and development organizations (CDMOs). This pattern disintermediates the direct sales channel between major pharmaceutical companies and packaging converters for many drug portfolios. The trend is most pronounced in North America and Europe, where CDMOs manage end-to-end drug production and packaging.
Pharmaceutical Blister Packaging Market Segmentation
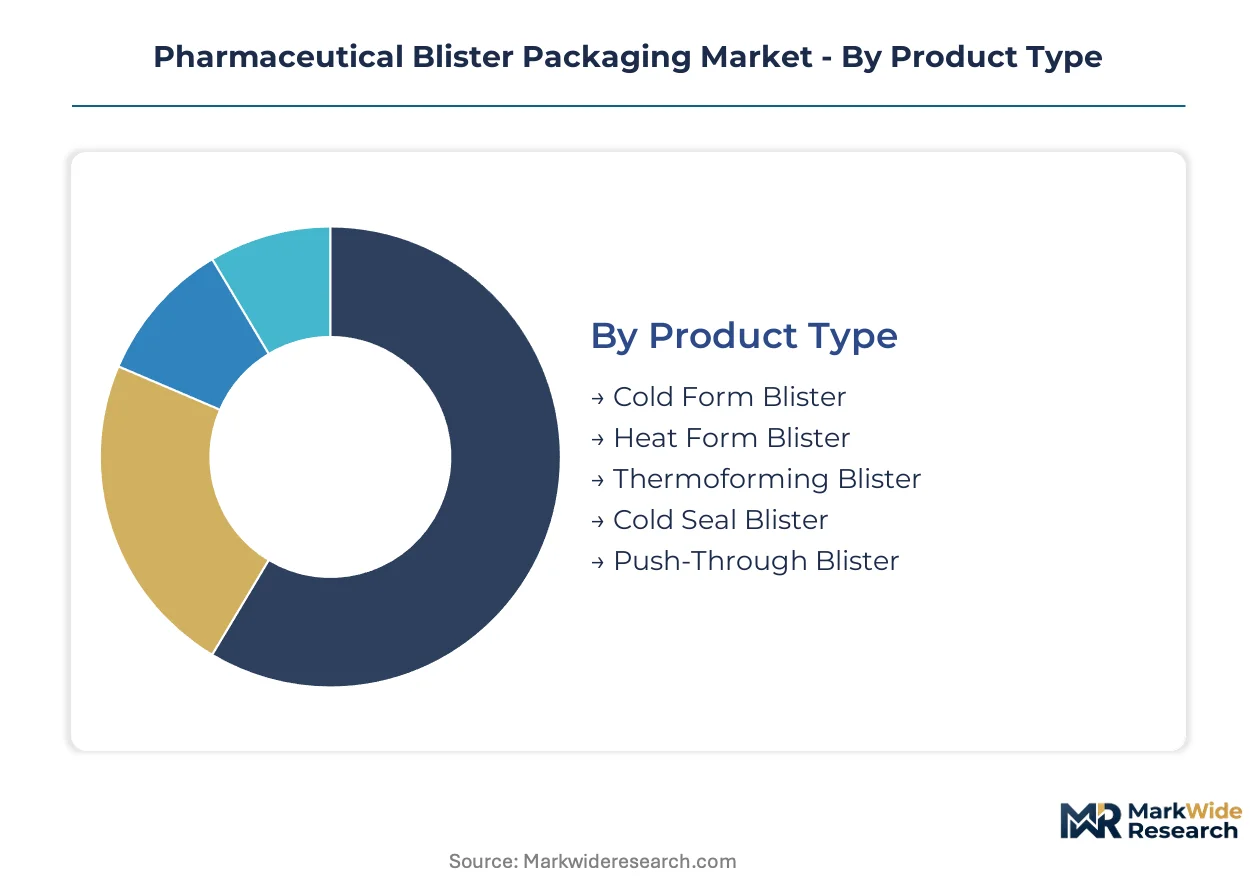
Understanding market segmentation is crucial for identifying distinct demand patterns and competitive landscapes within the pharmaceutical blister packaging industry. These segments delineate specific product types, materials, applications, and packaging formats, each driven by unique functional requirements and regulatory pressures. Analyzing these categories helps pinpoint areas of concentrated value and emerging opportunities for manufacturers.
Product Type:
Margin pools within product types are heavily influenced by barrier performance and material costs.
- Cold Form Blister:This packaging solution utilizes aluminum foil to create a cavity, offering superior barrier properties against moisture and oxygen. Demand concentrates in regions like Europe and China for highly sensitive drug formulations requiring maximum protection.
- Thermoforming Blister:Formed from plastic films like PVC and PVDC using heat, this type offers cost-effectiveness and high-volume production capabilities. It sees extensive demand for standard tablets and capsules, particularly in India due to generic drug manufacturing.
- Heat Form Blister:Similar to thermoforming, heat form blisters are created by heating plastic sheets to mold cavities for various solid dose products.
- Cold Seal Blister:These blisters use a pressure-sensitive adhesive coating, eliminating the need for heat during sealing, suitable for heat-sensitive drugs.
- Push-Through Blister:Designed for easy drug removal, this type allows a tablet or capsule to be pushed through the lidding material.
The dominant share belongs to Thermoforming Blister, while Cold Form Blister is closing the gap fastest.
Material:
Material selection hinges on a trade-off between cost, barrier properties, and regulatory compliance.
- Aluminum Foil:Employed in cold form blisters, this material provides an absolute barrier to moisture, oxygen, and light, commanding higher margins for critical pharmaceuticals. It is essential for moisture-sensitive medications globally.
- Aclar:A high-barrier fluoropolymer film, Aclar offers exceptional moisture protection and chemical resistance for highly sensitive drug formulations. Klöckner Pentaplast specializes in these advanced films for multinational clients.
- PVC:Polyvinyl chloride is a cost-effective and widely used material for thermoformed blisters, offering good rigidity and clarity for standard drugs.
- PVDC:Polyvinylidene chloride coatings enhance the barrier properties of PVC films against moisture and oxygen, extending product shelf life.
- Paperboard:Used primarily as a secondary packaging component or for certain over-the-counter blister designs, paperboard offers sustainability benefits.
- Polyethylene Terephthalate:PET films are gaining traction as a mono-material solution for recyclable blister packaging, aligning with sustainability mandates.
Aluminum Foil drives premium pricing for maximum protection, with PVC remaining vital for cost-effectiveness.
Application:
Volume demand across applications reflects prevalent dosage forms and emerging consumer health trends.
- Tablet Packaging:This application represents the largest volume segment, utilizing various blister types for solid oral dosage forms. Tablet packaging is a foundational requirement for pharmaceutical manufacturers worldwide.
- Nutraceutical Packaging:The expanding consumer use of vitamins, minerals, and supplements drives significant demand for standard PVC and PVDC blister formats. This category experiences rapid growth due to increasing health consciousness.
- Capsule Packaging:Blister packaging provides protection and unit-dose dispensing for capsules, a common oral dosage form.
- Sachet Packaging:While less common for blisters, sachet packaging involves flexible pouches for single-dose powders or liquids.
- Medical Device Packaging:Certain small medical devices and diagnostic kits utilize blister packaging for sterility and protection.
Tablet Packaging accounts for the largest volume, while Nutraceutical Packaging sees rapid expansion.
Packaging Type:
Regulatory mandates and patient safety considerations heavily influence the adoption of specific packaging types.
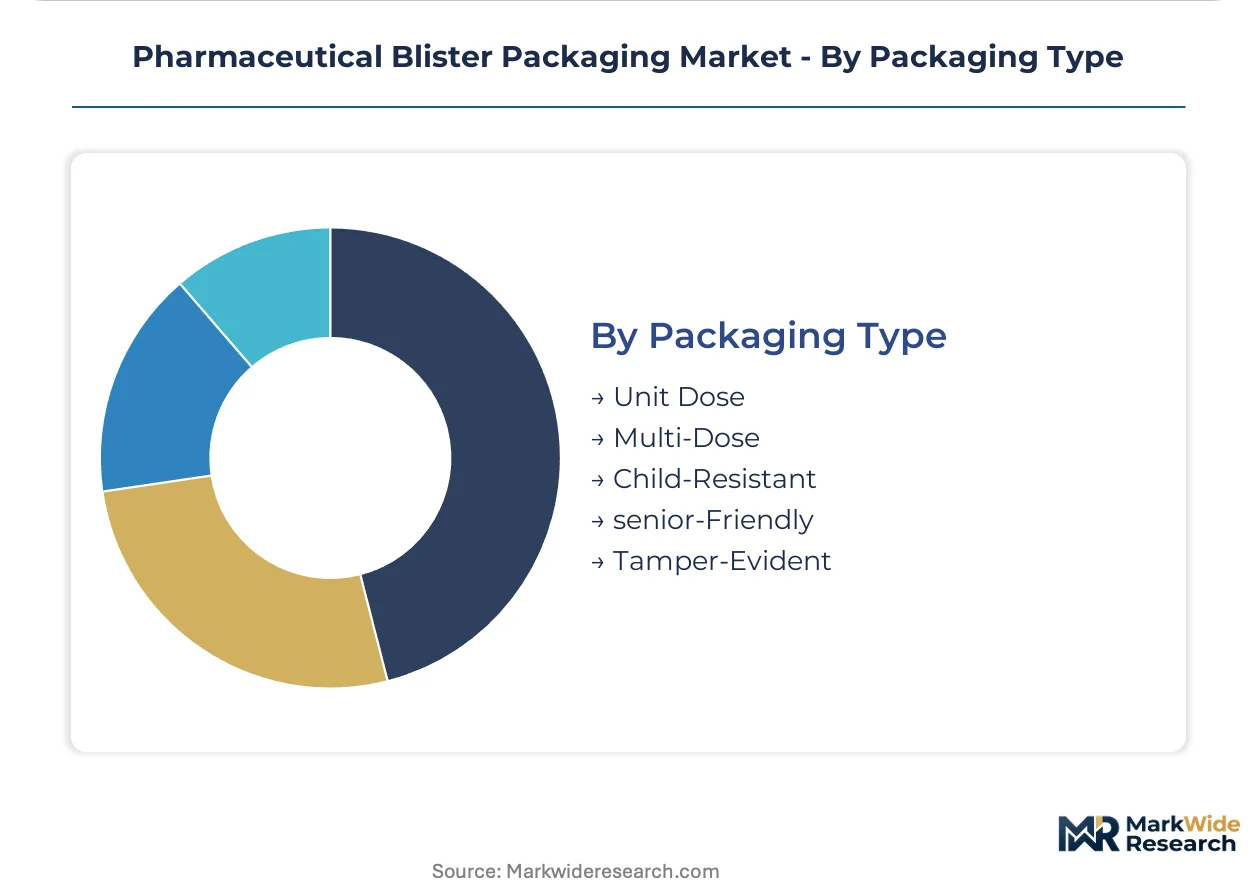
- Child-Resistant:These blister designs incorporate features making it difficult for children to open, mandated by regulators like the US Consumer Product Safety Commission. Such designs compel product redesigns favoring unit-dose formats.
- Unit Dose:Providing individual doses, unit-dose blisters enhance patient compliance, reduce medication errors, and offer tamper evidence. This format is increasingly preferred for prescription and over-the-counter drugs.
- Multi-Dose:Blisters designed to hold multiple doses, often for a specific treatment regimen or daily intake, offer convenience for patients.
- Senior-Friendly:Packaging designed for ease of opening by older adults, balancing accessibility with child-resistance requirements.
- Tamper-Evident:Features that visibly indicate if a package has been opened or altered, crucial for drug safety and integrity.
Child-Resistant packaging is frequently mandated by regulation, while Unit Dose enhances patient safety and convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's robust generic drug manufacturing base drives significant exports of pharmaceutical blister packaging to global markets, particularly Europe and North America. This dynamic is reshaping supply chains for cost-effective packaging solutions. The demand for product integrity and patient safety influences material selection globally.
India
India's expanding role as a global supplier of generic medicines fuels significant domestic demand for cost-effective thermoformed blister solutions. The Production Linked Incentive (PLI) scheme supports local manufacturing, further boosting packaging requirements. Hyderabad and Gujarat represent major pharmaceutical manufacturing clusters driving this volume.
China
China's stringent NMPA requirements for drug packaging integrity and full supply chain traceability directly shape market access and material qualifications. Demand concentrates in the country for highly sensitive drug formulations requiring maximum protection, favoring cold form blisters. The Yangtze River Delta region is a key hub for advanced pharmaceutical packaging production.
United States
The United States market experiences strong demand for child-resistant and senior-friendly packaging features, mandated by bodies like the US Consumer Product Safety Commission. The FDA's strict stability testing protocols also influence material selection for drug safety. The Northeast Corridor remains a significant center for pharmaceutical manufacturing and packaging innovation.
Germany
German pharmaceutical companies prioritize high-barrier films and advanced packaging solutions for sensitive drug formulations. Regulations from the European Medicines Agency (EMA) and the EU Green Deal drive innovation towards sustainable materials. The Rhine-Main region is a prominent cluster for pharmaceutical research, development, and packaging.
Japan
Japanese regulators, specifically the PMDA, enforce rigorous quality and safety standards for pharmaceutical packaging, influencing material and design choices. The country's advanced drug formulations require high-performance barrier properties. The Kanto region, including Tokyo, serves as a central hub for pharmaceutical production and packaging technology.
Pharmaceutical Blister Packaging Market Key Industry Players
Listed leaders compete with private specialists across material innovation and geographic reach within the pharmaceutical blister packaging market. The market exhibits a tiered structure, with large multinational corporations holding significant global presence. Global integrated manufacturers, regional converters, and specialized material suppliers represent distinct strategic archetypes. Companies pursue capacity expansion, strategic partnerships, and portfolio diversification to enhance their competitive positioning and meet evolving regulatory demands.
Global integrated manufacturers, such as Amcor plc, occupy a dominant position through their extensive manufacturing footprint and broad multinational client base. Specialists in high-barrier films, like Klöckner Pentaplast, a German-headquartered company, exemplify material innovation for sensitive drug formulations, particularly with products like Aclar. Constantia Flexibles, an Austrian company, represents agile providers of flexible solutions tailored for diverse unit-dose and multi-dose applications, adapting to varied market needs. These entities collectively shape the market's strategic direction and drive product development.
| Leading Market Players |
|---|
| Smurfit Westrock |
| Huhtamäki Oyj |
| Amcor plc |
| WINPAK LTD. |
| CCL Healthcare |
| Constantia Flexibles |
| Klöckner Pentaplast |
| Nelipak |
| Sonoco Products Company |
Cost & Logistics Intelligence
Extended lead times for specialized high-barrier films, such as Aclar, directly influence the pricing power of material suppliers and reflect a concentrated upstream supply chain. This dynamic creates cost predictability challenges for pharmaceutical manufacturers.
Pricing Analysis
A distinct pricing gap exists between traditional PVC/PVDC thermoformed blisters and advanced mono-material PET/PP alternatives. Contract-based long-term offtake agreements dominate for established formats. Price differentiation stems from barrier properties, specifically for moisture-sensitive drugs, and the level of regulatory certification required by bodies like the FDA. Pricing pressure intensifies for standard PVC formats due to high volume demand from generic drug manufacturers in India, who are highly price-sensitive, while innovator pharmaceutical firms prioritize performance over cost.
Supply Chain Analysis
Strategic stockpiling of critical raw materials, like aluminum foil, is common for high-barrier cold form blister manufacturers to mitigate price volatility. Supply concentration centers on key regions such as China for raw materials and Germany for specialized film production. Dependencies include PVC resin, PVDC coatings, and advanced fluoropolymer films. Commodity price volatility for aluminum represents a significant structural risk. Distribution runs through a hybrid model, with direct sales to large pharma and indirect channels via CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as incumbents must navigate the long-term threat posed by smart packaging solutions with integrated adherence monitoring. Protecting market share against these emerging technologies is paramount.
For Market Incumbents: Consolidate market position through strategic acquisitions of specialized mono-material film developers to gain intellectual property and production capabilities. Expand high-barrier film manufacturing capacity in regions with stringent regulatory mandates, such as the EU and China, to meet escalating demand for product integrity. This counters margin pressure from generic drug volume and the threat of smart packaging by offering advanced, compliant solutions. Invest heavily in R&D for sustainable, recyclable film technologies.
For New Entrants and Emerging Players: Differentiate on sustainability and digital traceability solutions, offering high-barrier mono-material PET or PP films for less-sensitive solid oral dose products. The most penetrable segment is nutraceutical packaging in emerging markets, where demand for basic blister formats is high and regulatory hurdles are lower. A key go-to-market angle involves providing compliance-as-a-service for complex global regulations, particularly NMPA requirements for supply chain integrity.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven essential infrastructure play because pharmaceutical packaging is fundamental to drug safety and efficacy globally. Target specialized material innovators developing high-barrier, mono-material films or regional converters with strong compliance expertise in specific markets like Japan or Germany. A critical signal to watch is the adoption rate of new sustainable mono-materials by major pharmaceutical companies, indicating a broader industry shift beyond pilot programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-material R&D | Develops recyclable alternatives to traditional multi-layer films, meeting EU Green Deal mandates. |
| Expand High-Barrier Film Production | Addresses demand for superior protection for sensitive drug formulations, particularly in China. |
| Acquire Digital Traceability Providers | Integrates QR/NFC technology to meet global serialization and anti-counterfeiting regulations. |
| Certify New Materials for NMPA/EMA | Ensures market access and compliance for innovative packaging solutions in regulated regions. |
| Form Partnerships with CDMOs | Secures volume through contract manufacturing organizations, aligning with procurement shifts. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and trade publications. This involved extensive interviews with pharmaceutical procurement managers, packaging engineers, CDMO executives, and regulatory affairs specialists across major geographies. Bottom-up data collection from market participants was triangulated with top-down analysis of macroeconomic indicators and healthcare spending trends.
Segmentation dimensions modeled include product type, material, application, packaging type, and regional regulatory cluster across the analysis window. Quantitative forecasts derive compound annual growth rates from historical data, projected market shifts, and expert consensus. Key industry-specific forecast inputs include generic drug production volumes in India and evolving nutraceutical consumption rates in Western markets.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or rapid technological disruption would require recalibration. Forecasts reflect assumptions regarding material cost stability and global pharmaceutical production trends. Revision becomes warranted when significant changes in global trade policies or public health crises cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market