
 Serum Bottles Market | 2026-2036
Serum Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Serum Bottles Market Analytics
China is reshaping competitive dynamics in serum bottle manufacturing through expanded borosilicate glass melting capacity and precision molding investments. Gerresheimer AG leverages its European furnace network to sustain premium glass supply for biologics clients. Virospack specializes in dropper-closure integration for precision dosing applications. Schott anchors high-value segments through its FIOLAX brand borosilicate tubing dominance.
Serum bottles are primary packaging vessels engineered from borosilicate glass or cyclic olefin polymers, designed to maintain sterility, chemical inertness, and light protection for injectable and diagnostic reagents across shelf lives exceeding twenty-four months. Glass segments retain margin leadership in biologics due to oxygen and moisture barrier superiority, while plastic alternatives gain traction in single-use diagnostic workflows where breakage risk and weight reduction matter. Pharmaceutical companies represent the dominant end-user channel, though research laboratories represent the fastest-growing demand segment as contract research organizations scale peptide and oligonucleotide development.
FDA stability-testing protocols and EMA Annex 1 sterile manufacturing guidelines mandate container-closure integrity validation, directly shaping material qualification timelines and supplier audit intensity. The EU MDR and REACH chemical disclosure requirements add compliance layers for European-market entrants. China's NMPA alignment with ICH Q1A standards accelerates local substitution of imported packaging. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP extractables-testing thresholds as these divergence points determine regional sourcing economics and qualification cost structures.
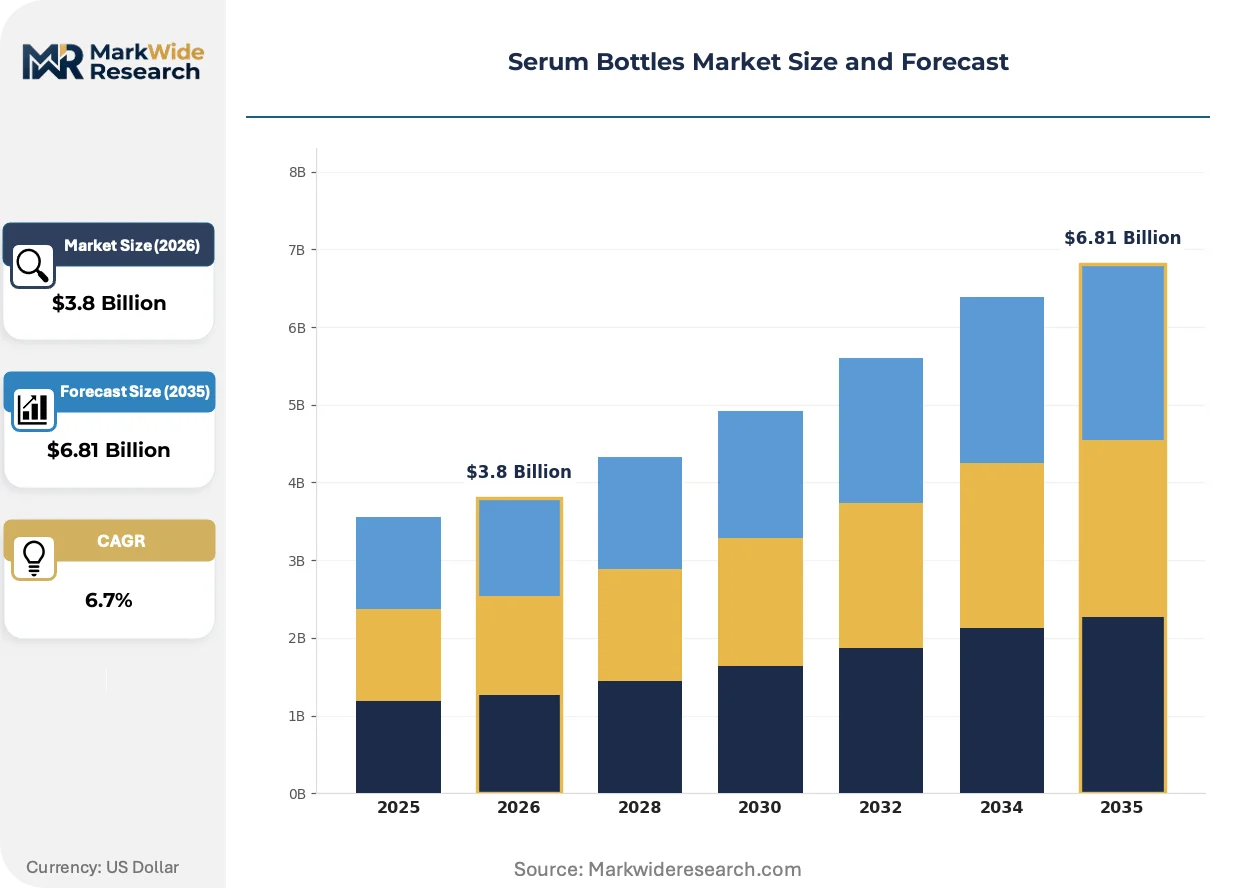
Market Dynamics
Biopharmaceutical manufacturing expansion is compressing supplier qualification timelines while amplifying demand for container-closure integrity validation under FDA and EMA sterile manufacturing protocols.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Container-closure integrity testing mandates are accelerating replacement cycles for legacy packaging across European biologics facilities.
- Peptide and oligonucleotide development:Contract research organizations are scaling serum bottle procurement for extended-stability reagent storage.
- Borosilicate glass melting capacity:Expanded furnace investments in China are reducing import dependency for high-barrier pharmaceutical glass.
Market Restraints
- Energy-intensive furnace operations:Natural gas price volatility in Germany is compressing margins for European borosilicate tubing producers.
- Single-source dependency:High-purity sand supply for pharmaceutical glass concentrates in limited geographic corridors.
- Extractables-testing divergence:Misaligned USP, EP, and ChP thresholds are extending material qualification timelines for multi-regional suppliers.
Strategic Opportunities
- Diagnostic single-use workflows:Cyclic olefin polymer bottles are capturing share in point-of-care testing where breakage risk and weight reduction outweigh barrier requirements.
- India's PLI scheme for pharmaceuticals:Domestic packaging localization incentives are creating captive demand for regional serum bottle manufacturing.
- Dropper-closure integration:Precision dosing applications in ophthalmic and biologic delivery are opening premium pricing tiers for integrated closure systems.
Industry Challenges
- Container-closure integrity validation:Demonstrating sterility maintenance across twenty-four-month shelf lives requires specialized equipment and trained personnel that mid-tier suppliers struggle to access.
- Pharmacopeial harmonization delays:Divergent extractables-testing protocols between USP, EP, and ChP are forcing redundant qualification studies for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum Bottles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Sterile, Non-Sterile Capacity: 5ml, 10ml, 20ml, 50ml Closure Type: Rubber Stopper, Aluminum Cap, Plastic Cap, Sealed Cap End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Clinics |
| Companies Covered | Boyu Packaging, Gerresheimer AG, Virospack, Schott, Aptar, Paupack, Vitro, HCP Packaging, Ningbo Songmile Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum Bottles Market Evolving Landscape
Material science advances and regulatory harmonization pressures are converging to reshape competitive positioning in serum bottle manufacturing. Three developments warrant particular attention.
Cyclic olefin polymer formulations are collapsing the traditional glass-plastic performance gap for diagnostic applications. Point-of-care testing manufacturers are adopting these materials at accelerated pace for single-use workflows. The technology is collapsing breakage-risk premiums that previously protected glass incumbents in weight-sensitive segments.
REACH chemical disclosure requirements and EU MDR traceability mandates are forcing reformulation of closure elastomers and coating chemistries. Manufacturers serving European markets are accelerating substitution of legacy silicone and rubber formulations. Biologics applications face the steepest compliance cost escalation as extractables thresholds tighten.
Buyer consolidation among contract development and manufacturing organizations is compressing supplier negotiation cycles. Large pharmaceutical packaging distributors are displacing direct procurement relationships for mid-tier biotech firms. This pattern is most visible in the United States, where three national distributors now control the majority of sterile injectable packaging flows to emerging biologics developers.
Serum Bottles Market Segmentation
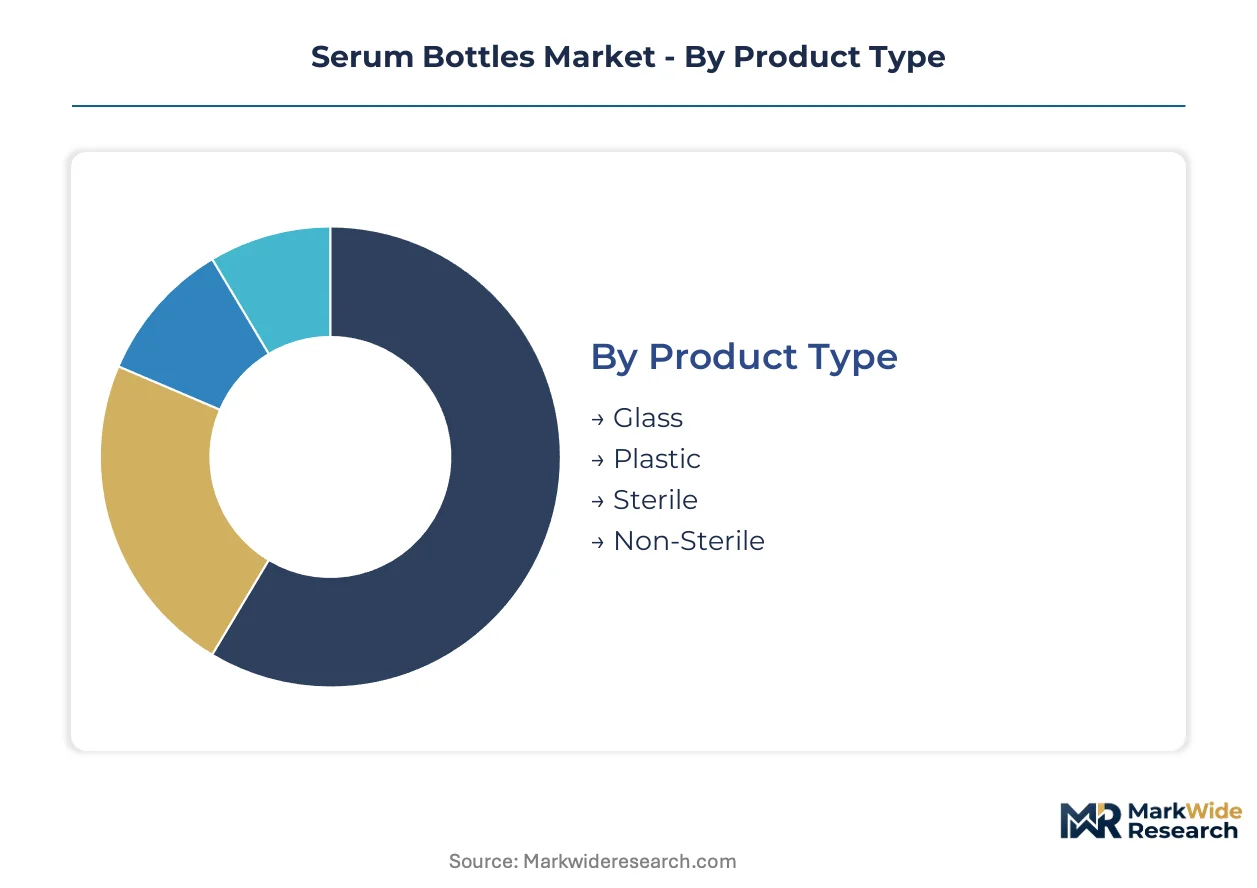
Serum bottle procurement patterns diverge sharply across material specifications, capacity requirements, and end-use sterility protocols. Understanding these segment boundaries enables suppliers to align furnace investments and molding capacity with actual demand concentration rather than assumed homogeneity.
Product Type:
Glass formulations dominate biologics applications demanding oxygen and moisture barriers, while polymer alternatives capture workflow efficiency in diagnostic settings.
- Glass:Borosilicate formulations from Schott's FIOLAX tubing and Gerresheimer's European furnace network supply high-barrier containers for twenty-four-month shelf life requirements. Demand concentrates in United States and German biologics manufacturing where FDA and EMA stability-testing protocols mandate inert surface properties.
- Plastic:Cyclic olefin polymers reduce breakage risk and shipping weight for point-of-care diagnostic workflows. China's expanded polymer compounding capacity is displacing imported glass in domestic diagnostic reagent packaging.
- Sterile:Pre-sterilized units eliminate terminal sterilization steps for aseptic fill-finish operations.
- Non-Sterile:Unsterilized containers serve research laboratories performing in-house sterilization or non-parenteral applications.
The dominant share belongs to Glass, while Plastic is closing the gap fastest in diagnostic single-use workflows.
Capacity:
Volume specifications track directly to dose economics and reagent concentration protocols across therapeutic categories.
- 5ml:Compact format for high-potency biologics and pediatric dosing applications where minimization of overfill waste drives specification.
- 10ml:Standard volume for peptide and oligonucleotide reagents stored by contract research organizations scaling development programs.
- 20ml:Mid-range capacity capturing bulk diagnostic reagent packaging and multi-dose vaccine formulations.
- 50ml:Largest format for reference standard storage and industrial cell culture media applications.
Procurement volume concentrates in 10ml specifications, though 5ml formats are expanding most quickly in precision biologics dosing.
Closure Type:
Sealing technology selection determines container-closure integrity validation outcomes under pharmacopeial testing regimes.
- Rubber Stopper:Bromobutyl and chlorobutyl elastomers provide gas barrier properties for oxygen-sensitive biologics. EMA Annex 1 guidelines are accelerating substitution of legacy formulations to meet tightened extractables thresholds.
- Aluminum Cap:Crimp-seal systems deliver tamper-evidence and mechanical protection for glass vial shipments. German glass tubing producers source aluminum closure components from regional metal forming specialists.
- Plastic Cap:Threaded polypropylene closures enable user-friendly access in research laboratory settings.
- Sealed Cap:Factory-applied hermetic seals guarantee sterility maintenance for pre-filled and ready-to-use presentations.
Rubber Stopper configurations retain the largest procurement share, though Sealed Cap integration is gaining share fastest in ready-to-use biologics delivery systems.
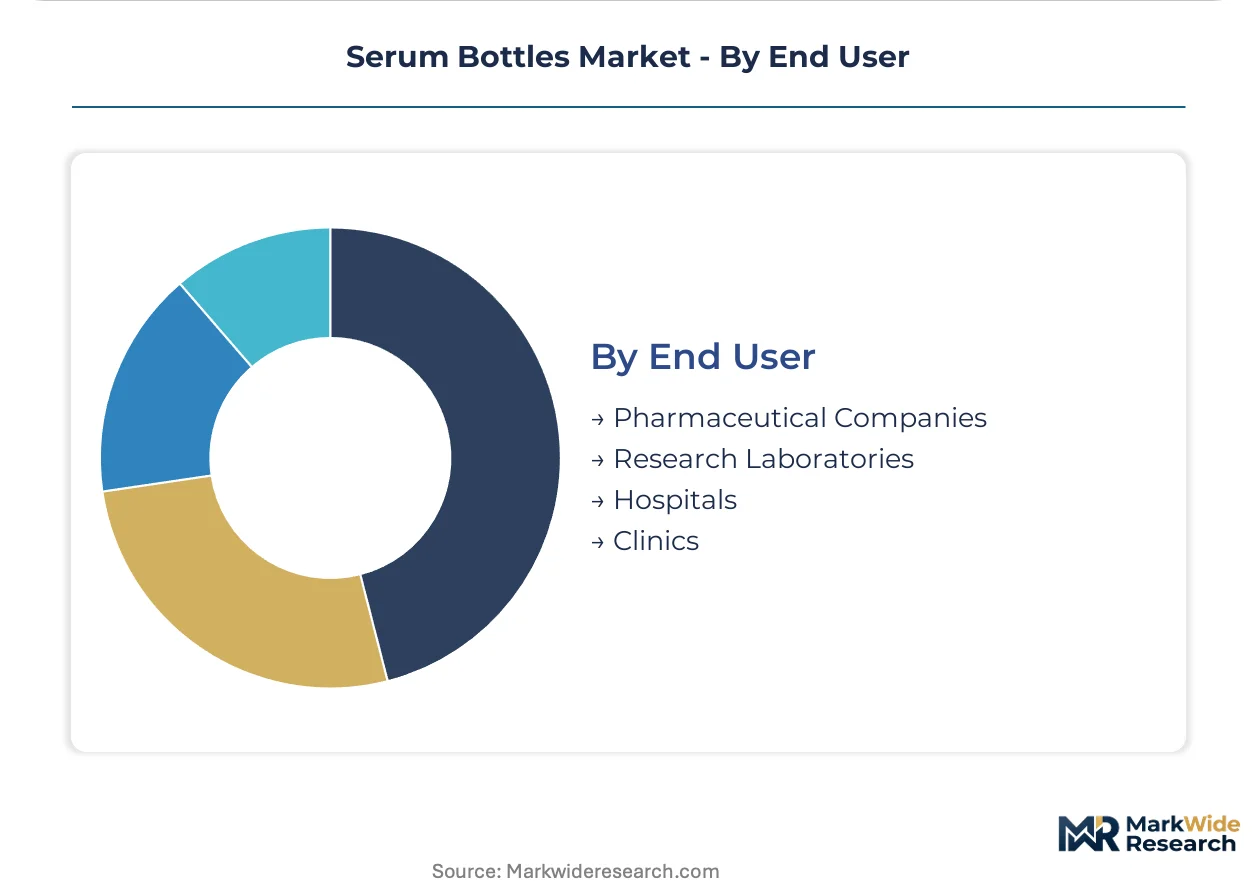
End User:
Customer type shapes order patterns, qualification intensity, and pricing tolerance through distinct procurement workflows.
- Pharmaceutical Companies:Multinational drug manufacturers impose extended supplier audits and container-closure integrity validation requirements. FDA stability-testing protocols dictate material qualification timelines for new product launches.
- Research Laboratories:Contract research organizations scaling peptide and oligonucleotide development are expanding serum bottle procurement for extended-stability reagent storage. India's PLI scheme for pharmaceuticals is creating captive demand for regional packaging supply.
- Hospitals:Institutional purchasers prioritize ready-to-use sterile presentations for compounding pharmacy operations.
- Clinics:Smaller healthcare facilities source through distributor consolidation channels controlling sterile injectable packaging flows.
Pharmaceutical Companies command the dominant procurement volume, while Research Laboratories are climbing the fastest as contract development organizations scale reagent storage infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites Europe's dominance in sterile injectable distribution, while China's high-speed rail network connects borosilicate glass furnace clusters to coastal biopharma manufacturing zones.
United States
FDA stability-testing protocols drive demand for container-closure integrity validation across Massachusetts and North Carolina biologics corridors. The Inflation Reduction Act's domestic manufacturing incentives are accelerating packaging localization near Boston and Research Triangle Park fill-finish facilities.
Germany
EMA Annex 1 sterile manufacturing guidelines compress supplier qualification timelines for Bavaria-based biologics producers. Natural gas price volatility in the Rhine-Ruhr furnace belt is forcing energy efficiency investments at tubing manufacturing sites near Mainz.
China
NMPA alignment with ICH Q1A standards accelerates substitution of imported pharmaceutical glass in Zhejiang and Jiangsu provinces. Expanded borosilicate melting capacity in the Yangtze River Delta is reducing dependency on European tubing imports for domestic vaccine producers.
India
The PLI scheme for pharmaceuticals creates captive demand for regional serum bottle manufacturing in Maharashtra and Gujarat. CDSCO regulatory convergence with FDA protocols is enabling contract research organizations in Hyderabad and Bangalore to qualify local packaging for export-bound biologics.
Japan
PMDA's stringent extractables-testing requirements sustain premium pricing for high-barrier glass in the Kanto biopharma cluster. METI's supply chain resilience initiatives are encouraging domestic furnace investments near Osaka to reduce import exposure for precision biologics packaging.
Serum Bottles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and precision molding. The vendor base stratifies between multinational glass tubing producers with captive furnace networks and regional fabricators serving diagnostic workflows. Three archetypes dominate: borosilicate furnace operators, polymer compounding specialists, and integrated closure-system designers. Capacity expansion and dropper-closure technology licensing represent the primary competitive vectors as biologics manufacturers consolidate supplier panels.
Among European furnace operators, Gerresheimer AG and Schott occupy positions anchoring premium glass supply for extended-shelf-life biologics. Virospack exemplifies the integrated closure-system archetype, sitting within the precision dosing tier where dropper-seal integration commands pricing premiums. These three names represent the competitive spectrum from upstream material dominance to downstream delivery-system specialization.
| Leading Market Players |
|---|
| Boyu Packaging |
| Gerresheimer AG |
| Virospack |
| Schott |
| Aptar |
| Paupack |
| Vitro |
| HCP Packaging |
| Ningbo Songmile Packaging |
| Others |
Value Network & Pricing Analysis
Single-source dependency on high-purity sand supply for pharmaceutical glass concentrates pricing power among furnace operators in Germany and China while compressing margin buffers for mid-tier fabricators serving diagnostic workflows. This concentration dynamic forces a three-tier pricing structure across premium FIOLAX-certified tubing, standard borosilicate formulations, and economy polymer alternatives, with each tier tethered to distinct qualification timelines and buyer risk tolerance.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with pharmaceutical companies capturing 15-25% unit cost reductions at annual contract thresholds above 10 million units. Price differentiation rests on EMA Annex 1 compliance certification and container-closure integrity validation depth, with FDA-validated suppliers commanding 30-40% premiums over research-grade alternatives. Cost compression in standard glass segments is intensifying because Chinese furnace expansion is flooding diagnostic-grade supply, while biologics manufacturers show least price sensitivity due to shelf-life failure costs. Research laboratories represent the most price-sensitive segment, frequently substituting cyclic olefin polymers where barrier requirements permit.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus as European furnace operators face 8-12% cost disadvantages against Yangtze River Delta competitors. Geographic supply concentrates in Germany, China, and the United States, with borosilicate tubing drawing from Rhine-Ruhr furnace networks and Zhejiang melting capacity. Raw material dependencies center on high-purity silica sand from limited deposits, natural gas for furnace operations, and aluminum for crimp-seal closures. Single-source vulnerability in pharmaceutical-grade sand creates chokepoint exposure. Distribution runs through three national distributor networks in the United States, direct mill relationships in Germany, and provincial procurement consortia in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopharmaceutical manufacturing expansion represents an early-cycle expansion story, with peptide and oligonucleotide development programs multiplying reagent storage infrastructure requirements faster than incumbent furnace capacity can absorb.
For Market Incumbents: Entrench position through backward integration into borosilicate sand sourcing and captive furnace upgrades in lower-energy-cost geographies. Cyclic olefin polymer substitution threatens glass incumbents in diagnostic workflows; defend through EMA Annex 1 pre-certification bundles that polymer suppliers cannot replicate. Prioritize container-closure integrity validation equipment deployment to compress buyer qualification timelines. For New Entrants and Emerging Players: Build out regional compounding capacity in India under PLI scheme incentives, targeting contract research organizations in Hyderabad and Bangalore with fast-turn qualification support. The most penetrable segment lies in 10ml cyclic olefin polymer bottles for single-use diagnostic workflows where breakage risk and weight reduction outweigh barrier requirements. Go-to-market angle: direct mill relationships displacing distributor markups for mid-tier biotech firms. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors furnace operators with validated European tubing networks over polymer compounders facing commoditization pressure. Long-term viability favors incumbents with EMA and FDA dual-certification depth and dropper-closure integration capabilities. Acquisition target archetype: regional glass fabricators with underutilized molding capacity and latent NMPA certification potential. Signal to watch: CDSCO regulatory convergence accelerating Indian packaging localization for export-bound biologics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Sand Sourcing | Mitigates single-source dependency risk from limited geographic sand deposits. |
| Container-Closure Integrity Pre-Certification | Compresses EMA Annex 1 validation timelines for biologics manufacturers. |
| Cyclic Olefin Polymer Compounding Expansion | Captures diagnostic workflow demand where breakage risk outweighs barrier requirements. |
| Dropper-Closure Integration Licensing | Opens premium pricing tiers in ophthalmic and precision biologic delivery segments. |
| Regional Furnace Investment Under PLI Incentives | Positions captive supply for India's accelerating biopharma manufacturing localization. |
Research Methodology
Desk research of FDA stability-testing protocols, EMA Annex 1 guidelines, and NMPA ICH Q1A alignment documents preceded structured interviews with biopharmaceutical packaging procurement directors, regulatory affairs leads at glass tubing manufacturers, contract research organization supply chain managers, and diagnostic reagent packaging engineers. Secondary validation drew from USP extractables-testing monographs, EP container-closure integrity standards, ChP pharmacopeial thresholds, and customs trade data on pharmaceutical glass imports. Bottom-up demand modeling from end-user procurement patterns triangulated against top-down furnace capacity assessments.
Forecast assumptions held regulatory harmonization timelines and energy cost trajectories within observed patterns while varying biopharmaceutical manufacturing expansion rates and diagnostic workflow plastic substitution elasticities. The analytical framework segmented by material type, capacity specification, closure technology, and end-user channel across the projection horizon. CAGRs derived from installed base replacement cycles, peptide development pipeline scaling, and regional manufacturing localization incentives. Industry-specific inputs included borosilicate furnace utilization rates and cyclic olefin polymer compounding capacity expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese furnace operators or disruptive polymer formulation entrants would shift outcomes beyond modeled ranges. Specific revision risks encompass pharmacopeial harmonization delays extending qualification timelines, natural gas price volatility compressing European margin structures, and REACH chemical disclosure requirements forcing elastomer reformulation costs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market