
 Global Cold Form Blister Packaging Market | 2026-2036
Global Cold Form Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cold Form Blister Packaging Market Intelligence
Generic drug manufacturers are bifurcating from branded drug producers as the faster-growing buyer archetype in cold form blister procurement. ACG anchors its position through deep specialization in aluminum cold form substrates for Indian and African generic supply chains. Amcor plc leverages integrated film-laminate capabilities to sustain volume leadership across European pharmaceutical packaging markets. Constantia Flexibles competes through advanced print-registration technology on high-speed form-fill-seal lines serving Central European CDMOs.
Cold form blister packaging consists of a laminate structure, typically aluminum foil paired with polyamide or PVC films, shaped under mechanical pressure without heat application to create cavity pockets with near-zero moisture vapor transmission rates. This construction delivers primary containment for hygroscopic tablets, effervescent formulations, and temperature-sensitive APIs where extended shelf stability is mandatory. Aluminum cold form blisters dominate unit dose pharmaceutical applications due to their absolute barrier performance and compatibility with tropical climate distribution. Composite cold form blisters represent the fastest-growing product category as formulators seek tailored barrier properties through multi-layer coextrusion without full aluminum substitution. Strip packs concentrate margin pools in contract packaging channels where serialization integration and short-run flexibility command pricing premiums over standard blister cards.
FDA stability guidelines for container-closure systems, EU MDR traceability requirements, and REACH substance restrictions on adhesive constituents collectively elevate compliance costs for laminate suppliers entering regulated pharmaceutical supply chains. The EPA monitors volatile organic compound emissions from solvent-based lamination processes used in domestic cold form manufacturing, pressuring converters toward aqueous or radiation-cured alternatives. Stakeholders must monitor how EMA's evolving quality-by-design expectations for barrier integrity documentation reshape qualification protocols for new cold form substrates.
Market Dynamics
Pharmaceutical contract packagers in India and Central Europe are consolidating procurement volumes around aluminum-barrier laminates, forcing substrate converters to qualify under simultaneous FDA stability guidelines and REACH substance restrictions.
Growth Catalysts
- Moisture-sensitive generics proliferation:Indian CDMOs are scaling cold form strip-pack lines for regulated export markets to the US and EU, creating sustained laminate demand.
- REACH compliance deadlines:ECHA substance restrictions on adhesive constituents are accelerating substrate requalification cycles that lock in qualified suppliers.
- Tropical climate distribution:Near-zero moisture vapor transmission rates from aluminum cold form construction enable shelf-stable distribution across high-humidity corridors in sub-Saharan Africa and Southeast Asia.
Market Restraints
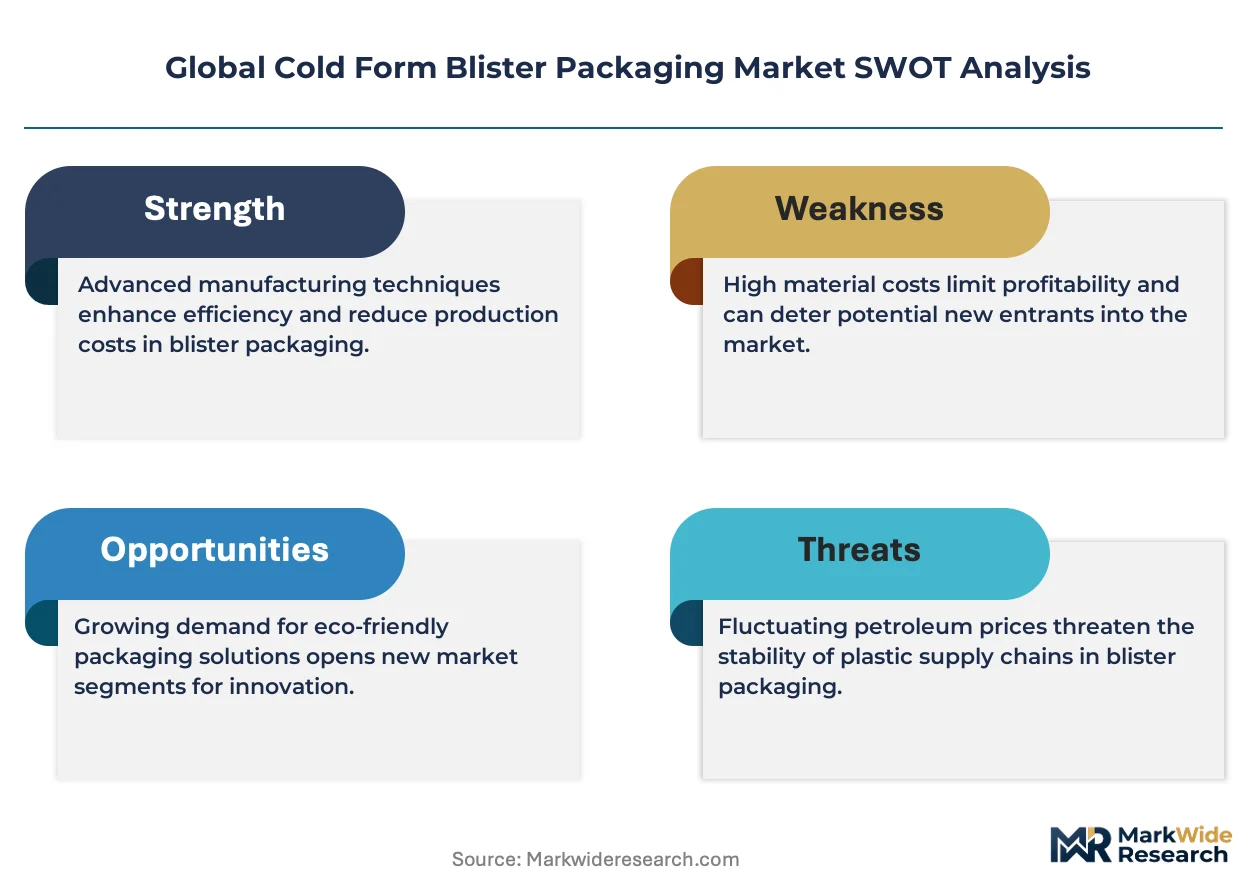
- Aluminum price volatility:Primary aluminum ingot cost swings directly compress converter margins on fixed-price pharmaceutical contracts.
- Solvent-based lamination emissions:EPA monitoring of volatile organic compound outputs pressures domestic manufacturers toward capital-intensive aqueous or radiation-cured process conversions.
- PVC substitution limitations:Polyamide film alternatives face technical barriers in deep-draw formability for high-cavity count blister configurations.
Strategic Opportunities
- Composite multi-layer coextrusion:Tailored barrier properties without full aluminum substitution are opening unit-dose applications for temperature-sensitive biologics.
- Serialization-integrated contract packaging:EU MDR traceability requirements position strip-pack channels for premium pricing on short-run, trackable configurations.
- Indian domestic generic houses:PLI scheme incentives for pharmaceutical manufacturing are expanding captive packaging demand from Mumbai and Hyderabad clusters.
Industry Challenges
- Barrier integrity documentation:EMA quality-by-design expectations for laminate qualification are extending new substrate approval timelines by 12-18 months.
- High-speed print registration:Form-fill-seal line speeds above 600 strokes per minute demand sub-millimeter registration tolerances that strain legacy rotogravure assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cold Form Blister Packaging Market |
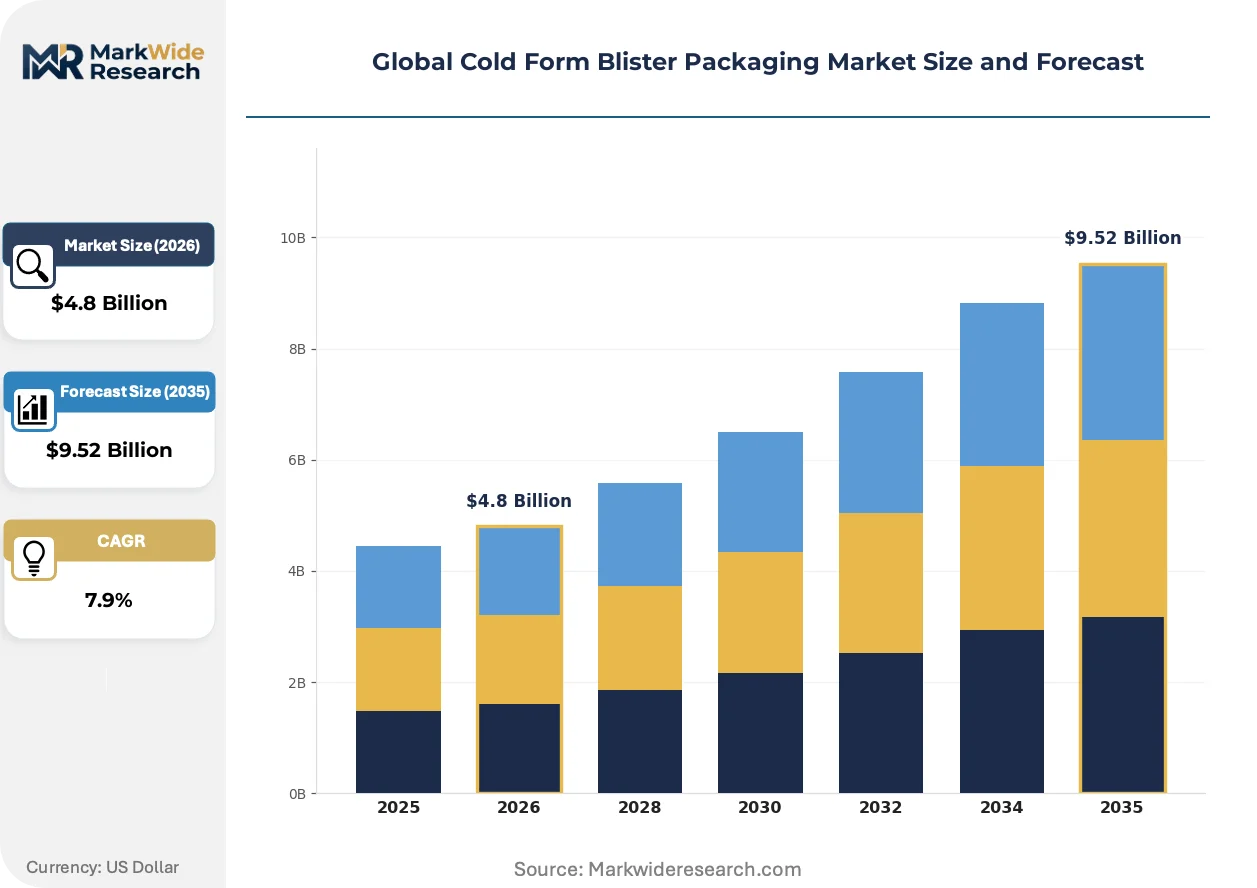
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.52 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cold Form Blister, PVC Cold Form Blister, Alloy Cold Form Blister, Composite Cold Form Blister Application: Pharmaceuticals, Nutraceuticals, Electronics, Personal Care, Food & Beverage End User: Generic Drug Manufacturers, Branded Drug Producers, Contract Packaging Providers, Supplement Makers Packaging Type: Unit Dose, Multi Dose, Strip Packs, Blister Cards, Tray Packs |
| Companies Covered | WINPAK LTD., ACG, Amcor plc, SteriPack Group, Bilcare Limited, Constantia Flexibles, Klöckner Pentaplast, Tekni-Plex, Inc., Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cold Form Blister Packaging Market Strategic Shifts & Innovations
Converters are reengineering laminate architectures and qualification protocols to satisfy divergent regulatory timelines across North American, European, and Asian pharmaceutical approval pathways.
Radiation-cured adhesive systems are supplanting solvent-based lamination in domestic manufacturing facilities. Pharmaceutical packagers in the US Midwest are piloting electron-beam curing lines to preempt EPA enforcement actions on volatile organic compound emissions. This transition is compressing the viable supplier base to converters with capital reserves for beam-hardening equipment.
EU MDR traceability mandates are forcing serialization hardware integration at the form-fill-seal line level. Contract packagers in Germany and Switzerland are retrofitting cold form blister equipment with aggregation software to satisfy unique device identifier requirements. High-value effervescent and hygroscopic tablet categories face the steepest compliance cost absorption.
Buyer concentration among Indian CDMOs is compressing supplier switching cycles. Mumbai-based generic houses are consolidating annual laminate procurement into single-source frameworks with qualification exclusivity clauses. This pattern is most visible in strip-pack channels where serialization integration and regulatory documentation bundling command pricing premiums over standard blister card configurations.
Global Cold Form Blister Packaging Market Segmentation
Cold form blister packaging segments diverge sharply by barrier performance requirements and regulatory qualification intensity. Product type and application selections determine laminate architecture, while end user and packaging format choices shape procurement scale and serialization complexity.
Product Type:
EMA and FDA stability guidelines enforce distinct barrier documentation standards across substrate categories, with aluminum-based constructions facing the most stringent moisture vapor transmission rate validation protocols.
- Aluminum Cold Form Blister:Absolute barrier construction using aluminum foil paired with polyamide or PVC films delivers near-zero moisture vapor transmission rates. Indian CDMOs and domestic generic houses in Mumbai and Hyderabad anchor procurement volumes for regulated export markets to the US and EU, with REACH substance restrictions on adhesive constituents locking in qualified suppliers through requalification cycles.
- Composite Cold Form Blister:Multi-layer coextrusion architectures tailor barrier properties through polymer engineering without full aluminum substitution. Temperature-sensitive biologics and next-generation APIs in German and Swiss contract packaging channels are expanding adoption fastest, as formulators seek lighter-weight alternatives that retain tropical climate distribution stability.
- PVC Cold Form Blister:Polyamide film alternatives face technical barriers in deep-draw formability for high-cavity count configurations.
- Alloy Cold Form Blister:Hybrid metal-polymer constructions serve niche applications requiring intermediate barrier performance at reduced material cost.
Established volume favors aluminum cold form blisters; emerging adoption favors composite cold form blisters.
Application:
Cost tier stratification separates premium pharmaceutical qualification from standard nutraceutical and electronics packaging, with serialization mandates concentrating margin pools in regulated drug channels.
- Pharmaceuticals:Primary containment for hygroscopic tablets, effervescent formulations, and temperature-sensitive APIs demands extended shelf stability documentation. EU MDR traceability requirements and FDA container-closure system guidelines impose the steepest compliance cost absorption, particularly for high-value effervescent categories in German and Swiss aggregation-retrofitted lines.
- Nutraceuticals:Supplement and functional food applications require moisture protection without full pharmaceutical-grade qualification. Strip-pack channels with serialization integration command pricing premiums over standard blister cards in Indian contract packaging frameworks.
- Electronics:Static-sensitive component protection drives demand for conductive laminate variants.
- Personal Care:Unit-dose cosmetic and hygiene applications favor shallow-draw cavity configurations.
- Food & Beverage:Oxygen and moisture barrier requirements for sensitive consumables remain limited by aluminum cost structures.
Pharmaceuticals concentrate procurement scale; nutraceuticals expand most quickly into serialization-integrated formats.
End User:
Customer type determines qualification timeline intensity, with generic drug manufacturers consolidating procurement through single-source frameworks while branded producers retain multi-supplier redundancy.
- Generic Drug Manufacturers:Indian CDMOs and domestic generic houses are scaling cold form strip-pack output for regulated US and EU export markets, bundling annual laminate procurement into qualification exclusivity clauses that compress supplier switching cycles.
- Contract Packaging Providers:Central European CDMOs in Germany and Switzerland retrofit form-fill-seal lines with aggregation software to satisfy EU MDR unique device identifier requirements, positioning strip-pack channels for premium pricing on short-run, trackable configurations.
- Branded Drug Producers:Multinational pharmaceutical companies maintain qualified supplier redundancy across geographic regions.
- Supplement Makers:Nutraceutical brands prioritize cost efficiency over pharmaceutical-grade barrier documentation.
Generic drug manufacturers concentrate volume commitment; contract packaging providers gain share fastest through serialization-integrated service expansion.
Packaging Type:
Supply concentration in Indian and Central European contract packaging channels favors strip-pack and unit-dose formats with integrated serialization, while multi-dose configurations serve cost-sensitive domestic markets.
- Strip Packs:Continuous roll-fed configurations enable high-speed form-fill-seal operation with embedded track-and-trace capability. Mumbai-based generic houses and German contract packagers are retrofitting equipment with aggregation software, with EU MDR mandates forcing hardware integration at the line level and commanding pricing premiums over standard blister cards.
- Unit Dose:Individual cavity isolation delivers maximum barrier integrity for hygroscopic and effervescent tablets. Sub-Saharan African and Southeast Asian tropical climate distribution corridors depend on aluminum cold form construction for shelf-stable pharmaceutical supply chains.
- Multi Dose:Shared cavity designs reduce per-unit material cost for stable formulations.
- Blister Cards:Standard push-through configurations dominate mature generic markets.
- Tray Packs:Deep-draw formats serve high-volume solid dose presentations.
Unit dose retains volume leadership in barrier-critical applications; strip packs represent the steepest expansion trajectory through serialization-mandated retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Mumbai and Jawaharlal Nehru Port Trust anchor pharmaceutical export corridors linking Indian generic manufacturers to regulated US and EU markets, while Rotterdam's container terminals distribute cold form laminates across Central European contract packaging networks.
United States
Pharmaceutical contract packagers in the Midwest are retrofitting electron-beam curing lines to preempt EPA enforcement on volatile organic compound emissions from solvent-based lamination. FDA container-closure system guidelines for aluminum-barrier packaging are tightening material qualification protocols. Chicago and Minneapolis industrial corridors concentrate domestic converter capacity serving branded drug producers.
Germany
Central European CDMOs are consolidating procurement volumes around REACH-compliant aluminum-barrier laminates for moisture-sensitive generics. ECHA substance restrictions on adhesive constituents are accelerating substrate requalification cycles that favor established suppliers. The Rhine-Ruhr and Bavarian packaging clusters retrofit form-fill-seal lines with EU MDR aggregation software.
India
Mumbai-based generic houses and Hyderabad CDMOs are scaling cold form strip-pack output for regulated US and EU export markets under PLI scheme incentives. CDSCO stability requirements and DGFT pharmaceutical export frameworks are bundling procurement into single-source qualification exclusivity clauses. The Mumbai-Pune and Hyderabad-Bengaluru industrial corridors dominate laminate demand.
Switzerland
High-value effervescent and hygroscopic tablet packagers are absorbing the steepest EU MDR compliance costs through serialization-integrated contract packaging channels. Swissmedic quality-by-design expectations for barrier integrity documentation are extending new substrate approval timelines. Basel and Zurich industrial zones concentrate precision form-fill-seal operations serving temperature-sensitive biologics.
China
Domestic pharmaceutical packaging converters are navigating NMPA stability guidelines while expanding composite cold form blister capacity for temperature-sensitive APIs. MEE environmental monitoring of lamination emissions is pressuring aqueous adhesive adoption. The Yangtze River Delta and Pearl River Delta manufacturing basins supply both domestic generic houses and export-oriented CDMOs.
Global Cold Form Blister Packaging Market Key Industry Players
Concentration sits with integrated film-laminate specialists and aluminum substrate converters serving pharmaceutical qualification channels. The supplier base stratifies between multinational converters with capital reserves for radiation-cured process equipment and regional specialists embedded in single-source procurement frameworks. Three archetypes dominate: integrated packaging conglomerates with pharmaceutical-grade certification depth, aluminum foil specialists with tropical climate distribution expertise, and contract packaging service providers with serialization-integrated line capabilities. Competitive moves center on substrate requalification cycle capture under REACH and FDA stability guidelines, plus electron-beam curing line investments to preempt EPA enforcement actions.
Among integrated packaging conglomerates, Amcor plc and Constantia Flexibles exemplify the scale-driven archetype with broad pharmaceutical certification portfolios. ACG occupies a specialist position within aluminum cold form substrate supply chains serving Indian and African generic markets. These three anchors represent divergent competitive vectors: integrated film-laminate capabilities, advanced print-registration technology on high-speed lines, and deep specialization in aluminum-barrier laminates for tropical climate distribution.
| Leading Market Players |
|---|
| WINPAK LTD. |
| ACG |
| Amcor plc |
| SteriPack Group |
| Bilcare Limited |
| Constantia Flexibles |
| Klöckner Pentaplast |
| Tekni-Plex, Inc. |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
Twenty-four to thirty-six month substrate requalification timelines under REACH and FDA stability guidelines concentrate pricing power with incumbent laminate converters who have already absorbed compliance costs, while Indian CDMOs leverage single-source procurement frameworks to compress supplier margins on annual volume commitments.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and electronics-economy levels separates qualification-intensive aluminum cold form laminates from composite alternatives and commodity PVC constructions. Price differentiation rests on FDA container-closure certification depth and REACH adhesive substance compliance, with generic drug manufacturers in Mumbai and Hyderabad exhibiting highest price sensitivity due to PLI scheme margin pressures. Cost compression in standard-grade laminates is intensifying as radiation-cured process investments elevate fixed-cost absorption thresholds for domestic converters.
Supply Chain Analysis
Primary aluminum ingot sourcing from Guinea-Bissau bauxite corridors and Russian smelter output creates chokepoint exposure for laminate converters serving European pharmaceutical markets. Raw material dependencies span aluminum foil rolling capacity in Germany and China, polyamide film extrusion in Japan and South Korea, and adhesive resin production in the US Gulf Coast. Single-source vulnerability concentrates in qualified substrate suppliers holding simultaneous FDA and EMA documentation packages. Distribution runs through Rotterdam container terminals for Central European CDMOs and Jawaharlal Nehru Port Trust corridors for Indian generic export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron-beam curing equipment and simultaneous multi-regulatory qualification capabilities have become the binding constraints that separate viable suppliers from margin-compressed commodity converters, with capital reserves now determining competitive survival more than technical differentiation.
For Market Incumbents: Compound barrier integrity documentation advantages by locking in requalification cycle capture under evolving EMA quality-by-design expectations, while accelerating backward integration into radiation-cured adhesive resin supply to preempt EPA enforcement exposure on solvent-based lamination emissions. For New Entrants and Emerging Players: Serialization-integrated contract packaging service layers in German and Swiss CDMO channels remain under-served by incumbent laminate specialists focused on substrate supply rather than line-level aggregation software bundling, creating white-space entry through EU MDR compliance-as-a-service offerings targeting high-value effervescent tablet packagers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electron-beam curing line deployments and multi-jurisdiction qualification maintenance, favoring acquisition targets with established FDA-EMA dual certification portfolios and unencumbered balance sheets capable of absorbing beam-hardening equipment capex cycles. The signal to monitor is EMA publication of revised barrier integrity documentation guidelines that would trigger substrate requalification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Electron-Beam Curing Line Deployment | EPA VOC enforcement exposure in US Midwest pharmaceutical corridors accelerates aqueous and radiation-cured process substitution. |
| REACH-Compliant Adhesive Reformulation | ECHA substance restrictions on lamination constituents lock in qualified suppliers through extended requalification cycles. |
| Serialization Hardware Integration | EU MDR unique device identifier mandates force aggregation software retrofit at German and Swiss form-fill-seal lines. |
| Single-Source Procurement Frameworks | Mumbai-based generic houses bundle annual laminate volumes with qualification exclusivity clauses that compress supplier switching. |
| Composite Multi-Layer Coextrusion Capacity | Temperature-sensitive biologics in Basel and Zurich packaging zones expand adoption of tailored barrier polymer engineering. |
Research Approach
Desk research of FDA container-closure guidance documents, EMA quality-by-design reflection papers, and REACH substance restriction annexes preceded structured interviews with pharmaceutical packaging procurement managers, laminate converter technical directors, CDMO operations executives, and regulatory affairs specialists across Indian, German, Swiss, and US markets. Secondary validation drew from EPA enforcement action databases, CDSCO pharmaceutical export notifications, and customs trade flow records for aluminum foil and polyamide film categories. Bottom-up volume estimates from individual converter capacity declarations were triangulated against top-down pharmaceutical packaging demand projections.
Variance decomposition across product type, application tier, end-user category, and packaging format dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate blending weighted by current procurement volume shares. Industry-specific forecast inputs incorporated REACH requalification cycle frequency assumptions and PLI scheme incentive absorption rates for Indian domestic generic houses.
Forecasts assume regulatory continuity in FDA stability guideline enforcement, EMA barrier integrity documentation expectations, and REACH substance restriction implementation timelines; material policy shifts in any of these regimes would require re-modeling. Practitioners should keep alternative scenarios live as EMA quality-by-design publication schedules and EPA VOC enforcement prioritization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
North America Blister Packaging Market