
 Global Biodegradable Pharmaceutical Packaging Market | 2026-2036
Global Biodegradable Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biodegradable Pharmaceutical Packaging Market Analysis
Premium certified compostable pharmaceutical packaging is decoupling from commodity-grade biodegradable alternatives on performance validation and traceability standards. Gerresheimer AG leverages its glass-to-biopolymer hybrid expertise to anchor high-barrier injectable formats. Amcor PLC sustains multi-continental production scale across oral solid dose applications. DS Smith PLC differentiates through fiber-based innovation in secondary pharmaceutical cartons.
Biodegradable pharmaceutical packaging encompasses primary and secondary containment systems engineered from polylactic acid, polyhydroxyalkanoates, starch blends, or cellulose derivatives, designed to decompose under industrial composting or marine conditions within specified timeframes while maintaining USP moisture vapor transmission and light protection standards. PLA and PHA material grades command widening formulation attention as barrier coating technologies mature for oral dosage blister packs. Cellulose-derived substrates occupy expanding share in cold-chain secondary packaging where moisture sensitivity limits starch adoption. Blister packs and containers represent the most technically contested segments as pharmaceutical companies demand child-resistance certification parity with conventional polymers.
FDA bioequivalence documentation requirements and EMA packaging material guidelines jointly determine acceptable degradation timelines for primary drug-contact layers. REACH substance restrictions and EU Green Deal circularity mandates are forcing reformulation of additive packages in European-sourced films. Stakeholders must monitor evolving compostability certification divergence between ASTM D6400 and EN 13432 testing protocols as regional procurement specifications harden.
Market Dynamics
The biodegradable pharmaceutical packaging sector is experiencing acute material substitution pressure as REACH substance restrictions and EU Green Deal circularity mandates force rapid transitions away from petroleum-derived films, creating supply bottlenecks for certified compostable alternatives.
Growth Catalysts
- REACH Compliance Deadlines:European chemical substance restrictions are compelling pharmaceutical manufacturers to reformulate additive packages in primary packaging films ahead of enforcement windows.
- Starch-Based Material Innovation:Contract packagers across Germany's pharmaceutical corridor are scaling procurement of modified starch blends for secondary containment systems.
- Barrier Coating Maturation:Advances in polylactic acid and polyhydroxyalkanoate vapor deposition technologies are unlocking moisture protection parity with conventional polymers for oral solid dose formats.
Market Restraints
- Industrial Composting Infrastructure Gaps:Limited availability of ASTM D6400 and EN 13432 certified composting facilities in North American and Asian markets restricts end-of-life value realization for biodegradable packaging.
- PHA Feedstock Volatility:Agricultural input price fluctuations for sugarcane and corn-derived fermentation feedstocks compress margin stability for biopolymer producers.
- Child-Resistance Certification Parity:USP and ISO 8317 testing protocols for biodegradable blister packs lag conventional polymer validation timelines by 18-24 months.
Strategic Opportunities
- Cold-Chain Secondary Packaging:Cellulose-derived substrates with integrated phase-change materials are penetrating temperature-sensitive biologics distribution in Switzerland and the Netherlands.
- Marine Biodegradability Certification:Emerging ASTM D6691 and D6692 testing standards for ocean-degradable films open specialized oncology and emergency medicine kit applications.
- Digital Product Passports:EU Green Deal-linked traceability requirements are creating integrated packaging-blockchain service bundles for batch-level compostability verification.
Industry Challenges
- Compostability Certification Divergence:Misalignment between ASTM D6400 industrial composting timelines and EN 13432 home composting standards forces dual-testing expenditure for multi-continental suppliers.
- Barrier-Formulation Talent Scarcity:Cross-disciplinary expertise spanning polymer chemistry, pharmaceutical stability science, and regulatory affairs commands premium compensation in Germany and Massachusetts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biodegradable Pharmaceutical Packaging Market |
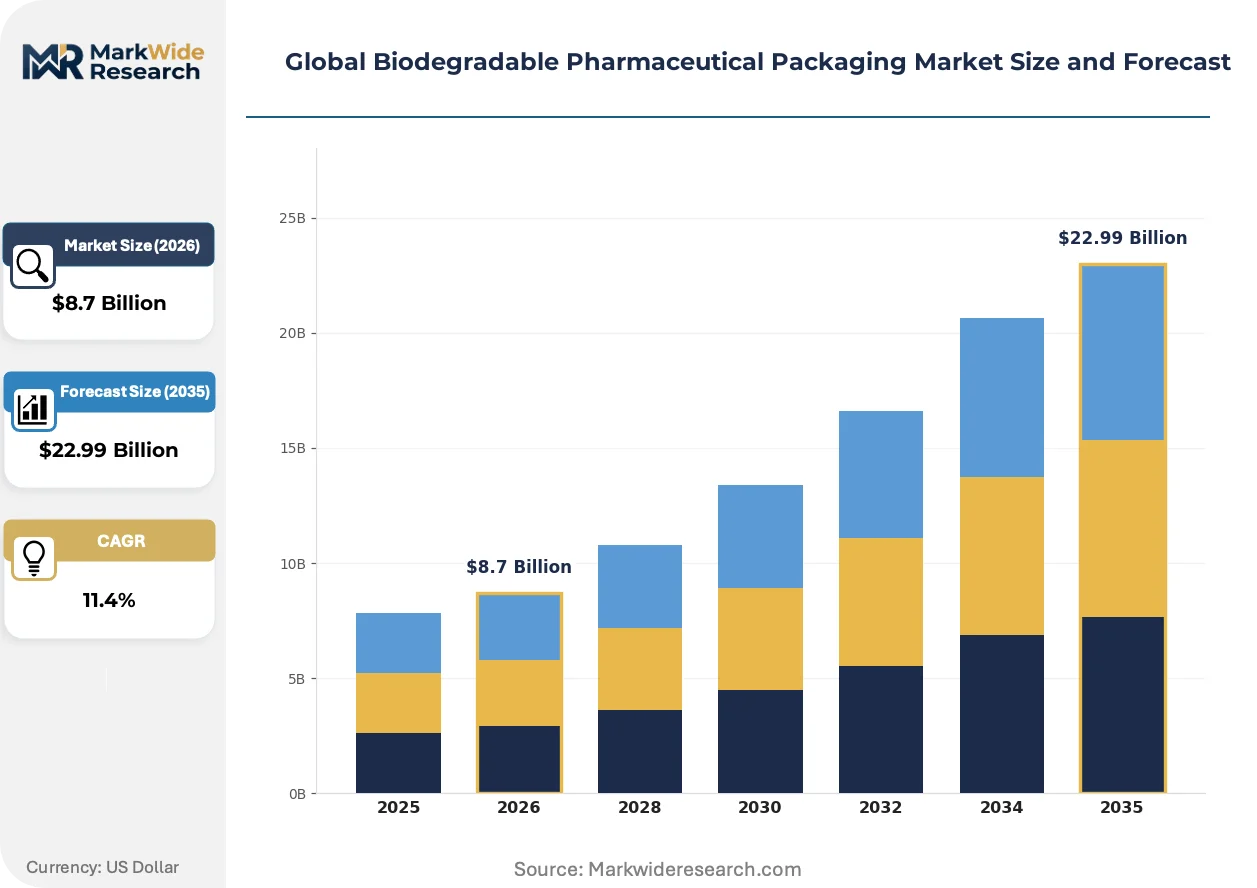
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Sachets, Containers, Labels Material: PLA, PHA, Starch Blends, Cellulose End User: Pharmaceutical Companies, Contract Packagers, Distributors, Hospitals Application: Oral, Injectable, Transdermal, Topical |
| Companies Covered | Gerresheimer AG, Berry Global, DS Smith PLC, Amcor PLC, Smurfit Kappa, Schott AG, WestRock, AptarGroup, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biodegradable Pharmaceutical Packaging Market Emerging Trajectories
Active barrier coating technologies and distributed manufacturing architectures are compressing the traditional centralized production model for pharmaceutical packaging, while regulatory fragmentation accelerates regional specialization.
Multi-layer co-extrusion of polylactic acid with bio-derived ethylene vinyl alcohol is decentralizing high-barrier film production from petrochemical hubs toward regional compounding facilities. Mid-sized contract manufacturers in the US Midwest and northern Italy are installing pilot-scale PLA/EVOH lines to serve local pharmaceutical clusters. This geographic redistribution is shortening supply chains for oral dosage blister packs while reducing carbon intensity from transoceanic film logistics.
EMA packaging material guidelines and FDA bioequivalence documentation requirements are tightening acceptable degradation timelines for primary drug-contact layers. Pharmaceutical sponsors must now submit accelerated stability data on biodegradable alternatives concurrent with conventional polymer controls. European generic manufacturers are responding by front-loading formulation development partnerships with certified compostable film suppliers.
Hospital and retail pharmacy procurement committees are elevating compostability certification to tier-one supplier qualification criteria alongside USP moisture vapor transmission rates. Group purchasing organizations in France and Scandinavia are bundling biodegradable packaging specifications into multi-year pharmaceutical distribution contracts. This specification-driven purchasing is most pronounced in oncology and parenteral nutrition segments where patient-facing sustainability messaging carries brand differentiation value.
Global Biodegradable Pharmaceutical Packaging Market Segmentation
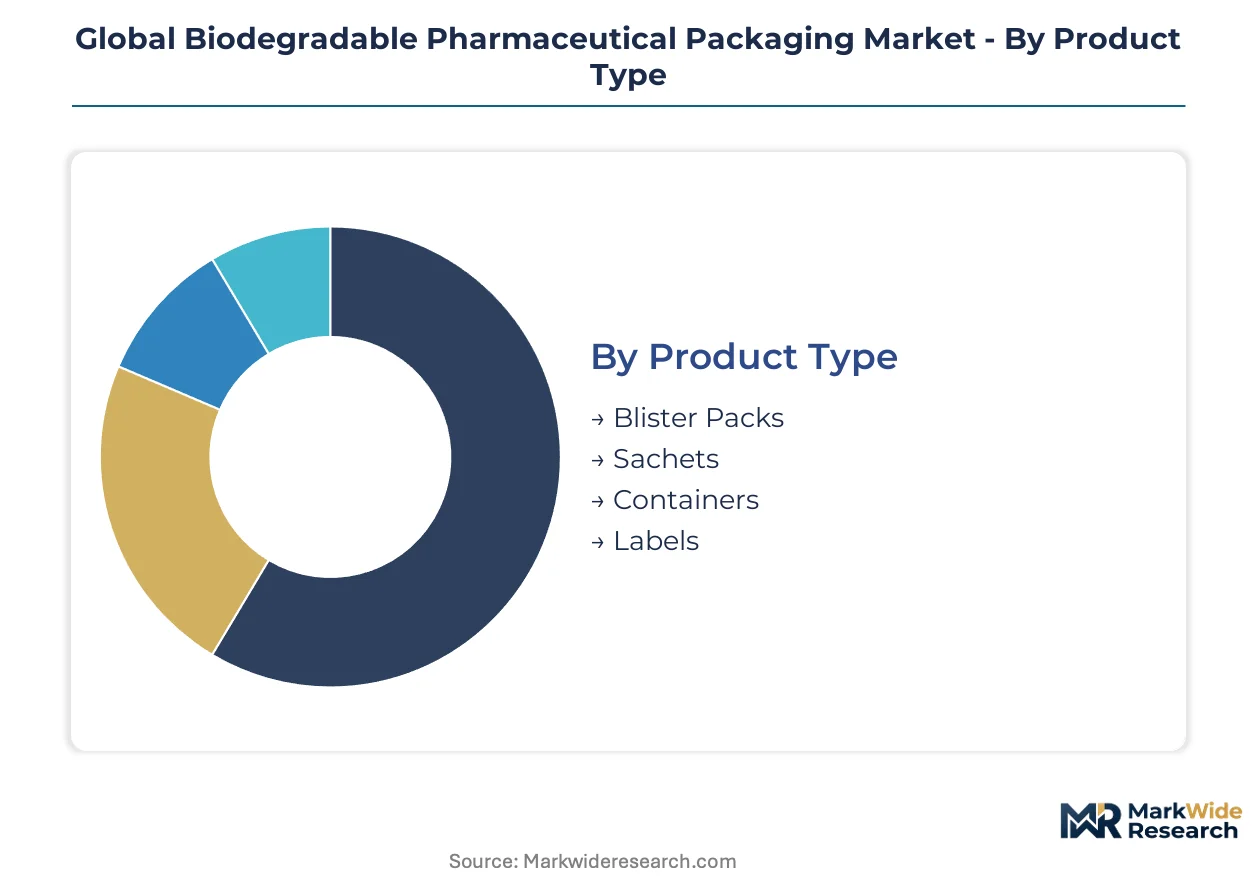
Segmentation in biodegradable pharmaceutical packaging reveals divergent certification burdens across product formats and material grades. USP moisture vapor transmission standards and ASTM D6400 compostability timelines create tiered compliance costs that reshape procurement economics for each segment cluster.
Product Type:
Child-resistance certification under ISO 8317 and USP <661> permeability testing impose asymmetric validation timelines across primary containment formats, with blister packs facing the longest approval queues.
- Blister Packs:Multi-cavity thermoformed configurations from PLA or starch blends require vapor-deposited barrier coatings to achieve moisture protection parity with PVC alternatives. Germany's contract packaging corridor concentrates demand for oral solid dose formats as EMA packaging material guidelines tighten degradation timeline documentation.
- Containers:Wide-mouth and narrow-neck designs from PHA or cellulose derivatives serve powder and liquid formulations where thread integrity and torque resistance must match HDPE performance. Swissmedic-registered manufacturers in Basel and Zurich are qualifying bio-derived containers for oncology APIs requiring light and oxygen exclusion.
- Sachets:Single-dose flexible pouches from cellulose films penetrate emerging markets where cold-chain infrastructure is limited.
- Labels:Pressure-sensitive adhesives on bio-derived facestocks face FDA bioequivalence scrutiny for transdermal patch backing applications.
Leading the category by volume: Blister Packs. Growing fastest: Containers.
Material:
Feedstock origin and fermentation scale determine cost tier positioning, with agricultural commodity price exposure creating margin volatility that separates premium-certified grades from commodity alternatives.
- PLA:Polylactic acid from corn or sugarcane fermentation dominates oral dosage applications through multi-layer co-extrusion with bio-derived EVOH barrier layers. Northern Italian compounding facilities are installing regional PLA lines to serve local pharmaceutical clusters, shortening supply chains while reducing transoceanic logistics emissions.
- PHA:Polyhydroxyalkanoates produced via bacterial fermentation of waste feedstocks command premium positioning for marine biodegradability certification under emerging ASTM D6691 protocols. Netherlands-based biopolymer producers are scaling PHA capacity for oncology kit applications where ocean-degradable disposal is specified.
- Starch Blends:Modified potato and corn starch formulations penetrate secondary cartons and cushioning where moisture sensitivity is less critical.
- Cellulose:Regenerated and derivatized wood pulp substrates anchor cold-chain secondary packaging with integrated phase-change materials.
Highest volume share: PLA. Steepest expansion trajectory: PHA.
End User:
Procurement authority and specification-writing power concentrate differently across the value chain, with group purchasing organizations and direct manufacturer R&D budgets driving divergent material qualification priorities.
- Pharmaceutical Companies:Brand-name and generic drug sponsors control primary packaging specification with FDA bioequivalence documentation requirements forcing concurrent stability testing of biodegradable alternatives against conventional polymer controls. European generic manufacturers are front-loading formulation development partnerships with certified compostable film suppliers.
- Contract Packagers:Third-party manufacturing and packaging service providers in Germany's pharmaceutical corridor are scaling starch-based procurement for secondary containment as REACH compliance deadlines accelerate material transitions.
- Distributors:Wholesalers and logistics operators influence tertiary packaging specifications for pallet stabilization and shipment integrity.
- Hospitals:French and Scandinavian pharmacy procurement committees are elevating compostability certification to tier-one supplier qualification criteria alongside USP performance standards.
Dominant procurement volume: Pharmaceutical Companies. Gaining specification authority fastest: Contract Packagers.
Application:
Route of administration dictates barrier performance thresholds and regulatory scrutiny intensity, with parenteral formats facing the most stringent extractables and leachables testing protocols.
- Oral:Tablets, capsules, and lozenges in blister packs and bottles constitute the largest addressable volume, with moisture vapor transmission rates under USP <671> determining shelf-life equivalence. Barrier coating maturation for PLA and PHA substrates is unlocking moisture protection parity for oral solid dose formats.
- Injectable:Vials, pre-filled syringes, and ampoules demand highest-barrier performance for biologics and vaccines, with glass-to-biopolymer hybrid expertise anchoring high-barrier formats. Gerresheimer AG leverages this capability for temperature-sensitive distribution.
- Transdermal:Patches and films require adhesive and backing layer compatibility with skin contact regulations.
- Topical:Creams, ointments, and gels in jars and tubes face less stringent barrier requirements but demand compatibility with diverse formulation chemistries.
Largest volume segment: Oral. Climbing the fastest: Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical corridor stretching from Frankfurt to Basel anchors procurement scale for certified compostable packaging, with contract packagers there driving starch-based material adoption ahead of EU Green Deal enforcement timelines.
United States
FDA bioequivalence documentation requirements are forcing concurrent stability testing of biodegradable alternatives against conventional polymer controls. The IRA's domestic manufacturing incentives are accelerating regional compounding capacity in the Midwest. Massachusetts-based pharmaceutical sponsors are front-loading formulation development partnerships with certified compostable film suppliers.
Germany
REACH substance restrictions and EMA packaging material guidelines are compelling rapid transitions away from petroleum-derived films. The EU Green Deal circularity mandates are forcing reformulation of additive packages in primary packaging films. Contract packagers across the Rhine-Main pharmaceutical cluster are scaling procurement of modified starch blends for secondary containment systems.
Switzerland
Swissmedic-registered manufacturers in Basel and Zurich are qualifying bio-derived containers for oncology APIs requiring light and oxygen exclusion. The country's pharmaceutical regulator maintains stringent extractables and leachables testing protocols for parenteral formats. Cold-chain secondary packaging with integrated phase-change materials is penetrating temperature-sensitive biologics distribution from Geneva to Zurich.
Netherlands
Netherlands-based biopolymer producers are scaling PHA capacity for oncology kit applications where ocean-degradable disposal is specified. The country's national pharmaceutical regulator aligns with EMA guidelines while supporting marine biodegradability certification under emerging ASTM D6691 protocols. Rotterdam's logistics hub is facilitating distribution of cellulose-derived substrates across Northern European pharmaceutical markets.
India
CDSCO packaging material regulations are tightening acceptable degradation timelines for primary drug-contact layers. The PLI scheme for pharmaceutical manufacturing is attracting investment in regional biodegradable packaging conversion capacity. Contract manufacturers in Maharashtra and Gujarat are qualifying PLA blister packs for oral solid dose export markets.
Global Biodegradable Pharmaceutical Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification grade and barrier performance tiers, with USP moisture vapor transmission parity commanding substantial price premiums. The vendor base separates into three strategic archetypes: glass-to-biopolymer hybrid specialists, multi-continental film producers, and fiber-based secondary packaging innovators. Dominant competitive moves include backward integration into PLA compounding capacity and strategic partnerships for marine biodegradability certification.
Among European-headquartered players, Gerresheimer AG and DS Smith PLC exemplify divergent archetype positioning. Gerresheimer AG represents the glass-to-biopolymer hybrid specialist tier, leveraging legacy pharmaceutical containment expertise toward high-barrier injectable formats. DS Smith PLC occupies the fiber-based innovation position, differentiating through secondary pharmaceutical carton engineering. Amcor PLC anchors the multi-continental production scale archetype, sustaining manufacturing footprint across oral solid dose applications. These three entities collectively illustrate how certification depth and geographic coverage determine margin capture in biodegradable pharmaceutical packaging.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Berry Global |
| DS Smith PLC |
| Amcor PLC |
| Smurfit Kappa |
| Schott AG |
| WestRock |
| AptarGroup |
| Mondi Group |
| Others |
Supply Flow & Price Mechanics
Barrier-formulation chemists in Germany's Rhine-Main corridor command compensation premiums that widen spreads between ASTM D6400-certified films and commodity starch alternatives. Labor-cost differentials between Massachusetts polymer scientists and northern Italian compounding technicians feed directly into three-tier pricing stratification across premium, standard, and economy certification grades.
Pricing Analysis
USP moisture vapor transmission parity anchors value-based pricing for high-barrier injectable formats. Three-tier pricing structure across premium, standard, and economy levels separates PHA marine-certified films from PLA industrial-compostable grades from unmodified starch blends. Cost compression in commodity starch tiers intensifies as agricultural input volatility transfers downstream. Contract packagers in Germany's pharmaceutical corridor exhibit lowest price sensitivity; emerging market distributors face acute budget constraints.
Supply Chain Analysis
Transoceanic freight premiums for PLA resin shipments from Thailand and China to European compounding facilities are compressing margins for non-integrated converters. Feedstock supply concentrates in the United States corn belt, Brazilian sugarcane regions, and Thai cassava plantations. PHA fermentation draws from waste glycerol, sugarcane bagasse, and municipal organic streams. Single-source vulnerability in bio-derived EVOH barrier coatings threatens multi-layer film producers. Distribution runs through regional pharmaceutical clusters rather than centralized petrochemical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable pharmaceutical packaging sits in active material-transition phase as polylactic acid and polyhydroxyalkanoate barrier coatings displace PVC and PVDC legacy films in oral solid dose applications.
For Market Incumbents: Hedge against PHA feedstock volatility through backward integration into agricultural supply contracts or fermentation capacity partnerships. Anchor market position by accelerating child-resistance certification pipelines for biodegradable blister packs before ISO 8317 protocol updates favor conventional polymers. Prioritize EMA packaging material guideline compliance ahead of REACH enforcement windows.
For New Entrants and Emerging Players: Marine biodegradability certification under ASTM D6691 protocols offers technology-first positioning in oncology kit and emergency medicine applications where ocean-degradable disposal commands specification priority. Target Swissmedic-registered manufacturers in Basel seeking light-exclusion containers for API containment. Lead with integrated digital product passport offerings that bundle batch-level compostability verification.
For Investors and Strategic Acquirers: Re-rating potential sits with glass-to-biopolymer hybrid specialists given FDA bioequivalence documentation requirements forcing concurrent stability testing partnerships. Long-term viability favors archetypes with captive barrier-coating R&D and multi-continental production footprints. Watch for EMA packaging material guideline revisions as inflection signal for accelerated material substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PLA Compounding | Corn-belt fermentation capacity secures feedstock cost parity against petrochemical films. |
| Marine Biodegradability Certification | ASTM D6691 qualification unlocks oncology kit specifications in Netherlands and Switzerland. |
| Digital Product Passport Integration | EU Green Deal traceability mandates create blockchain-verified compostability service bundles. |
| Cold-Chain Secondary Packaging Expansion | Cellulose-derived phase-change substrates penetrate Swissmedic biologics distribution networks. |
| Regional Compounding Facility Buildout | Northern Italian PLA lines shorten supply chains for EMA-compliant oral dosage formats. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pharmaceutical packaging engineers, EMA regulatory affairs leads, contract packaging procurement directors, and polymer chemistry R&D heads combined with FDA 510(k) submissions, REACH registration dossiers, and EU customs import records. Bottom-up facility capacity tallies and top-down pharmaceutical production forecasts were triangulated against certification database entries.
Data-stream reconciliation across material grade, product format, end-user archetype, application route, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume build-ups calibrated to pharmaceutical production indices and packaging intensity ratios. Forecast inputs included REACH compliance deadline schedules, ASTM D6400 certification pipeline counts, and PLA/PHA capacity expansion announcements.
Several conditions sit outside the modeled scope, including unannounced regulatory guideline revisions, breakthrough barrier-coating technologies, and macroeconomic disruptions to agricultural feedstock markets. Forecasts reflect documented assumptions about certification timeline continuity and composting infrastructure buildout rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market