
 Blister Packaging Equipment Market | 2026-2036
Blister Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Blister Packaging Equipment Market Analysis
Market Context
Pharmaceutical packaging is broadening its equipment footprint as oral solid dose production migrates toward high-speed automated lines. Uhlmann Packaging Group leverages vertical integration across forming, sealing, and cartoning modules to dominate European pharma installations. ACG Worldwide anchors its position in emerging markets through localized service networks and cost-optimized machine platforms. Syntegon Technology differentiates via Industry 4.0-enabled lines with real-time process analytics.
Technical Definition and Segment Structure
Blister packaging equipment forms, fills, and seals product cavities in thermoplastic or cold-form foil webs, operating at speeds from 50 to 1,200 cycles per minute with forming depths up to 12 millimeters for deep-draw pharmaceutical applications. Automatic machines command the largest installed base due to throughput requirements in high-volume pharmaceutical tableting operations, while digital machines with servo-driven forming stations represent the fastest-expanding category as lot-size-one production gains traction. Thermoformed plastic blisters hold mature volume leadership, though cold-formed aluminum segments retain premium margin pools where moisture and light barrier properties justify higher equipment and material costs.
Regulatory Frame and Outlook
FDA serialization mandates under the Drug Supply Chain Security Act and EU MDR traceability requirements compel equipment upgrades with integrated vision inspection and aggregation software. EMA's evolving Annex 1 sterile manufacturing guidelines and EPA emissions standards for solvent-based sealing processes further constrain machine design choices. Stakeholders must weigh total cost of ownership against compliance velocity when selecting between retrofit pathways and greenfield installations.
Market Dynamics
Serialization mandates from FDA and EMA are forcing pharmaceutical manufacturers to retire legacy blister lines and install integrated track-and-trace systems, compressing replacement cycles and reshaping capital allocation priorities across the equipment supply base.
Growth Catalysts
- EU MDR traceability mandates:European pharmaceutical contract manufacturers must deploy vision inspection and aggregation modules on all new blister installations, creating immediate equipment demand.
- Oral solid dose volume expansion:Generic drug producers in India are scaling automated thermoforming capacity to serve export markets under tightened FDA oversight.
- Cold-form aluminum barrier properties:Moisture-sensitive biologics and effervescent formulations require deep-draw aluminum cavities, sustaining premium equipment margins despite higher cycle costs.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for precision forming components compress OEM margins and extend quotation validity periods.
- Sealing solvent emissions compliance:EPA and ECHA constraints on solvent-based heat-sealing processes limit machine design flexibility and increase environmental abatement capex.
- Retrofit pathway viability:Legacy mechanical cam-driven lines lack the electrical architecture to support serialization modules, forcing binary upgrade-or-replace decisions.
Strategic Opportunities
- Underpenetrated biologics packaging:Cell and gene therapy producers in Switzerland and Massachusetts require specialized deep-cold blister formats with validated thermal stability.
- AI-enabled predictive maintenance:Convergence of machine vision and edge computing allows OEMs to offer uptime guarantees as subscription revenue streams.
- India PLI scheme for pharmaceuticals:Domestic production incentives are accelerating greenfield tablet manufacturing facilities with fully automated blister lines.
Industry Challenges
- Validation engineer scarcity:FDA 21 CFR Part 11 compliance documentation requires specialized qualification protocols that outstrip available talent pools in emerging manufacturing clusters.
- Multi-generational system integration:Brownfield sites must synchronize new servo-driven forming stations with existing cartoning and case-packing lines, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blister Packaging Equipment Market |
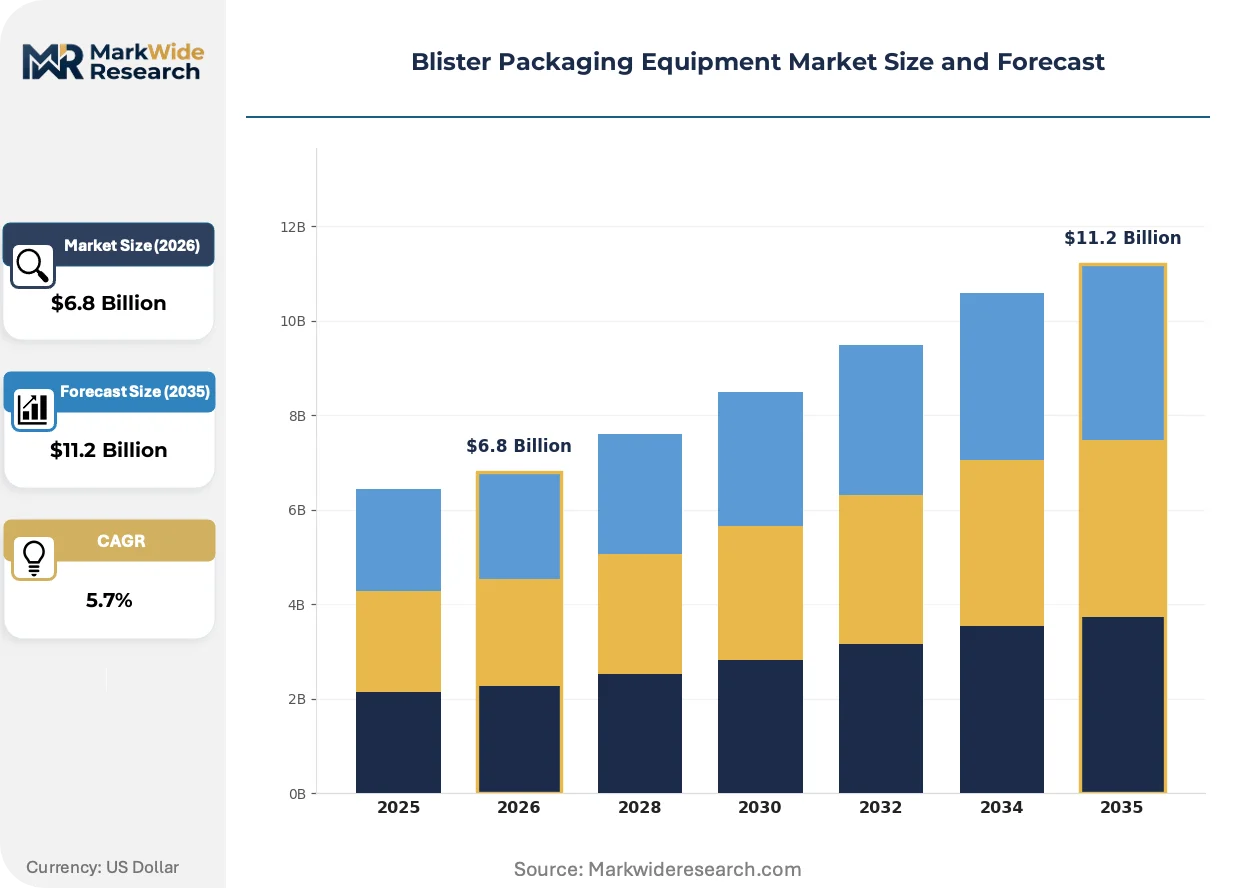
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Machines, Semi-Automatic Machines, Manual Machines, Digital Machines Material: Plastic, Aluminum, Paperboard, Composite End User: Pharmaceuticals, Food & Beverage, Consumer Goods, Electronics Form: Thermoformed, Cold Formed, Blister Packs, Push-Through |
| Companies Covered | Uhlmann Packaging Group, IMA Group, Marchesini Group, Romaco Group, Syntegon Technology, ACG Worldwide, Mediseal, Hoonga, CAM Packaging Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blister Packaging Equipment Market Emerging Trajectories
Equipment architecture is pivoting from mechanical synchronization to digital servo networks, enabling real-time process adjustment and lot-size-one production without tooling changeovers.
Continuous motion thermoforming with independent servo-driven forming stations is expanding into high-volume generic pharmaceutical operations. Indian and Chinese contract manufacturers are adopting these systems to compress changeover downtime between SKUs. The technology is expanding into markets previously served by intermittent-motion machines, compressing the addressable base for mechanical legacy platforms.
EMA Annex 1 sterile manufacturing revisions are tightening environmental monitoring requirements for packaging operations adjacent to cleanrooms. Equipment suppliers must now integrate particle monitoring and gloveless robotic handling modules as standard configurations. Aseptic blister applications in Germany and Ireland are driving demand for isolator-integrated lines with validated decontamination cycles.
After-sales service unbundling is accelerating as pharmaceutical procurement teams separate equipment purchase from maintenance contracts. Third-party service providers in the US and Germany are capturing calibration and spare parts revenue that OEMs previously monopolized. Large generic manufacturers in New Jersey and Bavaria now negotiate multi-vendor service agreements to reduce total cost of ownership.
Blister Packaging Equipment Market Segmentation
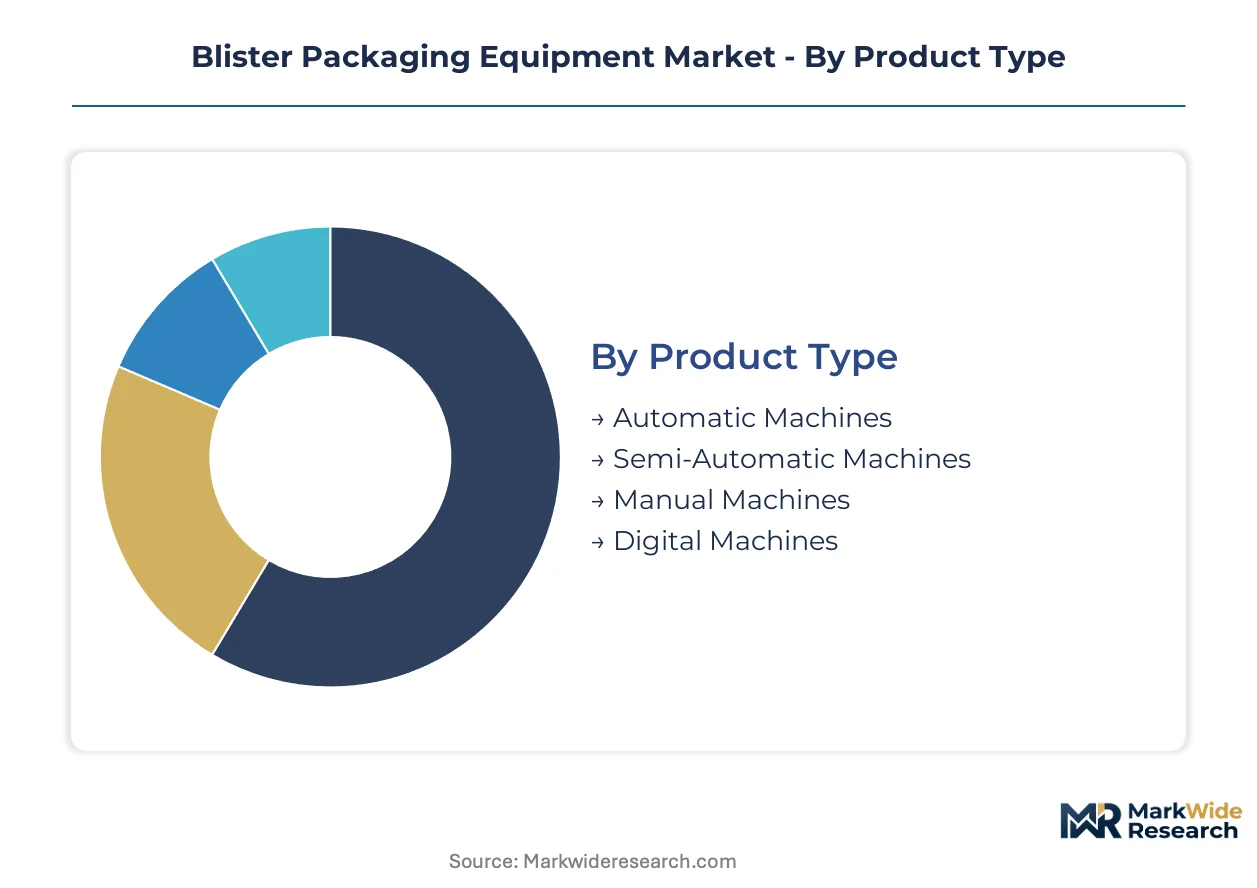
Blister packaging equipment segmentation reveals how capital allocation splits between throughput-driven pharmaceutical installations and flexibility-oriented formats serving smaller batch producers. Equipment choices cascade through material selection, end-use compliance requirements, and forming methodology, each tier carrying distinct margin profiles and technical validation burdens.
Product Type:
Supply concentration tilts toward high-throughput platforms as pharmaceutical contract manufacturers consolidate purchasing around proven OEMs with integrated serialization capabilities.
- Automatic Machines:These systems operate at 600-1,200 cycles per minute with servo-driven forming and sealing stations synchronized to downstream cartoning modules. Indian generic producers in Hyderabad and Ahmedabad are scaling automatic line purchases to meet FDA export compliance, compressing delivery timelines for domestic OEMs.
- Digital Machines:Independent servo networks enable real-time parameter adjustment without mechanical changeovers, supporting lot-size-one production with validated recipe management. Massachusetts cell therapy facilities are piloting digital platforms for deep-cold blister formats with thermal stability tracking.
- Semi-Automatic Machines:Intermediate platforms bridge manual loading with automated sealing for mid-volume nutraceutical operations in California and Ontario.
- Manual Machines:Footprint-constrained systems serve specialty pharmacy compounding and clinical trial packaging in Bavaria and New Jersey.
Automatic machines absorb the bulk of installed capacity; digital machines are expanding most quickly.
Material:
Cost tier stratification separates commodity thermoplastics from barrier-grade aluminum, with composite formats emerging at the premium intersection of performance and sustainability mandates.
- Plastic:PVC, PVDC, and cyclic olefin polymers dominate oral solid dose thermoforming for cost-sensitive generic tablets. German packaging lines process plastic webs at speeds exceeding 800 cycles per minute, though ECHA scrutiny of chlorine-containing films is accelerating material substitution studies.
- Alumin:Cold-form foil provides moisture, oxygen, and light barriers essential for effervescent formulations and moisture-sensitive biologics. Swiss pharmaceutical packaging facilities in Basel prioritize aluminum blister lines for high-value oncology products, sustaining equipment margin premiums despite slower cycle rates.
- Paperboard:Fiber-based backing materials gain traction in European sustainability-focused OTC packaging under EU Green Deal circularity targets.
- Composite:Multi-layer structures combining plastic barrier layers with aluminum lidding serve transdermal patch and inhalation device packaging in North Carolina and Ireland.
Plastic retains volume leadership across installed base; aluminum commands the steepest expansion trajectory in biologics applications.
End User:
Application severity dictates validation intensity, with pharmaceutical installations requiring 21 CFR Part 11 documentation that other sectors bypass entirely.
- Pharmaceuticals:Oral solid dose, sterile injectable, and biologic packaging lines must integrate vision inspection, aggregation, and serialization modules under FDA and EMA mandates. German contract manufacturers in Baden-Württemberg are retiring legacy mechanical lines ahead of EU MDR traceability deadlines.
- Food & Beverage:Modified atmosphere blister formats for portion-controlled snacks and confectionery operate without pharmaceutical-grade validation overhead. Italian equipment suppliers dominate this tier with cost-optimized thermoforming platforms.
- Consumer Goods:Battery, razor, and cosmetic blister packs prioritize seal integrity and retail theft deterrence over process documentation.
- Electronics:ESD-sensitive component packaging requires conductive materials and cleanroom-compatible handling systems in Taiwanese and South Korean manufacturing clusters.
Pharmaceuticals command the dominant share of equipment revenue; food and beverage applications are climbing fastest in absolute unit terms.
Form:
Maturity gradients separate entrenched thermoforming from emerging cold-form architectures, with push-through formats facing substitution pressure from child-resistant alternatives.
- Thermoformed:Heated plastic webs drawn into cavity molds via vacuum or pressure forming constitute the foundational pharmaceutical packaging format. Indian and Chinese contract manufacturers operate thermoformed lines at utilitarian price points, though EMA Annex 1 revisions are forcing environmental monitoring upgrades.
- Cold Formed:Aluminum foil stamped at ambient temperature into deep-draw cavities eliminates moisture permeation pathways. Massachusetts and Switzerland biologics producers are specifying cold-form equipment for cell therapy stability requirements.
- Blister Packs:Standard cavity-lidding configurations serve the majority of tablet and capsule presentations across retail pharmacy channels.
- Push-Through:Foil-lidded formats optimized for elderly patient compliance face regulatory pressure from child-resistant packaging mandates in California and the European Union.
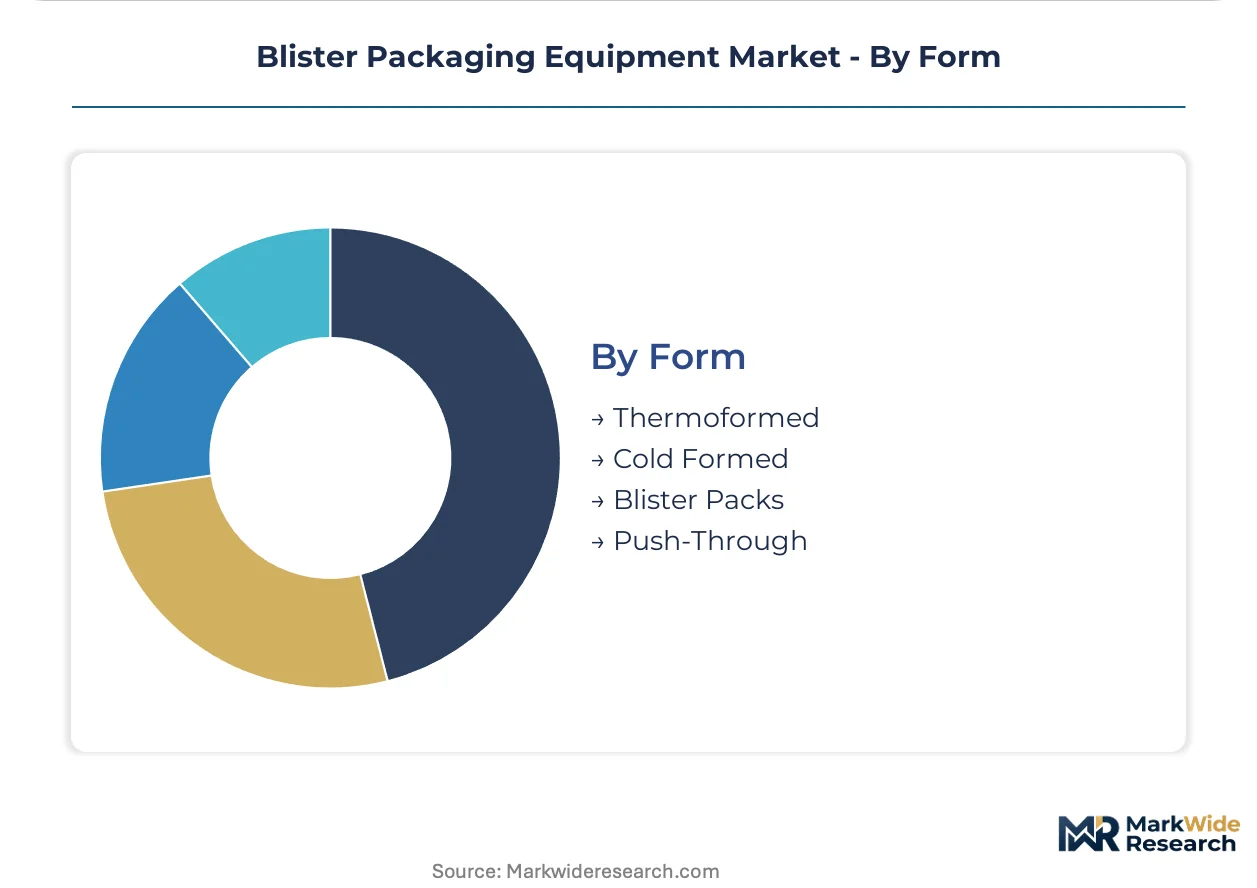
Thermoformed formats retain the largest installed footprint; cold-formed systems are gaining share fastest in high-barrier therapeutic categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Hyderabad and Bavaria concentrate pharmaceutical equipment manufacturing through tax incentives and infrastructure subsidies that accelerate automated line deployment.
Germany
Baden-Württemberg hosts the densest cluster of thermoforming OEMs serving EU MDR compliance deadlines. EMA serialization mandates force contract manufacturers in Stuttgart and Karlsruhe to retire mechanical cam-driven lines before traceability requirements activate. Bavarian packaging facilities in Munich integrate isolator-compatible modules for aseptic blister applications.
United States
FDA Drug Supply Chain Security Act deadlines compress replacement cycles for legacy equipment across New Jersey and Massachusetts pharmaceutical corridors. EPA emissions constraints on solvent-based sealing processes constrain machine design flexibility in Midwest manufacturing zones. Greater Boston cell therapy producers pilot deep-cold blister formats with thermal stability tracking systems.
India
PLI scheme subsidies for domestic pharmaceutical manufacturing accelerate greenfield tablet facilities with fully automated blister lines in Hyderabad and Ahmedabad. CDSCO export compliance requirements drive contract manufacturers toward integrated vision inspection modules. Gujarat packaging clusters adopt continuous-motion thermoforming to compress SKU changeover downtime.
Switzerland
Swissmedic oversight of high-value oncology packaging sustains premium equipment margins in Basel pharmaceutical manufacturing zones. Cold-form aluminum barrier requirements for moisture-sensitive biologics drive specialized deep-draw equipment demand. Zurich equipment integrators supply validated thermal stability systems for cell and gene therapy producers.
China
NMPA traceability regulations align with international serialization standards, forcing equipment upgrades in Yangtze River Delta pharmaceutical manufacturing zones. MIIT industrial automation subsidies accelerate servo-driven forming station adoption across Jiangsu and Zhejiang packaging facilities. Shanghai contract manufacturers scale thermoforming capacity for export markets under tightened FDA oversight.
Blister Packaging Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with European OEMs commanding premium positioning through integrated serialization architectures while Asian fabricators capture volume through cost-optimized platforms. The supply base organizes into three tiers: full-line integrators with vertical control over forming-to-cartoning sequences; modular specialists supplying standalone thermoforming or sealing stations; and regional assemblers serving emerging markets with standardized mechanical platforms. Consolidation pressure intensifies as serialization mandates force smaller mechanical-cam manufacturers toward acquisition or exit. Capacity expansion dominates competitive moves in India and China, while technology licensing agreements proliferate among European specialists seeking localized service presence.
Among German full-line integrators, Uhlmann Packaging Group and Syntegon Technology exemplify the premium-tier archetype through integrated Industry 4.0 architectures. ACG Worldwide anchors the emerging-market volume position through localized service networks across Indian pharmaceutical clusters. IMA Group and Marchesini Group occupy mid-tier positions between high-automation European standards and cost-optimized Asian platforms, with Italian engineering heritage visible in their corporate structures.
| Leading Market Players |
|---|
| Uhlmann Packaging Group |
| IMA Group |
| Marchesini Group |
| Romaco Group |
| Syntegon Technology |
| ACG Worldwide |
| Mediseal |
| Hoonga |
| CAM Packaging Machines |
| Others |
Supply Flow & Price Mechanics
Stainless steel price indices and servo motor component benchmarks cascade through blister packaging equipment supply chains, compressing OEM margins at the precision-forming tier while amplifying pricing power for integrators with captive component production.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium capture while spot inventory clears at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates full-line integrators with Industry 4.0 architectures from modular specialists and regional assemblers. Price differentiation hinges on FDA 21 CFR Part 11 certification tier and after-sales service bundling. Pricing pressure stems from Indian and Chinese contract manufacturers negotiating multi-vendor service agreements to reduce total cost of ownership. Generic pharmaceutical producers in Gujarat and Jiangsu exhibit highest price sensitivity; Swiss oncology packaging facilities in Basel demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing of servo-driven forming stations extend equipment lifecycles and create secondary revenue streams for OEMs. Manufacturing concentration rests on Germany, India, and China, with Baden-Württemberg and Hyderabad hosting dense OEM clusters. Supply chains draw from precision-machined aluminum tooling, high-torque servo motors, and vision inspection sensors. Single-source vulnerability in German-engineered forming station controllers creates bottleneck risk. Distribution runs through direct OEM sales for pharmaceutical integrators and regional distributor networks for emerging market assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blister packaging equipment supply is tightening around serialized line capacity, with validation engineer scarcity propping pricing for compliant installations.
For Market Incumbents: Extend service revenue through predictive maintenance subscriptions leveraging edge computing and machine vision analytics. Consolidate around full-line integration from forming through cartoning to defend against modular specialists. Add capacity in Hyderabad and Ahmedabad to capture PLI scheme-driven demand from Indian generic producers. For New Entrants and Emerging Players: Capture biologics packaging white space in Massachusetts and Switzerland where cold-form aluminum barrier requirements outstrip specialized equipment supply. Target digital machine segments for cell therapy applications with thermal stability tracking. Enter through technology licensing with European OEMs seeking localized service presence in Yangtze River Delta clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor mechanical-cam manufacturers in Southern Europe facing EU MDR compliance-driven obsolescence. Long-term viability centers on serialization-capable architectures over the next decade. Watch FDA DSCSA enforcement intensity and EMA Annex 1 sterile manufacturing revisions as inflection signals for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Uhlmann Packaging Group and Syntegon Technology reduce input cost volatility through captive supply of precision forming components. |
| Technology Licensing for Localized Service | European specialists grant forming station patents to Indian assemblers, capturing PLI scheme-driven demand without direct capital deployment. |
| AI-Enabled Predictive Maintenance Launch | OEMs offer uptime guarantees as subscription revenue streams, unbundling after-sales service from equipment purchase contracts. |
| Cold-Form Aluminum Line Expansion | Swiss and German manufacturers add deep-draw capacity to serve moisture-sensitive biologics packaging in Basel and Massachusetts cell therapy corridors. |
| Isolator-Integrated Line Development | Bavarian and Irish facilities demand validated decontamination cycles for aseptic blister applications under tightening EMA Annex 1 requirements. |
Methodological Framework
Trade publications, pharmaceutical manufacturing databases, and regulatory filing repositories formed the secondary backbone of this study. Primary interviews with packaging line engineers, pharmaceutical procurement managers, OEM sales directors, and validation compliance officers supplied operational context. Bottom-up equipment shipment tallies triangulated against top-down pharmaceutical capital expenditure surveys to anchor market sizing.
Historical trendline analysis of pharmaceutical packaging equipment procurement patterns established baseline growth trajectories across the projection horizon. Segmentation modeling spanned product type, material format, end-use application, forming methodology, and regional regulatory cluster. CAGRs were derived from curve-fitting validated shipment data against pharmaceutical production capacity expansion schedules and serialization mandate compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA DSCSA enforcement timing and EMA MDR traceability activation schedules. Forecasts reflect documented assumptions regarding generic drug export volume trajectories from India and China. Practitioners should monitor stainless steel price volatility and validation engineer labor market tightness for early signals of margin compression or delivery timeline extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Blister Cards Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market