
 Pharmaceutical Vials Market | 2026-2036
Pharmaceutical Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Vials Market Outlook
The EU Green Deal's packaging sustainability targets is shifting pharmaceutical buyers toward recyclable and reduced-weight vial formats. Gerresheimer AG leverages its borosilicate glass expertise to sustain leadership in premium sterile containment. SCHOTT AG anchors its position through proprietary FIOLAX glass tubing and controlled manufacturing scale across European and Asian plants. Stevanato Group differentiates via integrated offerings spanning glass tubing, vial conversion, and inspection systems.
Pharmaceutical vials are rigid primary containers engineered from borosilicate glass or polymer resins, typically ranging from 2 mL to 100 mL in nominal volume, designed to maintain sterility, chemical stability, and seal integrity for injectable and biologic drug products. Glass vials dominate parenteral applications owing to their inertness and barrier performance against oxygen and moisture ingress. Single-dose vials command premium positioning in oncology and vaccine portfolios where cross-contamination risks mandate unit-of-use packaging, while multi-dose formats retain cost advantages in chronic disease therapeutics administered in clinical settings. Plastic and polypropylene segments are gaining traction in cytotoxic and biologic applications where breakage resistance and reduced protein adsorption justify material switching.
FDA sterilization validation requirements and EU MDR traceability mandates are elevating compliance costs for vial converters while simultaneously consolidating procurement toward qualified suppliers with documented quality systems. ISO 15378 and USP <660> standards govern glass surface durability and extractable profiles, directly shaping material selection and supplier qualification timelines. BIS certification in India and NMPA registration pathways in China impose additional regional testing burdens that favor manufacturers with established regulatory affairs infrastructure. Stakeholders must monitor evolving pharmacopeial harmonization efforts and sterilization modality shifts, as electron beam and vaporized hydrogen peroxide alternatives to traditional steam sterilization are altering equipment capital requirements and validation protocols.
Market Dynamics
Biologics manufacturers are consolidating procurement around ready-to-fill vial formats, compressing supplier qualification timelines and elevating quality-system documentation requirements across the value chain.
Growth Catalysts
- EU MDR traceability mandates:Sterile containment buyers are prioritizing suppliers with documented batch-level material genealogy, accelerating consolidation toward qualified converters.
- Ready-to-fill vial adoption:Biologics fill-finish operations are eliminating washing and depyrogenation steps, reducing contamination risk and capital deployment.
- German glass tubing clusters:Proximity to borosilicate feedstock sources is shortening lead times for high-volume parenteral drug launches.
Market Restraints
- Borosilicate glass supply concentration:Three European tubing manufacturers control critical feedstock for premium sterile applications, creating vulnerability to energy-cost volatility.
- FDA sterilization validation burden:Steam sterilization alternatives require extensive protocol redevelopment, extending new product introduction timelines by 12-18 months.
- Polymer substitution limits:Cyclic olefin polymer vials face oxygen permeability constraints that exclude them from oxygen-sensitive biologics despite breakage advantages.
Strategic Opportunities
- India BIS certification pathways:Domestic vaccine manufacturing expansion is creating demand for locally certified glass converters with EU-equivalent quality systems.
- Electron beam sterilization convergence:Integration with continuous manufacturing lines enables real-time release testing, compressing batch release cycles.
- EU Green Deal packaging targets:Recyclable and reduced-weight vial formats are qualifying for preferential procurement in European public health tenders.
Industry Challenges
- Pharmacopeial harmonization delays:Divergent USP, EP, and JP surface durability test methods force redundant validation studies for multi-regional product registrations.
- Legacy inspection system integration:Automated visual inspection platforms require substantial retrofit investment to handle next-generation polymer vial refractive properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Vials Market |
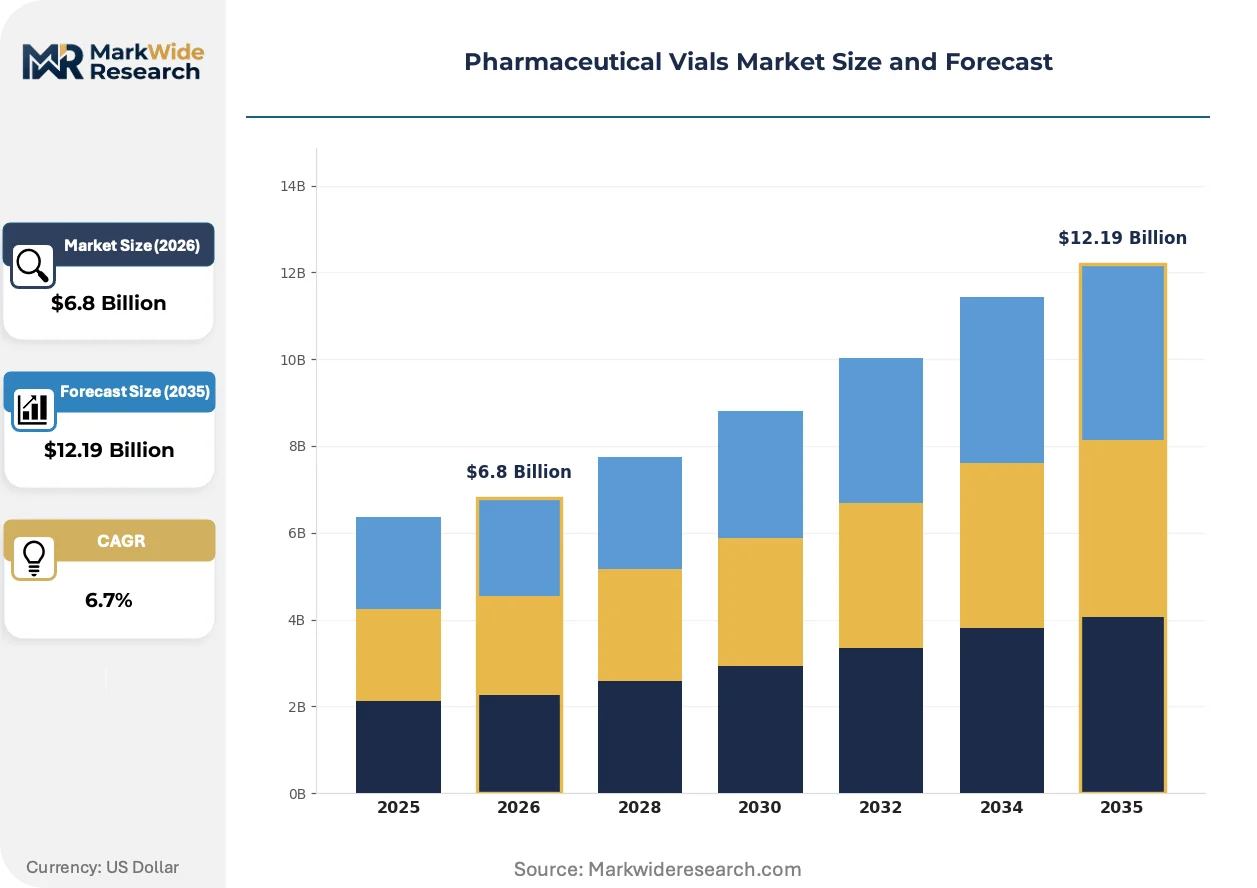
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Polypropylene, PVC Product Type: Single-Dose, Multi-Dose, Sterile, Non-Sterile Closure Type: Rubber Stopper, Plastic Cap, Metal Seal, Aluminum Cap End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Institutions, Healthcare Facilities |
| Companies Covered | Gerresheimer AG, SCHOTT AG, Stevanato Group, SGD Pharma, Nipro Corporation, West Pharmaceutical Services, DWK Life Sciences, Corning, Piramal Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Vials Market Strategic Shifts
Material science advances and regulatory protocol evolution are compressing traditional glass-to-plastic substitution cycles while elevating quality assurance automation requirements.
Cyclic olefin polymer vials are absorbing protein adsorption-sensitive biologic applications where silicone oil contamination from glass delamination poses stability risks. Oncology and cell therapy developers are piloting polymer formats for high-value monoclonal antibodies. This material transition is absorbing technical validation resources that previously supported glass tubing capacity expansion.
EU MDR Annex I general safety and performance requirements are mandating unique device identification on primary packaging, forcing vial converters to integrate laser-marking or label-embedding capabilities. The regulation compresses legacy unmarked vial inventories from European distribution. Sterile drug manufacturers with multi-regional portfolios are most affected, accelerating harmonization with FDA UDI timelines.
Fill-finish outsourcing to contract manufacturing organizations is concentrating buying power among specialized CDMOs with integrated ready-to-use component sourcing. Traditional distributor channels face margin compression as direct converter-CMO relationships bypass intermediaries. This consolidation is most visible in United States biotech hubs where venture-backed drug developers lack captive manufacturing infrastructure.
Pharmaceutical Vials Market Segmentation
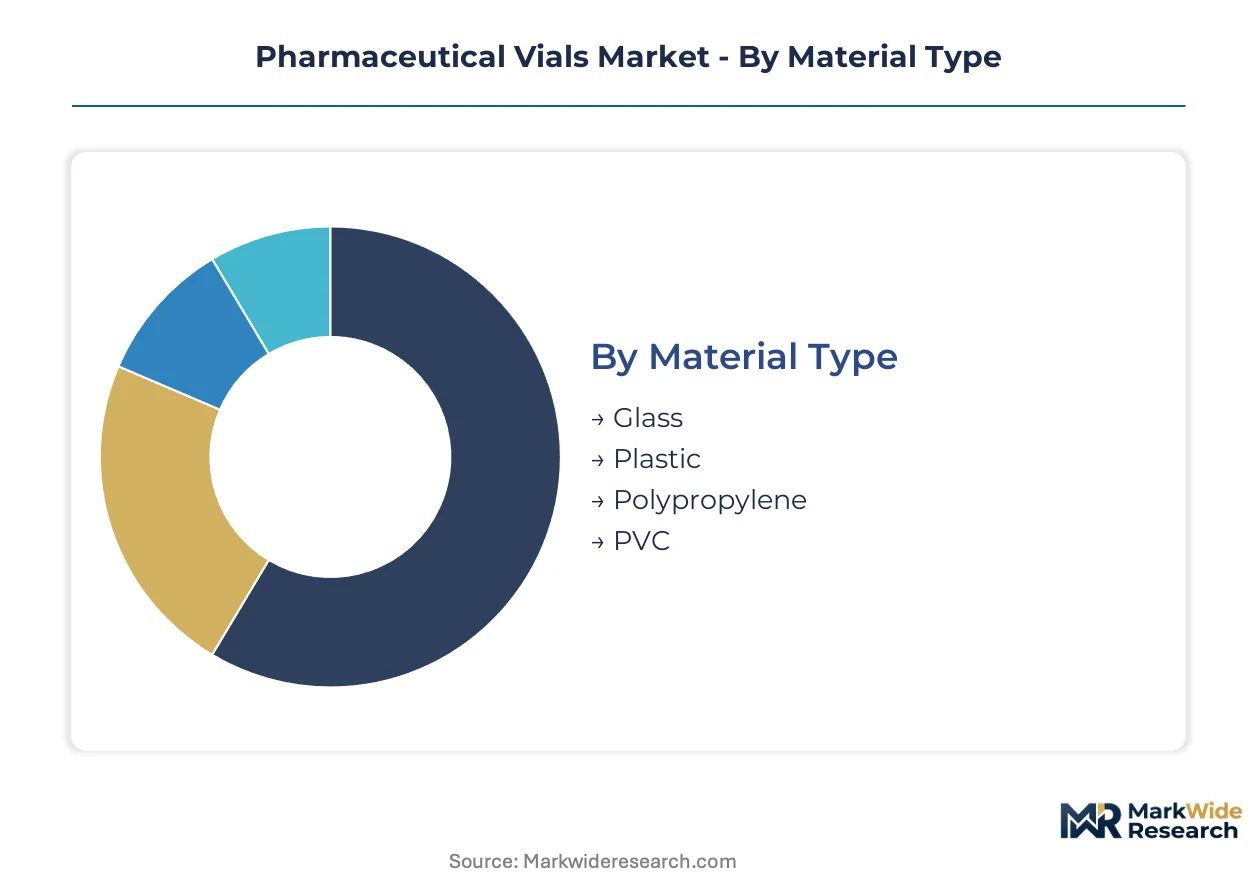
Segmentation in pharmaceutical vials reflects divergent sterilization protocols, material compatibility requirements, and procurement economics across biologics, generics, and clinical trial supply chains. Buyers prioritize extractable profiles, break resistance, and regulatory documentation breadth when selecting formats.
Material Type:
Cost tier and performance requirements separate buyers seeking premium barrier properties from those prioritizing handling durability.
- Glass:Borosilicate formulations dominate parenteral applications requiring inert surfaces and oxygen barrier performance. German and Indian sterile drug manufacturers specify FIOLAX-equivalent tubing for high-value biologics where delamination risks mandate premium feedstock.
- Plastic:Cyclic olefin polymers absorb protein adsorption-sensitive monoclonal antibody applications where silicone oil contamination from glass poses stability failures. Oncology developers in the United States pilot polymer formats for cell therapies despite oxygen permeability constraints.
- Polypropylene:Cost-sensitive generic injectables favor this resin for multi-dose antibiotic vials in clinical settings.
- PVC:Limited to non-parenteral diagnostic reagents where plasticizer migration is tolerable.
Glass leads volumes today; plastic is gaining share fastest.
Product Type:
Application risk profile determines whether buyers absorb premium unit-of-use costs or accept cross-contamination exposure.
- Single-Dose:Unit-of-use formats command premium positioning in oncology and vaccine portfolios where patient safety mandates elimination of multi-dose contamination pathways. FDA sterilization validation requirements for single-dose biologics compress supplier qualification timelines toward qualified converters.
- Multi-Dose:Chronic disease therapeutics administered in hospital settings retain cost advantages through shared vial formats. German healthcare procurement tenders specify multi-dose antibiotics for inpatient formulary compliance.
- Sterile:Ready-to-fill formats eliminate washing and depyrogenation steps for biologics fill-finish operations.
- Non-Sterile:Bulk API storage and compounding pharmacy applications accept terminal sterilization downstream.
Multi-Dose dominates procurement spend; Single-Dose shows steepest expansion trajectory.
Closure Type:
Seal integrity specifications and automated handling compatibility separate high-speed fill-finish operations from manual clinical compounding.
- Rubber Stopper:Bromobutyl and chlorobutyl formulations provide resealability for multi-dose access while minimizing extractables. Indian vaccine manufacturers specify coated stoppers to prevent protein aggregation in refrigerated biologics.
- Plastic Cap:Breakage-resistant formats serve cytotoxic drug handling where aluminum seal removal poses sharps hazards.
- Metal Seal:Crimped aluminum retains dominance in high-speed parenteral lines.
- Aluminum Cap:Flip-off designs accelerate nurse administration in emergency settings.
Rubber Stopper anchors sterile containment; Plastic Cap expands most quickly in oncology handling.
End User:
Regulatory documentation burden and volume scale separate integrated pharmaceutical operations from outsourced development.
- Pharmaceutical Companies:Captive fill-finish operations demand batch-level material genealogy documentation under EU MDR traceability mandates. German and United States biologics manufacturers consolidate procurement around qualified converters with ISO 15378 certification.
- Contract Manufacturing Organizations:CDMO buying power concentrates as venture-backed drug developers outsource sterile manufacturing. United States biotech hubs drive direct converter-CMO relationships bypassing traditional distribution.
- Research Institutions:Clinical trial supply chains require small-batch flexibility with rapid protocol amendments.
- Healthcare Facilities:Hospital pharmacy compounding demands just-in-time delivery of non-sterile bulk formats.
Pharmaceutical Companies command procurement volume; Contract Manufacturing Organizations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass tubing production originated in German industrial clusters during the early twentieth century, establishing quality benchmarks that persist in pharmaceutical containment standards today. Manufacturing gravity has since dispersed across three continents while regulatory fragmentation intensifies localization requirements.
Germany
Domestic biologics fill-finish operations demand FIOLAX-equivalent tubing for high-value monoclonal antibody portfolios. EU MDR traceability mandates compress supplier qualification timelines toward converters with batch-level material genealogy documentation. The Mainz-Wiesbaden corridor anchors specialized glass conversion capacity serving European sterile drug launches.
United States
Venture-backed biotech developers outsource sterile manufacturing to contract manufacturing organizations with integrated ready-to-use component sourcing. FDA sterilization validation requirements for single-dose biologics elevate quality-system documentation burdens. Boston-Cambridge and San Diego biotech clusters concentrate procurement power among specialized CDMOs bypassing traditional distribution channels.
India
Domestic vaccine manufacturing expansion under the PLI scheme creates demand for locally certified glass converters with EU-equivalent quality systems. BIS certification imposes regional testing burdens favoring manufacturers with established regulatory affairs infrastructure. Gujarat and Maharashtra pharmaceutical clusters drive qualification of indigenous borosilicate conversion capacity.
China
NMPA registration pathways for imported sterile containment require extensive local testing protocols. Domestic biologics developers pilot cyclic olefin polymer formats for protein adsorption-sensitive applications despite oxygen permeability constraints. Yangtze River Delta pharmaceutical manufacturing bases concentrate fill-finish outsourcing demand.
Switzerland
Swissmedic oversight of sterile drug manufacturing elevates documentation requirements for primary packaging suppliers. Precision biologics manufacturing in the Basel region demands premium barrier performance from borosilicate containment. The country's pharmaceutical value chain prioritizes suppliers with demonstrated pharmacopeial harmonization capabilities.
Pharmaceutical Vials Market Competitive Environment
Premium-margin players sit above commodity-margin players across material certification and regulatory documentation dimensions. The vendor base stratifies between integrated tubing-converter-inspection system operators and specialized conversion houses dependent on external feedstock. Three archetypes dominate: German-engineered glass specialists with captive tubing supply, Asian-scale converters serving cost-sensitive generics, and polymer-focused innovators targeting biologic protein stability applications. Capacity expansion and backward integration into borosilicate tubing production constitute the dominant competitive moves.
Among German-engineered specialists, Gerresheimer AG and SCHOTT AG occupy positions anchoring premium sterile containment supply. Stevanato Group exemplifies the integrated archetype spanning glass tubing, vial conversion, and inspection platforms. These three entities represent distinct strategic postures within a market where regulatory documentation breadth and material traceability capabilities separate qualified suppliers from commodity competitors.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| Stevanato Group |
| SGD Pharma |
| Nipro Corporation |
| West Pharmaceutical Services |
| DWK Life Sciences |
| Corning |
| Piramal Glass |
| Others |
Value Chain & Pricing Dynamics
FIOLAX borosilicate glass tubing spot prices cascade through three distinct procurement tiers, compressing margins for converters without captive feedstock while rewarding integrated German manufacturers with premium positioning in EU MDR-compliant supply chains. Energy cost volatility at European melting furnaces propagates downstream as surcharges on standard-grade vials, widening the spread between certified sterile containment and commodity multi-dose formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates qualified converters with ISO 15378 certification from regional generics suppliers. Price differentiation hinges on batch-level material genealogy documentation and sterilization validation completeness. Cost compression in standard-grade borosilicate formats is intensifying because Indian and Chinese converters are qualifying for BIS and NMPA pathways at lower overhead bases. Contract manufacturing organizations exhibit highest price sensitivity due to venture-backed biotech clients demanding ready-to-fill formats at scale; biologics innovators with captive fill-finish show lowest sensitivity, prioritizing delamination risk mitigation over unit cost.
Supply Chain Analysis
Specialized furnace operators in Germany, India, and China face acute competition for technical glassblowers and quality-system engineers, constraining expansion timelines for new tubing capacity. Borosilicate glass supply draws from concentrated European feedstock sources, with SCHOTT AG and Gerresheimer AG controlling premium FIOLAX-equivalent output. Single-source vulnerability pervades the premium sterile tier where three tubing manufacturers service global biologics demand. Distribution runs through direct converter-CDMO relationships in United States biotech hubs, bypassing traditional pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pharmaceutical vials rests on ready-to-fill format penetration compressing downstream processing costs for biologics manufacturers, while premium-tier pricing for polymer alternatives captures protein stability-sensitive applications.
For Market Incumbents: Anchor market position through backward integration into borosilicate tubing production and electron beam sterilization capability installation. Cyclic olefin polymer substitution threatens glass dominance in monoclonal antibody portfolios. Capacity addition in Gujarat and Maharashtra pharmaceutical clusters secures BIS-certified supply for domestic vaccine manufacturing expansion under India's PLI scheme. For New Entrants and Emerging Players: The mid-tier pricing gap between FIOLAX-certified German supply and Indian standard-grade conversion creates white-space for EU-equivalent quality systems at Asian cost bases. Contract manufacturing organizations in Boston-Cambridge and San Diego biotech corridors represent the most penetrable buyer segment. Qualify for FDA sterilization validation pathways to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated tubing-converter-inspection system operators possessing pharmacopeial harmonization capabilities. Five-to-ten year viability favors specialists with demonstrated EU MDR traceability infrastructure. Monitor electron beam sterilization adoption rates as inflection indicator for batch release cycle compression and real-time release testing penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captive FIOLAX-equivalent supply secures margin capture from German glass clusters. |
| Electron Beam Sterilization Deployment | FDA validation for vaporized hydrogen peroxide alternatives compresses new product introduction timelines. |
| BIS Certification Pathway Investment | Domestic Indian vaccine manufacturing under PLI scheme demands locally qualified conversion capacity. |
| Polymer Vial Platform Development | Cyclic olefin polymer formats absorb protein adsorption-sensitive biologics from glass delamination risks. |
| Laser-Marking Capability Integration | EU MDR Annex I UDI mandates force unique device identification on primary sterile containment. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fill-finish operations directors, regulatory affairs leads at sterile drug manufacturers, CDMO procurement heads, and glass tubing plant managers with secondary validation against FDA 483 observations, EMA inspection reports, USP pharmacopeial updates, and ISO 15378 certification registries. Bottom-up demand modeling from biologics pipeline databases triangulated against top-down glass tubing capacity estimates.
Segment-weighting across material type, product format, closure system, and end-user channel governed volume distribution through the projection horizon. Treatment line differentiation, administration route requirements, and regional regulatory cluster stringency shaped analytical framework construction. CAGRs derived from sterilization modality adoption curves, biologics fill-finish outsourcing rates, and polymer substitution elasticity in protein stability applications.
Caveats apply where EU MDR implementation delays, borosilicate energy cost spikes, or pharmacopeial harmonization failures could materially shift the outlook. Forecasts embed assumptions regarding sterilization validation protocol convergence and CDMO consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Vial Box Market