
 Single Dose Dispensers Market | 2026-2036
Single Dose Dispensers Market Size, Share, and Industry Trends Forecast 2026-2036
Single Dose Dispensers Market Analytics
Connected device architecture and cloud-based medication adherence tracking is rewriting how single dose dispensers integrate into care workflows. Becton, Dickinson and Company leverages its hospital automation portfolio to anchor high-acuity dispensing installations across North American health systems. Omnicell competes through centralized inventory platforms that extend into retail pharmacy automation, while Swisslog Healthcare specializes in robotic dispensing systems for European hospital pharmacies.
Single dose dispensers are precision-engineered medication delivery units designed to isolate, store, and release one pre-measured unit of pharmaceutical product per activation cycle, typically incorporating tamper-evident seals, moisture barriers, and child-resistant locking mechanisms to preserve drug stability and prevent accidental ingestion. Their primary commercial purpose centers on eliminating dosing errors, reducing medication waste, and enabling remote adherence monitoring across decentralized care settings. Pill dispensers dominate unit volumes due to oral solid dosage form prevalence, though smart dispensers represent the fastest-expanding margin pool as IoT-enabled devices command premium pricing through real-time caregiver alerts and integration with electronic health records. Liquid dispensers occupy a mature niche serving pediatric and geriatric populations with swallowing difficulties, where formulation complexity limits supplier entry.
FDA 21 CFR Part 11 compliance requirements shape software-enabled dispenser validation protocols, while EMA's Falsified Medicines Directive mandates serialization features that drive hardware upgrade cycles across European deployments. Japan's PMDA enforces stringent electromagnetic compatibility standards for home-use automated devices, creating certification barriers for non-domestic manufacturers. Stakeholders must weigh regulatory divergence against platform standardization strategies when allocating R&D budgets across geographic footprints.
Market Dynamics
Connected single dose dispensers are digitizing medication adherence workflows through cloud-native architectures that compress care coordination costs and enable real-time intervention by remote clinical teams.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements for software-enabled dispensers are accelerating validation investments by hospital pharmacy automation vendors.
- Home healthcare expansion:Aging populations in Germany and Japan are deploying smart dispensers to manage polypharmacy outside institutional settings.
- EMA Falsified Medicines Directive:Serialization mandates for unit-dose packaging are forcing hardware upgrade cycles across European hospital pharmacies.
Market Restraints
- Electromagnetic compatibility certification:Japan's PMDA enforces stringent EMC standards for home-use devices, creating 12-18 month approval delays for non-domestic manufacturers.
- Moisture barrier material concentration:Supply of pharmaceutical-grade desiccant polymers concentrates among three specialty chemical suppliers in Germany and Switzerland.
- Li-ion battery thermal runaway risk:Smart dispensers with rechargeable power sources face transport and disposal restrictions under evolving UN 38.3 testing protocols.
Strategic Opportunities
- Rural India penetration:Last-mile pharmacy networks in Maharashtra and Karnataka present untapped demand for solar-powered, offline-capable dispensers with vernacular interfaces.
- Biologic cold-chain integration:Convergence of IoT temperature logging with single-dose injection devices opens refrigerated last-mile delivery for mRNA therapeutics.
- US Medicare Advantage supplemental benefits:2024 CMS expansion of in-home supportive services creates reimbursement pathways for dispenser-as-medical-equipment models.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time operating system programming for medical devices competes with automotive and aerospace sectors for limited engineering pools in Massachusetts and Bavaria.
- EHR interoperability certification:HL7 FHIR compliance timelines stretch 14-22 months as health systems demand bidirectional data exchange with Epic and Cerner deployments.
- Multi-jurisdiction patent thickets:Child-resistant locking mechanism IP fragments across 40+ patent families held by packaging conglomerates and independent inventors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Dose Dispensers Market |
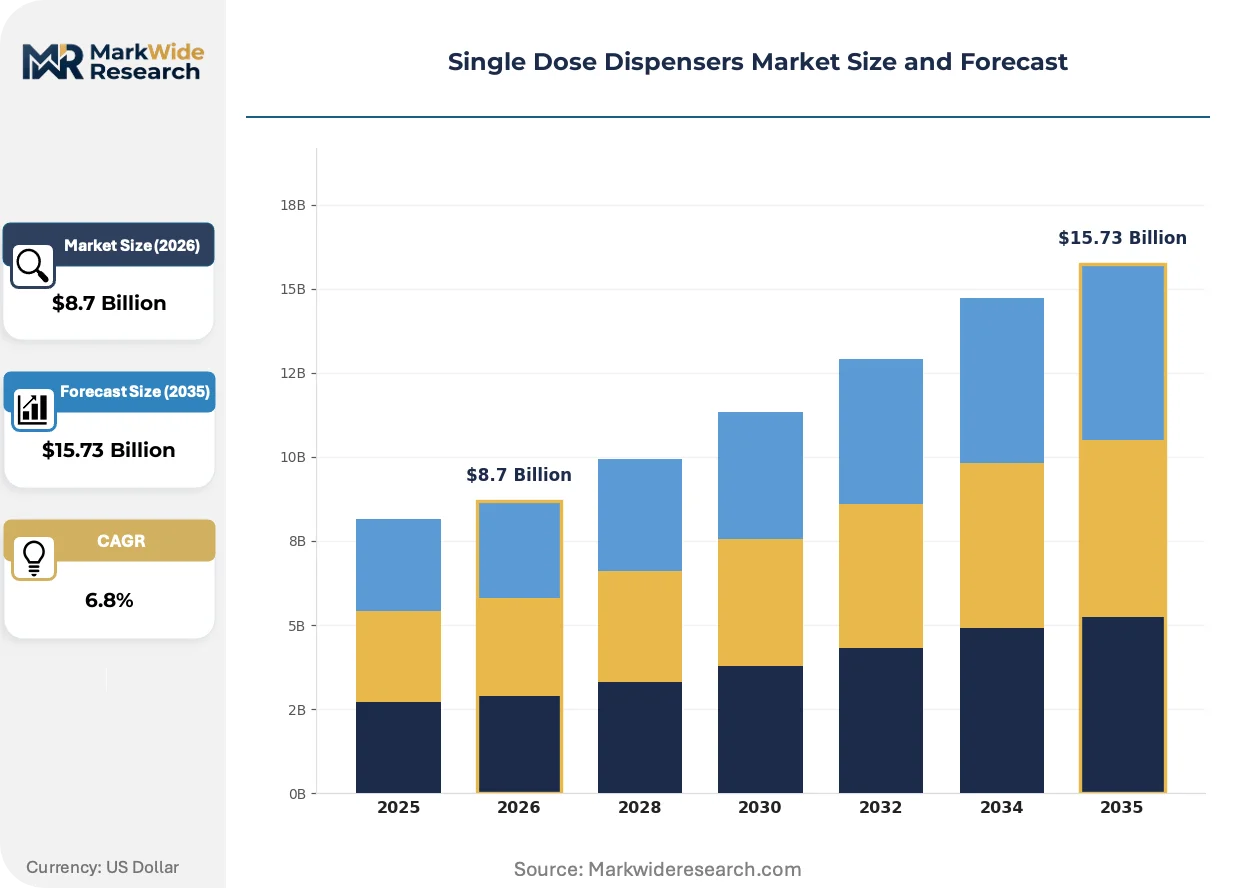
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pill Dispensers, Liquid Dispensers, Powder Dispensers, Patch Dispensers Application: Home Healthcare, Hospitals, Pharmacies, Long-term Care Facilities End User: Patients, Caregivers, Healthcare Professionals, Retailers Technology: Automated Systems, Manual Systems, Smart Dispensers, Mobile Applications |
| Companies Covered | Becton, Dickinson and Company, Omnicell, Capsa Healthcare, ScriptPro, McKesson Corporation, ARxIUM, ACCU-CHART, Yuyama Co., Ltd, Swisslog Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Dose Dispensers Market Evolving Landscape
Three intersecting forces are restructuring how single dose dispensers capture value: embedded sensor miniaturization, regulatory mandates for pharmaceutical traceability, and the unbundling of device ownership from medication adherence services.
Near-field communication and accelerometer arrays embedded in pill blister packs are digitizing dose-level consumption data without requiring patient smartphone pairing. Long-term care facilities in the Netherlands and Denmark are piloting these passive smart packages to reduce nursing documentation burden. The technology is digitizing adherence verification by eliminating manual pill counts and enabling automated refill triggers through pharmacy management systems.
EMA's 2023 delegated regulation on safety features for medicinal products is mandating two-dimensional data matrix codes on all unit-dose packaging by February 2025. European hospital pharmacies are retrofitting robotic dispensing cells with vision systems capable of verifying serialized blisters at 600 units per minute. German health insurers are conditioning reimbursement on dispensers capable of scanning and logging these identifiers, compressing upgrade cycles for legacy automation infrastructure.
Pharmacy benefit managers in the United States are consolidating procurement decisions for connected dispensers under centralized formulary committees, displacing individual health system purchasing autonomy. UnitedHealthcare and CVS Caremark are requiring device interoperability with their proprietary adherence dashboards as a condition of preferred network placement. This concentration is most visible in Florida and Texas, where Medicare Advantage penetration exceeds 50% and PBM-owned specialty pharmacies dominate high-cost oral oncology distribution.
Single Dose Dispensers Market Segmentation
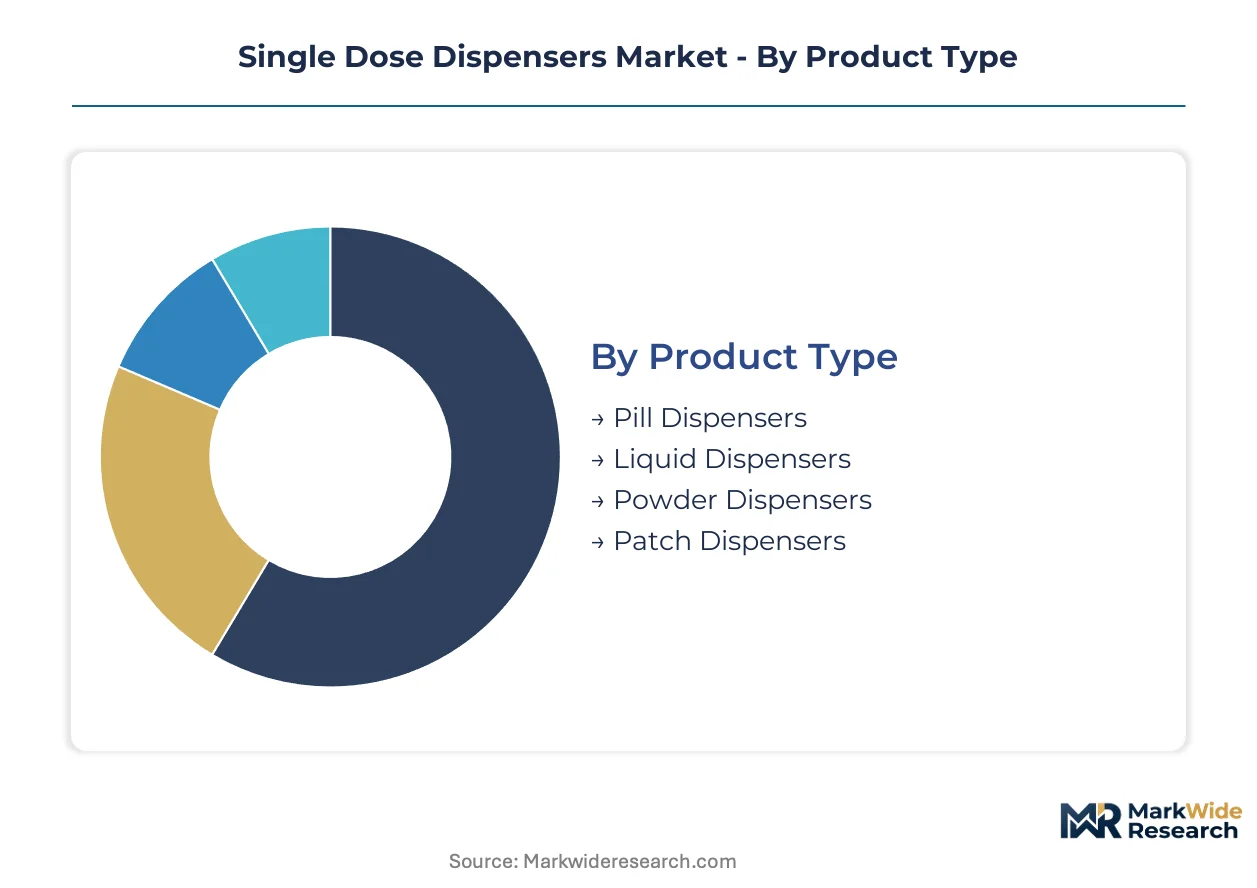
Single dose dispensers fragment across four intersecting dimensions that determine pricing power, regulatory burden, and channel access. Product type and technology stratification create the deepest margin pools, while application and end-user segmentation govern procurement authority and reimbursement pathways.
Product Type:
Mature oral solid formats dominate installed base volumes, though emerging delivery mechanisms are capturing premium positioning in specialized therapeutic areas.
- Pill Dispensers:Mechanical and electromechanical units engineered for tablet and capsule isolation, incorporating tamper-evident seals and child-resistant locking mechanisms. Demand concentrates in United States Medicare Advantage networks and German long-term care chains where polypharmacy management drives automation procurement. Moisture barrier material shortages from German and Swiss specialty chemical suppliers constrain margin expansion.
- Liquid Dispensers:Precision pump and syringe-based systems designed for oral suspensions and solutions, featuring dose-volume verification and anti-microbial contact surfaces. Pediatric wards in Tokyo metropolitan hospitals and geriatric facilities in Osaka prefecture generate concentrated demand for swallowing-difficulty formulations. Formulation complexity limits supplier entry to established medical device manufacturers with fluid handling expertise.
- Powder Dispensers:Aerosol containment systems for inhalable and reconstitutable pharmaceuticals, integrating particle size control and humidity protection.
- Patch Dispensers:Unit-dose peel-and-seal packaging for transdermal delivery systems, emphasizing adhesive stability and oxygen barrier properties.
Pill dispensers retain volume leadership; patch dispensers hold the steepest expansion curve given transdermal therapeutic expansion in pain management and hormone replacement.
Application:
Procurement authority shifts from centralized hospital pharmacy committees to distributed home healthcare budgets as reimbursement models migrate toward value-based care.
- Home Healthcare:Patient-operated and caregiver-managed dispensing units deployed in residential settings, spanning basic mechanical organizers to cloud-connected adherence monitors. UnitedHealthcare and CVS Caremark formulary committees in Florida and Texas now mandate interoperability with proprietary adherence dashboards as a condition of preferred network placement. FDA 21 CFR Part 11 compliance requirements for software-enabled devices extend validation timelines.
- Hospitals:High-throughput robotic dispensing cells integrated with pharmacy information systems, capable of 600-unit-per-minute verification through vision systems. European hospital pharmacies in the Netherlands and Denmark are retrofitting infrastructure to meet EMA serialization mandates by the delegated regulation deadline.
- Pharmacies:Retail and specialty pharmacy automation spanning will-call retrieval systems to patient-facing adherence packaging.
- Long-term Care Facilities:Nurse-station and bedside dispensing solutions emphasizing documentation reduction and regulatory compliance for controlled substances.
Home healthcare applications are expanding most quickly as aging populations in Germany and Japan seek independent medication management outside institutional settings; hospitals maintain the highest average transaction values.
End User:
Decision-making authority fragments across clinical, familial, and commercial stakeholders with divergent technical requirements and purchasing processes.
- Patients:Direct consumers managing chronic conditions through self-administered regimens, prioritizing portability and simplified interfaces. Rural India networks in Maharashtra and Karnataka present demand for solar-powered, offline-capable dispensers with vernacular interfaces.
- Caregivers:Family members and home health aides requiring remote monitoring capabilities and alert systems for missed doses.
- Healthcare Professionals:Physicians, pharmacists, and nurses driving formulary decisions based on EHR integration and clinical workflow compatibility. HL7 FHIR compliance timelines stretch 14-22 months as health systems demand bidirectional data exchange with Epic and Cerner deployments.
- Retailers:Pharmacy chains and medical equipment distributors consolidating procurement under centralized supply chain functions.
Healthcare professionals control specification authority for institutional deployments; patients represent the fastest-growing direct purchaser segment through Medicare Advantage supplemental benefit expansion.
Technology:
Capability stratification separates premium connected platforms from commodity mechanical units, with intermediate automation occupying a contracting middle tier.
- Automated Systems:Electromechanical dispensing with programmable schedules, locking mechanisms, and basic audit logging, excluding cloud connectivity. European hospital pharmacies are forcing hardware upgrade cycles to accommodate EMA Falsified Medicines Directive serialization requirements.
- Manual Systems:Non-powered organizers and blister packs relying on patient or caregiver adherence without electronic verification.
- Smart Dispensers:IoT-enabled devices with cellular or Wi-Fi connectivity, real-time caregiver alerts, and integration with electronic health records. Japan's PMDA enforces stringent electromagnetic compatibility standards for home-use devices, creating 12-18 month approval delays for non-domestic manufacturers. Embedded systems firmware talent scarcity in Massachusetts and Bavaria constrains development velocity.
- Mobile Applications:Smartphone-based adherence tracking and dose reminder systems, often paired with passive smart packaging rather than active dispensing hardware.
Manual systems retain volume leadership across price-sensitive segments; smart dispensers command the steepest value expansion trajectory through premium pricing and recurring service revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical suppliers export pharmaceutical-grade desiccant polymers to automated dispenser manufacturers across North American and Asian health systems, creating a trade-flow corridor that shapes regional deployment timelines and moisture barrier material availability.
United States
Medicare Advantage networks in Florida and Texas drive procurement concentration for connected adherence devices through formulary committee centralization. FDA 21 CFR Part 11 compliance requirements extend software validation timelines for cloud-native dispenser platforms. Hospital automation clusters in Greater Boston and the Research Triangle anchor high-acuity robotic dispensing installations.
Germany
Long-term care chains and polypharmacy management programs generate institutional demand for electromechanical pill dispensers. EMA Falsified Medicines Directive serialization mandates force hardware upgrade cycles across hospital pharmacy infrastructure. The Baden-Württemberg medical technology corridor concentrates robotic dispensing system engineering and vision system integration capabilities.
Japan
Aging populations in Tokyo and Osaka prefectures deploy smart dispensers for independent medication management outside institutional settings. PMDA electromagnetic compatibility standards for home-use devices create 12-18 month approval delays for non-domestic manufacturers. The Nagoya medical device cluster specializes in precision pump systems for liquid dispensers serving swallowing-difficulty populations.
India
Last-mile pharmacy networks in Maharashtra and Karnataka present demand for solar-powered, offline-capable dispensers with vernacular interfaces. CDSCO medical device regulations tighten quality standards for imported automated dispensing hardware. The Bangalore health technology cluster incubates low-cost connected adherence platforms targeting rural healthcare infrastructure gaps.
Netherlands
Long-term care facilities pilot passive smart packaging with embedded NFC and accelerometer arrays to reduce nursing documentation burden. EMA delegated regulation deadlines accelerate vision system retrofits for serialized blister verification. The Eindhoven medical electronics cluster advances sensor miniaturization for dose-level consumption tracking without smartphone pairing.
Single Dose Dispensers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where hospital automation vendors, retail pharmacy systems integrators, and regional medical device fabricators occupy distinct capability layers. Consolidation pressure concentrates procurement authority under pharmacy benefit managers and centralized hospital supply chains. Three archetypes dominate: full-stack automation platforms, modular dispensing component suppliers, and geographic niche specialists. Competitive moves center on EHR interoperability certification and serialization-ready hardware upgrade programs.
Within the full-stack automation tier, Becton, Dickinson and Company and Omnicell exemplify channel-controlling positioning through hospital system anchoring and centralized inventory platform extension. Swisslog Healthcare occupies a position within the European robotic dispensing specialization cluster. Yuyama Co., Ltd represents the Japan-based precision engineering archetype serving fluid handling and electromechanical dispensing applications. These three companies illustrate how geographic origin and corporate structure correlate with strategic archetype alignment across the competitive map.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Omnicell |
| Capsa Healthcare |
| ScriptPro |
| McKesson Corporation |
| ARxIUM |
| ACCU-CHART |
| Yuyama Co., Ltd |
| Swisslog Healthcare |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container rate volatility amplifies cost differentials between German-engineered precision components and Asian-manufactured electromechanical assemblies, concentrating margin pressure on mid-tier automated dispenser suppliers while enabling premium pricing for serialization-ready hardware.
Pricing Analysis
Next-generation IoT-enabled smart dispensers command substantial premiums over electromechanical automated systems and basic manual organizers. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 11 software validation status and EMA serialization compliance certification. Cost compression in the mid-tier automated segment intensifies because European hospital pharmacies accelerate hardware refresh cycles ahead of regulatory deadlines. Retail pharmacy chains and Medicare Advantage formulary committees exhibit the highest price sensitivity, while academic medical centers prioritize interoperability over unit cost.
Supply Chain Analysis
Pharmaceutical-grade desiccant polymers and precision-molded child-resistant locking mechanisms draw from specialty chemical suppliers concentrated in Germany, Switzerland, and Japan. Raw material dependencies center on moisture barrier films, Li-ion power cells, and medical-grade ABS resins. Single-source vulnerability pervades the desiccant polymer segment where three suppliers control global capacity. Distribution runs through hospital GPO contracts, PBM-owned specialty pharmacies, and regional medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating under pharmacy benefit manager formulary committees and hospital GPO procurement functions, fragmenting individual health system autonomy and compressing supplier negotiation leverage.
For Market Incumbents: Pre-empt margin erosion in European hospital automation by accelerating EMA serialization-ready hardware deployments before competitor retrofit programs mature. Deepen captive supply of pharmaceutical-grade desiccant polymers through backward integration into Baden-Württemberg specialty chemical partnerships. Lock in UnitedHealthcare and CVS Caremark preferred network placement through proprietary adherence dashboard interoperability certification. For New Entrants and Emerging Players: Pursue rural India penetration through solar-powered, offline-capable dispensers with vernacular interfaces targeting Maharashtra and Karnataka last-mile pharmacy networks. Capture Medicare Advantage supplemental benefit reimbursement pathways in Florida and Texas where PBM consolidation creates equipment-as-a-service entry points. Lead with disposable passive smart packaging rather than capital-intensive connected hardware to bypass Japan's PMDA electromagnetic compatibility certification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular component suppliers with FDA software validation capabilities over full-stack automation platforms facing PBM procurement concentration. Five-to-ten year viability hinges on EHR interoperability certification velocity and serialization hardware upgrade cycle capture. Watch HL7 FHIR compliance timeline compression as the inflection signal indicating which suppliers can secure Epic and Cerner integration commitments.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Serialization Hardware Upgrade | European hospital pharmacies must retrofit robotic cells ahead of delegated regulation deadlines. |
| FDA 21 CFR Part 11 Software Validation | Cloud-native dispenser platforms require extended validation timelines for electronic records compliance. |
| HL7 FHIR EHR Interoperability Certification | Bidirectional data exchange with Epic and Cerner deployments stretches certification to 14-22 months. |
| Medicare Advantage Reimbursement Strategy | CMS supplemental benefits expansion creates equipment-as-medical-equipment procurement pathways. |
| Backward Integration into Desiccant Supply | German and Swiss specialty chemical concentration creates captive supply opportunities for moisture barrier materials. |
Research Methodology
Desk research of FDA 510(k) filings, EMA centralized procedure documentation, and hospital pharmacy procurement databases preceded structured interviews with hospital automation directors, PBM formulary managers, biomedical engineers, and GPO contracts specialists. Primary fieldwork validated secondary findings against hospital capital expenditure plans and retail pharmacy automation roadmaps. Bottom-up unit deployment estimates triangulated against top-down healthcare infrastructure spending projections.
Fixed assumptions across the analysis window held regulatory deadline schedules and reimbursement policy trajectories constant while varying technology adoption curves and supply chain disruption scenarios. Segmentation modeling incorporated product type, technology tier, application setting, and end-user decision authority dimensions. CAGRs derived from installed base growth rates, replacement cycle compression, and premium product mix shifts. Forecast inputs included polypharmacy prevalence projections and Medicare Advantage penetration patterns.
Sensitivities concentrate around PMDA certification timeline extensions, desiccant polymer supply disruptions, and PBM formulary committee procurement centralization. Forecasts reflect documented assumptions about regulatory enforcement intensity and healthcare labor cost trajectories. Cross-checking against CMS Medicare cost report data and European hospital pharmacy automation surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market