
 Middle East and Africa Pharmaceutical Plastic Packaging Market | 2026-2036
Middle East and Africa Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmaceutical Plastic Packaging Market Insights
A capital-intensity divergence between blow-molding equipment scale and barrier-coating capabilities is redrawing competitive tiers in the Middle East and Africa pharmaceutical plastic packaging market. Amcor Group GmbH leverages its multi-layer extrusion infrastructure to anchor supply contracts with multinational drug makers operating in Egypt and Saudi Arabia. Berry Global Inc. sustains regional competitiveness through rigid container specialization that meets Gulf Packaging Industries Limited dominates local distribution channels across the GCC states.
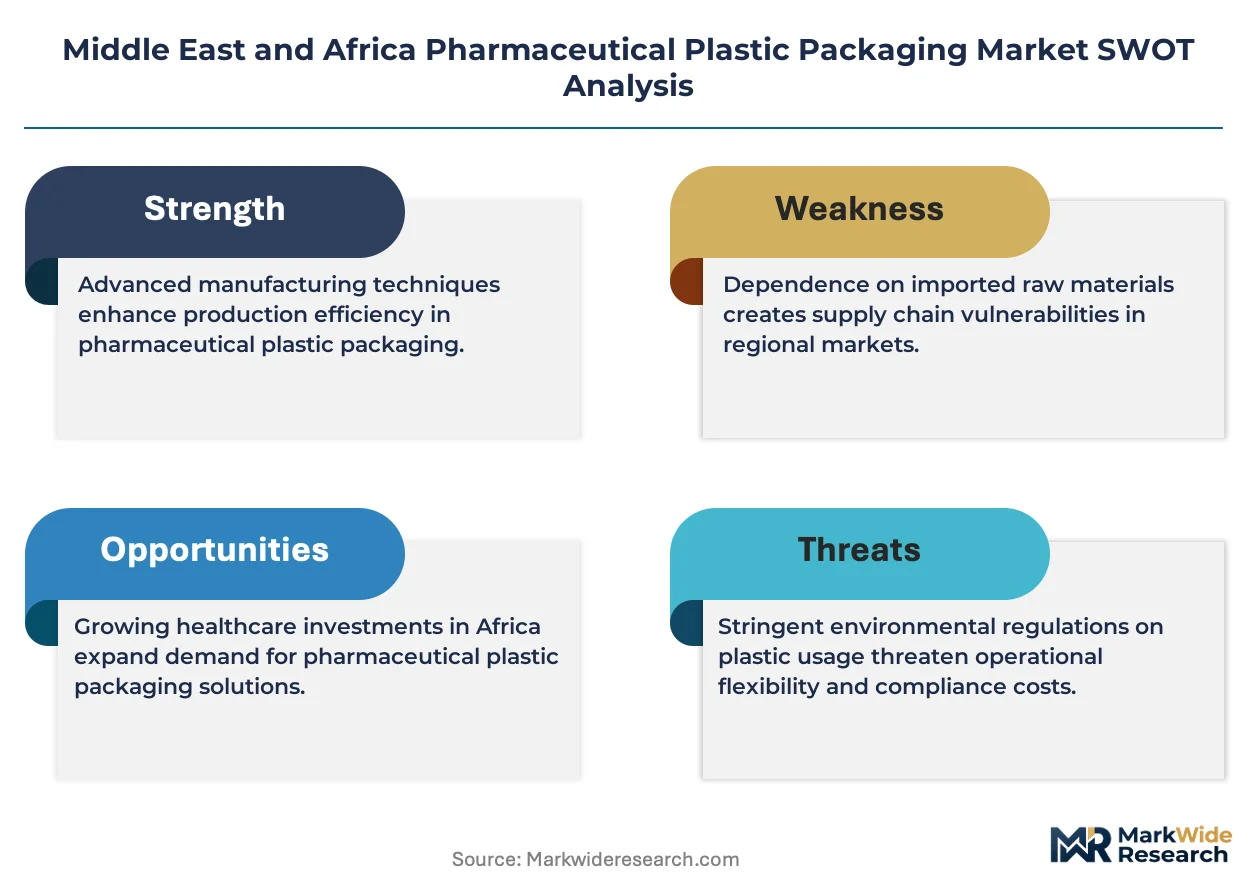
Pharmaceutical plastic packaging encompasses polymer-based primary and secondary containment systems engineered to protect drug stability, with specifications including oxygen transmission rates below 0.1 cc per square meter per day for high-barrier applications and compliance with USP Class VI biocompatibility protocols. Bottles remain the largest product category by volume, though blister packs are gaining share as unit-dose compliance packaging expands across chronic disease therapies. Polypropylene leads material selection for parenteral applications due to its thermal stability and autoclave compatibility, while PET is displacing PVC in oral solid dosage formats as regulatory scrutiny of plasticizers intensifies.
South Africa's SAHPRA, Saudi Arabia's SFDA, and Nigeria's NAFDAC collectively enforce serialization mandates and stability-testing protocols that elevate packaging specification thresholds across the region. The EU MDR and F-Gas Regulation exert extraterritorial influence through supply chain requirements for exporters serving European-registered drug owners. Stakeholders must monitor harmonization gaps between national pharmacopeia standards and WHO prequalification criteria as local manufacturing incentives reshape sourcing geography.
Market Dynamics
Injectable drug delivery systems are redrawing capacity requirements across Middle East and Africa pharmaceutical plastic packaging, as hospital networks upgrade to multi-chamber vials and pre-filled syringes that demand oxygen transmission rates below 0.1 cc per square meter per day.
Growth Catalysts
- SFDA serialization mandates:Saudi Arabia's drug traceability requirements are accelerating investment in tamper-evident closure systems and machine-readable packaging substrates.
- Local production incentives:Nigeria's pharmaceutical manufacturing corridor between Lagos and Abuja is concentrating demand for barrier-coated polypropylene containers as import substitution policies expand.
- WHO prequalification alignment:South Africa's SAHPRA adoption of international stability-testing protocols is elevating specification thresholds for primary packaging across the region.
Market Restraints
- Ethylene feedstock volatility:Gulf petrochemical supply concentration exposes converters to naphtha price swings that compress margin buffers on multi-layer extrusion runs.
- Barrier-coating equipment scarcity:Plasma-enhanced chemical vapor deposition systems remain concentrated among a limited supplier base in Europe and East Asia.
- PVC regulatory friction:Intensifying scrutiny of plasticizer migration is forcing premature line changeovers for oral solid dosage packagers.
Strategic Opportunities
- Cold-chain expansion:Egypt's vaccine manufacturing scale-up is creating demand for insulated pharmaceutical shippers with validated thermal profiles.
- Unit-dose compliance packaging:Blister pack penetration is deepening across chronic disease therapies as patient adherence programs multiply.
- EU MDR extraterritorial pull:Exporters serving European-registered drug owners must upgrade to F-Gas-compliant barrier films, creating specification premiums for compliant regional suppliers.
Industry Challenges
- Polymer characterization expertise gap:Regional laboratories lack capacity for USP Class VI biocompatibility validation, extending certification timelines.
- Autoclave-compatible resin sourcing:Medical-grade polypropylene with validated thermal stability requires long-lead procurement from certified polymer compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmaceutical Plastic Packaging Market |
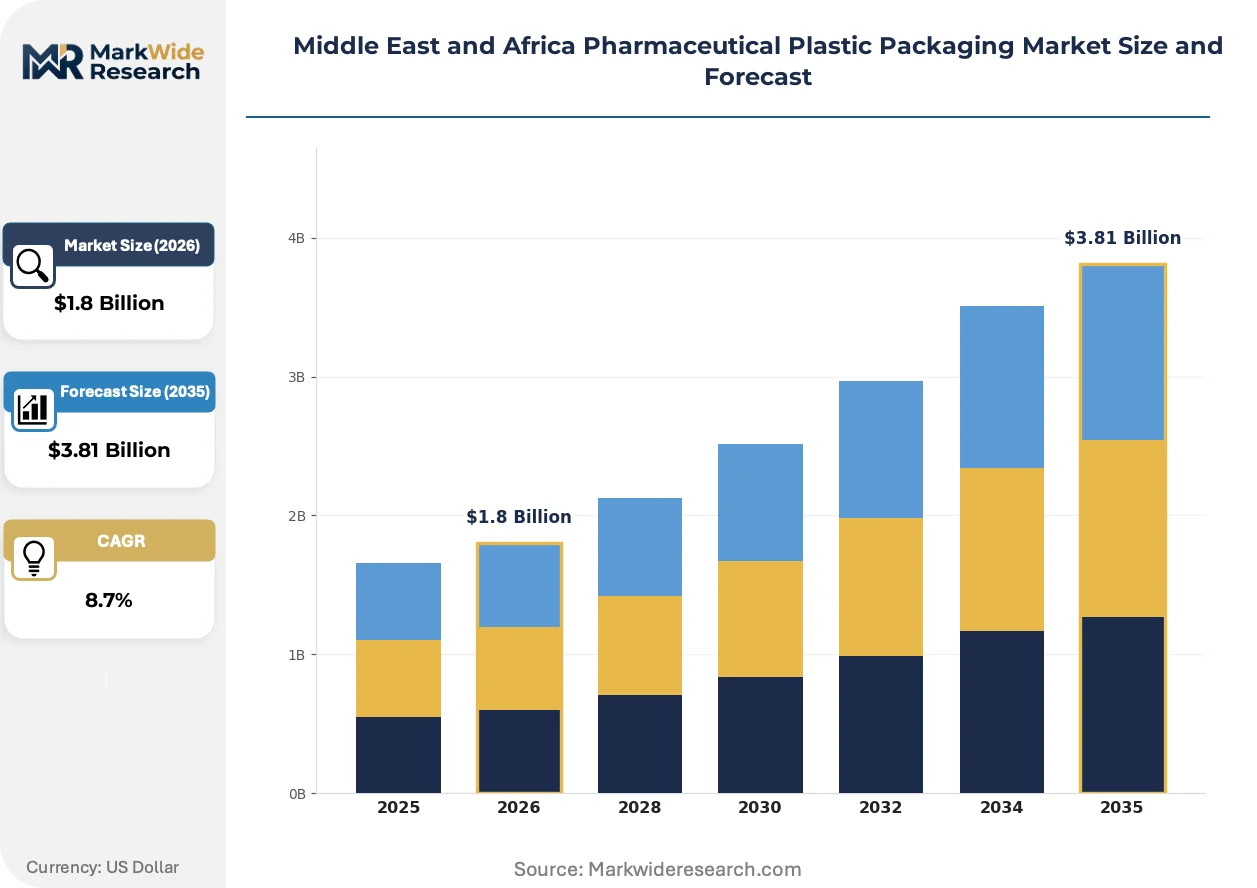
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blisters, Jars, Pouches Material: Polyethylene, Polypropylene, Polyvinyl Chloride, PET End User: Pharmaceutical Companies, Contract Manufacturers, Research Laboratories, Wholesalers Packaging Type: Rigid Packaging, Flexible Packaging, Specialty Packaging, Sustainable Packaging |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., ALPLA Werke Alwin Lehner GmbH & Co KG, Gil Plastic Products Ltd, AptarGroup Inc, Plastipak Holdings, Inc., Alpack Plastics, Drug Plastics Group, Gulf Packaging Industries Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmaceutical Plastic Packaging Market Trends and Innovations
Multi-layer co-extrusion is compressing legacy single-material formats while regulatory harmonization pressures and hospital procurement consolidation are rewriting competitive requirements across the value chain.
Cyclic olefin polymer is decomposing conventional glass vial demand in parenteral applications. Saudi hospital networks are adopting COP syringes for biologic delivery at accelerating pace. This substitution is decomposing the traditional glass-to-plastic cost hierarchy and enabling regional molders to capture contracts previously held by European glass converters.
SAHPRA's alignment with WHO prequalification standards is tightening barrier-property documentation requirements for primary packaging. Drug owners must now submit oxygen transmission and moisture vapor transmission data across accelerated aging protocols. South African contract manufacturers are responding by qualifying alternate suppliers with existing stability-testing dossiers.
Hospital group purchasing organizations are consolidating pharmaceutical packaging procurement across Egypt, Saudi Arabia, and UAE networks. Volume concentration is compressing supplier margins while favoring converters with dedicated regulatory affairs teams capable of managing multi-jurisdiction dossier submissions. This concentration is most visible in Cairo and Riyadh where health system mergers have created single-source tender opportunities exceeding prior annual volumes.
Middle East and Africa Pharmaceutical Plastic Packaging Market Segmentation
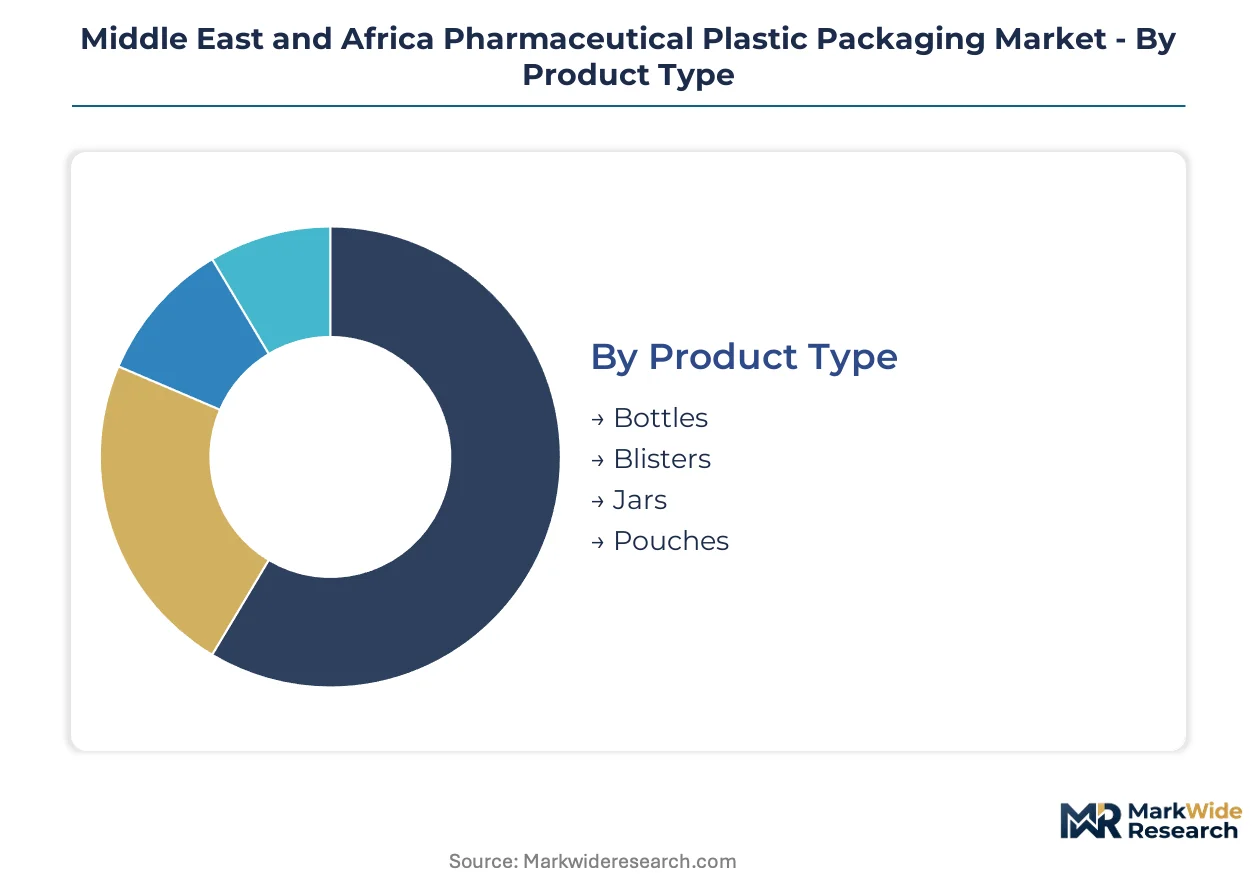
Segmentation in Middle East and Africa pharmaceutical plastic packaging reveals how regulatory divergence and hospital procurement consolidation concentrate demand across specific formats. Understanding these splits exposes where specification premiums emerge versus where commodity competition dominates.
Product Type:
Domestic manufacturing in Nigeria and Egypt drives demand for bottles and jars, while export-oriented production in South Africa and Saudi Arabia tilts toward blisters and pouches serving European-registered drug owners.
- Bottles:HDPE and PET containers dominate oral liquid and solid dosage containment across hospital formularies. Demand clusters in Egypt's vaccine manufacturing scale-up and Nigeria's Lagos-Abuja corridor, where local production incentives favor large-volume formats.
- Blisters:Unit-dose PVC and Aclar laminates serve chronic disease adherence programs. South African contract manufacturers are expanding cold-form foil capacity to meet EU MDR serialization requirements for export markets.
- Jars:Wide-mouth polypropylene containers secure ointments and creams. Procurement concentrates through Saudi hospital group purchasing organizations consolidating dermatology and topical therapy packaging.
- Pouches:Multi-layer films deliver IV solutions and enteral nutrition. SFDA barrier-property documentation mandates are elevating specification thresholds for parenteral flexible formats.
Bottles command the established base. The steepest expansion runs through blisters.
Material:
Cost tier stratification separates medical-grade certified resins from commodity polymer streams, with autoclave-compatible grades commanding procurement premiums.
- Polyethylene:HDPE bottles and closures serve oral solid dosage across price-sensitive African markets. Nigerian converters favor blow-molded PE for its feedstock proximity to Gulf petrochemical supply.
- Polypropylene:Thermal stability and autoclave compatibility position PP for parenteral vials and syringes. SAHPRA's WHO prequalification alignment is tightening biocompatibility validation requirements for medical-grade grades.
- Polyvinyl Chloride:Blister base films face intensifying plasticizer scrutiny. Egyptian packagers are executing premature line changeovers to PET-G and Aclar alternatives ahead of anticipated SFDA restrictions.
- PET:Displacing PVC in oral solid dosage formats due to regulatory pressure on plasticizers. Amorphous PET-G variants are penetrating high-barrier blister applications previously reserved for PVC-PVDC laminates.
Polyethylene anchors volume throughput. PET is climbing the fastest as regulatory friction erodes PVC's historical position.
End User:
Customer type determines specification intensity, with multinational drug makers demanding stability-testing dossiers that regional wholesalers rarely require.
- Pharmaceutical Companies:Multinational drug makers operating in Egypt and Saudi Arabia specify oxygen transmission rates below 0.1 cc per square meter per day. These buyers require dedicated regulatory affairs support for multi-jurisdiction dossier submissions.
- Contract Manufacturers:South African and Egyptian CMOs are qualifying alternate suppliers with existing stability-testing dossiers to meet SAHPRA's tightened barrier-property documentation requirements.
- Research Laboratories:Clinical trial packaging demands serialization-ready formats with tamper-evident features. Procurement volumes remain fragmented across investigator-initiated studies.
- Wholesalers:Distribution intermediaries in Nigeria and Kenya prioritize cost-optimized standard bottles and jars. These buyers rarely specify barrier coatings or accelerated aging protocols.
Pharmaceutical companies concentrate the premium tier. Contract manufacturers are expanding most quickly as local production incentives deepen outsourcing relationships.
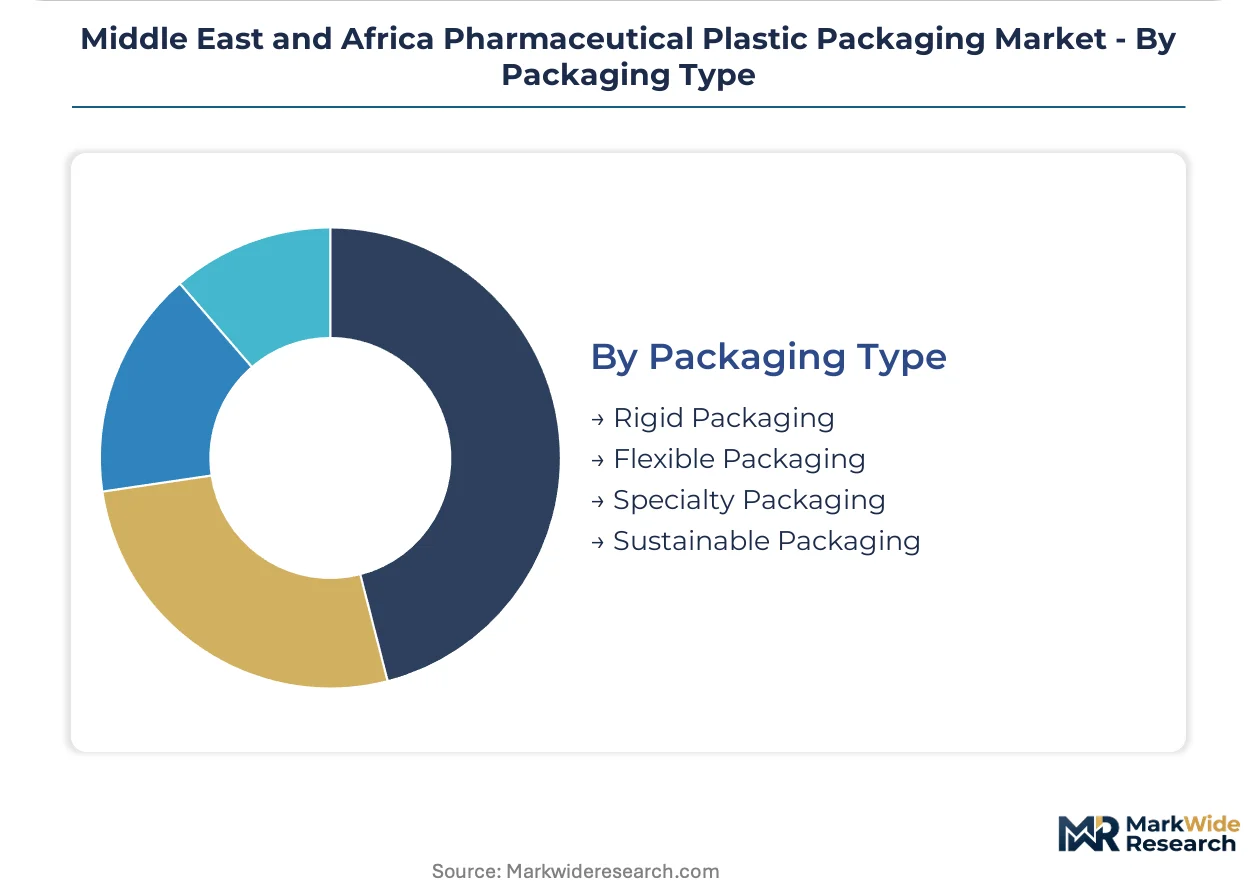
Packaging Type:
Supply concentration differs sharply between rigid formats dominated by regional molders and specialty barriers requiring imported coating equipment.
- Rigid Packaging:Bottles, vials, and jars produced via injection and blow molding. Gulf Packaging Industries Limited anchors local distribution channels across GCC states for these formats.
- Flexible Packaging:Pouches, sachets, and strip packs serving unit-dose compliance programs. Plasma-enhanced chemical vapor deposition scarcity limits regional high-barrier film production.
- Specialty Packaging:Pre-filled syringes, multi-chamber vials, and COP containers for biologic delivery. Saudi hospital networks are adopting COP syringes at accelerating pace, decomposing traditional glass demand.
- Sustainable Packaging:Recycled content and mono-material formats for EU MDR F-Gas compliance. Exporters serving European-registered drug owners must upgrade to compliant barrier films, creating specification premiums.
Rigid packaging holds the volume base. Specialty packaging is gaining share fastest as hospital networks upgrade to biologic-compatible delivery systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply between Gulf states prioritizing high-barrier formats for biologics and African markets optimizing for cost-efficient oral solid dosage containment. This divergence shapes resin selection, equipment investment, and regulatory compliance priorities across the region.
Saudi Arabia
Pre-filled syringe demand from hospital networks is accelerating cyclic olefin polymer adoption for biologic delivery. SFDA serialization mandates require tamper-evident closure systems and machine-readable substrates by 2025. Riyadh's health system mergers have created single-source tender opportunities exceeding prior annual procurement volumes.
South Africa
Contract manufacturers are expanding cold-form foil capacity to serve EU MDR serialization requirements for export markets. SAHPRA alignment with WHO prequalification standards tightens barrier-property documentation for oxygen and moisture vapor transmission data. The Gauteng- KwaZulu-Natal manufacturing belt is qualifying alternate suppliers with existing stability-testing dossiers.
Egypt
Vaccine manufacturing scale-up is creating demand for insulated pharmaceutical shippers with validated thermal profiles. Local production incentives favor large-volume HDPE and PET bottle formats for domestic oral liquid containment. Cairo's pharmaceutical cluster is consolidating procurement through hospital group purchasing organizations.
Nigeria
Import substitution policies are concentrating demand for barrier-coated polypropylene containers in the Lagos-Abuja manufacturing corridor. Price-sensitive procurement prioritizes blow-molded PE formats leveraging Gulf petrochemical feedstock proximity. The national pharmaceutical regulator enforces stability-testing protocols that elevate specification thresholds for primary packaging.
United Arab Emirates
Distribution hub status positions Dubai as a consolidation point for multi-jurisdiction dossier submissions serving MENA markets. MOHAP pharmaceutical regulations harmonize with Gulf Cooperation Council technical standards. Jebel Ali free zone logistics infrastructure supports cold-chain pharmaceutical packaging transit to African and South Asian destinations.
Middle East and Africa Pharmaceutical Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa pharmaceutical plastic packaging market. Multi-layer extrusion infrastructure and barrier-coating capabilities separate the upper tier from commodity converters serving price-sensitive African markets. Three archetypes dominate: Gulf-based rigid container specialists, European multinationals with regional extrusion assets, and local distributors anchoring GCC supply channels. Competitive moves center on qualifying alternate resin suppliers and securing hospital group purchasing organization contracts.
Within the multinational tier, Amcor Group GmbH and Berry Global Inc. exemplify scale-driven positioning through regional infrastructure deployment. Amcor leverages multi-layer extrusion capabilities to anchor supply relationships with drug makers operating in Egypt and Saudi Arabia. Berry sustains competitiveness through rigid container specialization aligned with hospital formulary requirements. Gulf Packaging Industries Limited represents the regional distribution archetype, controlling local channels across GCC states through logistics proximity and regulatory affairs support.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Gil Plastic Products Ltd |
| AptarGroup Inc |
| Plastipak Holdings, Inc. |
| Alpack Plastics |
| Drug Plastics Group |
| Gulf Packaging Industries Limited |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day resin lead times for medical-grade polypropylene compounders compress margin buffers when Gulf petrochemical feedstock volatility spikes, concentrating pricing power with converters holding long-term offtake agreements with certified polymer suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational drug makers and regional converters, though spot purchasing persists for commodity HDPE bottles serving Nigerian wholesalers. Price differentiation rests on USP Class VI certification tier and autoclave-validation documentation, with medical-grade PP commanding premiums over standard pharmaceutical grades. Cost compression in oral solid dosage formats intensifies as Egyptian packagers execute premature PVC-to-PET line changeovers ahead of anticipated SFDA restrictions. Hospital group purchasing organizations in Riyadh and Cairo exhibit lowest price sensitivity, while Kenyan and Nigerian distribution intermediaries prioritize economy-tier formats.
Supply Chain Analysis
Strategic stockpiling of barrier-coated films characterizes Saudi and South African converter procurement, whereas Egyptian and Nigerian operators favor just-in-time resin flows to minimize working capital exposure. Feedstock concentration in Saudi Arabia, UAE, and Qatar exposes regional molders to naphtha price swings that ripple through multi-layer extrusion economics. Raw material dependencies center on Gulf-sourced polyethylene, imported cyclic olefin polymer, and European-supplied plasma-enhanced chemical vapor deposition equipment. Single-source vulnerability for high-barrier coating systems creates chokepoint risk. Distribution runs through Jebel Ali free zone consolidation points serving MENA hospital networks and African distribution corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory dossier management and stability-testing services are expanding faster than base packaging hardware as SAHPRA and SFDA documentation requirements deepen outsourcing demand.
For Market Incumbents: Secure multi-year hospital group purchasing organization contracts in Riyadh and Cairo before health system merger waves consolidate procurement further. Invest in captive barrier-coating capabilities to offset European equipment supplier concentration risk. Backward integration into medical-grade PP compounding defends margin position against Gulf petrochemical price volatility. For New Entrants and Emerging Players: Lead with cold-chain insulated shipper formats targeting Egypt's vaccine manufacturing scale-up, the most penetrable white-space segment. Qualify alternate suppliers with existing WHO prequalification dossiers to bypass South Africa's polymer characterization expertise gap. Pursue toll-manufacturing partnerships with established GCC distributors to bypass channel control barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from European multinational packaging parents seeking to monetize non-core Middle East extrusion assets amid portfolio rationalization. Five-to-ten-year viability hinges on regulatory affairs capabilities rather than commodity molding scale. Monitor SFDA serialization mandate enforcement rigor as inflection indicator for tamper-evident closure system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating Equipment Acquisition | Captive PECVD capacity eliminates European supplier chokepoint for Saudi hospital network contracts. |
| USP Class VI Certification Investment | Biocompatibility validation unlocks multinational drug maker supply relationships in Egypt and Saudi Arabia. |
| Cold-Chain Logistics Partnership | Validated thermal profile capabilities capture Egypt vaccine manufacturing packaging demand. |
| Multi-Jurisdiction Dossier Service Launch | Regulatory affairs support commands premium pricing from hospital GPOs across Cairo and Riyadh. |
| Cyclic Olefin Polymer Molding Scale-Up | COP syringe production displaces glass converter contracts in Saudi biologic delivery networks. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical packaging procurement managers, regulatory affairs directors at multinational drug makers, hospital GPO contract specialists, and polymer compounder technical sales leads, then refined against secondary validation from FDA packaging guidance documents, EMA quality dossier requirements, SFDA serialization directives, and WHO prequalification stability-testing protocols. Bottom-up volume estimates from converter capacity utilization and top-down demand projections from pharmaceutical manufacturing expansion plans were triangulated to reconcile variance.
Variance decomposition across the projection horizon isolates volume drivers by product format, material grade tier, end-user customer type, and national regulatory cluster. CAGRs were derived from segment-level growth rate distributions anchored to pharmaceutical production expansion trajectories and packaging specification upgrade cycles. Modeled inputs include oxygen transmission rate threshold compliance costs and autoclave-compatible resin availability timelines.
Forecasts assume regulatory continuity in Saudi SFDA serialization mandates and South African SAHPRA WHO alignment; material policy shifts would require re-modeling specification threshold trajectories and certification timeline assumptions. Revision becomes warranted when Gulf petrochemical feedstock price volatility crosses thresholds that trigger converter margin compression responses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market