
 Canada Sachet Packaging Market | 2026-2036
Canada Sachet Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Sachet Packaging Market Insights
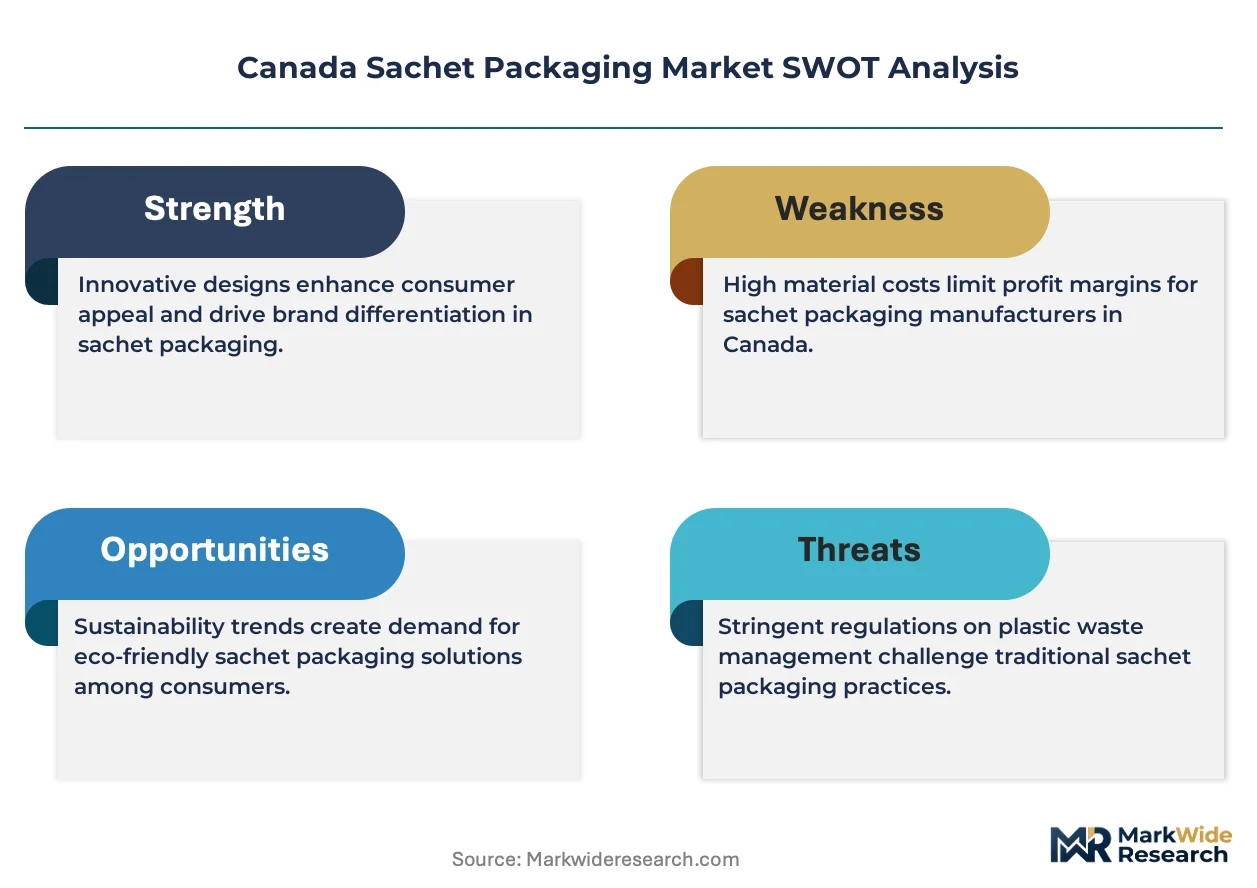
Premium-grade barrier specifications is unwinding legacy commodity positioning across the Canada sachet packaging landscape. Winpak Ltd leverages its Winnipeg manufacturing base to dominate high-barrier protein and dairy sachet supply. Amcor Group GmbH anchors North American flexible R&D through its Canadian technical center. Berry Global Inc specializes in healthcare-compliant unit-dose formats for pharmaceutical clients.
Sachet packaging denotes small-format sealed pouches, typically constructed from multi-layer laminates measuring 50–150 microns total thickness, engineered for moisture, oxygen, and light barrier protection of single-use product quantities. The format serves primary containment and portion-control functions across food service, travel retail, and clinical trial supply chains. Food and beverage product types occupy the largest volume share, though pharmaceutical applications command superior unit margins due to validation and serialization requirements. Biodegradable material grades represent the fastest-expanding segment, constrained currently by limited domestic composting infrastructure and Health Canada migration testing protocols.
Health Canada sets primary safety standards for food-contact materials under the Food and Drugs Act, while the Canadian Food Inspection Agency enforces label integrity and net quantity verification. The Canadian Standards Association certifies packaging machinery electrical and operational safety, shaping capital equipment procurement criteria. Stakeholders must monitor evolving extended producer responsibility provincial implementations and compostability certification harmonization between BNQ and BPI standards to secure long-term material qualification pathways.
Market Dynamics
Extended producer responsibility frameworks are forcing material requalification across Ontario and Quebec manufacturing corridors, compressing legacy polyolefin supply chains while opening certification pathways for compostable laminates.
Growth Catalysts
- Quick-service restaurant single-serve adoption:Institutional food service channels in Ontario's Golden Horseshoe are standardizing portion-control sachets for condiments and sauces, driving laminate volume requirements.
- Health Canada migration testing protocols:Updated safety requirements for food-contact materials are accelerating validation investments by domestic converters seeking pharmaceutical-grade barrier qualifications.
- Biodegradable material R&D clusters:Montreal's flexible packaging research infrastructure is advancing PLA and PHA laminate structures with improved heat-seal performance for hot-fill applications.
Market Restraints
- Domestic composting infrastructure gaps:Limited industrial composting facility coverage in Prairie provinces restricts commercialization of certified biodegradable sachet grades despite material availability.
- Multi-layer laminate recycling complexity:Current mechanical recycling streams cannot process typical 5-7 layer barrier structures, creating end-of-life liability under provincial extended producer responsibility programs.
- Aluminum foil price volatility:High-barrier specifications dependent on metallized layers face input cost instability from primary aluminum supply concentration.
Strategic Opportunities
- Atlantic Canada underpenetration:Nova Scotia and New Brunswick food processing corridors lack dedicated high-barrier sachet converting capacity, creating regional supply gaps for seafood and agricultural exporters.
- Healthcare unit-dose serialization mandates:Pharmaceutical traceability requirements are expanding demand for individually coded sachet formats in clinical trial and hospital pharmacy distribution.
- BNQ-BPI compostability certification harmonization:Alignment between Quebec's Bureau de normalisation du Québec and North American BPI standards would streamline material qualification for cross-border CPG brands.
Industry Challenges
- Barrier engineer talent scarcity:Specialized expertise in coextrusion die design and oxygen transmission rate optimization is concentrated among retiring professionals in Quebec's legacy packaging workforce.
- Validation timeline compression:Health Canada stability testing protocols for pharmaceutical sachet formats extend commercialization cycles, requiring parallel-track regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Sachet Packaging Market |
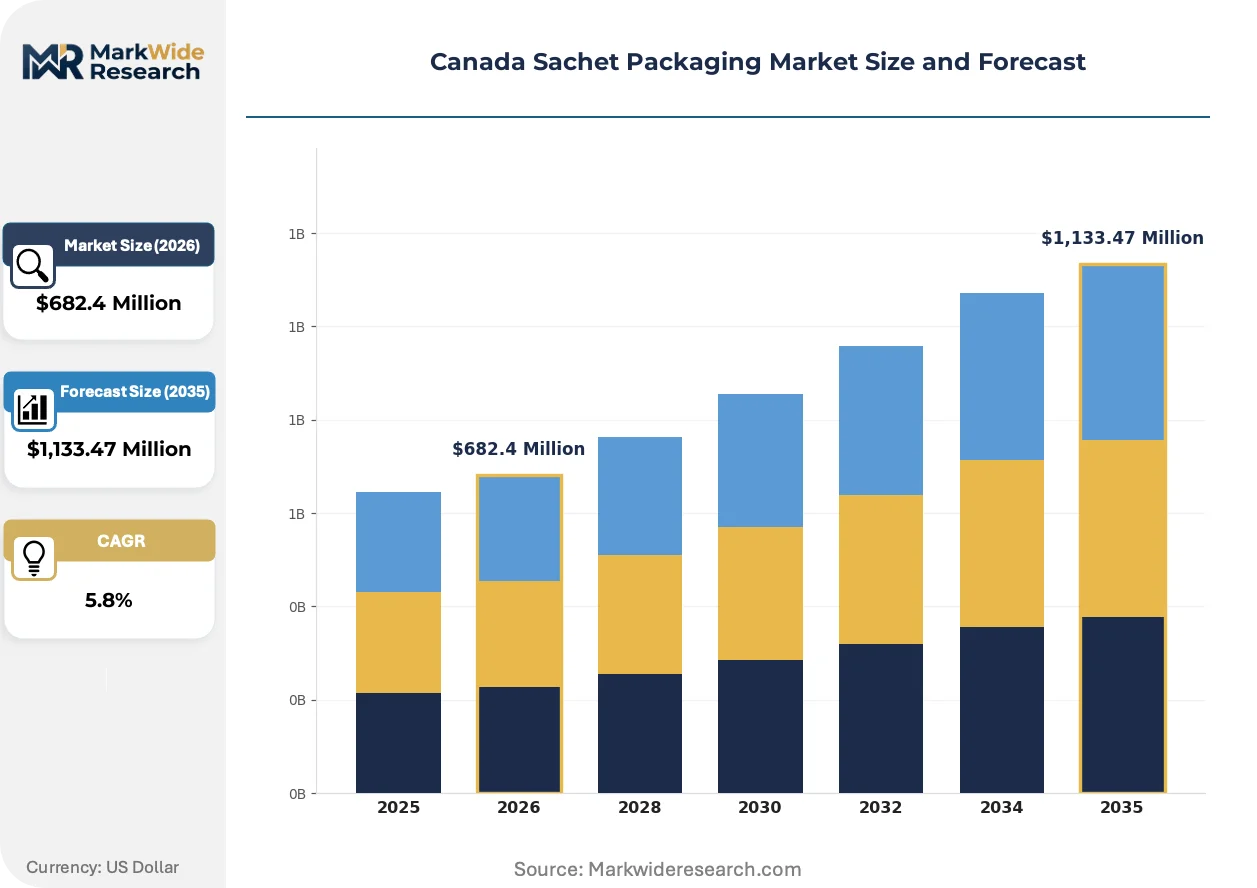
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,133.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverages, Pharmaceuticals, Personal Care Material: Plastic, Paper, Aluminum, Biodegradable Size: Single Serve, Multi-Serve, Sample Size, Bulk Packaging End User: Retail, E-Commerce, Food Service, Hospitality |
| Companies Covered | Amcor Group GmbH, Winpak Ltd, Berry Global Inc, Huhtamaki Oyj, Sonoco Products Company, TC Transcontinental, Mondi Group, Transcontinental Inc, Constantia Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Sachet Packaging Market Trends and Innovations
Material science advances and regulatory stringency are converging to redefine performance benchmarks across Canada's sachet converting base, with sustainability credentials becoming inseparable from technical specifications.
High-barrier bio-based films incorporating cellulose nanocrystal layers are displacing conventional metallized PET structures in premium food applications. Specialty coffee roasters and craft condiment producers in British Columbia are specifying these laminates for extended shelf-life claims. The transition is compressing margin structures for commodity converters while rewarding integrated material science capabilities.
The Canadian Council of Ministers of the Environment's harmonized extended producer responsibility framework is mandating recycled content minimums and standardized labeling requirements. This policy architecture is reshaping capital allocation decisions among Ontario-based flexible packaging groups. Pharmaceutical and food safety segments are responding with segregated production lines to prevent cross-contamination from recycled feedstocks.
Direct-to-manufacturer procurement models are consolidating buyer power among national CPG brands, compressing distributor margins in traditional supply channels. Western Canada's natural products sector is pioneering this shift, negotiating laminate specifications directly with Montreal-area converters. The pattern is most pronounced in organic certification-driven categories where material provenance documentation requirements exceed distributor capabilities.
Canada Sachet Packaging Market Segmentation
Sachet packaging demand fragments across four intersecting dimensions that determine laminate specifications, barrier requirements, and channel economics. Understanding these segment boundaries clarifies where converter investments concentrate and where margin compression threatens legacy positioning.
Product Type:
Channel routing varies sharply by product category, with food service procurement dominating condiment and sauce formats while pharmaceutical serialization mandates reshape healthcare distribution.
- Food:Multi-layer laminates with oxygen transmission rates below 0.1 cc/m²/day protect shelf-stable condiments, gravies, and seasoning blends. Quick-service restaurants in Ontario's Golden Horseshoe standardize these formats for portion control, though Health Canada migration testing protocols extend qualification timelines for new laminate structures.
- Beverages:Hot-fill compatible coextrusions with modified atmosphere barrier properties serve instant coffee, drink mixes, and liquid concentrates. Montreal-area converters specialize in these structures, leveraging proximity to flavor houses and beverage formulation labs.
- Pharmaceuticals:Unit-dose formats with individual serialization codes meet hospital pharmacy and clinical trial traceability requirements.
- Personal Care:Single-use shampoo, lotion, and cosmetic samples target travel retail and hospitality amenity programs.
Food dominates installed base. Pharmaceuticals is where expansion concentrates.
Material:
Cost tiers separate commodity polyolefin supply from certified biodegradable alternatives commanding 40-60% premiums.
- Plastic:Polyethylene and polypropylene coextrusions with ethylene vinyl alcohol interlayers provide moisture and oxygen barrier protection at lowest unit cost. These structures face recycling complexity under extended producer responsibility frameworks, creating end-of-life liability for brand owners.
- Paper:Fiber-based substrates with polymer barrier coatings serve dry food and cosmetic applications where grease resistance matters. British Columbia specialty roasters specify these for premium positioning, though heat-seal performance lags plastic alternatives.
- Aluminum:Metallized PET and pure foil laminates deliver ultra-high barrier for pharmaceutical and sensitive food applications.
- Biodegradable:PLA and PHA grades with improved heat-seal performance are climbing the fastest, constrained by Prairie province composting infrastructure gaps.
Plastic holds volume leadership. Biodegradable grades capture strategic investment.
Size:
Application context determines format selection, with food service procurement favoring single-serve while e-commerce sampling drives sample size specifications.
- Single Serve:5-20 milliliter pouches for condiments, sauces, and pharmaceuticals dominate quick-service restaurant and hospital pharmacy channels. These formats maximize line efficiency through high-speed form-fill-seal equipment running 600+ units per minute.
- Multi-Serve:Larger pouches for family-size condiments and institutional food service balance portion control with operational efficiency.
- Sample Size:Trial formats for cosmetics and nutraceuticals target direct-to-consumer e-commerce subscription models.
- Bulk Packaging:Industrial-size formats for food manufacturing and pharmaceutical compounding supply.
Single serve commands production capacity. Sample size is gaining share fastest.
End User:
Customer type dictates specification complexity, with retail and food service representing opposite poles of barrier requirement and documentation burden.
- Retail:Consumer-facing formats with extended shelf-life claims require high-barrier specifications and prominent labeling space. Atlantic Canada seafood exporters lack dedicated converting capacity, creating supply gaps for this channel.
- E-Commerce:Direct-to-consumer shipment demands puncture-resistant structures and compact cube efficiency for last-mile economics.
- Food Service:Institutional procurement prioritizes cost minimization and portion standardization over maximum barrier performance.
- Hospitality:Amenity programs for hotels and airlines favor premium aesthetic finishes with minimal unit volumes.
Food service drives laminate tonnage. E-commerce is where specification innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity concentrates in Ontario and Quebec, where extended producer responsibility mandates are forcing material requalification across legacy supply chains. Prairie provinces and Atlantic Canada present contrasting demand profiles shaped by infrastructure gaps and export-oriented food processing.
Ontario
Quick-service restaurant procurement drives laminate demand through the Golden Horseshoe manufacturing corridor. Health Canada's migration testing protocols extend qualification timelines for new food-contact structures. Toronto-area converters are segregating production lines to prevent cross-contamination from recycled feedstocks mandated by provincial extended producer responsibility frameworks.
Quebec
Montreal's flexible packaging cluster anchors North American R&D for PLA and PHA heat-seal improvements. The Bureau de normalisation du Québec certification requirements shape compostable material development pathways. Laval and Longueuil converters supply pharmaceutical-grade barrier specifications to hospital pharmacy networks across the province.
British Columbia
Specialty coffee roasters and craft condiment producers specify cellulose nanocrystal laminates for premium shelf-life positioning. Limited industrial composting infrastructure constrains commercialization of certified biodegradable grades despite material availability. Vancouver-area natural products brands negotiate direct-to-manufacturer procurement with Montreal-area converters.
Prairie Provinces
Agricultural commodity processing generates bulk sachet demand for seasoning and ingredient supply to food manufacturers. Domestic composting facility coverage gaps restrict adoption of biodegradable packaging alternatives. Winnipeg-based Winpak Ltd leverages its manufacturing base to serve protein and dairy sachet requirements across Manitoba and Saskatchewan.
Atlantic Canada
Seafood and agricultural exporters lack dedicated high-barrier converting capacity for retail-facing formats. Nova Scotia and New Brunswick food processing corridors source sachet supply from distant Ontario and Quebec converters. Regional supply gaps create logistics cost premiums for portion-control packaging of value-added marine products.
Canada Sachet Packaging Market Competitive Landscape
Concentration sits with integrated flexible packaging groups possessing captive material science capabilities and pharmaceutical validation expertise. The competitive terrain separates high-barrier specialists serving regulated healthcare segments from commodity converters facing margin compression under extended producer responsibility liabilities. Three archetypes dominate: vertically integrated multinational film producers, regional converters with deep customer relationships in food service channels, and niche players specializing in biodegradable laminate structures. Capacity expansion and portfolio diversification toward certified compostable grades represent the dominant competitive moves as provincial regulations tighten.
Within the integrated multinational tier, Amcor Group GmbH and Berry Global Inc exemplify archetypes with North American technical infrastructure and healthcare compliance capabilities. Winpak Ltd occupies a position as a Canada-domiciled converter with concentrated manufacturing presence in Winnipeg. These three anchors illustrate how geographic proximity to Ontario and Quebec demand clusters combines with regulatory qualification depth to structure competitive positioning in this market.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Winpak Ltd |
| Berry Global Inc |
| Huhtamaki Oyj |
| Sonoco Products Company |
| TC Transcontinental |
| Mondi Group |
| Transcontinental Inc |
| Constantia Flexibles |
| Others |
Pricing and Supply Chain Analysis
Cellulose nanocrystal laminate adoption by British Columbia specialty roasters simultaneously redistributes converter procurement power toward Montreal-area material science clusters and compresses margin structures for legacy metallized PET suppliers in Ontario's Golden Horseshoe. This substitution dynamic concentrates pricing leverage among integrated converters with captive R&D infrastructure while fragmenting commodity converter positioning.
Pricing Analysis
Health Canada's migration testing protocols dictate the pricing tier structure across food-contact and pharmaceutical-grade sachet specifications. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical barriers from food-service commodity laminates and certified biodegradable grades. Cost compression in standard polyolefin tiers is intensifying because extended producer responsibility liabilities now embed end-of-life fees into converter quotes. Food service procurement teams exhibit highest price sensitivity, while pharmaceutical serialization mandates render healthcare buyers relatively inelastic.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement for aluminum foil and EVOH interlayers, whereas just-in-time inventory management governs finished sachet logistics to quick-service restaurant distribution centers. Domestic supply concentrates in Ontario and Quebec, with critical metallized film inputs drawing from US and German specialty substrate producers. Single-source vulnerability sits with primary aluminum supply concentration affecting high-barrier specifications. Distribution runs through direct-to-manufacturer procurement channels consolidating buyer power among national CPG brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: Health Canada validation timelines and provincial extended producer responsibility compliance create switching costs that protect qualified incumbents from rapid displacement.
For Market Incumbents: Secure pharmaceutical-grade barrier qualifications through parallel-track Health Canada submissions before serialization mandates expand to clinical trial supply. Extend backward integration into PLA and PHA resin supply through partnership with Montreal-area biopolymer R&D clusters to preempt biodegradable material scarcity.
For New Entrants and Emerging Players: Atlantic Canada seafood exporter supply gaps represent the most penetrable white-space target, as Nova Scotia and New Brunswick food processing corridors currently source high-barrier retail formats from distant Ontario converters. A regional converting facility with dedicated seafood moisture-barrier specifications would capture logistics cost premiums currently embedded in cross-provincial supply chains.
For Investors and Strategic Acquirers: The market sits at a regulatory-escalation phase that favors converters with pre-qualified pharmaceutical infrastructure and integrated material science capabilities. Target acquisition archetypes include Quebec-based flexible packaging specialists with Bureau de normalisation du Québec compostability certification pathways and existing hospital pharmacy network relationships. Watch for BNQ-BPI harmonization announcements as inflection indicators for cross-border CPG brand procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Certification Investment | Bureau de normalisation du Québec pathway secures Quebec CPG brand procurement preference. |
| Atlantic Canada Converting Capacity Expansion | Nova Scotia facility captures seafood exporter logistics premiums from distant Ontario supply. |
| Pharmaceutical Serialization Line Addition | Health Canada unit-dose mandates expand addressable market into clinical trial distribution. |
| Direct-to-Manufacturer Procurement Partnership | British Columbia natural products brands bypass distributor margins for laminate specification control. |
| Recycled Content Line Segregation | Ontario extended producer responsibility mandates require production isolation to prevent cross-contamination. |
Research Methodology
Cross-validation between primary interviews with flexible packaging plant managers, pharmaceutical procurement leads at hospital pharmacy networks, and quick-service restaurant supply chain directors anchors the qualitative findings. Secondary validation draws from Health Canada Food and Drugs Act guidance documents, Canadian Food Inspection Agency label integrity enforcement records, Canadian Standards Association machinery safety certifications, and provincial extended producer responsibility implementation schedules. Bottom-up laminate demand modeling triangulates against top-down converter capacity assessments across Ontario's Golden Horseshoe and Quebec's Montreal cluster.
Sensitivity analysis across material substitution scenarios and regulatory implementation timelines shapes the analytical framework. Segmentation dimensions modeled include product type, material grade tier, barrier specification level, and end-user channel across the projection horizon. CAGRs derive from laminate volume trajectories indexed to quick-service restaurant expansion, pharmaceutical serialization mandate phase-ins, and biodegradable material adoption curves. Forecast inputs incorporate Health Canada stability testing protocol timelines and provincial composting infrastructure buildout assumptions.
Forecasts assume regulatory continuity in Health Canada migration testing regimes and provincial extended producer responsibility frameworks; material policy shifts would require re-modeling. Specific risks that could revise projections include BNQ-BPI certification harmonization delays, Prairie province industrial composting facility construction failures, and aluminum foil supply disruption from primary smelter concentration. Revision becomes warranted when biodegradable material cost premiums compress below threshold levels enabling mass-market CPG adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sachet Packaging
Sachet and Pouch Handling Systems Market
Sachet Packaging
China Sachet Packaging Market
Sachet Packaging
Germany Sachet Packaging Market
Sachet Packaging
Sanitizer Sachet Market
Sachet Packaging
US Sachet Packaging Market
Sachet Packaging
Full Container Shrink Sleeves Market
Sachet Packaging
Sachet Packaging Machines Market
Sachet Packaging
India Sachet Packaging Market
Sachet Packaging
Japan Sachet Packaging Market
Sachet Packaging
Single Dose Sachet Market
Sachet Packaging
Aluminium Foil Sachet Market
Sachet Packaging
Asia Pacific Sachet Packaging Market
Sachet Packaging
Sachet Packaging Market
Sachet Packaging
Snap Sachets Market
Sachet Packaging
North America Sachet Packaging Market
Sachet Packaging
India Plastic Packaging Market