
 China Pharmaceutical Contract Packaging Market | 2026-2036
China Pharmaceutical Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Pharmaceutical Contract Packaging Market Intelligence
China's eastern seaboard is reconfiguring pharmaceutical packaging capacity through dedicated contract facilities serving domestic and export markets. Catalent Inc leverages integrated development-to-commercialization infrastructure across multiple Chinese sites. Amcor PLC anchors flexible packaging supply for oral solid dose formats with regional manufacturing scale. West Pharmaceutical Services Inc specializes in containment and delivery systems for biologics, competing on technical specification rather than commodity volume.
Pharmaceutical contract packaging encompasses outsourced primary and secondary packaging services performed under formal agreements between drug owners and specialized service providers, encompassing bottle filling, blister lidding, carton assembly, and unit-level serialization for regulatory traceability. The practice eliminates capital-intensive in-house packaging lines while ensuring compliance with evolving quality standards. Blister packaging dominates unit volume for oral medications due to child-resistance and moisture-barrier performance, while serialization technology captures disproportionate investment as NMPA mandates phase in nationwide track-and-trace requirements. Cold forming occupies a premium niche for moisture-sensitive compounds, though heat sealing sustains broader applicability across generic portfolios.
NMPA regulations, cGMP standards, and ISO certification frameworks collectively govern facility qualification, batch documentation, and cross-border shipment eligibility for contract packagers operating in China. Compliance costs favor larger operators with dedicated quality systems over fragmented local competitors. Stakeholders must monitor regulatory harmonization between NMPA and FDA standards as domestic innovators pursue simultaneous global filings.
Market Dynamics
NMPA serialization mandates are compressing packaging timelines while biotech outsourcing demand reshapes capacity allocation across eastern China manufacturing clusters.
Growth Catalysts
- Biotech Outsourcing Surge:Domestic biologics developers are transferring packaging operations to contract specialists as pipeline candidates advance to commercialization, eliminating in-house line investments.
- Track-and-Trace Mandates:NMPA serialization requirements for unit-level traceability are forcing drug owners toward qualified contract packagers with validated aggregation infrastructure.
- Yangtze River Delta Concentration:Shanghai and Jiangsu province pharmaceutical manufacturing density creates natural demand gravity for regional packaging facilities.
Market Restraints
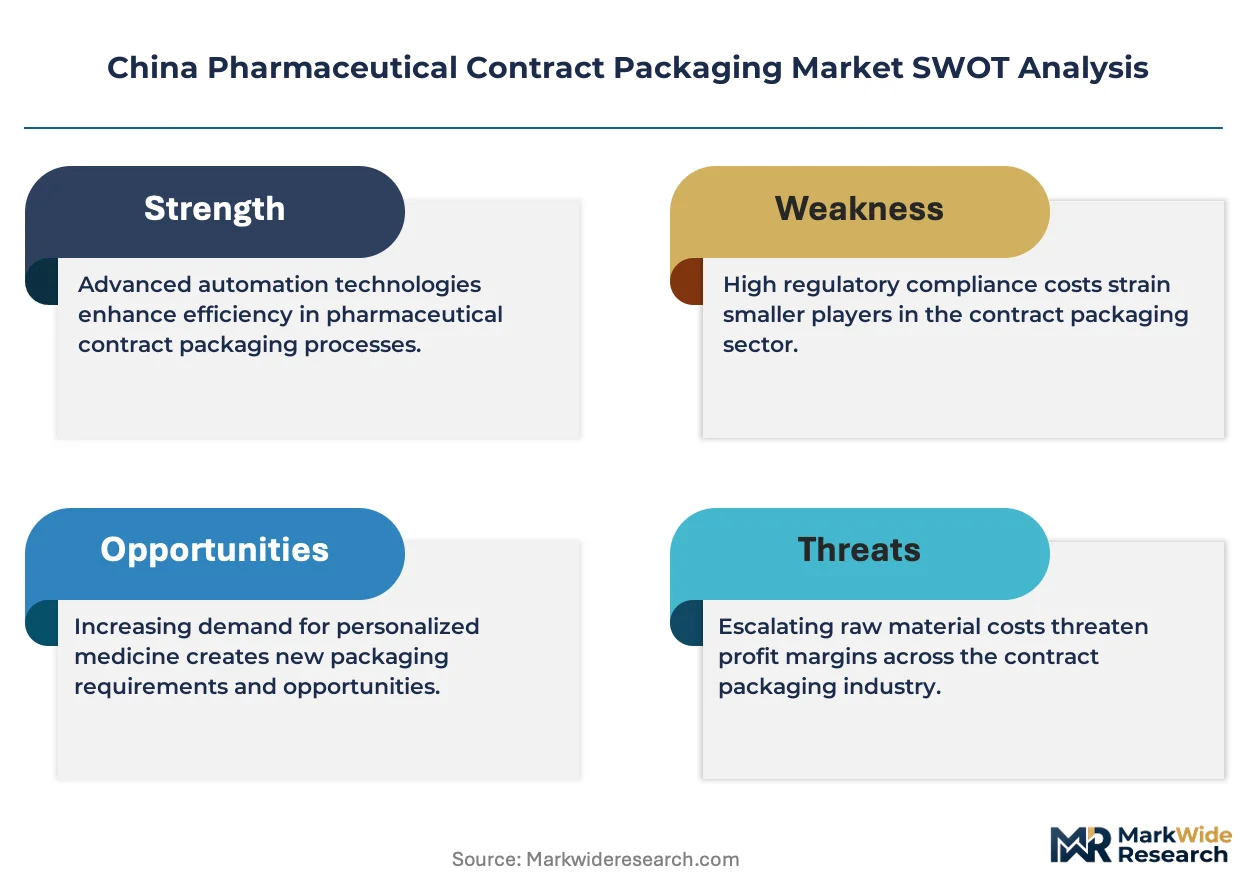
- Aluminum Foil Price Volatility:Cold-form blister substrates depend on aluminum supply chains exposed to energy cost fluctuations and trade flow disruptions.
- Quality System Capital Burden:NMPA cGMP compliance and ISO 15378 certification requirements favor operators with dedicated validation infrastructure over smaller regional competitors.
- Pre-filled Syringe Substitution:Injectable biologics are migrating toward ready-to-use delivery formats that bypass traditional secondary packaging workflows entirely.
Strategic Opportunities
- Greater Bay Area Expansion:Guangdong province biopharma investment is outpacing local packaging capacity, creating whitespace for qualified entrants.
- Cell and Gene Therapy Packaging:Cryogenic chain requirements for CAR-T and gene therapy products demand specialized containment solutions absent from generic portfolios.
- Dual Carbon Policy Alignment:MEE environmental compliance incentives favor packagers with renewable energy sourcing and recyclable material certifications.
Industry Challenges
- Serialization Engineering Talent Scarcity:Qualified professionals capable of integrating aggregation software with legacy line equipment command premium compensation in Shanghai and Suzhou markets.
- Validation Timeline Compression:NMPA facility qualification and process validation protocols extend commercialization timelines for new contract relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pharmaceutical Contract Packaging Market |
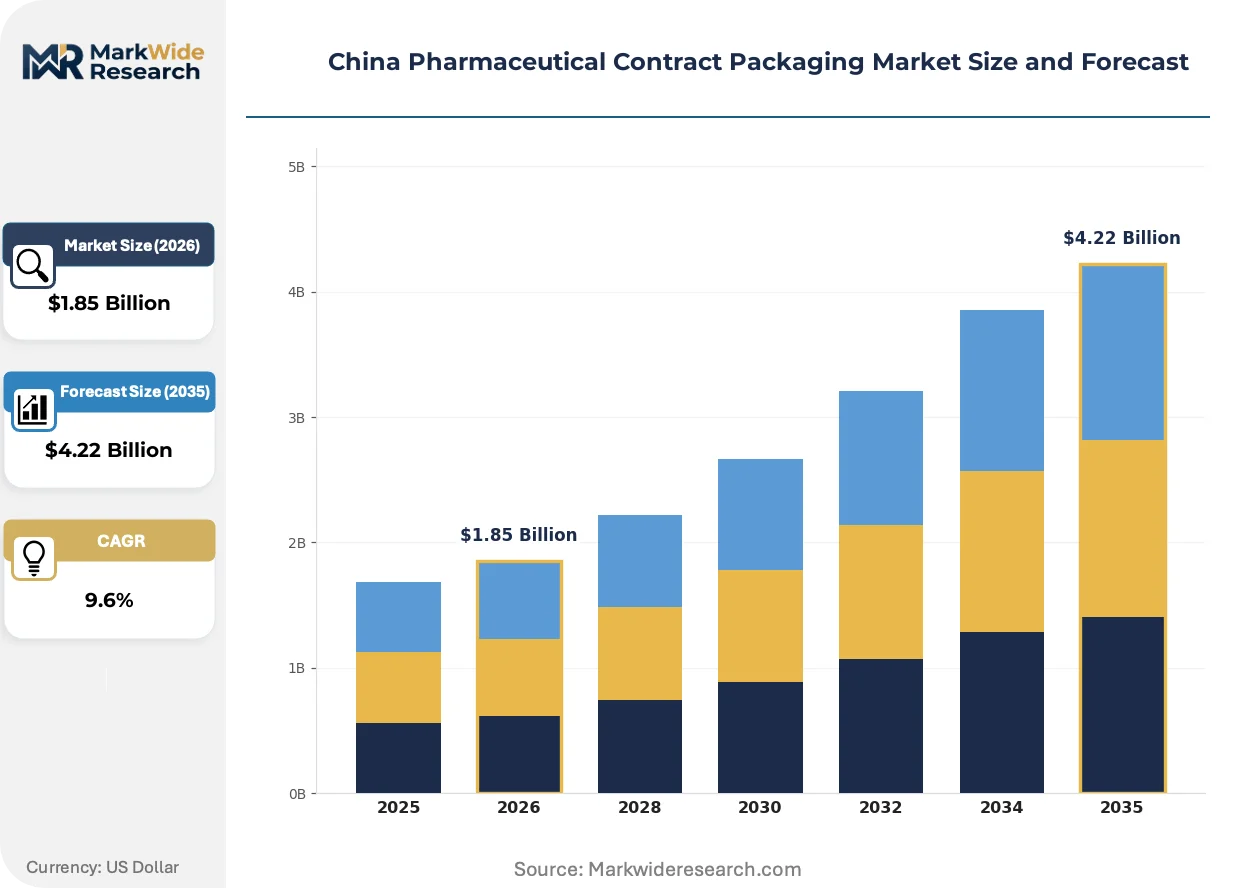
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.22 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Blisters, Pouches, Cartons Technology: Cold Forming, Heat Sealing, Vacuum Packing, Serialization End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturing Organizations, Generic Manufacturers Regulatory Compliance: FDA Standards, EU GMP, ISO Certification, cGMP |
| Companies Covered | Catalent Inc, Amcor PLC, Daito Pharmaceutical Co Ltd, CCL Industries, Schott AG, Nipro Corporation, Westrock Company, PCI Pharma Services, West Pharmaceutical Services Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pharmaceutical Contract Packaging Market Strategic Shifts & Innovations
Digital track-and-trace infrastructure and sustainable material transitions are reconfiguring technical specifications and capital deployment priorities across Chinese pharmaceutical packaging operations.
Blockchain-enabled verification systems are replacing paper-based chain-of-custody documentation for high-value biologics shipments. Domestic innovators and multinational subsidiaries are piloting distributed ledger integration for temperature excursion accountability. This architecture is rendering obsolete manual batch record reconciliation that previously delayed release decisions.
NMPA serialization deadlines are accelerating aggregation infrastructure investment across tier-one contract packagers. The regulator's phased implementation of unit-dose traceability is compressing qualification timelines for line-level camera verification and cloud-based repository connectivity. Biologics manufacturers with export ambitions face the steepest compliance ramps as they harmonize NMPA and FDA validation protocols simultaneously.
Hospital procurement consolidation is consolidating packaging specification authority into centralized tendering platforms. Provincial volume commitments are displacing fragmented hospital-level purchasing, forcing contract packagers toward standardized formats with longer production runs. This concentration is most visible in Jiangsu and Zhejiang, where health commission unified bidding now governs majority pharmaceutical expenditure.
China Pharmaceutical Contract Packaging Market Segmentation
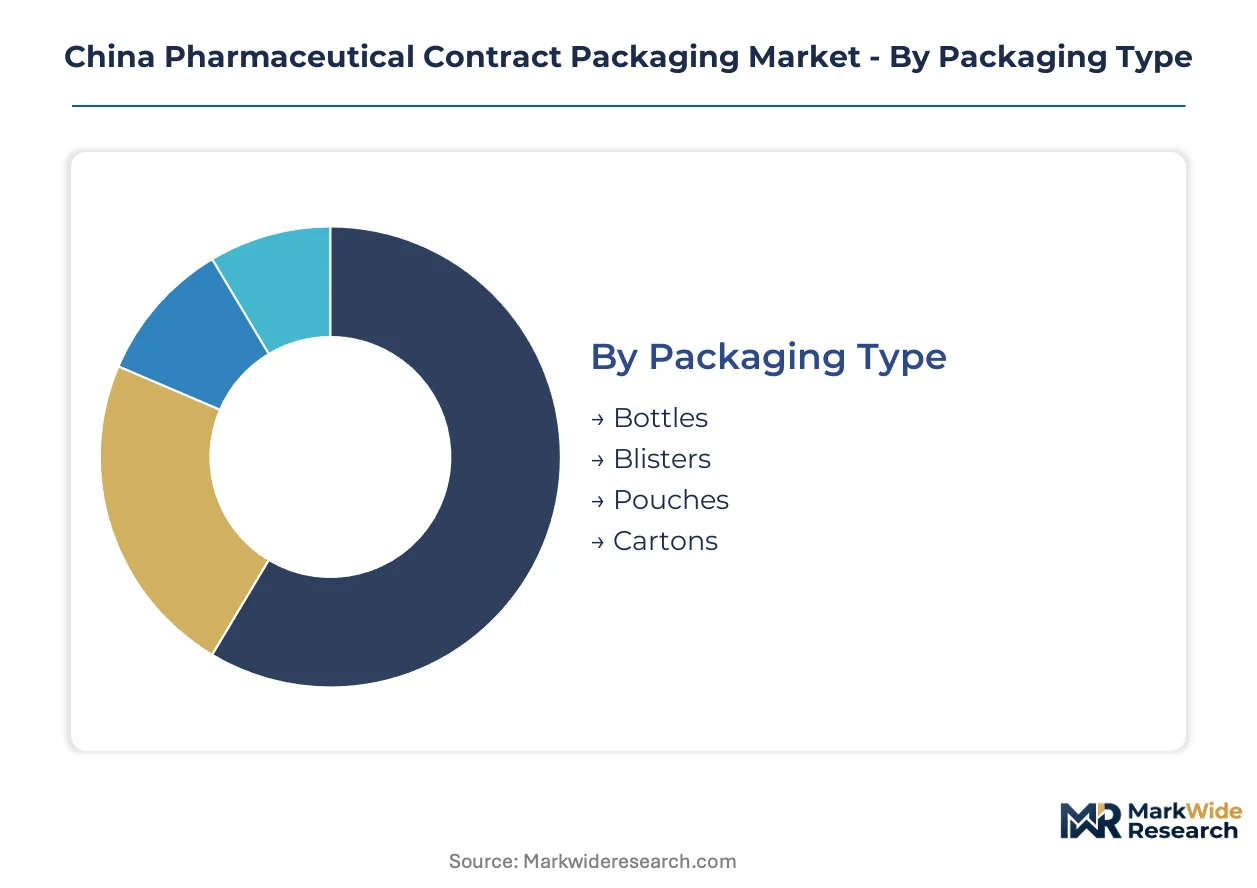
Contract packaging segmentation in China reveals how NMPA mandates and biotech commercialization are redistributing capacity across format types and customer categories. Packaging type and end-user splits now drive capital allocation more than geographic expansion.
Packaging Type:
Cost tier differentiation separates high-barrier formats from commodity volume plays in China's pharmaceutical packaging landscape.
- Blisters:Aluminum-PVC or aluminum-cold form laminates deliver unit-dose protection with child-resistant and senior-friendly opening features. Demand concentrates among oral solid dose manufacturers in Jiangsu province where NMPA serialization mandates require integrated blister-line camera verification systems.
- Bottles:HDPE and PET containers with induction sealing serve high-volume generic portfolios requiring moisture and tamper evidence. Shanghai-based contract packagers report bottle filling lines running at maximum utilization as provincial procurement consolidation lengthens production runs for standardized formats.
- Pouches:Flexible film structures with resealable zippers accommodate powder and granule formulations for pediatric and geriatric dosing convenience.
- Cartons:Folding carton assembly with leaflet insertion and braille embossing completes secondary packaging workflows for export-bound biologics.
Blister formats hold installed capacity. Pouch configurations are rotating up the share rankings.
Technology:
Application requirements determine whether moisture sensitivity or traceability compliance commands technical investment priority.
- Serialization:Unit-dose aggregation with GS1-compliant barcode printing and cloud repository connectivity addresses NMPA track-and-trace mandates. Yangtze River Delta facilities face compressed qualification timelines as biotech firms with simultaneous FDA filing ambitions demand harmonized validation protocols.
- Cold Forming:Deep-draw aluminum laminates without PVC create impermeable barriers for hygroscopic compounds and effervescent tablets. Suzhou-based packagers specializing in cold form capture premium pricing from multinational subsidiaries launching respiratory and cardiovascular portfolios in China.
- Heat Sealing:Conventional thermal bonding sustains broader applicability across generic solid dose portfolios with less stringent stability requirements.
- Vacuum Packing:Oxygen exclusion systems extend shelf life for oxidation-sensitive APIs and herbal formulations in traditional Chinese medicine segments.
Serialization infrastructure holds installed capacity. Cold forming lines are rotating up the share rankings.
End User:
Customer type segmentation tracks how pipeline maturity and capital constraints reshape outsourcing decisions across China's pharmaceutical value chain.
- Biotech Firms:Domestic biologics developers with CAR-T and monoclonal antibody pipelines transfer packaging operations to contract specialists as candidates advance to commercialization. Shanghai and Suzhou facilities report fastest capacity absorption from this segment as in-house line investments become economically unjustifiable for single-product companies.
- Pharmaceutical Companies:Multinational subsidiaries and established domestic innovators maintain hybrid models, outsourcing overflow volume and specialized formats while retaining strategic packaging capabilities in-house.
- Contract Manufacturing Organizations:CDMOs with integrated packaging capabilities compete directly with standalone contract packagers for biotech outsourcing contracts.
- Generic Manufacturers:Cost-optimized oral solid dose producers drive commoditized blister and bottle volume through high-throughput eastern China facilities.
Pharmaceutical companies hold installed capacity. Biotech firms are rotating up the share rankings.
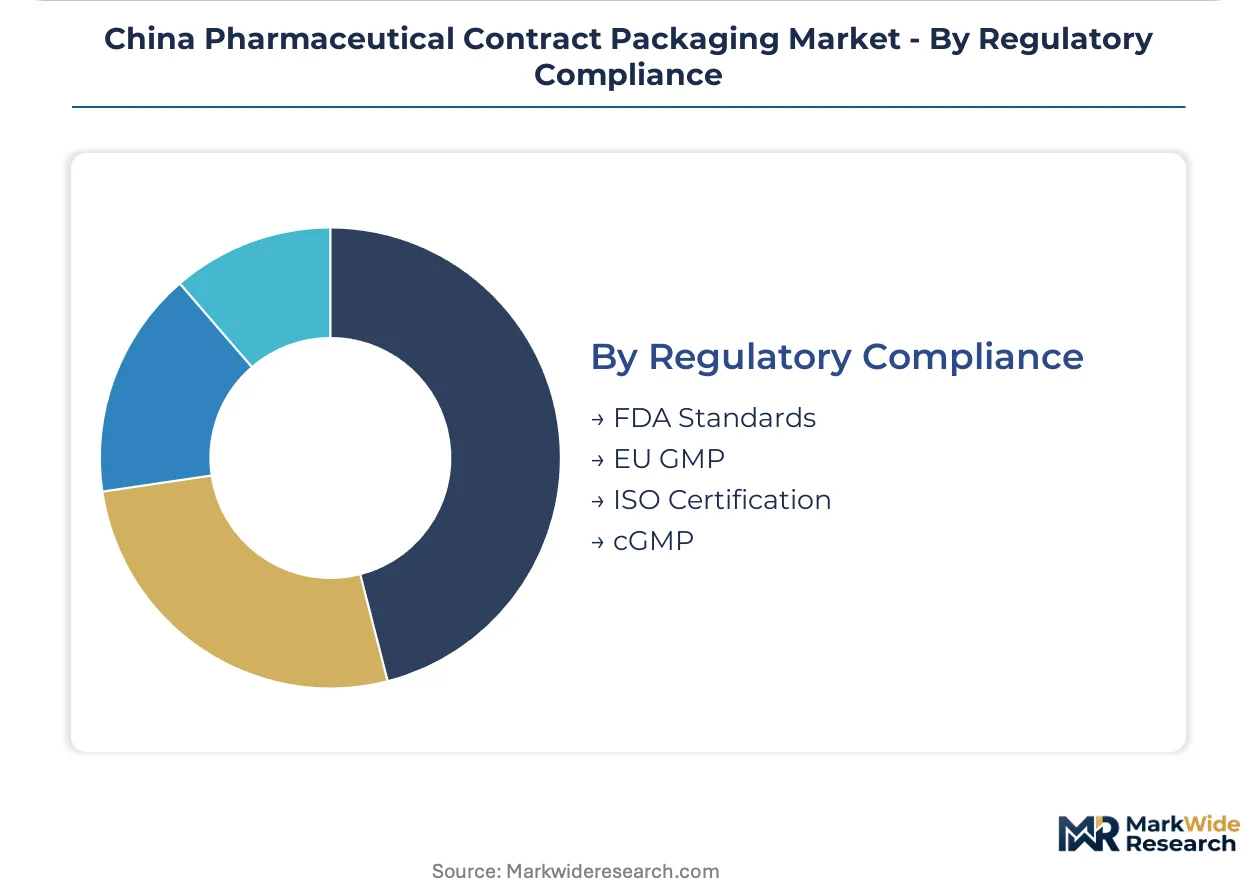
Regulatory Compliance:
Certification tier determines facility qualification for domestic distribution versus export eligibility and biologics handling authority.
- cGMP:NMPA current Good Manufacturing Practice standards govern facility qualification, batch documentation, and quality system architecture for all domestic pharmaceutical packaging operations. Jiangsu province inspectors enforce cGMP compliance with increasing stringency, favoring operators with dedicated validation infrastructure over fragmented regional competitors.
- ISO Certification:ISO 15378 primary packaging materials certification and ISO 9001 quality management systems support supplier qualification for multinational pharmaceutical procurement.
- FDA Standards:US FDA validation protocols enable export eligibility for contract packagers serving multinational subsidiaries with simultaneous global filing strategies.
- EU GMP:European Union Good Manufacturing Practice certification opens access to European market distribution for domestic innovators pursuing international expansion.
cGMP compliance holds installed capacity. FDA standards certification is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA serialization mandates and biotech commercialization are redistributing pharmaceutical packaging capacity across China's eastern manufacturing corridors. Provincial industrial policies and procurement consolidation are reshaping where contract packagers locate validation infrastructure.
Yangtze River Delta
Shanghai and Jiangsu province anchor the dominant concentration of pharmaceutical contract packaging demand. NMPA cGMP enforcement in Jiangsu favors operators with dedicated quality systems over fragmented competitors. Suzhou-based facilities report fastest capacity absorption from domestic biotech firms transferring commercial packaging operations.
Pearl River Delta
Guangdong province biopharma investment is outpacing local packaging capacity, creating whitespace for qualified entrants. The province's health commission unified bidding now governs majority pharmaceutical expenditure, forcing standardized format production. Shenzhen and Guangzhou pharmaceutical manufacturing clusters are driving secondary packaging demand for export-bound biologics.
Beijing-Tianjin-Hebei
The northern corridor concentrates domestic innovator headquarters and regulatory expertise. NMPA's proximity in Beijing accelerates facility qualification timelines for packagers serving companies with simultaneous FDA filing ambitions. Tianjin port infrastructure supports cold-chain packaging workflows for temperature-sensitive biologics shipments.
Sichuan-Chongqing
Western China pharmaceutical manufacturing is expanding beyond traditional herbal medicine into synthetic drug production. Chongqing's logistics hub status attracts contract packagers seeking inland distribution coverage. Provincial procurement platforms are consolidating packaging specifications into centralized tendering systems.
Shandong Peninsula
The province's chemical and API manufacturing base generates downstream packaging demand for generic solid dose formats. Qingdao and Yantai pharmaceutical exporters require ISO 15378 certification for multinational procurement qualification. Local facilities compete on high-throughput bottle and blister line utilization.
China Pharmaceutical Contract Packaging Market Key Industry Players
Multinational integrated service providers and specialized regional operators split the market along capability depth and geographic coverage lines. Tier-one operators command premium positioning through validated serialization infrastructure and dual NMPA-FDA compliance protocols. Three archetypes dominate: integrated development-to-commercialization platforms, flexible packaging specialists, and containment system technical leaders. Competitive dynamics center on capacity expansion in underserved southern provinces and strategic partnerships with domestic biotech firms lacking in-house packaging investments.
Within the integrated service tier, Catalent Inc exemplifies the development-to-commercialization platform archetype with multiple Chinese site presence. Amcor PLC anchors flexible packaging supply capabilities for high-volume oral solid dose formats. West Pharmaceutical Services Inc occupies the containment and delivery systems specialization vector, competing on technical specification rather than commodity throughput. These three operators represent distinct strategic positioning models that regional competitors must match or circumvent through niche specialization.
| Leading Market Players |
|---|
| Catalent Inc |
| Amcor PLC |
| Daito Pharmaceutical Co Ltd |
| CCL Industries |
| Schott AG |
| Nipro Corporation |
| Westrock Company |
| PCI Pharma Services |
| West Pharmaceutical Services Inc |
| Others |
Cost & Logistics Intelligence
Shanghai-Ningbo port corridor freight rates compress margin structures across eastern China pharmaceutical packaging clusters, concentrating pricing power among Yangtze River Delta operators while forcing Guangdong entrants to absorb elevated logistics costs that differentiate their regional quotations from Jiangsu-based competitors serving identical NMPA serialization requirements.
Pricing Analysis
Geographic price spreads between Yangtze River Delta and Pearl River Delta facilities reach 12-18% for equivalent NMPA cGMP-certified serialization services. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated biologics specialists from domestic-only cGMP operators and uncertified regional packagers. Pricing pressure stems from aluminum foil cost volatility and provincial procurement consolidation forcing standardized format commoditization. Generic manufacturers exhibit highest price sensitivity, while biotech firms with CAR-T pipelines prioritize validation pedigree over unit cost.
Supply Chain Analysis
Supplier-financing arrangements with 90-120 day payment terms strain working capital for cold-form aluminum laminate distributors serving Suzhou packaging clusters. Raw material sourcing concentrates in China, South Korea, and Germany for pharmaceutical-grade films, foils, and barrier resins. Single-source vulnerability persists for deep-draw aluminum substrates used in moisture-sensitive compound packaging. Distribution runs through pharmaceutical manufacturing clusters in Jiangsu, Shanghai, and Guangdong with just-in-time delivery protocols synchronized to NMPA batch release timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China pharmaceutical contract packaging is recovering from cyclical compression as biotech commercialization pipelines refill capacity absorption schedules following post-pandemic regulatory backlog clearance. NMPA serialization mandate phasing creates predictable demand visibility for qualified operators.
For Market Incumbents: Entrench serialization infrastructure advantages through aggregation software upgrades that preempt competitor qualification timelines. Defend against CDMO vertical integration by locking biotech firms into multi-year commercialization partnerships with dedicated line capacity. Prioritize FDA dual-certification investment to capture export-bound biologics volume from domestic innovators pursuing simultaneous global filings. For New Entrants and Emerging Players: Pursue Greater Bay Area whitespace where Guangdong biopharma investment outpaces local packaging capacity. Target cell and gene therapy cryogenic containment as the most penetrable specialty segment absent from generic portfolios. Establish go-to-market positioning through MEE environmental compliance certifications that align with dual carbon policy incentives. For Investors and Strategic Acquirers: Regional specialists with NMPA-FDA dual validation protocols represent the most defensible acquisition archetype for long-term viability across the 5-10 year regulatory harmonization window. Monitor biotech firm capital raising velocity as the inflection signal for contract packaging demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Investment | NMPA aggregation compliance separates qualified operators from fragmented regional competitors in Jiangsu. |
| FDA Dual-Certification Pathway | Export eligibility unlocks multinational subsidiary contracts for domestic innovators with global ambitions. |
| Cell Therapy Cold Chain Partnership | Cryogenic containment capabilities capture CAR-T commercialization demand absent from standard portfolios. |
| Greater Bay Area Capacity Expansion | Guangdong biopharma investment growth exceeds local packaging supply, creating qualified entrant whitespace. |
| MEE Environmental Compliance Program | Dual carbon policy alignment secures preferred supplier status with state-owned pharmaceutical procurement platforms. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging operations directors, NMPA regulatory affairs leads, biotech supply chain managers, and hospital procurement officers across Shanghai, Suzhou, and Guangzhou. Secondary validation drew from NMPA drug approval databases, FDA facility inspection records, provincial health commission tendering platforms, and pharmaceutical customs export data. Bottom-up capacity utilization estimates triangulated against top-down market sizing derived from manufacturing cluster economic census aggregates.
Calibration against historical NMPA serialization compliance timelines and biotech firm capital deployment patterns anchored the analytical framework across the projection horizon. Segmentation modeling incorporated packaging format type, technology tier, end-user category, and regional regulatory cluster dimensions. CAGRs were derived from capacity expansion announcements, facility qualification backlogs, and patient population growth assumptions for targeted therapeutic areas.
Sensitivities concentrate around NMPA regulatory timeline acceleration, aluminum commodity price volatility, and biotech funding environment shifts. Forecasts reflect documented assumptions regarding serialization mandate enforcement consistency and provincial procurement consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Polymer Vials Market