
 Middle East and Africa Pharmaceutical Packaging Market | 2026-2036
Middle East and Africa Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmaceutical Packaging Market Foresight
The capability gap between integrated multinationals and regional converters is collapsing as barrier-film specifications tighten across the Middle East and Africa. Amcor plc leverages its blown-film extrusion network to supply high-barrier laminates to Saudi Arabian injectable producers. Gerresheimer AG anchors its position through molded glass capacity serving North African oncology formulation facilities. Mondi Group competes via kraft-based secondary packaging optimized for humid Sub-Saharan distribution corridors.
Middle East and Africa Pharmaceutical Packaging encompasses primary, secondary, and tertiary containment systems engineered to maintain drug stability, ensure patient safety, and comply with serialization mandates across diverse climatic conditions; these systems employ multi-layer coextrusions, desiccant-integrated closures, and tamper-evident features to protect moisture-sensitive formulations from manufacture through last-mile delivery. Blister packs dominate unit-dose dispensing for tropical markets where strip-format stability outweighs bottle convenience, while cold forming technology leads in aluminum-barrier applications for hygroscopic generics. Plastic bottles sustain volume share across over-the-counter segments, though glass vials capture premium margin pools in biologics and vaccine distribution.
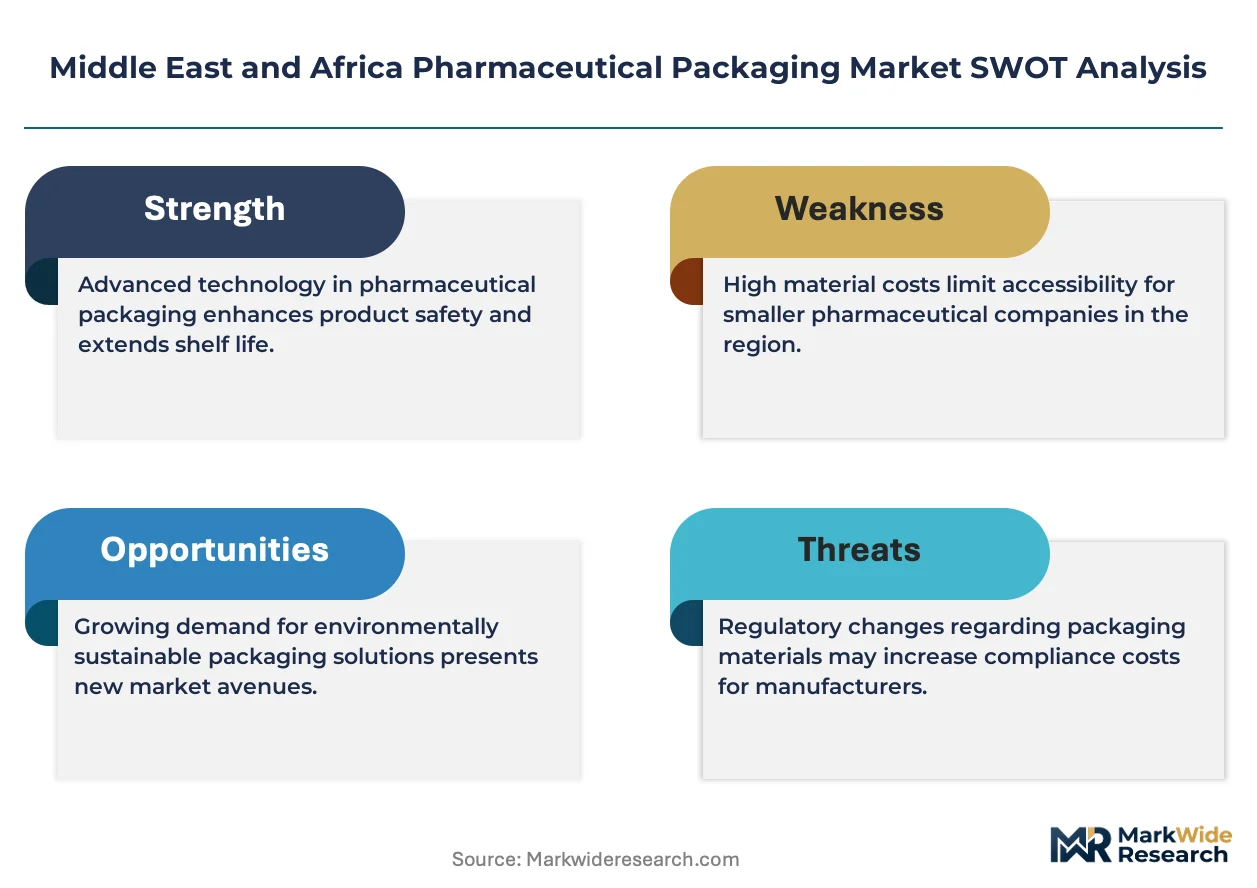
SFDA in Saudi Arabia and SAHPRA in South Africa enforce serialization and stability-testing protocols that elevate packaging material qualification costs for market entrants. Egypt's national drug authority and the UAE's Ministry of Health and Prevention are harmonizing track-and-trace requirements with GS1 standards, reshaping label and box specifications across the region. Stakeholders must monitor regulatory divergence between Gulf Cooperation Council states and Sub-Saharan African blocs, as incompatible coding standards threaten to fragment procurement scale.
Market Dynamics
Biologics cold-chain expansion across Gulf States is compressing qualification timelines for barrier-laminate suppliers while SAHPRA's ICH Q1A alignment in South Africa forces reformulation of primary container specifications.
Growth Catalysts
- SFDA serialization mandates:Saudi Arabia's track-and-trace requirements are accelerating investment in tamper-evident label and carton infrastructure across injectable production facilities.
- Cairo-Alexandria corridor expansion:Egypt's domestic pharmaceutical manufacturing cluster is scaling blister-pack demand for tropical stability formulations serving North African distribution.
- Desiccant-integrated closures:Multi-layer coextrusion advances in high-humidity Sub-Saharan corridors are extending shelf life for hygroscopic generic tablets.
Market Restraints
- Aluminum-barrier input concentration:Cold-forming foil supply concentrates among Asian converters, exposing North African oncology facilities to freight-cost volatility and extended lead times.
- ICH Q1A testing burden:SAHPRA's stability-guideline alignment is elevating material-qualification costs for regional entrants without multinational laboratory networks.
- Glass vial substitution pressure:Cyclic olefin polymer (COP) syringes are capturing biologics volume from molded glass in temperature-sensitive vaccine distribution.
Strategic Opportunities
- GS1 harmonization in UAE:MOHAP's track-and-trace alignment with global standards is opening procurement consolidation across Gulf Cooperation Council label and secondary packaging specifications.
- Kraft-based secondary packaging:Humid-climate-optimized corrugated solutions for last-mile Sub-Saharan distribution remain underpenetrated relative to synthetic alternatives.
- Cold-chain infrastructure gaps:Biologics manufacturers in Saudi Arabia and UAE are seeking domestic blow-fill-seal capacity to reduce import dependency for sterile liquid containment.
Industry Challenges
- Barrier-film technician scarcity:Multi-layer coextrusion expertise concentrates among multinational converters, constraining regional independent film suppliers from meeting SFDA qualification protocols.
- Serialization line retrofit costs:Egypt's national drug authority track-and-trace deadlines are forcing mid-scale generic producers to prioritize capex toward coding equipment over primary container upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmaceutical Packaging Market |
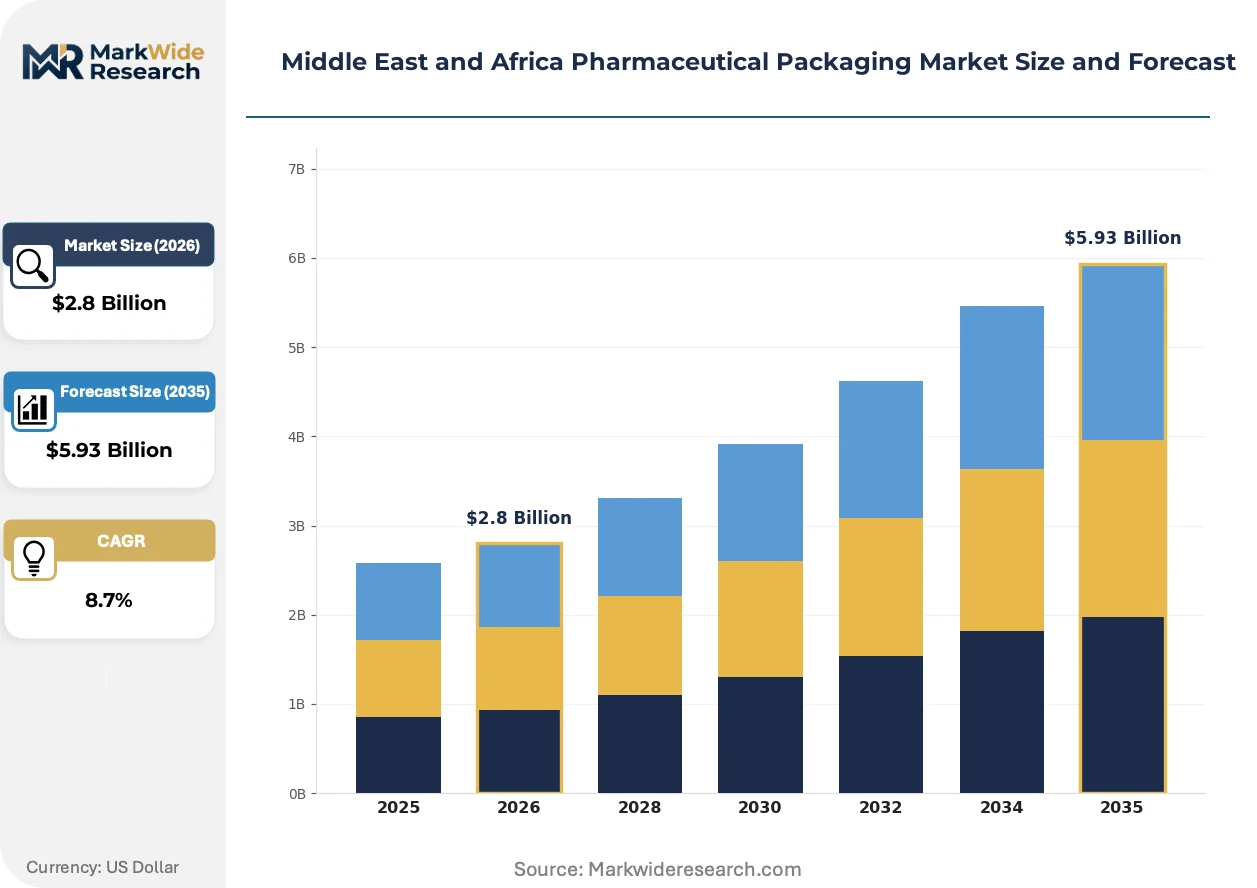
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Blister Packs, Labels, Boxes Material: Plastic, Glass, Metal, Paper End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals Technology: Cold Forming, Vacuum Forming, Flexographic Printing, Digital Printing |
| Companies Covered | Amcor plc, AptarGroup, Inc., Berry Global, Inc., ALPLA Werke Alwin Lehner GmbH & Co KG, Schott AG, Gerresheimer AG, Mondi Group, Constantia Flexibles Group GmbH, Huhtamaki Oyj, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmaceutical Packaging Market Shifts & Advancements
Active and intelligent packaging systems are penetrating pharmaceutical supply chains as climatic variability and regulatory traceability requirements intensify across Middle Eastern and African distribution corridors.
Cold-forming aluminum barrier technology is bifurcating the primary container market between high-performance oncology and vaccine applications versus cost-optimized generic tablet protection. Saudi Arabian injectable producers are adopting deep-drawn cold-form blisters at accelerated rates for moisture-sensitive biologics. This technology is bifurcating procurement pools into qualified high-barrier suppliers and commodity converters unable to meet ICH stability thresholds.
SAHPRA's enforcement of ICH Q1A stability guidelines is compressing acceptable water-vapor transmission rates for primary containers across South African formulation facilities. Regional converters must now invest in upgraded barrier-testing infrastructure to retain oncology supply contracts. North African glass and polymer vial manufacturers are responding with accelerated desiccant-integration programs and enhanced closure-seal validation protocols.
Biologics manufacturers are consolidating procurement relationships around converters offering integrated serialization and cold-chain documentation capabilities. Traditional fragmented supplier bases across Egypt and UAE are contracting toward full-service packaging partners capable of GS1-compliant label production and temperature-monitoring device integration. This concentration is most visible in Saudi Arabia's Riyadh-Dammam pharmaceutical manufacturing corridor, where injectable producers now require single-source accountability for primary barrier and secondary track-and-trace compliance.
Middle East and Africa Pharmaceutical Packaging Market Segmentation
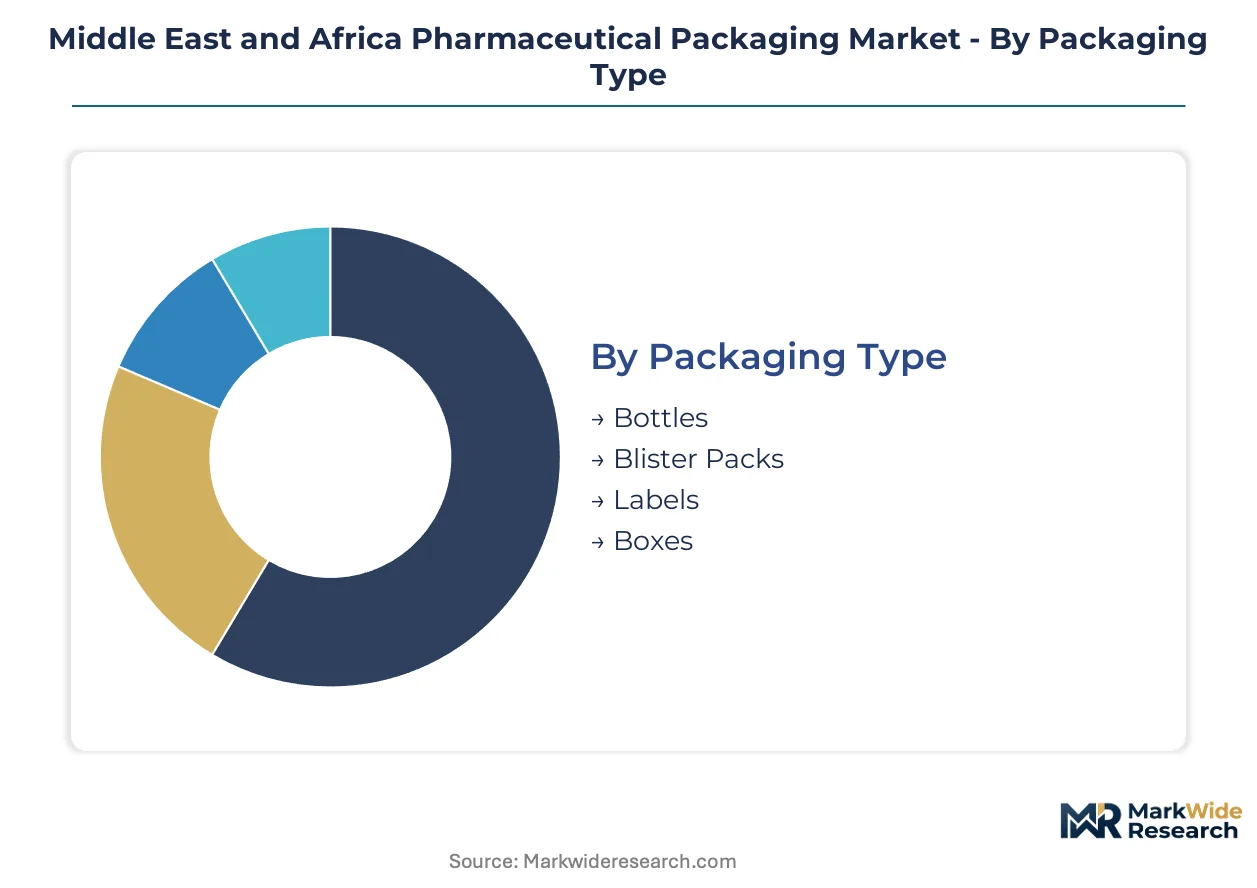
Pharmaceutical packaging procurement across the Middle East and Africa fragments across four distinct taxonomies. Each segmentation axis reveals divergent margin structures, qualification barriers, and channel access patterns that shape supplier strategy in this climate-stressed, regulation-intensive market.
Packaging Type:
Channel flow splits between high-volume oral solid distribution and specialized sterile containment, with tropical stability requirements dictating format selection across North African and Gulf State corridors.
- Bottles:HDPE and PET containers dominate OTC analgesic and vitamin distribution through Egyptian retail pharmacies. Plastic bottle procurement concentrates among Cairo-Alexandria generic producers seeking cost-efficient moisture protection for humidity-exposed tablet stocks.
- Blister Packs:Cold-form aluminum and thermoformed PVC structures capture unit-dose dispensing for tropical markets where strip-format stability outweighs bottle convenience. Saudi Arabian injectable producers are accelerating deep-drawn cold-form adoption for moisture-sensitive biologics, compressing qualification timelines for barrier-laminate suppliers.
- Labels:Pressure-sensitive and booklet formats integrate GS1-compliant serialization for SFDA and MOHAP track-and-trace mandates. Label specifications are tightening as UAE harmonizes with global standards, opening procurement consolidation across Gulf Cooperation Council states.
- Boxes:Kraft-based corrugated secondary packaging optimized for humid Sub-Saharan distribution corridors remains underpenetrated relative to synthetic alternatives. Mondi Group competes in this segment with climate-resistant board grades.
By volume, bottles lead. By growth pace, blister packs are expanding most quickly.
Material:
Cost tier stratification separates premium barrier materials from commodity substrates, with ICH Q1A alignment in South Africa forcing upward migration in primary container specifications.
- Plastic:Multi-layer coextrusions and cyclic olefin polymers displace glass in temperature-sensitive vaccine distribution. COP syringes are capturing biologics volume from molded glass as cold-chain infrastructure expands across Saudi Arabia and UAE.
- Glass:Molded borosilicate and soda-lime vials retain premium positioning in oncology formulation facilities across North Africa. Gerresheimer AG anchors supply through regional molded glass capacity, though desiccant-integration programs are accelerating to meet SAHPRA stability thresholds.
- Metal:Cold-forming aluminum foil supply concentrates among Asian converters, exposing North African facilities to freight-cost volatility. Aluminum-barrier applications lead in hygroscopic generic protection where water-vapor transmission rates must compress under tightening guidelines.
- Paper:Kraft and micro-flute corrugated solutions serve last-mile distribution in humid Sub-Saharan corridors. Paper-based secondary packaging offers sustainability positioning against plastic alternatives, though moisture resistance remains the critical performance hurdle.
Plastic commands the largest procurement spend. Glass maintains the steepest margin expansion trajectory.
End User:
Customer type determines serialization sophistication and cold-chain documentation requirements, with biologics manufacturers consolidating procurement around full-service packaging partners.
- Pharmaceutical Companies:Integrated multinationals and regional champions in Egypt and Saudi Arabia drive specification-setting for barrier-film and track-and-trace compliance. These buyers require single-source accountability for primary barrier and secondary serialization across Riyadh-Dammam manufacturing corridors.
- Contract Manufacturers:Mid-scale generic producers in Egypt face serialization line retrofit costs that prioritize capex toward coding equipment over primary container upgrades. CDMOs are fragmenting supplier relationships between specialized converters and commodity packaging traders.
- Research Institutions:Clinical trial material packaging demands small-batch flexibility and temperature-monitoring device integration. This segment sources through specialized converters capable of protocol-specific documentation.
- Hospitals:Unit-dose and compliance-pouch formats for inpatient pharmacy distribution concentrate in South African and UAE tertiary care networks. Hospital procurement emphasizes tamper-evidence and patient-safety features over cost minimization.
Pharmaceutical companies generate the deepest volume. Contract manufacturers are gaining share fastest as production outsourcing accelerates.
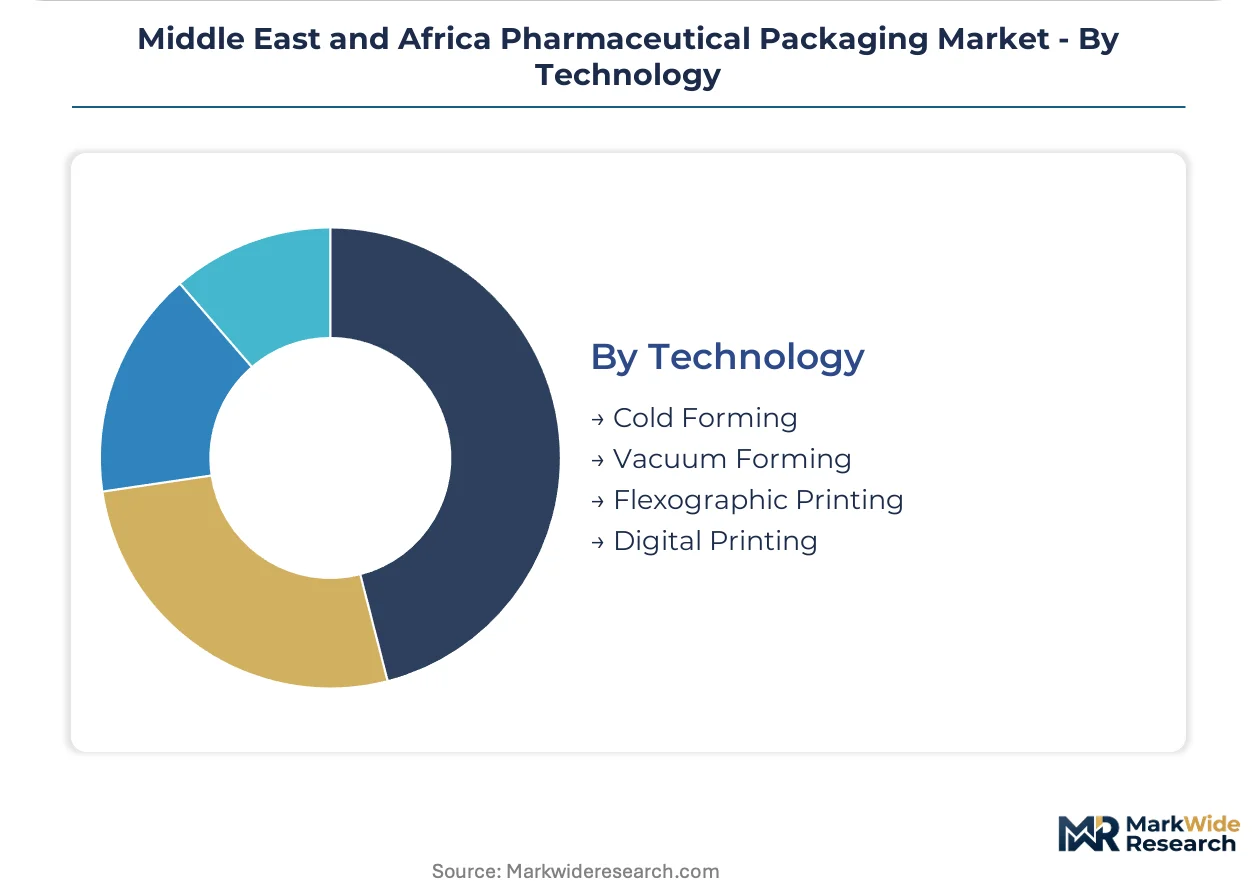
Technology:
Maturity gradients separate established forming processes from digitally enabled printing platforms, with regulatory traceability requirements reshaping capital allocation across converter facilities.
- Cold Forming:Deep-drawn aluminum barrier technology bifurcates procurement between high-performance oncology applications and cost-optimized generic tablet protection. Cold forming demands specialized technician expertise that concentrates among multinational converters.
- Vacuum Forming:Thermoformed PVC and PETG structures serve cost-sensitive oral solid markets across North Africa. This technology offers faster qualification timelines than cold forming but sacrifices barrier performance in extreme humidity.
- Flexographic Printing:High-speed rotary printing dominates serialized label production for SFDA-mandated track-and-trace infrastructure. Flexo lines require significant retrofit investment to meet variable-data coding requirements.
- Digital Printing:Inkjet and toner platforms enable short-run flexibility for clinical trial materials and regional language customization. Digital adoption accelerates in UAE and Saudi Arabia where MOHAP harmonization demands rapid label specification changes.
Cold forming anchors the highest-value applications. Digital printing is climbing the fastest as serialization complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the region. Gulf State buyers prioritize cold-chain qualification over unit cost, while Egyptian and Nigerian procurement teams face acute budget constraints that favor locally sourced secondary packaging.
Saudi Arabia
Injectable biologics production is scaling rapidly in the Riyadh-Dammam corridor. SFDA serialization mandates are compressing supplier qualification timelines for track-and-trace compliant label and carton infrastructure. Domestic blow-fill-seal capacity expansion is reducing import dependency for sterile liquid containment.
United Arab Emirates
MOHAP's GS1 harmonization is consolidating procurement specifications across Dubai and Abu Dhabi pharmaceutical free zones. Cold-chain infrastructure investment is accelerating demand for temperature-monitoring device integration in secondary packaging. Jebel Ali pharmaceutical logistics clusters are attracting full-service packaging partners.
Egypt
Domestic generic manufacturing is concentrating in the Cairo-Alexandria corridor, driving blister-pack demand for tropical stability formulations. The national drug authority's track-and-trace deadlines are forcing mid-scale producers to prioritize coding equipment capex. Local converters are expanding PVC and PET thermoforming capacity for oral solid dose protection.
South Africa
SAHPRA's ICH Q1A alignment is elevating barrier-property requirements for primary containers serving oncology formulation facilities. Cape Town and Johannesburg pharmaceutical clusters are upgrading desiccant-integration programs. Regional glass vial manufacturers are investing in enhanced closure-seal validation protocols.
Nigeria
Humid-climate distribution challenges are sustaining demand for kraft-based secondary packaging in Lagos and Kano pharmaceutical corridors. The national pharmaceutical regulator is gradually aligning with WHO prequalification standards for packaging material traceability. Local corrugated converters are developing moisture-resistant board grades for last-mile generic drug distribution.
Middle East and Africa Pharmaceutical Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational converters controlling high-barrier laminate supply and regional players competing on secondary packaging logistics. The market structure rewards players offering combined serialization compliance and cold-chain documentation capabilities. Three archetypes dominate: full-service multinationals with blown-film extrusion networks, molded glass specialists serving oncology facilities, and kraft-based corrugated converters optimized for humid Sub-Saharan corridors. Competitive moves center on backward integration into barrier-film production and strategic partnerships with biologics manufacturers seeking single-source accountability.
Among the integrated multinational tier, Amcor plc and Gerresheimer AG exemplify contrasting positioning strategies. Amcor occupies a position representing blown-film extrusion leadership for high-barrier laminate supply to Gulf State injectable producers. Gerresheimer anchors the molded glass specialist archetype, with regional capacity serving North African oncology formulation requirements. Mondi Group sits within the climate-optimized secondary packaging tier, competing via kraft-based solutions for humid distribution corridors.
| Leading Market Players |
|---|
| Amcor plc |
| AptarGroup, Inc. |
| Berry Global, Inc. |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Schott AG |
| Gerresheimer AG |
| Mondi Group |
| Constantia Flexibles Group GmbH |
| Huhtamaki Oyj |
| Others |
Supply & Pricing Matrix
Cyclic olefin polymer syringe substitution for molded glass vials is redrawing procurement geography across Gulf State biologics corridors while compressing premium-tier pricing power formerly anchored in borosilicate supply chains. This material migration simultaneously fragments supplier consolidation and forces cold-chain packaging converters toward volume-based contract structures.
Pricing Analysis
After-sales service contracts for serialization line maintenance and cold-chain documentation compliance now capture lifetime value exceeding primary container hardware margins. Three-tier pricing structure across premium barrier laminates, standard thermoformed films, and economy-grade corrugated separates SFDA-qualified multinationals from regional converters lacking ICH stability certification. Cost compression in economy-tier secondary packaging intensifies as Egyptian generic producers prioritize coding equipment capex over material upgrades. Contract manufacturers exhibit acute price sensitivity, while Saudi Arabian injectable biologics manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites aluminum cold-forming foil delivery schedules to North African oncology facilities, exposing just-in-time inventory models to geopolitical disruption. Raw material procurement draws from Asian converter networks for high-barrier laminates, German and Austrian suppliers for molded glass vials, and domestic Egyptian capacity for PVC thermoforming substrates. Single-source vulnerability concentrates in desiccant-integrated closure supply, where multinational chemical specialists control moisture-scavenger formulation IP. Distribution feeds from Jebel Ali pharmaceutical free zones through humid Sub-Saharan last-mile corridors served by kraft-based corrugated specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams for temperature-monitoring device integration and GS1-compliant serialization documentation are expanding faster than primary container hardware sales across Middle East and Africa pharmaceutical corridors. This recurring-revenue layer justifies repositioning around full-service packaging partnerships rather than transactional material supply.
For Market Incumbents: Fortify barrier-film technician training pipelines to defend against regional converter capability gaps closing under SAHPRA and SFDA pressure. Expand backward integration into multi-layer coextrusion capacity within Saudi Arabia's Riyadh-Dammam corridor to capture biologics cold-chain procurement consolidating around domestic qualification. Deepen captive supply of desiccant-integrated closures to offset COP syringe substitution threatening molded glass oncology margins. For New Entrants and Emerging Players: Cold-chain documentation service gaps where incumbents under-serve mid-scale Egyptian generic producers present the most penetrable white-space target. Target kraft-based secondary packaging for humid Nigerian and Kenyan distribution corridors where moisture-resistant board grades remain underdeveloped relative to synthetic alternatives. Lead with digital printing capabilities for rapid UAE label specification changes under MOHAP harmonization timelines. For Investors and Strategic Acquirers: SAHPRA's full ICH Q1A enforcement reshapes the acquisition landscape toward regional converters with upgraded barrier-testing infrastructure and validated desiccant-integration programs. Long-term viability favors targets combining serialization compliance capabilities with cold-chain documentation service layers across the Gulf Cooperation Council. Watch for biologics manufacturer procurement consolidation signals as single-source accountability requirements compress fragmented supplier bases in Egypt and UAE.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multi-Layer Coextrusion | Captures SFDA qualification timelines compressing for Saudi injectable producers. |
| Desiccant-Integrated Closure Capacity Expansion | Retains oncology supply contracts as SAHPRA stability thresholds tighten. |
| GS1-Compliant Serialization Service Layer | Opens procurement consolidation across MOHAP-harmonized UAE specifications. |
| Kraft-Based Corrugated Moisture Resistance R&D | Addresses underpenetrated Sub-Saharan last-mile distribution challenges. |
| Cold-Chain Documentation Partnership Programs | Consolidates biologics manufacturer relationships around integrated accountability. |
Research Methodology
The analysis maps primary container formats, secondary packaging materials, serialization technologies, and cold-chain documentation systems, each validated through packaging engineers at Saudi and Egyptian pharmaceutical manufacturers, procurement leads at UAE biologics free zones, regulatory affairs specialists navigating SAHPRA and SFDA protocols, and corrugated converters serving Nigerian distribution corridors. Secondary sources include SFDA serialization guidance documents, SAHPRA stability-testing protocols, GS1 UAE implementation standards, and trade flow data for aluminum barrier laminate imports. Bottom-up unit demand modeling triangulates against top-down pharmaceutical production capacity assessments across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. The analytical framework segments by packaging type, material substrate, end-user archetype, and forming technology, with additional stratification by regional regulatory cluster reflecting divergence between Gulf Cooperation Council serialization mandates and Sub-Saharan African stability guidelines. CAGRs derive from pharmaceutical production expansion trajectories, cold-chain infrastructure investment pipelines, and barrier-property specification tightening schedules. Forecast inputs incorporate biologics capacity buildout announcements and ICH Q1A alignment timelines for national regulators.
Forecasts assume regulatory continuity in Saudi SFDA and South African SAHPRA regimes; material policy shifts would require re-modeling of qualification cost burdens and barrier-testing infrastructure investment schedules. Practitioners should keep alternative scenarios live as GS1 harmonization progress and COP syringe substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market