
 Vaccine Shippers Market | 2026-2036
Vaccine Shippers Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Shippers Market Analytics
Aftermarket service revenue for thermal packaging lifecycle management is fragmenting across regional service networks and digital monitoring platforms. Envirotainer leverages its controlled-room-temperature container fleet to anchor intercontinental pharmaceutical lanes. Softbox Systems competes through single-use parcel shipper lines designed for last-mile COVID-19 vaccine distribution. Csafe sustains premium positioning via reusable active container programs with integrated real-time telemetry.
Vaccine shippers are insulated enclosures engineered to maintain specified temperature bands, typically between -80°C and +8°C, through phase-change materials, vacuum insulation panels, or mechanical refrigeration systems; their primary purpose is to preserve antigen stability during transit from manufacturing sites to administration points. Passive shippers dominate unit volumes in emerging market immunization programs where electricity infrastructure remains unreliable, while active shippers capture disproportionate value in commercial biologics distribution where excursion tolerance approaches zero. Cryogenic containers represent the fastest-expanding product category as gene therapy developers commercialize ultra-cold storage requirements, though fiberboard-based passive systems still occupy the largest installed base for standard refrigerated vaccines.
WHO Guidelines and IATA Regulations jointly govern cross-border vaccine logistics, with the former establishing product stability testing protocols and the latter mandating pilot training for dangerous goods handling including dry ice shipments. FDA Standards enforce Current Good Manufacturing Practice traceability for domestic distribution, creating compliance cost barriers for non-validated packaging suppliers. Stakeholders must monitor the divergence between passive shipper sustainability mandates and active container energy intensity as environmental disclosure requirements tighten across European and North American procurement frameworks.
Market Dynamics
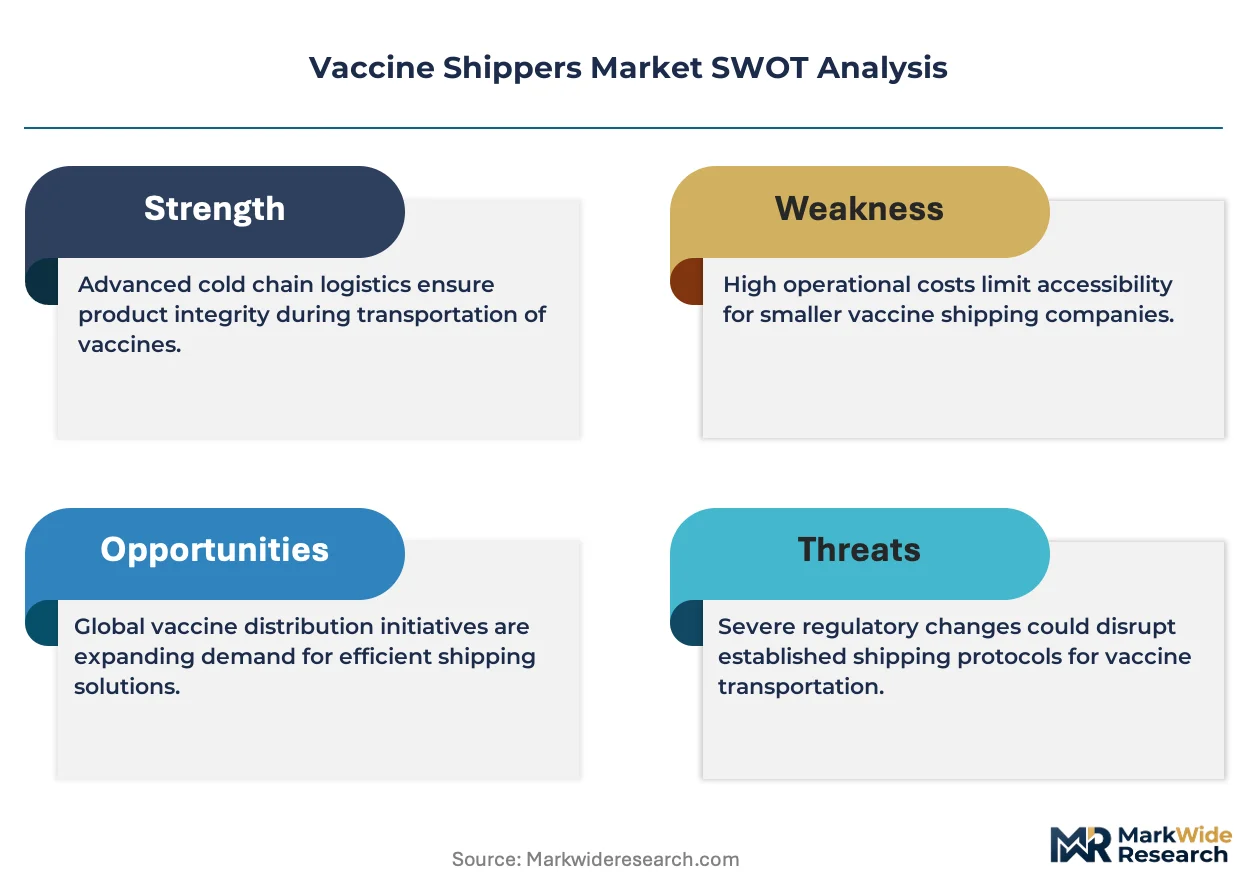
The vaccine shippers market is being reshaped by the divergence between passive shipper sustainability mandates and active container energy intensity as environmental disclosure requirements tighten across European and North American procurement frameworks.
Growth Catalysts
- WHO PQS Prequalification:The Performance, Quality and Safety framework is tightening thermal packaging validation requirements, forcing manufacturers to upgrade qualification protocols and driving replacement demand for certified systems.
- mRNA Portfolio Expansion:Biopharmaceutical cold chain logistics represents the fastest-expanding end-use segment as pharmaceutical companies broaden mRNA and cell therapy pipelines requiring ultra-stable temperature control.
- German Manufacturing Clusters:Vaccine production concentration around Marburg and Dresden is generating specialized shipper procurement demand that pulls advanced thermal packaging technologies into commercial scale deployment.
Market Restraints
- Dry Ice Supply Volatility:Carbon dioxide capture rate fluctuations and regional production concentration are creating input cost instability for cryogenic passive shipper operations.
- Active Container Energy Intensity:Mechanical refrigeration systems face mounting carbon accounting scrutiny under EU CSRD disclosure rules, compressing their addressable market in sustainability-weighted tenders.
- Validation Timeline Compression:Evolving EU GDP Annex 9 revisions are extending qualification periods for new shipper designs, delaying revenue recognition for packaging innovators.
Strategic Opportunities
- Cell Therapy Commercialization:Autologous CAR-T manufacturing is creating demand for cryogenic containers capable of maintaining liquid nitrogen temperatures through multi-modal distribution.
- Digital Monitoring Convergence:Integration of real-time telemetry with blockchain traceability is opening subscription revenue streams in lifecycle management services.
- India Universal Immunization:The country's national cold chain expansion under Mission Indradhanush is generating volume demand for passive shippers designed for unreliable electricity infrastructure.
Industry Challenges
- Thermal Engineer Scarcity:Phase-change material formulation expertise and vacuum insulation panel design capability are concentrated among a narrow specialist workforce, constraining product development velocity.
- Qualification Protocol Fragmentation:Divergent IATA dangerous goods training requirements and WHO stability testing protocols are forcing manufacturers to maintain multiple validation datasets for identical shipper designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Shippers Market |
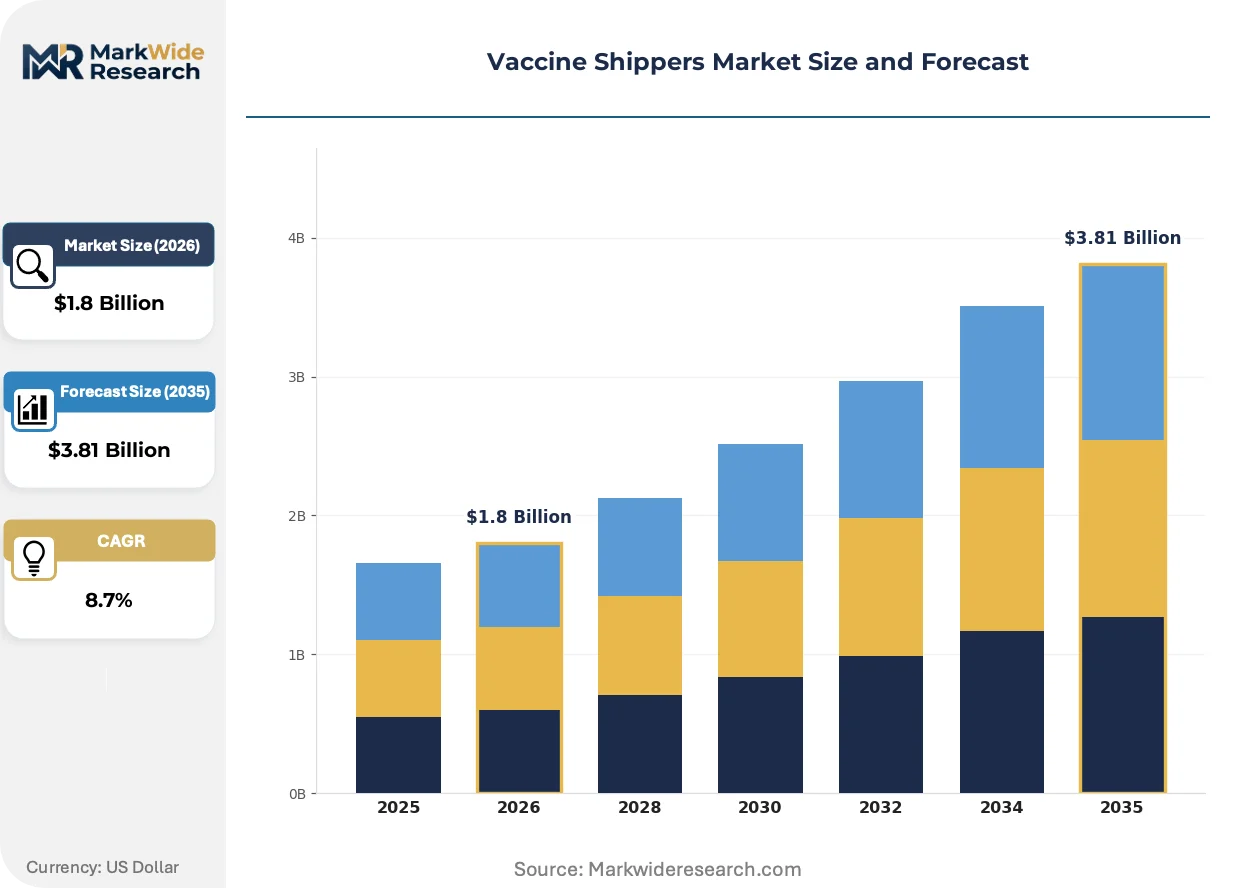
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Shippers, Active Shippers, Temperature-Controlled Containers, Cryogenic Containers Material: Polyethylene, Aluminum, Polystyrene, Fiberboard End User: Pharmaceutical Companies, Hospitals, Research Laboratories, Clinical Trials Regulatory Compliance: Good Distribution Practice, WHO Guidelines, IATA Regulations, FDA Standards |
| Companies Covered | Softbox Systems, Envirotainer, Intelsius, Csafe, DHL, Sealed Air Corporation, B Medical Systems, Stevanato, Gerresheimer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Shippers Market Evolving Landscape
Vaccine shipper technology is bifurcating between sustainability-optimized passive systems and telemetry-integrated active containers, with material science advances compressing performance gaps between the two categories.
Vacuum insulation panels incorporating silica aerogel cores are rendering obsolete traditional expanded polystyrene enclosures in premium pharmaceutical lanes. Gene therapy developers commercializing ultra-cold storage requirements are adopting these panels for cryogenic containers, compressing the weight-to-performance ratio that previously favored mechanical refrigeration for sub-zero distribution.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition timelines for active container fleets. Mechanical systems dependent on hydrofluorocarbons face escalating compliance costs and retrofit mandates, forcing logistics providers toward alternative cooling chemistries or hybrid thermal storage designs in European lanes.
Aftermarket service unbundling is fragmenting thermal packaging lifecycle management across regional service networks and digital monitoring platforms. Pharmaceutical buyers are separating hardware procurement from validation, refurbishment, and telemetry subscription services, compressing vendor margins on initial shipper sales while expanding recurring revenue pools in Germany and the United States.
Vaccine Shippers Market Segmentation
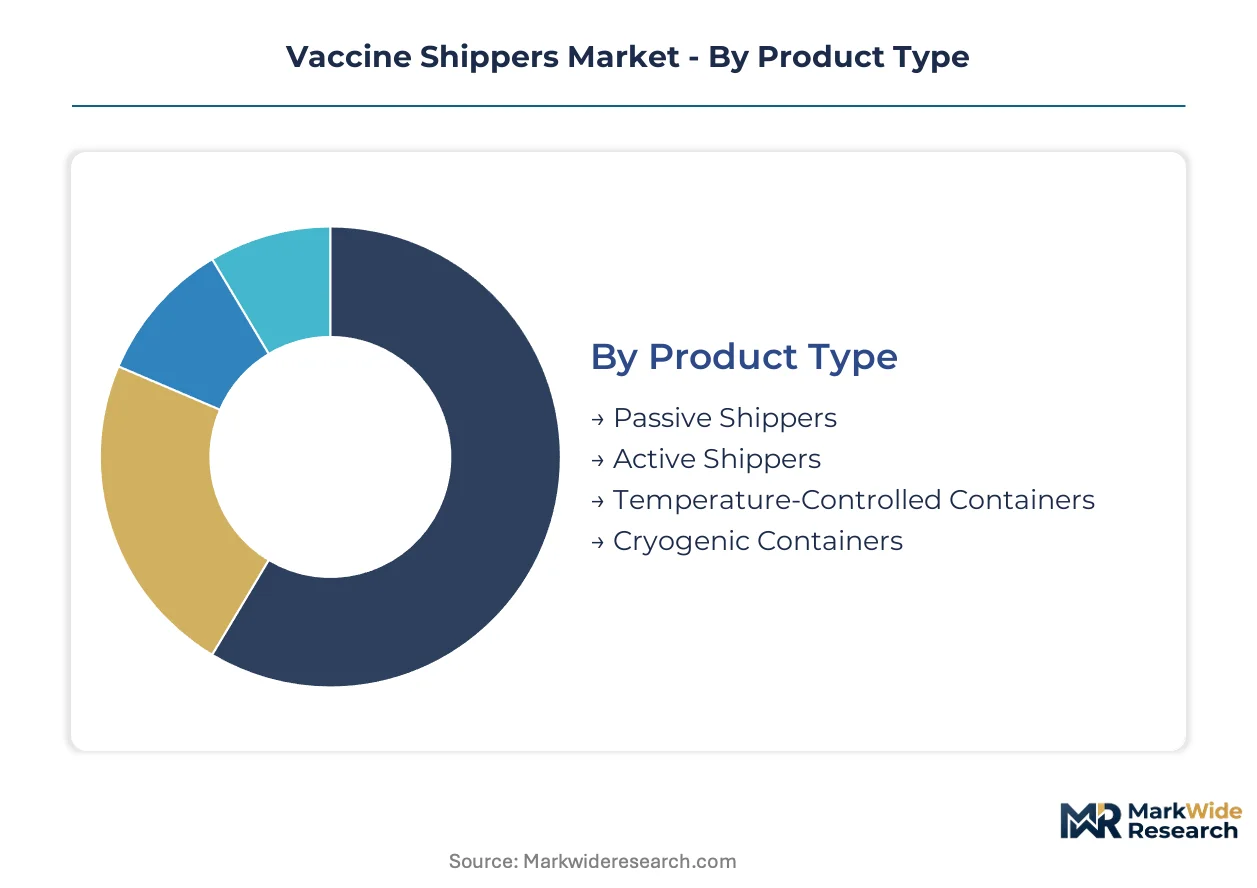
Vaccine shipper procurement patterns diverge sharply across product architectures, with passive systems turning over in high-volume immunization cycles while active containers command extended service lifespans through refurbishment programs. Material selection and regulatory tiering further stratify supplier margins and qualification burdens.
Product Type:
Passive shippers rotate through distribution networks fastest, typically exhausting their thermal mass within 72-96 hours of activation, while active containers with mechanical refrigeration cycle through years of redeployment with telemetry-monitored maintenance intervals.
- Passive Shippers:Insulated enclosures relying on phase-change materials or dry ice sublimation maintain temperature bands without external power. Demand concentrates in India's Mission Indradhanush expansion and other national immunization programs where electricity infrastructure remains unreliable, with WHO PQS prequalification serving as the primary procurement filter.
- Active Shippers:Battery-powered mechanical refrigeration systems with integrated real-time telemetry enable precise temperature control across extended transit durations. Pharmaceutical companies commercializing mRNA and cell therapy portfolios in Germany's Marburg-Dresden manufacturing corridor drive procurement, though EU CSRD carbon disclosure rules are compressing their addressable market in sustainability-weighted tenders.
- Temperature-Controlled Containers:Reusable pallet-scale systems designed for intercontinental pharmaceutical lanes with multi-week autonomy.
- Cryogenic Containers:Liquid nitrogen or vapor-phase systems maintaining ultra-cold chains for gene therapy commercialization.
Passive shippers dominate installed base. Cryogenic containers are where expansion concentrates.
Material:
Cost tiering separates premium-performance materials commanding qualification-intensive procurement from commodity substrates serving high-volume, price-sensitive tenders.
- Polyethylene:Rotationally molded shells with integrated insulation cavities dominate single-use parcel shipper production for last-mile distribution. Pharmaceutical companies in the United States favor polyethylene for its impact resistance through multi-modal handoffs.
- Aluminum:Aircraft-grade alloys fabricate active container exteriors and cryogenic vessel walls, with vacuum insulation panel integration enabling weight-to-performance ratios that displace mechanical refrigeration in premium lanes. German logistics providers specify aluminum-core systems for EU GDP Annex 9 compliance.
- Polystyrene:Expanded and extruded forms provide low-cost thermal buffering for standard refrigerated vaccines in emerging market distribution.
- Fiberboard:Corrugated structures with metallized liners occupy the lowest cost tier for short-duration, ambient-protected shipments.
Fiberboard and polystyrene anchor volume procurement. Aluminum is climbing the fastest.
End User:
Customer type stratifies around validation depth, with commercial manufacturers demanding extensive qualification documentation while point-of-care settings prioritize operational simplicity.
- Pharmaceutical Companies:Integrated cold chain operators requiring end-to-end traceability from manufacturing through distribution. FDA Current Good Manufacturing Practice enforcement creates compliance cost barriers for non-validated packaging suppliers in domestic US lanes.
- Hospitals:Administration sites receiving finished vaccines for immediate patient delivery, with procurement emphasizing receiving simplicity over outbound thermal performance.
- Research Laboratories:Preclinical and clinical material handlers with specialized cryogenic requirements for cell line preservation.
- Clinical Trials:Decentralized investigational product distributors facing patient-specific temperature protocol variability.
Pharmaceutical companies concentrate procurement value. Clinical trials are gaining share fastest.
Regulatory Compliance:
Jurisdiction-specific validation protocols fragment shipper design requirements, with manufacturers maintaining multiple qualification datasets for identical physical systems.
- Good Distribution Practice:EU Annex 9 revisions extending qualification timelines for new shipper designs, with German authorities interpreting temperature mapping requirements most stringently.
- WHO Guidelines:Performance, Quality and Safety prequalification establishing product stability testing protocols for emerging market procurement eligibility.
- IATA Regulations:Dangerous goods handling mandates including pilot training for dry ice shipments, with lithium battery restrictions affecting active container airworthiness certification.
- FDA Standards:Domestic US traceability requirements under Current Good Manufacturing Practice creating documentation burdens distinct from international frameworks.
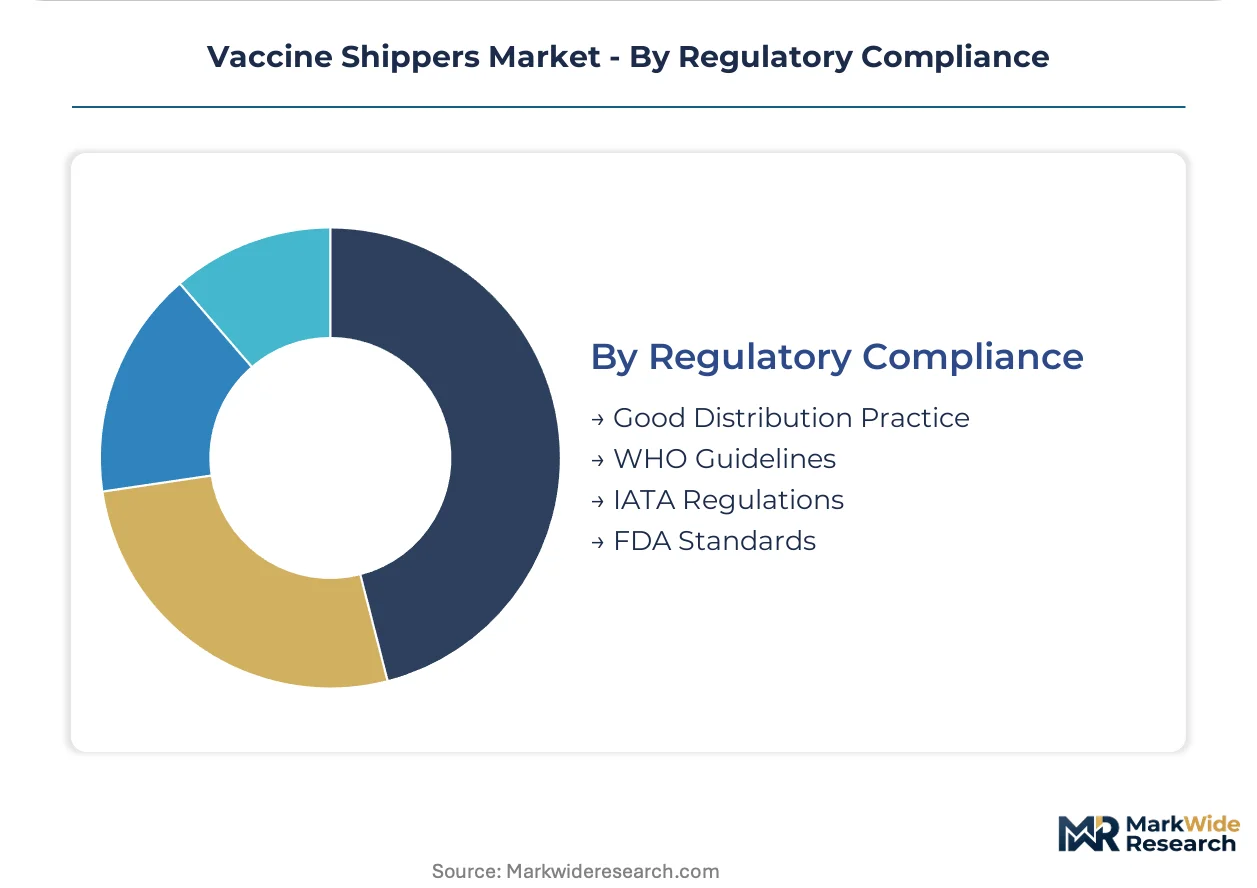
WHO Guidelines dominate emerging market access. EU GDP revisions are where compliance investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vaccine shipper manufacturing clusters in Germany, the United States, and India generate disproportionate procurement pull for advanced thermal packaging systems. Production concentration around Marburg and Dresden anchors European demand, while Indian universal immunization programs drive volume requirements for passive systems.
Germany
Marburg and Dresden manufacturing corridors generate specialized procurement for ultra-cold chain systems serving mRNA portfolios. EMA oversight of EU GDP Annex 9 revisions extends qualification timelines, compressing revenue recognition for packaging innovators. Bavaria-based logistics providers specify aluminum-core vacuum insulation systems for intercontinental pharmaceutical lanes.
United States
FDA Current Good Manufacturing Practice enforcement creates compliance barriers for non-validated packaging suppliers in domestic distribution. The agency's traceability requirements drive pharmaceutical companies toward integrated cold chain operators with end-to-end documentation capabilities. Greater Boston and Research Triangle clusters concentrate biologics manufacturing demand.
India
Mission Indradhanush expansion generates volume demand for passive shippers engineered for unreliable electricity infrastructure. CDSCO alignment with WHO PQS prequalification protocols filters procurement eligibility for emerging market tenders. Gujarat and Maharashtra cold chain networks anchor national immunization logistics.
Japan
PMDA stability testing protocols for cell therapy commercialization drive cryogenic container adoption. METI guidance on pharmaceutical distribution standards shapes domestic qualification requirements. Osaka-Kobe pharmaceutical manufacturing belt concentrates demand for precision temperature control systems.
Switzerland
Swissmedic oversight of gene therapy logistics creates premium-tier demand for liquid nitrogen temperature maintenance. Basel pharmaceutical headquarters operations anchor specialized procurement for multi-modal distribution. Alpine logistics corridors favor lightweight vacuum insulation systems for air freight efficiency.
Vaccine Shippers Market Competitive Landscape
Active container specialists and passive shipper fabricators split the market along performance-versus-cost fault lines. Consolidation pressure concentrates among reusable system providers facing EU CSRD carbon disclosure scrutiny, while single-use parcel manufacturers compete on volume scale in emerging market tenders. Three archetypes dominate: integrated cold chain operators with telemetry platforms, material science specialists advancing vacuum insulation formulations, and regional fabricators serving national immunization programs. Capacity expansion and qualification protocol unification represent the dominant competitive moves as manufacturers seek to compress multi-jurisdiction validation burdens.
Within the integrated cold chain tier, Envirotainer and Csafe occupy positions anchored by intercontinental pharmaceutical lane coverage. Softbox Systems exemplifies the single-use parcel specialist archetype, with its product line representing passive shipper innovation for last-mile distribution. These three companies collectively illustrate the strategic bifurcation between reusable active systems with telemetry integration and disposable thermal packaging optimized for emerging market infrastructure constraints.
| Leading Market Players |
|---|
| Softbox Systems |
| Envirotainer |
| Intelsius |
| Csafe |
| DHL |
| Sealed Air Corporation |
| B Medical Systems |
| Stevanato |
| Gerresheimer |
| Others |
Value Network & Pricing Analysis
Marburg and Dresden manufacturing corridors anchor European vaccine production capacity, concentrating procurement leverage among Bavaria-based logistics providers who specify aluminum-core vacuum insulation systems. This geographic pull tightens margins for non-validated packaging suppliers while amplifying pricing power for WHO PQS-certified manufacturers serving German mRNA portfolios.
Pricing Analysis
Aftermarket service contracts and telemetry subscription tiers generate disproportionate lifetime value relative to initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates integrated cold chain operators with end-to-end traceability from regional fabricators serving national immunization programs. Cost compression in passive shipper categories is intensifying because Indian Mission Indradhanush tenders prioritize volume scale over performance specifications. Pharmaceutical companies in Germany exhibit lowest price sensitivity due to EU GDP Annex 9 compliance burdens, while emerging market procurement offices face acute budget constraints.
Supply Chain Analysis
Carbon dioxide feedstock for dry ice production concentrates in Germany, the United States, and China, with regional capture rate fluctuations creating input cost instability for cryogenic passive shipper operations. Vacuum insulation panel manufacturing draws from silica aerogel precursors and aircraft-grade aluminum alloys, resting on specialty chemical suppliers with limited geographic diversification. Single-source vulnerability in phase-change material formulation expertise constrains product development velocity for emerging entrants. Distribution runs through pharmaceutical third-party logistics providers with GDP-certified warehousing networks in Basel, Boston, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy commercialization is accelerating penetration for ultra-cold chain infrastructure, positioning cryogenic container adoption as an early-cycle expansion story with sustained procurement pull from cell therapy developers.
For Market Incumbents: Harden qualification protocol unification across WHO PQS and EU GDP Annex 9 frameworks to compress multi-jurisdiction validation burdens. Deepen backward integration into vacuum insulation panel manufacturing to defend margin position against material cost volatility. Carbon disclosure requirements under EU CSRD represent the primary regulatory threat compressing active container addressable markets. For New Entrants and Emerging Players: Mid-market clinical trial distributors in Asia-Pacific represent the most penetrable entry point for cryogenic container specialists lacking established pharmaceutical lane relationships. India's Mission Indradhanush expansion offers volume-scale procurement access for passive shipper fabricators with WHO PQS prequalification capabilities. Target CDSCO alignment pathways as the critical go-to-market angle for emerging market tender eligibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because divergence between passive shipper sustainability mandates and active container energy intensity creates persistent vendor consolidation pressure. Acquisition targets should exhibit integrated telemetry platforms with blockchain traceability capabilities. Watch EU F-Gas Regulation phase-down schedules as the signal indicating accelerated refrigerant transition timelines and retrofit mandate intensity.| Strategic Initiative | Industry Significance |
|---|---|
| WHO PQS Prequalification Investment | Unlocks emerging market procurement eligibility for Indian and African immunization tenders. |
| Vacuum Insulation Panel Backward Integration | Captures silica aerogel cost compression and accelerates cryogenic container development cycles. |
| Telemetry-Blockchain Platform Integration | Generates recurring subscription revenue from pharmaceutical companies requiring end-to-end traceability. |
| EU GDP Annex 9 Qualification Unification | Compresses validation timelines and reduces redundant testing burdens across German manufacturing corridors. |
| Dry Ice Supply Agreement Structuring | Hedges carbon dioxide capture volatility through long-term offtake contracts with regional industrial gas suppliers. |
Research Methodology
Operator-level perspectives from cold chain logistics directors, pharmaceutical procurement managers, thermal packaging engineers, and regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against WHO PQS prequalification databases, EU GDP Annex 9 guidance documents, IATA dangerous goods regulations, and FDA Current Good Manufacturing Practice enforcement records. Bottom-up shipper deployment estimates and top-down biopharmaceutical cold chain expenditure analysis converged on market sizing outputs.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling incorporating product architecture, material substrate, end-user validation depth, and regional regulatory cluster. CAGRs derived from weighted average of historical procurement patterns and pipeline-based adoption curves for mRNA and cell therapy portfolios. Cryogenic container penetration assumptions and passive shipper replacement cycles served as key forecast inputs.
Practitioners should monitor EU CSRD disclosure implementation timelines and WHO PQS protocol revisions for early signals of qualification burden shifts. Forecasts reflect documented assumptions regarding gene therapy commercialization velocity and dry ice supply stability. Material shifts in EU F-Gas Regulation enforcement stringency or carbon capture technology economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market