
 Pharmaceutical Plastic Bottles Market | 2026-2036
Pharmaceutical Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Plastic Bottles Market Analysis
Polyethylene terephthalate is rebalancing cost-performance economics as it displaces glass in oral solid and liquid dosage applications. Amcor plc leverages integrated blow-molding capacity across North America and Europe to sustain supply security for large pharmaceutical contract packagers. Gerresheimer AG anchors its position through specialized barrier-coated PET technologies that extend shelf stability for moisture-sensitive formulations. Berry Global Group, Inc. competes on scale, operating multi-site HDPE extrusion networks that serve generic drug distributors with high-volume, standardized bottle programs.
Pharmaceutical plastic bottles are blow-molded or injection-stretch blow-molded containers fabricated from HDPE, PET, LDPE, or PVC, typically ranging from 15 mL to 1,000 mL capacity, designed to meet USP <661> and EP 3.1 extractables standards for primary drug packaging. Their primary purpose is to protect dosage forms from moisture, oxygen, and light while enabling precise dispensing and child-resistant functionality. Rigid bottles dominate volume demand for tablet and capsule counts above thirty units, where structural integrity during automated filling lines matters most. Squeeze bottles represent the fastest-expanding category in ophthalmic and nasal spray segments, as metered-dose pump integration with flexible LDPE walls gains formulary acceptance. Child-resistant closures command premium positioning due to Poison Prevention Packaging Act compliance burdens and the technical complexity of senior-friendly yet toddler-resistant designs.
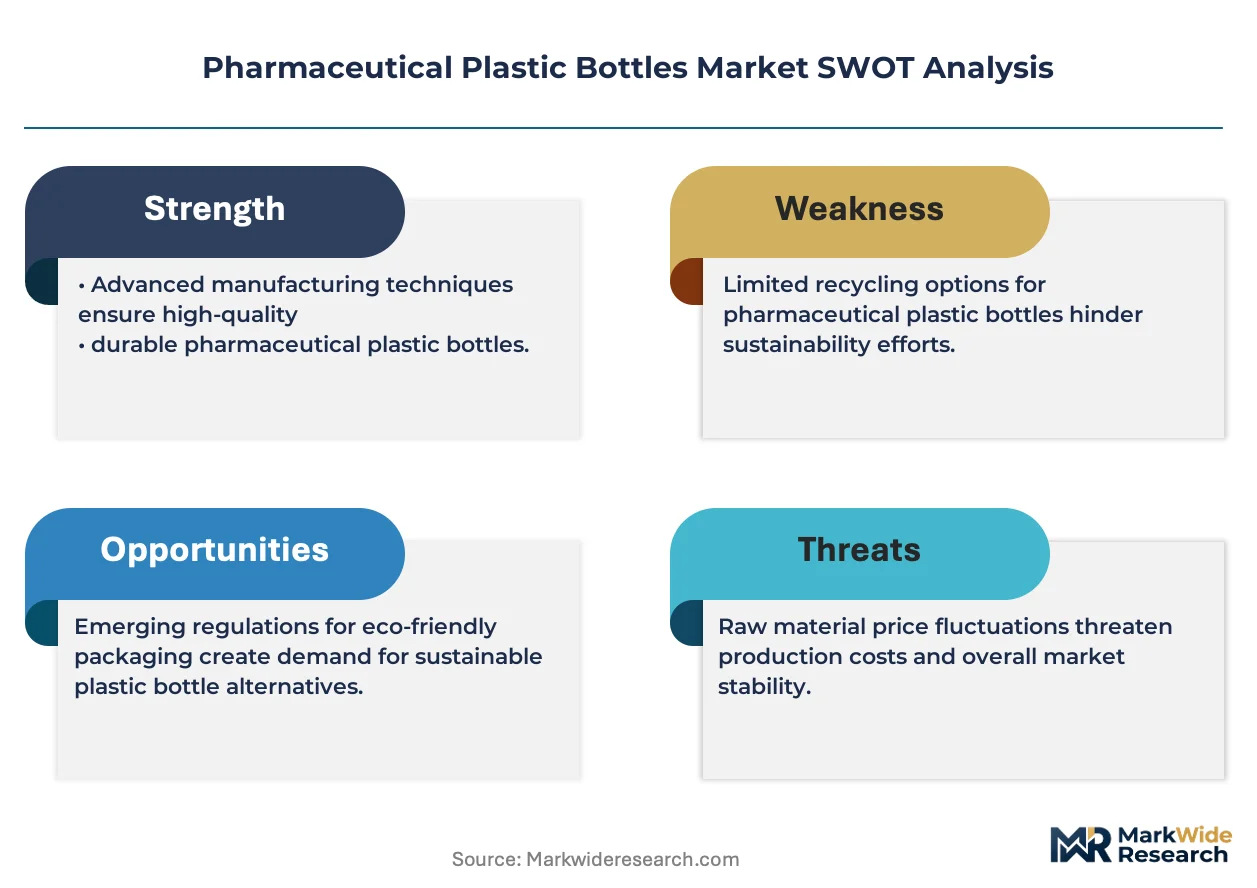
FDA enforces 16 CFR 1700 child-resistant packaging standards that dictate closure torque and reclosure testing protocols, while EMA's MDR and REACH restrict phthalate plasticizers in PVC bottles destined for European patients. India's CDSCO aligns with Schedule M requirements for primary packaging material traceability, tightening supplier qualification for export-oriented generic manufacturers. Stakeholders must monitor evolving EFSA and EPA assessments of recycled content eligibility in pharmaceutical-contact applications, as post-consumer resin approvals could redraw raw material sourcing strategies.
Market Dynamics
Contract manufacturing organizations are consolidating procurement power, forcing bottle suppliers to absorb certification costs and restructure pricing around multi-year supply agreements rather than spot-volume transactions.
Growth Catalysts
- EMA MDR compliance deadlines:European pharmaceutical contract packagers are accelerating primary packaging qualification cycles to meet medical device regulation timelines for combination products.
- India's Schedule M traceability mandates:Export-oriented generic manufacturers are upgrading packaging material documentation systems to satisfy CDSCO audit protocols.
- Barrier-coated PET:Moisture-sensitive oral solid dosage formulations are migrating from glass to advanced polymer containers with oxygen-scavenging inner layers.
Market Restraints
- HDPE resin supply concentration:Gulf Coast petrochemical disruptions expose pharmaceutical bottle molders to feedstock allocation volatility and force majeure declarations.
- REACH phthalate restrictions:ECHA substance of very high concern listings are eliminating plasticizer options for PVC bottles in European liquid dosage applications.
- Glass substitution ceiling:High-barrier parenteral and biologic formulations remain locked in borosilicate containers due to USP <660> surface durability requirements.
Strategic Opportunities
- Post-consumer resin regulatory pathways:EFSA and FDA are advancing qualification frameworks for recycled PET in pharmaceutical-contact applications.
- Ophthalmic squeeze-dose convergence:Metered-dose pump integration with flexible LDPE walls is creating new formulary categories for preservative-free formulations.
- China's NMPA bioequivalence expansion:Domestic generic drug volume growth is driving demand for primary packaging with accelerated stability certification.
Industry Challenges
- Extractables validation timelines:USP <661.1> and EP 3.1 migration studies require month-long analytical protocols that delay new material introductions.
- Child-resistant closure engineering:Senior-friendly yet toddler-resistant designs demand iterative torque testing that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Plastic Bottles Market |
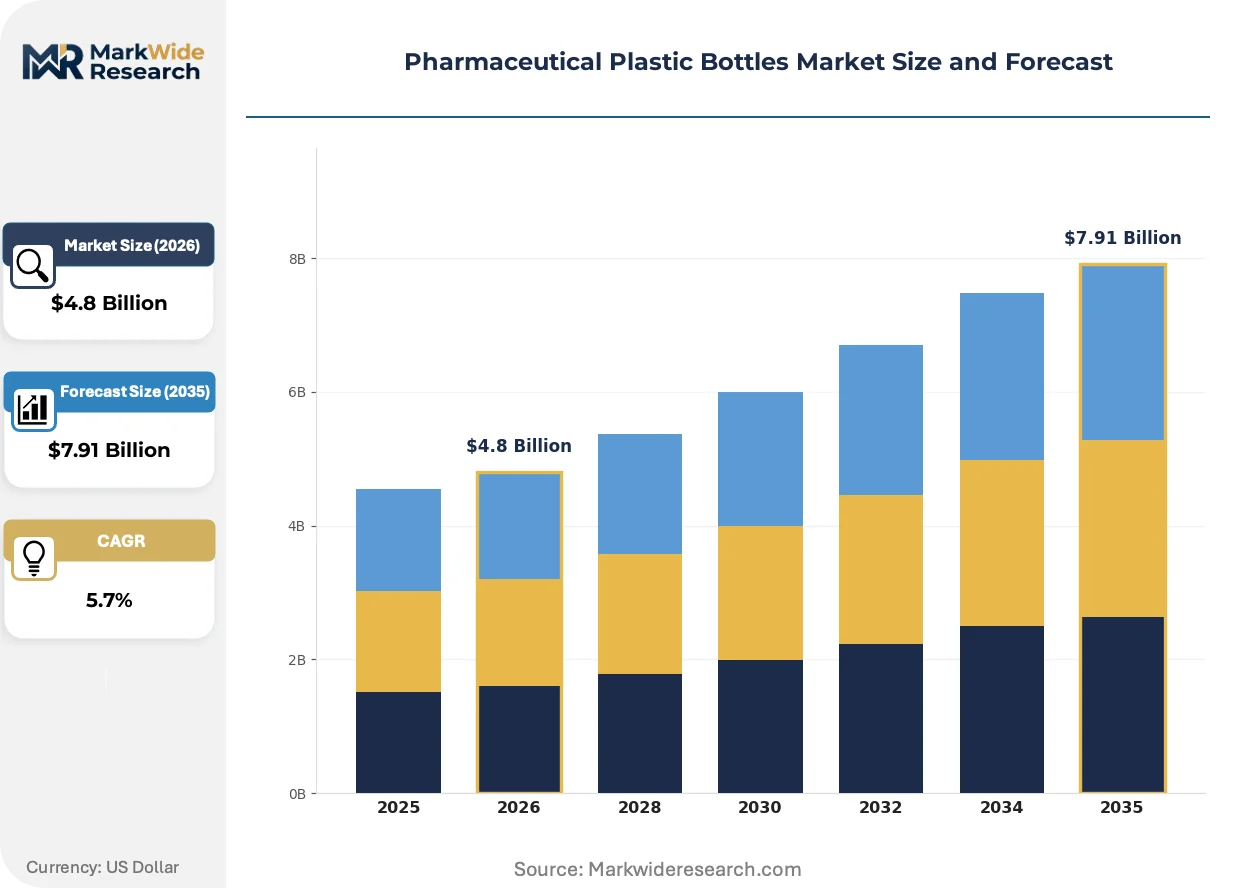
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Bottles, Chubby Bottles, Rigid Bottles, Squeeze Bottles Material: HDPE, PET, LDPE, PVC Closure Type: Child-Resistant Caps, Screw Caps, Dropper Caps, Snap-on Caps End User: Pharmacies, Hospitals, Clinics, Research Laboratories |
| Companies Covered | Amcor plc, Gerresheimer AG, AptarGroup, Inc., Berry Global Group, Inc., ALPLA Group, Alpha Packaging, Inc., SCHOTT AG, West Pharmaceutical Services, Inc., Stevanato Group S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Plastic Bottles Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing development cycles while elevating performance thresholds for moisture and oxygen barrier properties across dosage categories.
Multilayer co-injection blow-molding is absorbing functional additives directly into PET bottle walls rather than relying on external coatings. Large pharmaceutical contract packagers in North America are qualifying these structures for chronic disease medications with month-long stability requirements. This technology is absorbing coating-line capital expenditures and consolidating supplier tiers toward integrated resin-compounding capabilities.
REACH authorization requirements for intentionally added substances are forcing reformulation of colorants and slip agents used in European pharmaceutical packaging. The industrial consequence is a shift toward additive-free natural resins with downstream processing adjustments. High-volume generic distributors serving EMA-regulated markets are most affected and are responding with dual-sourcing strategies that segregate European from rest-of-world material streams.
Buyer consolidation among contract development and manufacturing organizations is compressing supplier qualification timelines from eighteen months to under nine. Long-term supply agreements with volume guarantees are displacing transactional purchasing in oral solid dosage packaging. This pattern is most visible in India and China where domestic generic production capacity expansion is concentrating procurement decisions among fewer contract packaging entities.
Pharmaceutical Plastic Bottles Market Segmentation
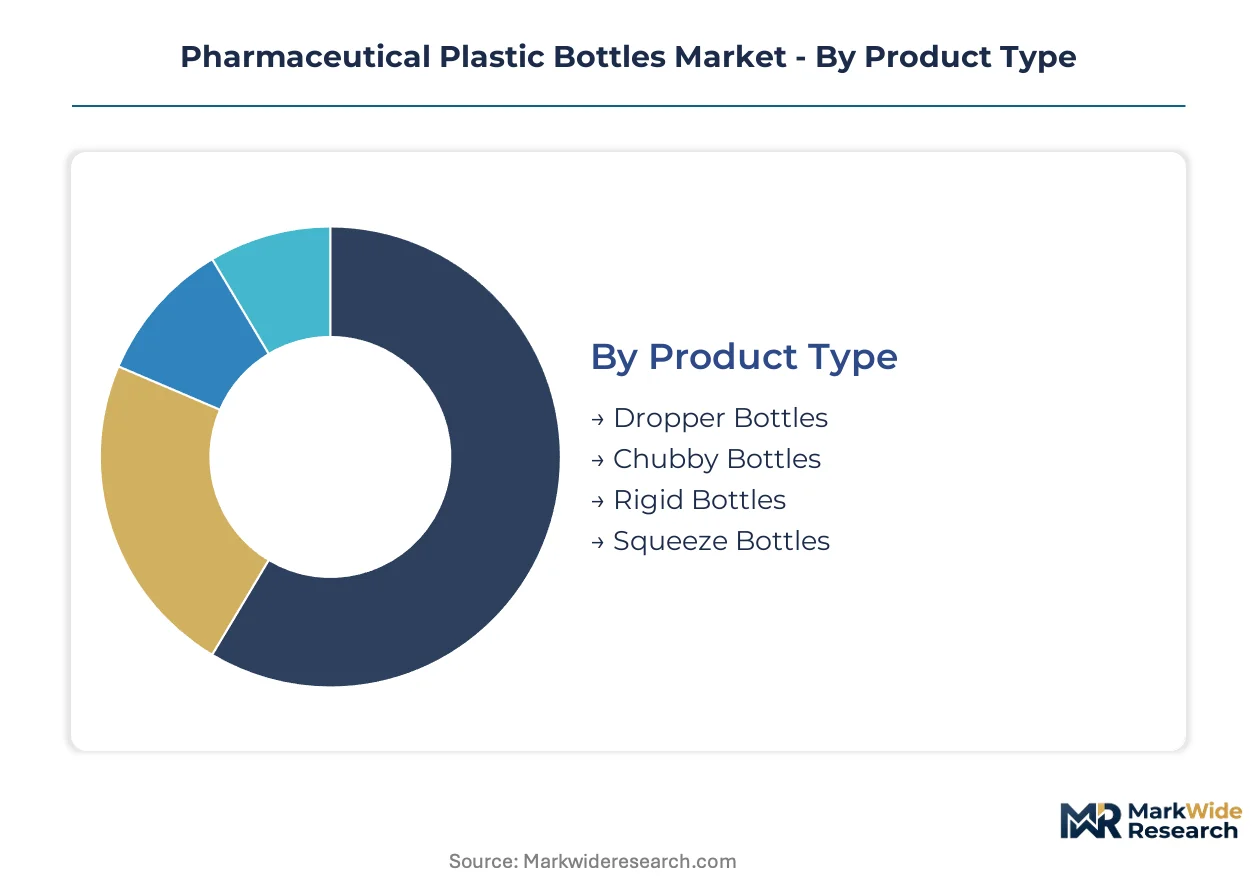
Pharmaceutical plastic bottle segmentation reflects divergent performance requirements across dosage forms, regulatory jurisdictions, and dispensing environments. Material selection and closure engineering decisions cascade through supply chain qualification timelines and end-user procurement specifications.
Product Type:
Volume applications dominate oral solid dosage, while premium squeeze formats capture ophthalmic and nasal spray growth.
- Rigid Bottles:Blow-molded HDPE and PET structures engineered for automated filling line integrity at tablet counts above thirty units. Demand concentrates among Indian and Chinese generic manufacturers expanding chronic disease medication output where structural stability during high-speed packaging operations remains non-negotiable.
- Squeeze Bottles:Flexible LDPE walls with integrated metered-dose pump systems serving preservative-free ophthalmic formulations. Adoption accelerates in North American and European contract manufacturing organizations qualifying new formulary categories for dry eye and glaucoma therapies.
- Dropper Bottles:Narrow-neck PET and glass-compatible designs for liquid oral and topical applications requiring precise volumetric dispensing.
- Chubby Bottles:Wide-mouth HDPE containers optimized for effervescent tablets and powder reconstitution products with desiccant integration requirements.
Today's leader: Rigid bottles. Tomorrow's challenger: Squeeze bottles.
Material:
Cost-performance tradeoffs and barrier specifications segment resin selection across moisture-sensitive and oxygen-sensitive formulations.
- PET:Barrier-coated and multilayer co-injection variants displacing glass in oral solid dosage applications. European and North American contract packagers drive qualification for chronic medications with extended stability requirements.
- HDPE:High-volume extrusion networks serving standardized generic drug programs where moisture barrier demands remain moderate. Gulf Coast petrochemical supply concentration exposes molders to feedstock allocation volatility.
- LDPE:Flexible squeeze walls with pump integration for ophthalmic and nasal delivery systems gaining formulary acceptance in preservative-free categories.
- PVC:Phthalate plasticizer restrictions under REACH authorization requirements are eliminating European liquid dosage applications; residual demand concentrates in non-regulated markets with legacy equipment.
PET climbs fastest on barrier innovation. HDPE retains volume dominance on scale economics.
Closure Type:
Regulatory compliance burdens and senior-friendly engineering requirements create premium positioning for specialized closure systems.
- Child-Resistant Caps:FDA 16 CFR 1700 torque and reclosure testing protocols drive iterative development cycles. US and European markets absorb premium pricing for Poison Prevention Packaging Act compliance combined with senior-accessibility engineering.
- Screw Caps:Standardized threading systems for non-restricted medications and institutional dispensing environments where child-resistant functionality is not mandated.
- Dropper Caps:Integrated bulb and pipette assemblies for liquid oral and topical applications requiring precise drop control.
- Snap-on Caps:Cost-optimized closure for single-use and sample packaging with minimal reclosure requirements.
Child-resistant systems command margin premiums. Screw caps anchor volume throughput.
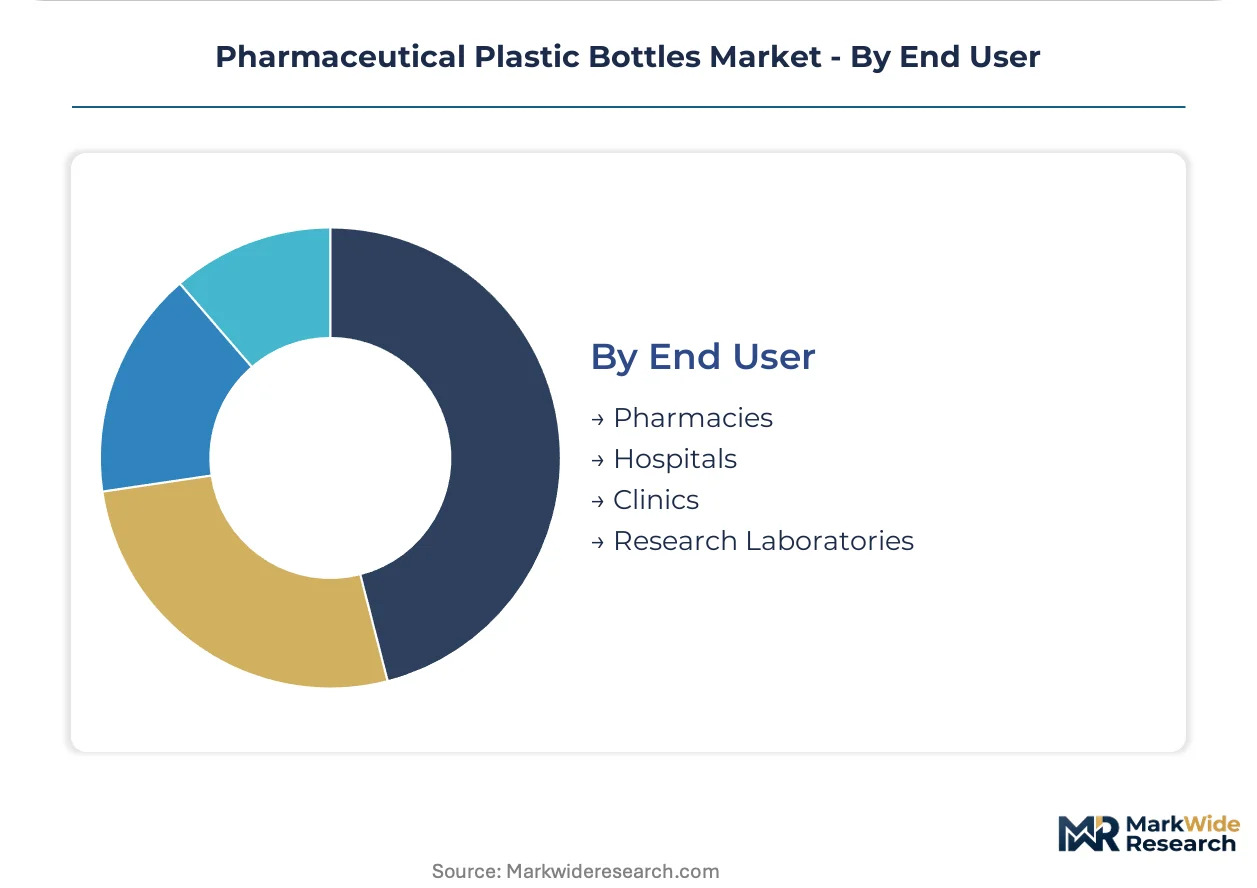
End User:
Procurement consolidation patterns and dispensing workflow requirements differentiate customer segments.
- Pharmacies:Retail and mail-order dispensing operations driving demand for child-resistant packaging with patient counseling information panels. US and European chains consolidate procurement through centralized generic sourcing programs.
- Hospitals:Unit-dose and bulk institutional packaging with barcode traceability requirements aligned with FDA DSCSA and EU FMD serialization mandates.
- Clinics:Outpatient and specialty care settings with mixed dispensing volumes and sample distribution needs.
- Research Laboratories:Clinical trial material packaging with batch documentation and stability study protocols for investigational new drug submissions.
Pharmacies concentrate purchasing power. Hospitals tighten traceability specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ahmedabad's pharmaceutical packaging cluster anchors global supply for oral solid dosage bottles, serving contract manufacturers across three continents. FDA and EMA regulatory alignment pressures concentrate qualification activity in this western Indian hub. Regional expansion patterns diverge between mature markets tightening barrier specifications and emerging economies scaling generic production.
United States
New Jersey and Pennsylvania contract packagers drive demand for child-resistant PET bottles as chronic disease medication volumes climb. FDA 16 CFR 1700 enforcement tightens closure torque testing protocols for Poison Prevention Packaging Act compliance. Indianapolis-area generic distributors consolidate procurement through multi-year supply agreements with blow-molding specialists.
Germany
EMA MDR deadlines accelerate barrier-coated PET qualification cycles for combination products. REACH authorization requirements eliminate phthalate plasticizers from PVC liquid dosage bottles destined for European patients. Bavarian pharmaceutical contract manufacturers invest in multilayer co-injection capacity for moisture-sensitive formulations.
China
NMPA bioequivalence expansion fuels domestic generic drug output requiring primary packaging with accelerated stability certification. Yangtze River Delta blow-molders scale HDPE extrusion networks to serve state-owned pharmaceutical distributors. Shanghai-based contract manufacturers integrate quality documentation systems for CDSCO export compliance.
India
Schedule M traceability mandates force export-oriented generic manufacturers to upgrade packaging material documentation systems. Gujarat's bottle molding corridor supplies HDPE and PET containers to European and US generic drug distributors. CDSCO audit protocols tighten supplier qualification timelines from eighteen months to under nine.
Switzerland
Swissmedic guidance on primary packaging extractables drives migration toward additive-free natural resins. Basel-area pharmaceutical headquarters concentrate procurement decisions for global chronic disease portfolios. Alpine barrier technology specialists develop oxygen-scavenging inner layers for moisture-sensitive oral solid dosages.
Pharmaceutical Plastic Bottles Market Vendor Landscape
Global majors compete with regional champions across regulatory qualification capabilities and integrated manufacturing scale. The market structures around three tiers: multinational packaging conglomerates with blow-molding networks spanning multiple continents, mid-cap specialists with barrier-coating expertise, and regional fabricators serving domestic generic distributors. Strategic moves concentrate on backward integration into resin compounding and multi-year supply agreements that lock in volume guarantees.
Within the integrated multinational tier, Amcor plc and Berry Global Group, Inc. represent scale-driven archetypes with blow-molding capacity across North America and Europe. Gerresheimer AG occupies a position among barrier technology specialists, anchoring premium positioning through coated PET shelf-stability solutions. These three entities exemplify the competitive tension between volume throughput and specialized performance specifications.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| AptarGroup, Inc. |
| Berry Global Group, Inc. |
| ALPLA Group |
| Alpha Packaging, Inc. |
| SCHOTT AG |
| West Pharmaceutical Services, Inc. |
| Stevanato Group S.p.A. |
| Others |
Supply Flow & Price Mechanics
Ethylene feedstock price volatility cascades through HDPE and PET resin markets into three distinct pricing tiers for pharmaceutical bottle procurement. Gulf Coast petrochemical disruptions compress margins for standardized generic programs while barrier-coated PET commands premium positioning in chronic disease medication supply chains.
Pricing Analysis
Input-cost pass-through from resin indices dominates contract renegotiation cycles between molders and pharmaceutical contract packagers. Three-tier pricing structure across premium, standard, and economy levels segments by barrier certification grade and volume commitment scale. Pricing pressure stems from procurement consolidation among Indian and Chinese generic distributors demanding multi-year volume guarantees. High-volume standardized HDPE programs exhibit maximum price sensitivity, while barrier-coated PET for moisture-sensitive formulations maintains pricing resilience.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast ethylene crackers supplying HDPE feedstock to North American pharmaceutical molders. Manufacturing concentrates in India, China, and Germany for blow-molded pharmaceutical containers. Raw material flows draw from Saudi Arabian and Qatari polyethylene exports, Texas ethylene derivatives, and Asian PET resin production. Tariff exposure on Chinese-manufactured closures threatens cost structures for European contract packagers. Distribution runs through pharmaceutical contract manufacturing organizations consolidating procurement decisions in Ahmedabad, Shanghai, and New Jersey corridor hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in barrier-coated PET substitution for glass and captive resin compounding integration. Cost-down drivers from multilayer co-injection technology adoption enable premium-tier positioning without proportional input cost increases.
For Market Incumbents: Lock in multi-year supply agreements with Indian and Chinese contract manufacturers before Schedule M and NMPA qualification timelines compress further. Invest in backward integration into PET resin compounding to defend margin position against Gulf Coast feedstock volatility. Anchor barrier technology leadership through oxygen-scavenging inner layer development for moisture-sensitive oral solid dosages. For New Entrants and Emerging Players: EMA MDR compliance deadlines in Europe open a window for specialized barrier-coated PET qualification services targeting combination product manufacturers. Target ophthalmic squeeze-dose convergence segments where metered-dose pump integration with LDPE walls remains underpenetrated. Pursue CDSCO audit-ready documentation systems as the go-to-market angle for export-oriented Indian generic manufacturers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap barrier technology specialists possessing EMA and FDA dual-qualification capabilities. Five-to-ten year viability hinges on post-consumer resin regulatory pathway advancement for pharmaceutical-contact applications. Watch EFSA and FDA recycled PET approval timelines as the inflection indicator for raw material sourcing strategy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive HDPE and PET supply secures margin control against Gulf Coast volatility. |
| Barrier-Coated PET Capacity Expansion | EMA MDR deadlines accelerate qualification cycles for moisture-sensitive formulations. |
| Multi-Year Supply Agreement Restructuring | Volume guarantees with Indian generic manufacturers displace transactional spot purchasing. |
| Post-Consumer Resin Regulatory Qualification | EFSA and FDA recycled content approvals redraw pharmaceutical-contact material sourcing. |
| Ophthalmic Squeeze-Dose System Integration | Metered-dose pump convergence with LDPE walls creates preservative-free formulary categories. |
Methodological Framework
Direct dialogue with pharmaceutical packaging procurement directors, regulatory affairs leads at contract manufacturing organizations, blow-molding plant managers, and CDSCO compliance officers grounded qualitative insights. Secondary validation drew from FDA 483 inspection observations, EMA MDR submission databases, USP <661> and EP 3.1 pharmacopeial standards, and Indian Schedule M audit protocols. Bottom-up resin consumption models and top-down pharmaceutical production volume estimates underwent triangulation.
Bottom-up volume modeling segmented by material type, closure system complexity, and end-user procurement channel across the projection horizon. Dosage form sensitivity, regional regulatory cluster stringency, and contract manufacturer consolidation patterns informed segmentation dimensions. CAGRs derived from resin price elasticity assumptions and pharmaceutical outsourcing intensity trajectories. Forecast inputs incorporated EMA MDR compliance deadline phasing and NMPA bioequivalence expansion timelines.
Revisions become necessary when Gulf Coast petrochemical disruption frequency accelerates, EFSA recycled PET approvals stall, or Indian Schedule M enforcement intensity shifts. Forecasts reflect documented assumptions about resin supply stability and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market